
 Global Comprehensive Metabolic Panel Market | 2026-2036
Global Comprehensive Metabolic Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Comprehensive Metabolic Panel Market Foresight
CLIA certification is rotating toward multiplexed platforms and automated chemistry analyzers, reshaping which vendors qualify for high-volume laboratory contracts. Quest Diagnostics leverages its national logistics network to sustain same-day turnaround across thousands of patient service centers. Laboratory Corporation of America Holdings anchors its position through captive patient access points and health plan partnerships. Siemens Healthineers competes on integrated instrument-reagent systems that lock in consumable pull-through.
A comprehensive metabolic panel measures glucose, electrolytes, kidney function markers, liver enzymes, and protein levels from serum or plasma samples using spectrophotometric or ion-selective electrode methods on clinical chemistry analyzers. The test serves as a frontline screening tool for metabolic disorders, medication toxicity, and organ dysfunction in acute and ambulatory settings. Liver function and kidney function test categories dominate routine ordering patterns, while electrolyte and acid-base panels generate premium pricing in critical care environments. Diagnostic laboratories absorb the largest share of end-user demand, though ambulatory surgical centers represent the fastest-growing site of care as same-day procedure volumes expand.
FDA clearance pathways for IVD devices and CLIA complexity classification determine which platforms enter clinical laboratories, while the EU MDR and IVDR impose post-market surveillance obligations that extend compliance costs. WHO prequalification standards shape procurement decisions in low- and middle-income health systems expanding basic chemistry testing. Stakeholders must monitor how decentralized point-of-care platforms challenge centralized laboratory economics without sacrificing analytical performance against reference methods.
Market Dynamics
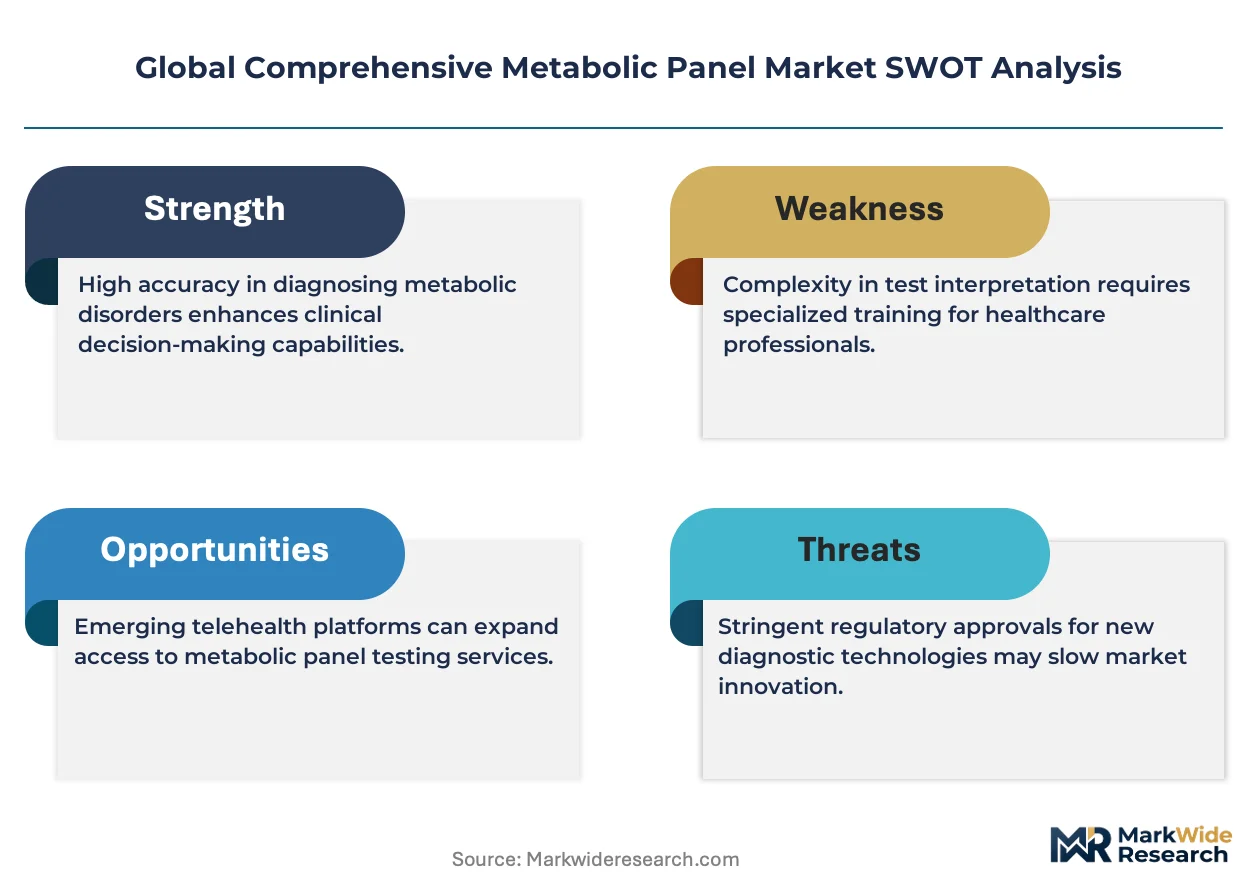
Multiplexed chemistry platforms are compressing turnaround times and forcing laboratory consolidation, while CLIA complexity classifications determine which vendors qualify for high-volume hospital contracts.
Growth Catalysts
- Preventive care protocols:Aging populations in Germany, Japan, and the United States generate recurring test volumes for chronic disease monitoring through standardized screening programs.
- IVD regulatory harmonization:The EU IVDR's expanded post-market surveillance obligations accelerate quality upgrades among manufacturers seeking CE marking for automated analyzer systems.
- Same-day surgical volumes:Ambulatory surgical centers in metropolitan clusters demand rapid-result metabolic panels to support discharge protocols.
Market Restraints
- Reagent cost volatility:Specialized enzymes and calibrators for spectrophotometric assays face input price pressure from concentrated biochemical suppliers.
- Platform lock-in effects:Integrated instrument-reagent systems create switching costs that limit laboratory flexibility when negotiating service contracts.
- Reference method divergence:Variability between ion-selective electrode and spectrophotometric standards complicates inter-laboratory result reconciliation.
Strategic Opportunities
- Point-of-care convergence:Handheld cartridge-based analyzers combining electrolyte and liver function readouts penetrate rural clinics lacking centralized lab access.
- WHO prequalification pathways:Chemistry testing expansion in low- and middle-income health systems creates procurement channels for basic metabolic panel platforms.
- Health plan partnership models:Diagnostic chains negotiate preferred network status by guaranteeing capitated pricing for routine panel volumes.
Industry Challenges
- CLIA high-complexity staffing:Qualified clinical laboratory scientists command premium wages, constraining expansion timelines for new testing sites.
- Legacy analyzer integration:Middleware compatibility gaps between third-party devices and hospital information systems delay automation rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Comprehensive Metabolic Panel Market |
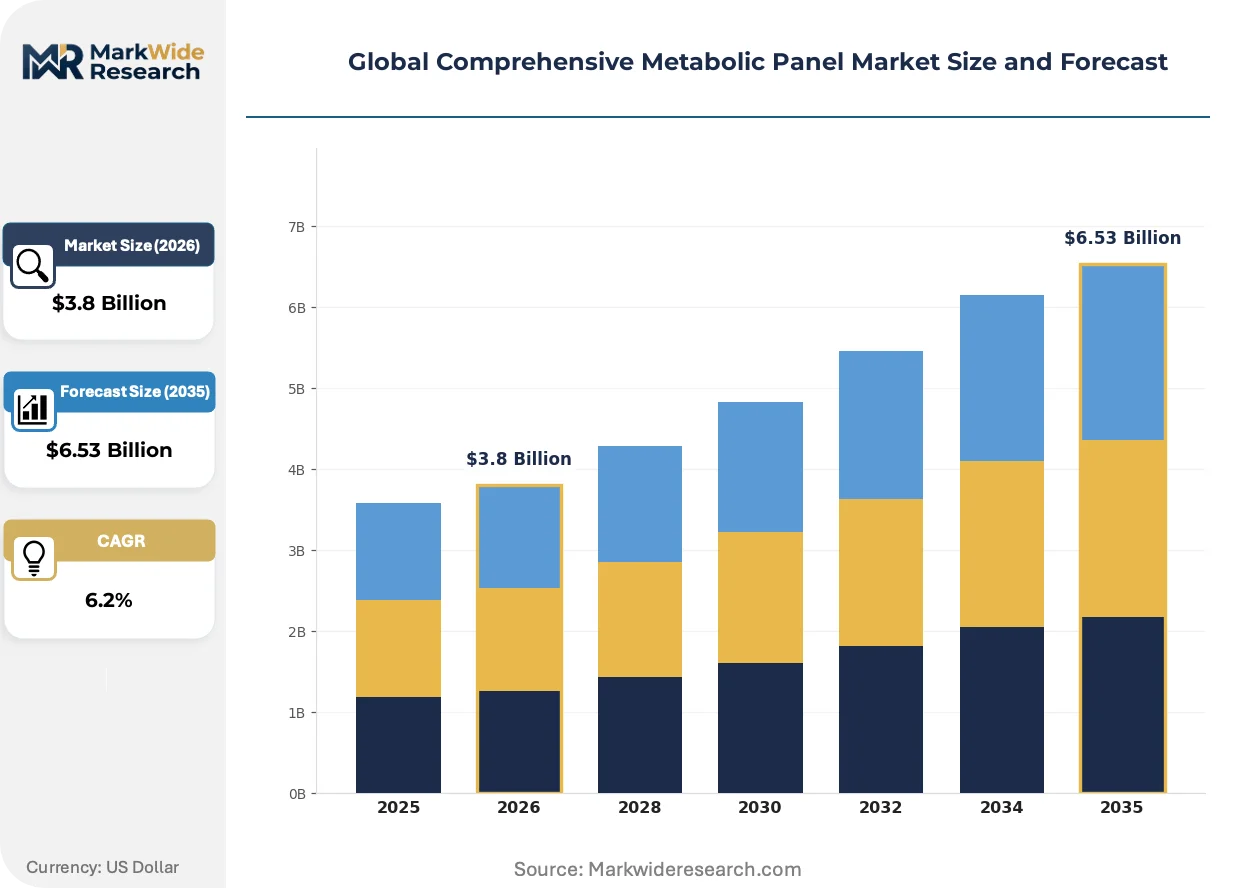
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Liver Function, Kidney Function, Electrolyte & Acid-Base Balance, Glucose, Protein Levels Application: Chronic Disease Monitoring, Preoperative Testing, Nutritional Assessment, Toxicology Screening, Routine Health Checkup End User: Diagnostic Laboratories, Ambulatory Surgical Centers, Research Institutions, Blood Banks, Specialty Clinics Sample Type: Serum, Plasma, Whole Blood, Capillary Blood, Urine |
| Companies Covered | Quest Diagnostics, Laboratory Corporation of America Holdings, Abbott Laboratories, Siemens Healthineers, Sonic Healthcare, SYNLAB International GmbH, Roche Diagnostics, Thermo Fisher Scientific, ARUP Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Comprehensive Metabolic Panel Market Shifts & Advancements
Automation architectures and regulatory frameworks are simultaneously expanding test access and compressing the vendor base capable of serving high-compliance environments.
Random-access chemistry analyzers with discrete sample handling are fragmenting the traditional batch-processing model that dominated hospital core laboratories. Mid-size diagnostic chains in the United States and Japan adopt these systems to maintain STAT turnaround without dedicated stat lines. The technology is fragmenting volume concentration previously captured by centralized reference laboratories into distributed networks of rapid-response nodes.
The EU MDR and IVDR impose clinical evidence requirements that extend clearance timelines for new chemistry assays and analyzer platforms. Manufacturers must generate post-market performance data under stricter surveillance protocols than predecessor directives demanded. In vitro diagnostic companies with legacy product portfolios face portfolio rationalization decisions as recertification costs concentrate resources on high-volume metabolic panels.
Capitated reimbursement contracts are displacing fee-for-service billing for routine screening panels in integrated delivery networks. Health systems in Germany and the United States bundle metabolic testing into annual wellness program pricing, compressing per-test revenue while locking in guaranteed volumes. This shift pressures independent laboratories to secure exclusive network contracts or accept margin compression on standardized chemistry menus.
Global Comprehensive Metabolic Panel Market Segmentation
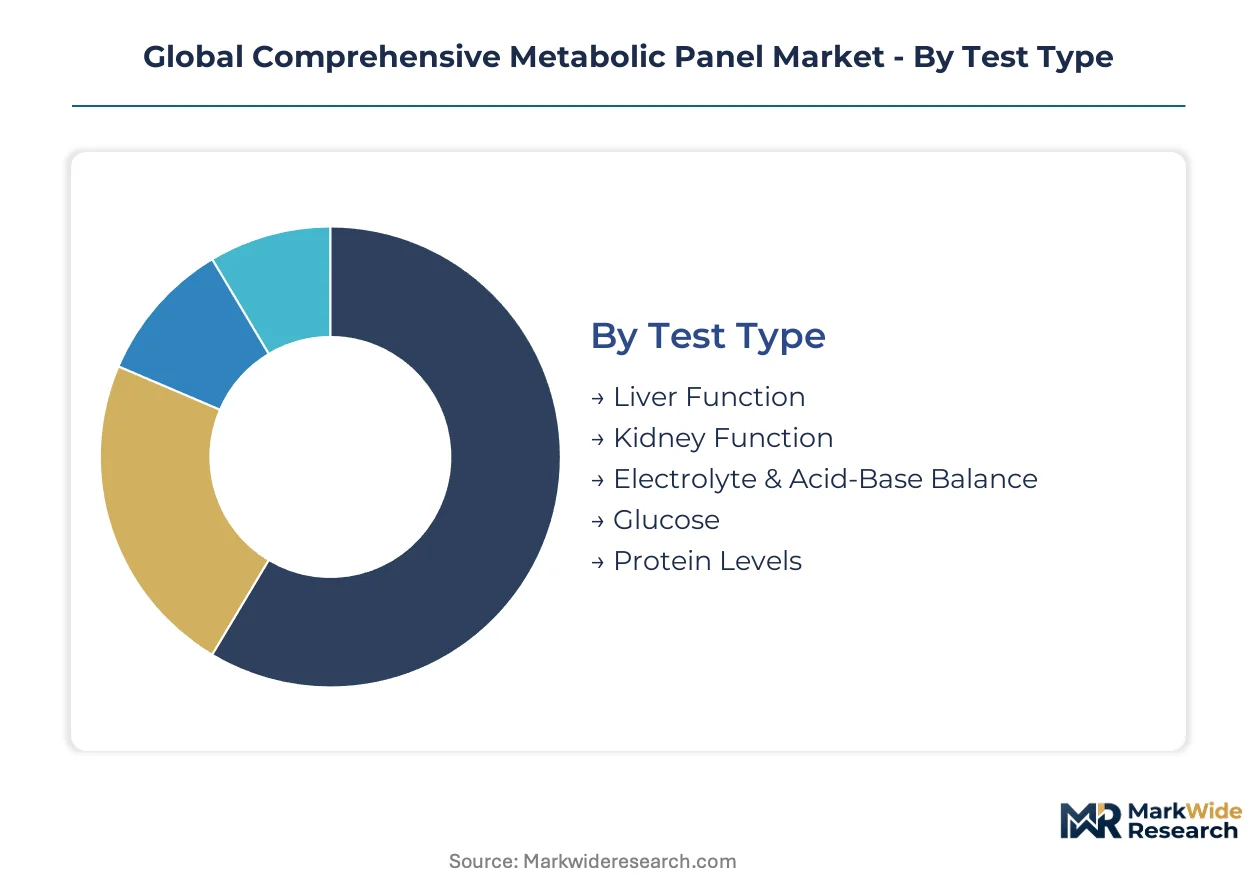
Comprehensive metabolic panel segmentation reveals how test complexity, clinical setting, and sample handling requirements reshape procurement patterns across laboratory networks. Channel economics favor high-throughput configurations in hospital core labs while point-of-care formats penetrate ambulatory settings.
Test Type:
Channel mix splits between high-volume automated platforms for routine chemistries and specialized analyzers for critical care electrolyte panels.
- Liver Function:Enzyme assays measuring ALT, AST, alkaline phosphatase, and bilirubin dominate routine screening protocols. Hospital laboratories in the United States and Germany absorb the largest volumes as hepatology surveillance expands among aging cohorts with metabolic syndrome.
- Kidney Function:BUN and creatinine measurements with calculated eGFR values anchor chronic kidney disease staging. Dialysis chains and nephrology practices in Japan generate recurring demand tied to reimbursement-mandated monitoring intervals.
- Electrolyte & Acid-Base Balance:Sodium, potassium, chloride, and CO2 measurements command premium pricing in ICU settings.
- Glucose:Fasting glucose and calculated indices feed diabetes management protocols across primary care networks.
- Protein Levels:Albumin and total protein assessments support nutritional status evaluation in surgical preadmission testing.
By volume, Liver Function leads. By expansion trajectory, Electrolyte & Acid-Base Balance is climbing the fastest.
Application:
Cost tier stratification separates capitated wellness screening from premium-priced acute care diagnostics.
- Chronic Disease Monitoring:Recurring panels for diabetes, hypertension, and cardiovascular risk management create predictable revenue streams. Medicare Advantage plans in the United States and statutory health insurers in Germany bundle these into annual wellness contracts.
- Preoperative Testing:Mandatory metabolic clearance for elective surgery generates concentrated demand spikes. Ambulatory surgical centers in metropolitan Japan and the United States require rapid-turnaround panels to maintain same-day discharge protocols.
- Nutritional Assessment:Protein and electrolyte panels support bariatric surgery follow-up and malnutrition screening.
- Toxicology Screening:Liver and kidney function monitoring accompanies medication safety protocols for high-risk therapeutics.
- Routine Health Checkup:Standardized CMP orders dominate occupational health and insurance-mandated screening.
Chronic Disease Monitoring captures the largest revenue pool. Preoperative Testing is gaining share fastest as same-day surgery volumes climb.
End User:
Volume concentration tilts toward centralized laboratories while growth concentrates at distributed care sites.
- Diagnostic Laboratories:National reference chains and hospital core labs process the majority of CMP volumes through automated chemistry analyzers. Quest Diagnostics and Laboratory Corporation of America Holdings leverage logistics density to sustain same-day turnaround across thousands of patient service centers.
- Ambulatory Surgical Centers:Freestanding surgery facilities demand STAT-capable platforms with minimal sample handling. Rapid-result metabolic panels enable discharge protocols that keep beds turning in high-throughput metropolitan clusters.
- Research Institutions:Clinical trial sponsors require standardized chemistry panels for protocol compliance.
- Blood Banks:Donor screening and component testing utilize abbreviated metabolic assessments.
- Specialty Clinics:Nephrology, hepatology, and endocrinology practices order disease-focused panel variations.
Diagnostic Laboratories process the highest absolute volumes. Ambulatory Surgical Centers are expanding most quickly.
Sample Type:
Maturity gradients separate established serum-based workflows from emerging whole blood formats.
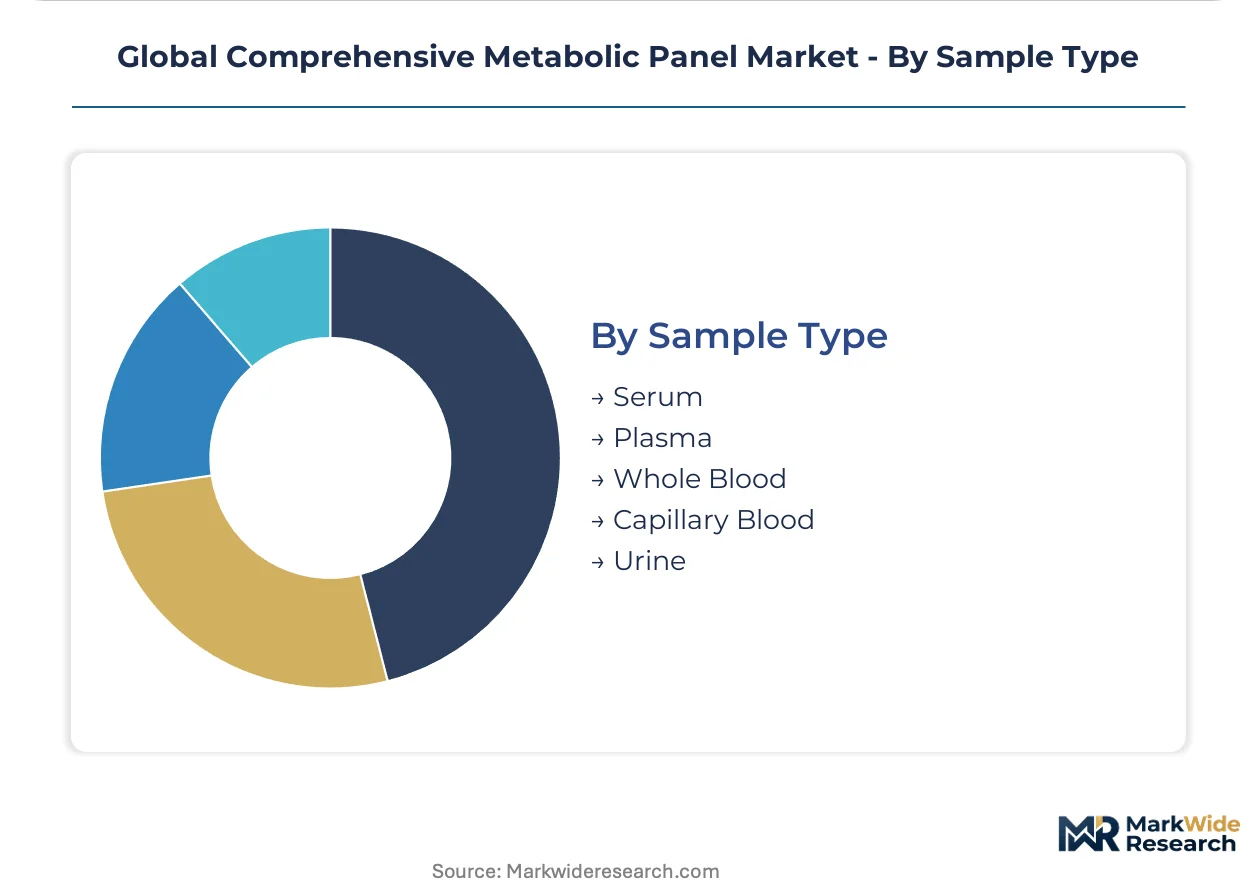
- Serum:Gold-standard specimen type for comprehensive metabolic panels supports the broadest assay menu. Reference laboratories in Germany and the United States standardize on serum separator tubes for automated track systems.
- Plasma:Lithium heparin and EDTA anticoagulant options enable rapid processing without clotting delays. Emergency departments favor plasma for STAT chemistries requiring immediate centrifugation.
- Whole Blood:Point-of-care cartridges bypass laboratory infrastructure for bedside testing.
- Capillary Blood:Fingerstick sampling expands access in pediatric and geriatric populations with difficult venous access.
- Urine:Adjunct metabolic assessments complement serum panels for hydration status and renal function.
Serum maintains volume leadership. Whole Blood is advancing fastest as handheld analyzer penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement bundling for preventive care protocols is concentrating test volumes in health systems with mature chronic disease management programs. The United States, Germany, and Japan absorb the dominant share of comprehensive metabolic panel demand through standardized screening schedules tied to aging population care pathways.
United States
Medicare Advantage annual wellness contracts and commercial capitation models generate recurring CMP volumes for diabetes and cardiovascular monitoring. FDA CLIA high-complexity certification requirements filter vendor participation in hospital laboratory contracts. The Quest Diagnostics national logistics network enables same-day turnaround across metropolitan patient service centers in California, Texas, and the Northeast Corridor.
Germany
Statutory health insurance disease management programs mandate quarterly metabolic panels for enrolled chronic kidney disease and diabetes patients. EU IVDR post-market surveillance obligations extend compliance timelines for new chemistry analyzer platform introductions. The Rhine-Ruhr metropolitan cluster concentrates reference laboratory capacity serving the densest insured population in Europe.
Japan
National health insurance reimbursement schedules incentivize frequent monitoring intervals for elderly patients with polypharmacy regimens. PMDA regulatory harmonization with IVD standards accelerates approval pathways for automated chemistry systems. The Kanto region surrounding Tokyo anchors the highest test volume density through integrated delivery networks and dialysis chain consolidation.
United Kingdom
NHS Long Term Plan targets for early chronic disease detection expand primary care screening panel authorizations. MHRA post-Brexit regulatory alignment with EU IVDR creates transitional compliance burdens for IVD suppliers. London and the Southeast England corridor concentrate private diagnostic laboratory capacity supplementing NHS core lab services.
China
National essential public health service standards mandate free annual health examinations for elderly rural residents including basic metabolic panels. NMPA Class II IVD registration requirements for automated analyzers extend market entry timelines for foreign manufacturers. The Yangtze River Delta region surrounding Shanghai hosts the densest concentration of tertiary hospital laboratory automation deployments.
Global Comprehensive Metabolic Panel Market Competitive Landscape
Player mix skews toward integrated diagnostic service networks and instrument-reagent system manufacturers with captive consumable streams. National reference laboratory chains leverage logistics density to secure exclusive health plan contracts, while diversified medtech conglomerates compete on analyzer platform lock-in effects. Two strategic archetypes dominate: high-volume service operators optimizing turnaround economics, and integrated system vendors capturing recurring reagent pull-through. Competitive moves concentrate on exclusive network contracting and automated platform refresh cycles.
Within the integrated system tier, Siemens Healthineers and Roche Diagnostics exemplify instrument-reagent bundling strategies that embed laboratories in long-term consumable commitments. Quest Diagnostics and Laboratory Corporation of America Holdings occupy positions as high-volume service operators competing on logistics reach and capitated pricing guarantees. SYNLAB International GmbH represents the European diagnostic service consolidation archetype, anchoring multi-country laboratory networks through acquisition-led expansion.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Abbott Laboratories |
| Siemens Healthineers |
| Sonic Healthcare |
| SYNLAB International GmbH |
| Roche Diagnostics |
| Thermo Fisher Scientific |
| ARUP Laboratories |
| Others |
Supply & Pricing Matrix
Capitated health plan contracts lock in multi-year reagent supply commitments for high-volume diagnostic laboratories, embedding price visibility while constraining vendor switching flexibility across the United States and Germany. These arrangements concentrate purchasing power among national reference chains while independent laboratories face margin compression on standardized chemistry menus.
Pricing Analysis
Certification level (CLIA high-complexity versus waived complexity) creates the primary spread between premium instrument-reagent bundles and entry-level analyzer systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by throughput capacity and automation depth, with integrated delivery networks commanding volume discounts that independent sites cannot match. Cost compression in the economy tier intensifies because capitated reimbursement bundles compress per-test revenue while guaranteeing panel volumes. Hospital core laboratories exhibit lowest price sensitivity due to captive patient flows, while ambulatory surgical centers negotiate aggressively on rapid-turnaround STAT pricing.
Supply Chain Analysis
Strategic stockpiling of specialized enzymes and calibrator lots dominates inventory strategy among large diagnostic chains seeking to buffer against reagent lot-to-lot variability. Manufacturing concentration clusters in Germany, Japan, and the United States for clinical chemistry analyzers, while biochemical reagent production draws from Switzerland and Singapore for precision enzyme formulations. Single-source vulnerability persists for ion-selective electrode membranes and spectrophotometric calibrators with limited qualified suppliers. Distribution runs through direct instrument-reagent bundling contracts that lock laboratories into captive consumable streams over five-to-seven-year depreciation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where CLIA certification requirements and integrated instrument-reagent systems generate switching costs that entrench incumbent positions against new platform entrants.
For Market Incumbents: Compound defensive positioning by deepening backward integration into proprietary reagent manufacturing and securing exclusive health plan network contracts in metropolitan clusters with dense insured populations. Point-of-care cartridge platforms pose substitution risk for routine screening volumes, making middleware integration investments and STAT-capable automation refreshes essential to maintain hospital core laboratory relevance. For New Entrants and Emerging Players: Anchor in ambulatory surgical center networks where rapid-result demands outpace incumbent turnaround capabilities and price sensitivity exceeds hospital laboratory thresholds. Rural clinic point-of-care deployment represents the most penetrable white space, with handheld electrolyte-liver function combination analyzers enabling bypass of centralized laboratory infrastructure entirely. For Investors and Strategic Acquirers: Regional diagnostic service consolidators with captive logistics density and capitated contract books offer the most attractive acquisition profile for portfolio exposure to recurring chemistry panel volumes. WHO prequalification progress for basic metabolic panel platforms in low- and middle-income health systems signals inflection potential for manufacturers with cost-optimized analyzer architectures.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | FDA and state laboratory licensing requirements filter vendor eligibility for hospital contracts. |
| Instrument-Reagent Bundling Contracts | Siemens Healthineers and Roche Diagnostics lock laboratories into captive consumable pull-through streams. |
| Point-of-Care Platform Development | Handheld cartridge analyzers penetrate rural clinics lacking centralized laboratory infrastructure access. |
| Health Plan Exclusive Network Partnerships | Quest Diagnostics leverages logistics density to secure capitated pricing guarantees across thousands of patient service centers. |
| EU IVDR Post-Market Surveillance Compliance | Extended clinical evidence requirements concentrate manufacturer resources on high-volume metabolic panel recertification. |
Research Methodology
A standing panel of hospital laboratory directors, clinical chemistry specialists, diagnostic chain procurement executives, and CLIA compliance officers provided ongoing calibration against operational realities in high-throughput testing environments. Primary interview findings triangulated against FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, EU IVDR technical documentation requirements, and hospital GPO contract disclosures. Bottom-up test volume modeling across instrument placements and reagent consumption rates converged with top-down market sizing derived from statutory health insurance claims patterns.
Consistency checks validated volume and value outputs against external benchmarks including national health expenditure reports and diagnostic service operator financial disclosures. Segmentation dimensions spanned test type (liver function, kidney function, electrolyte panels), end-user site (hospital core laboratory, ambulatory surgical center, point-of-care), and geographic regulatory cluster (FDA-CLIA, EU IVDR, PMDA, NMPA). CAGRs were derived from regression analysis of historical test volume trends against aging population projections and preventive care protocol expansion schedules, with sensitivity analysis applied to capitated reimbursement adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable CLIA complexity classifications and continued statutory insurance coverage for chronic disease monitoring panels; material deviation in regulatory reclassification or reimbursement bundling acceleration would warrant model refresh. Revision becomes warranted when point-of-care analytical performance achieves parity with central laboratory reference methods across core metabolic analytes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Blood Culture Media Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Viral Antigens Market
Diagnostics
Predictive Disease Analytics Market