
 Global Diagnostic Radiopharmaceuticals and Contrast Media Market | 2026-2036
Global Diagnostic Radiopharmaceuticals and Contrast Media Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diagnostic Radiopharmaceuticals and Contrast Media Market Foresight
Gadolinium-based contrast agents is consolidating market share as macrocyclic chelates displace linear formulations over nephrogenic systemic fibrosis liability. GE Healthcare leverages its integrated cyclotron-radiopharmacy network across North America and Europe. Bracco Imaging anchors its position through proprietary liposomal ultrasound contrast technology and dedicated manufacturing in Italy. Siemens Healthineers competes by bundling diagnostic imaging hardware with proprietary radiotracer protocols.
Diagnostic radiopharmaceuticals and contrast media comprise sterile formulations containing radioactive isotopes or heavy-element compounds that enhance tissue visualization during molecular and anatomical imaging procedures. Technetium-99m generators and fluorine-18 fludeoxyglucose remain the workhorse isotopes, with half-lives of 6 hours and 110 minutes respectively dictating just-in-time production logistics. Positron Emission Tomography radiotracers command premium positioning due to cyclotron dependency and short half-lives that create regional supply moats. Magnetic Resonance Imaging contrast agents represent a mature revenue base where macrocyclic gadolinium formulations now dominate new prescriptions.
The FDA breakthrough device designation and EMA's centralized marketing authorization procedure shape competitive timelines for novel diagnostic radiopharmaceuticals across the United States and European Union. China's NMPA has accelerated local approval pathways for domestically produced technetium generators and fluorine-18 labeled compounds under national self-sufficiency directives. Stakeholders must monitor cyclotron capacity buildouts and radiopharmacy licensing frameworks as these infrastructure investments determine which geographies can sustain PET tracer supply without import dependency.
Market Dynamics
Short half-lives of fluorine-18 and technetium-99m isotopes enforce just-in-time production logistics, concentrating competitive advantage around cyclotron proximity and radiopharmacy licensing density rather than manufacturing scale alone.
Growth Catalysts
- FDA Breakthrough Device Designation:The streamlined approval pathway accelerates novel diagnostic radiopharmaceutical entry into United States clinical practice, reducing time-to-market for PET tracers targeting oncology staging.
- Academic Medical Center Expansion:Oncology departments in Germany and China are scaling PET-CT utilization for cancer monitoring, driving installed base growth and recurring isotope demand.
- Technetium-99m Generator Localization:China's NMPA self-sufficiency directives are accelerating domestic production capacity, reducing import dependency for this workhorse diagnostic isotope.
Market Restraints
- Cyclotron Capital Intensity:Regional supply moats for PET radiotracers require $3-5 million cyclotron investments per site, limiting production geography to metropolitan clusters with sufficient procedure volume.
- Nephrogenic Systemic Fibrosis Liability:Linear gadolinium chelate formulations face ongoing clinical safety scrutiny, compressing residual market share despite macrocyclic alternatives.
- MEA Licensing Bottlenecks:Radiopharmacy licensing frameworks vary across United States states and European member countries, creating fragmented compliance burdens for multi-site operators.
Strategic Opportunities
- India Diagnostic Infrastructure:Underpenetrated nuclear medicine capacity in tier-2 Indian cities offers first-mover positioning as CDSCO streamlines molecular imaging product registrations.
- Theranostic Convergence:Paired diagnostic-therapeutic radiopharmaceutical protocols are opening unified service lines, with lutetium-177 PSMA therapy driving companion imaging demand.
- Direct-to-Hospital Distribution:Bypassing wholesale intermediaries through captive radiopharmacy fleets is compressing cold-chain handoffs and extending effective isotope shelf-life.
Industry Challenges
- Radiochemist Talent Scarcity:Qualified synthesis specialists for carbon-11 and gallium-68 labeling remain concentrated in academic training programs, constraining production scale-up timelines.
- Good Manufacturing Practice Compliance:Sterile radiopharmaceutical production requires dedicated cleanroom suites and environmental monitoring systems that extend facility commissioning cycles.
- Cross-Border Isotope Transport:International shipment of fluorine-18 compounds faces customs clearance delays that consume half the available half-life, limiting sourcing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diagnostic Radiopharmaceuticals and Contrast Media Market |
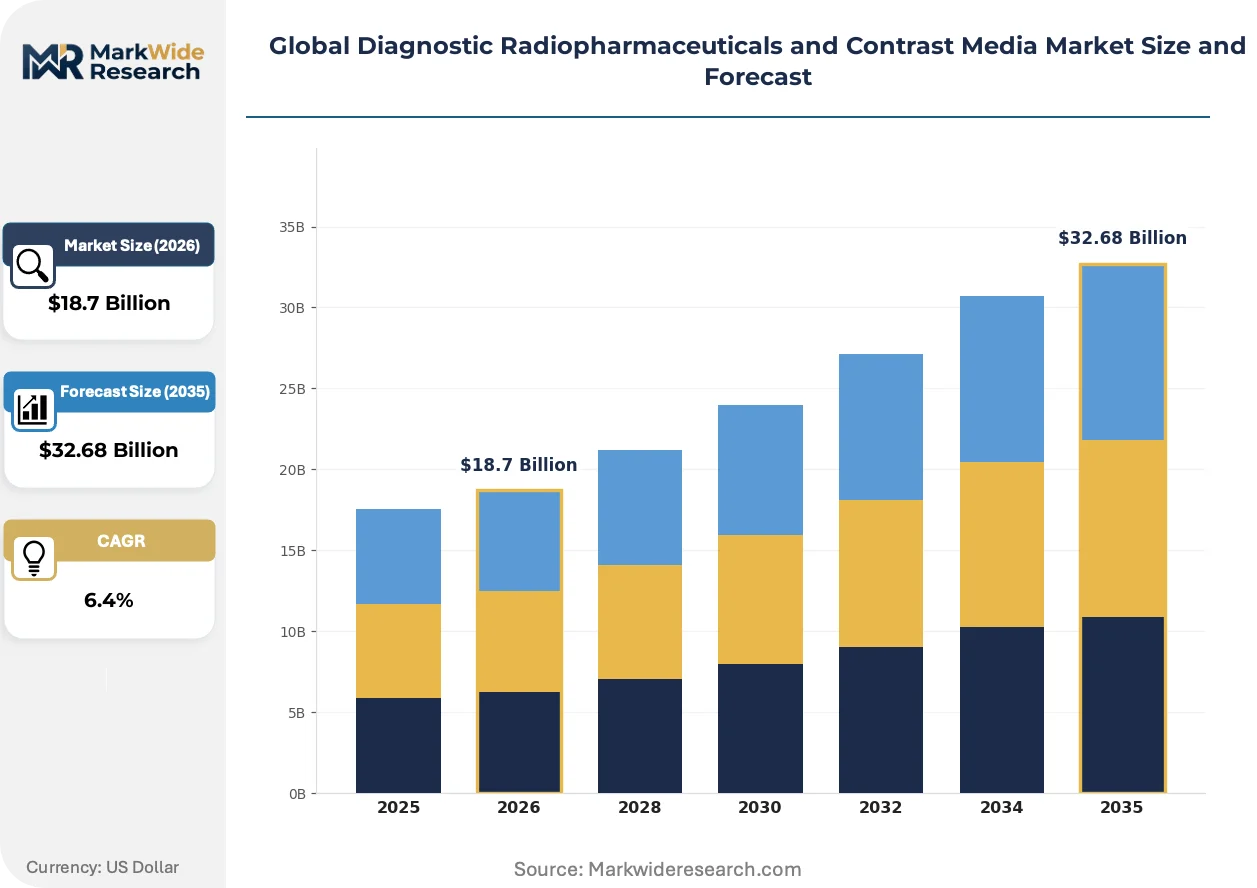
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiotracers, Contrast Agents, Radiopaque Substances, Paramagnetic Agents, Ultrasound Contrast, Others Imaging Modality: Positron Emission Tomography, Magnetic Resonance Imaging, Computed Tomography, Single Photon Emission Computed Tomography, Ultrasound Imaging, Angiography End User: Diagnostic Centers, Research Laboratories, Cancer Treatment Centers, Mobile Imaging Units, Veterinary Clinics, Nuclear Medicine Clinics Administration Route: Intravenous, Oral, Intrathecal, Inhalation, Intramuscular, Subcutaneous |
| Companies Covered | Bayer AG, GE Healthcare, Bracco Imaging, Curium, Lantheus Medical Imaging, Cardinal Health, Siemens Healthineers, Guerbet Group, Nordion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diagnostic Radiopharmaceuticals and Contrast Media Market Shifts & Advancements
Artificial intelligence integration into molecular imaging workflows is compressing interpretation timelines while novel chelation chemistry expands the addressable patient population for contrast-enhanced procedures.
Copper-64 radiolabeling is electrifying antibody and peptide imaging applications by extending diagnostic windows to 12-hour half-life intervals. Academic medical centers in the United States and Germany are adopting copper-64 PSMA and DOTATATE tracers for next-day imaging protocols. This isotope is electrifying decentralized production models by relaxing the geographic radius constraints that bind fluorine-18 distribution.
EMA's centralized marketing authorization procedure is harmonizing novel radiopharmaceutical entry across European Union member states, replacing fragmented national approval pathways. Manufacturers now submit single dossiers for technetium-labeled cardiac agents and inflammation tracers, reducing regulatory duplication. France's ANSM and Germany's BfArM are aligning inspection protocols, accelerating multi-country commercialization for compliant sponsors.
Hospital procurement departments are consolidating contrast media purchasing through multi-year sole-source agreements that bundle MRI, CT, and ultrasound agents. This behavior is displacing fragmented specialty distributor relationships in United States integrated delivery networks. Radiology service line administrators in Texas and California health systems are negotiating volume commitments in exchange for guaranteed supply priority during isotope shortages.
Global Diagnostic Radiopharmaceuticals and Contrast Media Market Segmentation
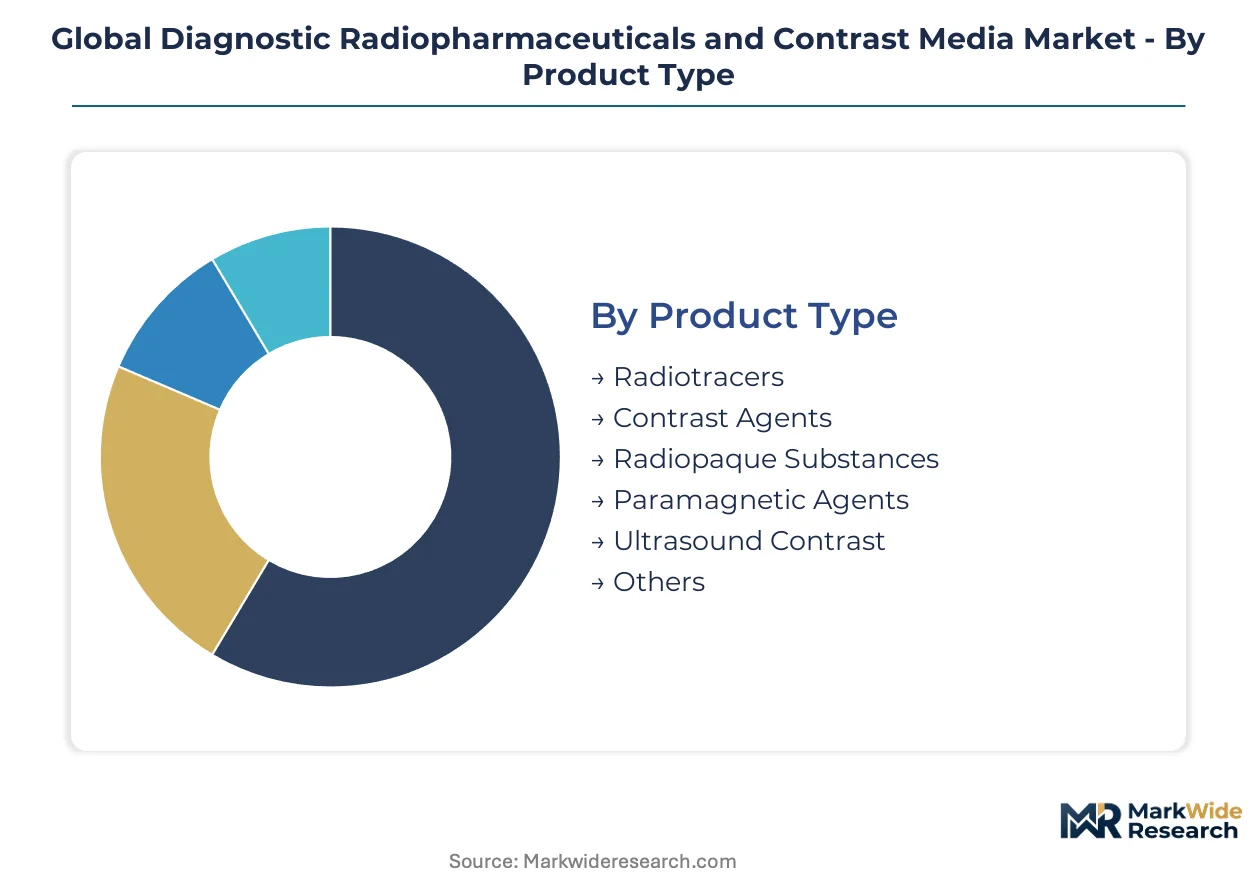
Segmentation in diagnostic radiopharmaceuticals and contrast media reveals how supply chain constraints, regulatory pathways, and clinical workflows fragment purchasing decisions. Product half-lives, imaging modality compatibility, and end-user infrastructure requirements create distinct commercial battlegrounds that resist simple volume-based competition.
Product Type:
Standardization dominates commodity isotopes while custom synthesis commands premium positioning for novel molecular targets.
- Radiotracers:Fluorine-18 and technetium-99m formulations constitute the procedural backbone across oncology and cardiology. Demand concentrates in United States academic medical centers where cyclotron proximity enables just-in-time production for PET-CT staging protocols. Short half-lives enforce regional supply moats that protect incumbent producers.
- Contrast Agents:Gadolinium-based MRI enhancers and iodinated CT media represent mature revenue pools with established safety profiles. Germany's hospital procurement coalitions are consolidating purchasing power around macrocyclic gadolinium formulations, displacing linear chelates over nephrogenic systemic fibrosis liability.
- Radiopaque Substances:Barium sulfate suspensions anchor gastrointestinal fluoroscopy procedures with minimal regulatory burden.
- Paramagnetic Agents:Iron oxide nanoparticles enable specialized liver and lymph node imaging in research settings.
- Ultrasound Contrast:Liposomal microbubble formulations from Italian manufacturing centers serve cardiac perfusion studies.
- Others:Emerging optical and multimodal agents occupy preclinical development pipelines.
Leading the category by volume: Contrast Agents. Growing fastest: Radiotracers.
Imaging Modality:
Capital intensity and reimbursement rates stratify demand across hardware-dependent procedure categories.
- Positron Emission Tomography:Cyclotron dependency and radiochemist scarcity constrain supply expansion despite superior sensitivity for oncology staging. China's NMPA self-sufficiency directives are accelerating domestic fluorine-18 production capacity in Beijing and Shanghai clusters.
- Magnetic Resonance Imaging:Non-ionizing contrast enhancement supports repeated monitoring protocols without cumulative radiation exposure. United States integrated delivery networks in Texas and California are negotiating multi-year gadolinium supply agreements with guaranteed shortage priority.
- Computed Tomography:Iodinated media enable rapid trauma and emergency diagnostics with universal scanner compatibility.
- Single Photon Emission Computed Tomography:Technetium-99m generators sustain cost-effective cardiac perfusion imaging in outpatient settings.
- Ultrasound Imaging:Microbubble contrast expands functional assessment without ionizing radiation exposure.
- Angiography:Iodinated agents support interventional cardiology and neuroradiology procedures.
Highest reimbursement rates attach to PET. Fastest procedure volume expansion: MRI contrast protocols.
End User:
Procurement sophistication varies sharply between centralized hospital systems and distributed specialty operators.
- Diagnostic Centers:High-throughput outpatient facilities in Germany aggregate PET-CT volumes that justify dedicated cyclotron partnerships. Purchasing decisions emphasize isotope reliability over unit cost given procedure scheduling density.
- Research Laboratories:Carbon-11 and gallium-68 labeling requirements drive demand for academic radiochemistry expertise concentrated in United States National Cancer Institute-designated centers.
- Cancer Treatment Centers:Theranostic convergence is pairing diagnostic PSMA imaging with lutetium-177 therapy in unified service lines.
- Mobile Imaging Units:Generator-based technetium supplies enable rural and temporary deployment models.
- Veterinary Clinics:Companion animal oncology is adopting human-grade radiotracer protocols at reduced scale.
- Nuclear Medicine Clinics:Standalone facilities face radiopharmacy licensing bottlenecks that favor hospital-affiliated operations.
Dominant volume: Diagnostic Centers. Steepest expansion trajectory: Cancer Treatment Centers integrating theranostic protocols.
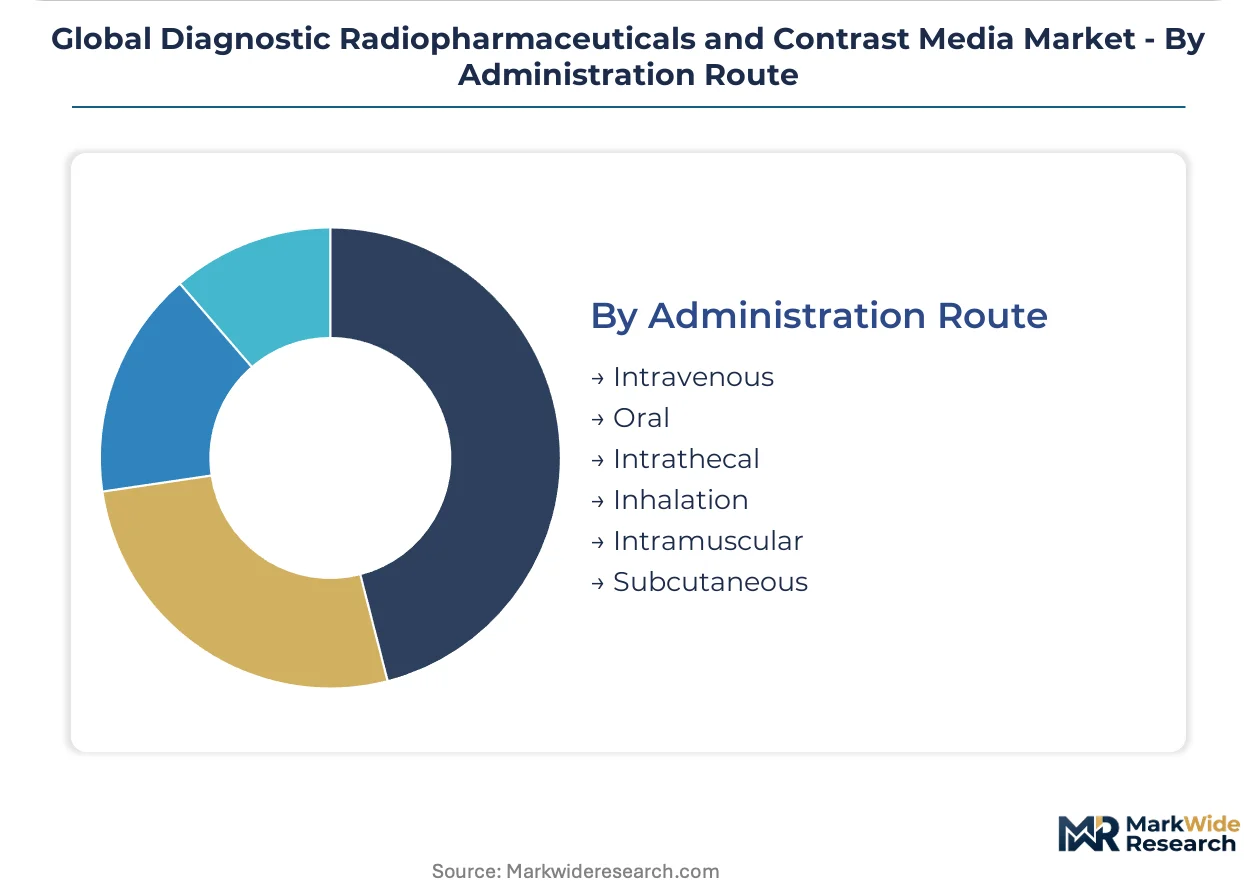
Administration Route:
Patient throughput considerations and safety monitoring requirements shape route selection across clinical settings.
- Intravenous:Universal compatibility with CT, MRI, and PET agents supports standardized nursing protocols. United States hospital systems emphasize closed-system transfer devices to reduce occupational exposure during high-volume contrast administration.
- Oral:Barium sulfate suspensions for GI studies require minimal patient preparation and monitoring overhead.
- Intrathecal:Myelography applications demand specialized neuroradiology expertise with limited procedure volume.
- Inhalation:Xenon-133 ventilation studies occupy declining nuclear pulmonary diagnostics.
- Intramuscular:Limited applications in lymphoscintigraphy for sentinel node mapping.
- Subcutaneous:Lymphatic imaging protocols in melanoma staging use filtered sulfur colloid preparations.
Intravenous administration commands absolute volume dominance. Subcutaneous applications are gaining share fastest in sentinel node protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and China as these countries build cyclotron networks and centralized radiopharmacy infrastructure. Academic medical centers in all three markets are expanding PET-CT utilization for oncology staging. Each geography presents distinct regulatory and infrastructure investment patterns.
United States
Oncology departments at academic medical centers are scaling PET-CT utilization for cancer monitoring, driving recurring isotope demand. The FDA breakthrough device designation accelerates novel diagnostic radiopharmaceutical entry into clinical practice. Cyclotron-radiopharmacy networks concentrate in metropolitan clusters across Texas and California health systems.
Germany
Hospital procurement coalitions are consolidating purchasing power around macrocyclic gadolinium formulations. The BfArM aligns inspection protocols with France's ANSM under EMA centralized procedures, accelerating multi-country commercialization. High-throughput diagnostic facilities in Bavaria and North Rhine-Westphalia aggregate PET-CT volumes justifying dedicated cyclotron partnerships.
China
NMPA self-sufficiency directives accelerate domestic technetium generator and fluorine-18 labeled compound production. Beijing and Shanghai clusters are building out cyclotron capacity to reduce import dependency for workhorse diagnostic isotopes. Tier-2 cities remain underpenetrated for nuclear medicine capacity.
India
Tier-2 cities offer first-mover positioning as CDSCO streamlines molecular imaging product registrations. Domestic production of technetium-99m generators is expanding under national self-sufficiency programs. Maharashtra and Karnataka host emerging radiopharmacy infrastructure serving diagnostic center networks.
Japan
PMDA maintains rigorous approval pathways for novel radiotracers while supporting academic carbon-11 and gallium-68 labeling programs. The Kanto region around Tokyo concentrates cyclotron capacity and radiochemist expertise. METI policies encourage domestic isotope production to secure supply chain resilience.
Global Diagnostic Radiopharmaceuticals and Contrast Media Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cyclotron proximity and radiopharmacy licensing density determining competitive advantage more than manufacturing scale alone. The vendor base stratifies into three tiers: integrated imaging hardware-radiotracer bundlers, standalone contrast media formulators, and regional radiopharmacy operators. Two dominant competitive moves are reshaping positioning: direct-to-hospital distribution bypassing wholesale intermediaries, and theranostic convergence pairing diagnostic imaging with therapeutic radiopharmaceuticals.
Among diversified healthcare conglomerates, Bayer AG and GE Healthcare exemplify integrated imaging system-radiopharmaceutical bundling strategies. Siemens Healthineers occupies a position at the hardware-protocol nexus, competing through proprietary radiotracer protocols tied to scanner installations. Bracco Imaging anchors the specialized contrast media tier through proprietary liposomal ultrasound technology. Guerbet Group and Lantheus Medical Imaging sit within the focused radiopharmaceutical developer archetype, while Curium and Cardinal Health represent radiopharmacy distribution and generator supply specialists.
| Leading Market Players |
|---|
| Bayer AG |
| GE Healthcare |
| Bracco Imaging |
| Curium |
| Lantheus Medical Imaging |
| Cardinal Health |
| Siemens Healthineers |
| Guerbet Group |
| Nordion |
| Others |
Supply & Pricing Matrix
United States hospital procurement coalitions and German diagnostic center networks concentrate purchasing power, anchoring contract-based long-term offtake agreements that lock in isotope supply priority during shortage periods. This buyer concentration enables volume-tiered pricing structures where multi-year commitments secure preferential rates against spot-market volatility.
Pricing Analysis
High-volume commodity isotopes trade on thin margins while novel PET tracers command premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates cyclotron-produced fluorine-18 compounds from generator-derived technetium-99m and imported bulk iodinated media. Cost compression in standard-grade gadolinium formulations is intensifying because macrocyclic chelates displace linear alternatives. Research laboratories exhibit lowest price sensitivity given grant-funded procurement, while outpatient diagnostic centers face acute margin pressure from reimbursement rate compression.
Supply Chain Analysis
Direct-to-hospital radiopharmacy fleets bypass wholesale intermediaries, compressing cold-chain handoffs and extending effective shelf-life for short-half-life compounds. Production concentrates in the United States, Germany, and China where cyclotron networks cluster around metropolitan medical hubs. Supply rests on molybdenum-99 reactor targets, enriched uranium feedstock, and specialized gadolinium oxide precursors. Single-source vulnerability in technetium-99m generator manufacturing creates systemic exposure to reactor maintenance shutdowns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive cyclotron capacity to secure isotope supply autonomy against import dependency and cross-border logistics friction.
For Market Incumbents: Hedge against radiochemist talent scarcity by embedding training partnerships with National Cancer Institute-designated academic centers. Secure backward integration into molybdenum-99 processing to reduce exposure to reactor supply disruptions. Lock hospital systems into multi-year sole-source agreements before CDSCO regulatory streamlining enables Indian competitor entry. For New Entrants and Emerging Players: Enter via tier-2 Indian cities where nuclear medicine capacity remains underpenetrated and CDSCO approval pathways are accelerating. Target copper-64 radiolabeling services as the most penetrable segment given relaxed geographic radius constraints versus fluorine-18. Pursue direct-to-hospital distribution partnerships rather than wholesale channel dependency. For Investors and Strategic Acquirers: Distressed-cycle entries favor radiopharmacy operators with licensed cyclotron sites in Texas and California health system clusters. Long-term viability hinges on theranostic convergence positioning where diagnostic PSMA imaging feeds therapeutic lutetium-177 demand. Monitor FDA breakthrough device designation grants as inflection indicators for novel tracer commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Capacity Buildout | Captive fluorine-18 production in Texas and California clusters reduces cross-border customs exposure. |
| Radiopharmacy Licensing Expansion | Multi-state MEA compliance in the United States creates defensible regional supply moats against entrants. |
| Theranostic Protocol Integration | Paired lutetium-177 therapy with PSMA imaging opens unified oncology service lines at academic medical centers. |
| Direct-to-Hospital Distribution | Bypassing wholesale intermediaries compresses cold-chain handoffs and extends effective isotope shelf-life. |
| Copper-64 Labeling Capability | Extended 12-hour half-life enables decentralized production models beyond fluorine-18 geographic constraints. |
Research Methodology
FDA 510(k) filings, EMA centralized marketing authorization procedures, and hospital GPO contract databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with radiopharmacy operations directors, cyclotron facility managers, nuclear medicine department heads, and biomedical procurement officers at United States academic medical centers and German diagnostic networks validated demand assumptions. Bottom-up isotope volume modeling triangulated against top-down healthcare expenditure analysis across the projection horizon.
Historical trendline analysis of PET-CT procedure volumes, technetium generator shipment records, and contrast media purchasing patterns established baseline growth trajectories. The analytical framework segmented demand by isotope half-life category, imaging modality hardware dependency, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to installed scanner base expansion and reimbursement rate evolution. Forecast inputs incorporated cyclotron capacity buildout pipelines and NMPA self-sufficiency directive implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged molybdenum-99 reactor outages or abrupt gadolinium safety labeling revisions. Periodic stress-testing of base assumptions is recommended given radiochemist training pipeline constraints and evolving FDA breakthrough device designation criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Global Serological Testing Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Rapid Diagnostics Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market