
 Pancreatic Cyst Diagnostics Market | 2026-2036
Pancreatic Cyst Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Pancreatic Cyst Diagnostics Market Analytics
The United States is fragmenting into competing diagnostic imaging ecosystems as hospital networks and outpatient clinics adopt divergent procurement standards for pancreatic cyst evaluation. GE Healthcare leverages its installed base of ultrasound platforms to sustain service revenue across academic medical centers. Siemens AG anchors its position through integrated CT-MRI workflows that streamline cyst characterization protocols. Koninklijke Philips N.V. differentiates via advanced image processing software that reduces radiologist interpretation time.
Pancreatic cyst diagnostics encompasses imaging and laboratory modalities designed to classify cystic lesions of the pancreas by malignant potential, utilizing resolution thresholds below two millimeters and contrast-enhanced tissue characterization to guide clinical management. Endoscopic ultrasound with fine-needle aspiration represents the functional gold standard for retrieving cyst fluid while simultaneously visualizing mural nodules or septations. CT scan product types dominate procedural volume in emergency settings where rapid triage decisions prove essential. Molecular imaging technology captures margin concentration as biomarker-guided diagnostics command premium reimbursement. Cloud-based delivery modes are expanding fastest among outpatient clinics seeking to decentralize specialist interpretation without capital-intensive hardware deployment.
The FDA governs device clearance through 510(k) and De Novo pathways that shape time-to-market for novel pancreatic imaging platforms, while the Centers for Medicare & Medicaid Services determines reimbursement codes that directly influence hospital purchasing cycles. ISO 13485 quality management requirements constrain supplier qualification for manufacturers serving regulated health systems across North America and Europe. Stakeholders must monitor evolving AI-enabled diagnostic algorithms and their regulatory classification as clinical decision support tools or autonomous diagnostic devices.
Market Dynamics
The convergence of artificial intelligence with endoscopic ultrasound imaging is compressing diagnostic timelines from days to hours, forcing hospital procurement committees to reassess capital allocation between traditional radiology suites and integrated AI-enabled platforms.
Growth Catalysts
- De Novo pathway acceleration:The FDA's streamlined premarket notification for AI-assisted cyst characterization tools reduces commercialization barriers for novel imaging algorithms. Device developers leverage this regulatory efficiency to reach tertiary care centers faster.
- Minimally invasive protocol adoption:Hospital end users across the United States are replacing surgical biopsy workflows with endoscopic ultrasound-guided fine-needle aspiration. This procedural shift expands addressable volume for disposable aspiration needles and specialized echoendoscopes.
- Cloud-based delivery expansion:Outpatient clinics in suburban and rural markets deploy teleradiology partnerships to access specialist interpretation without on-site MRI infrastructure. This channel innovation unlocks previously unreachable patient populations.
Market Restraints
- Reimbursement code fragmentation:The Centers for Medicare & Medicaid Services maintains separate coding for diagnostic imaging versus interventional procedures, creating administrative friction that delays hospital purchasing cycles.
- Contrast agent supply concentration:Gadolinium-based and iodinated contrast manufacturing concentrates among three European chemical suppliers, exposing imaging centers to price volatility and allocation constraints during supply disruptions.
- Pathologist interpretive bottleneck:Cyst fluid cytology requires specialized gastrointestinal pathologists whose training pipeline produces insufficient throughput to match rising procedural volume.
Strategic Opportunities
- Biomarker-guided diagnostic integration:Molecular analysis of cyst fluid DNA mutations and protein markers converges with imaging data to create composite malignancy risk scores. This technology fusion commands premium reimbursement from private payers.
- Community hospital penetration:Secondary care facilities in the United States remain underpenetrated for advanced endoscopic ultrasound services, representing white-space volume for platform manufacturers offering training and proctoring programs.
- ISO 13485 certification arbitrage:Manufacturers achieving this quality management designation gain preferential supplier status with integrated delivery networks seeking to consolidate vendor bases. The certification functions as a competitive moat against uncredentialed competitors.
Industry Challenges
- Echoendoscopist training deficit:Therapeutic endoscopy fellowship programs produce fewer than two hundred qualified operators annually, constraining service expansion regardless of equipment availability.
- Legacy PACS integration complexity:AI-enabled cyst analysis tools require interoperability with existing picture archiving systems that use incompatible data formats, extending implementation timelines and inflating IT consulting costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancreatic Cyst Diagnostics Market |
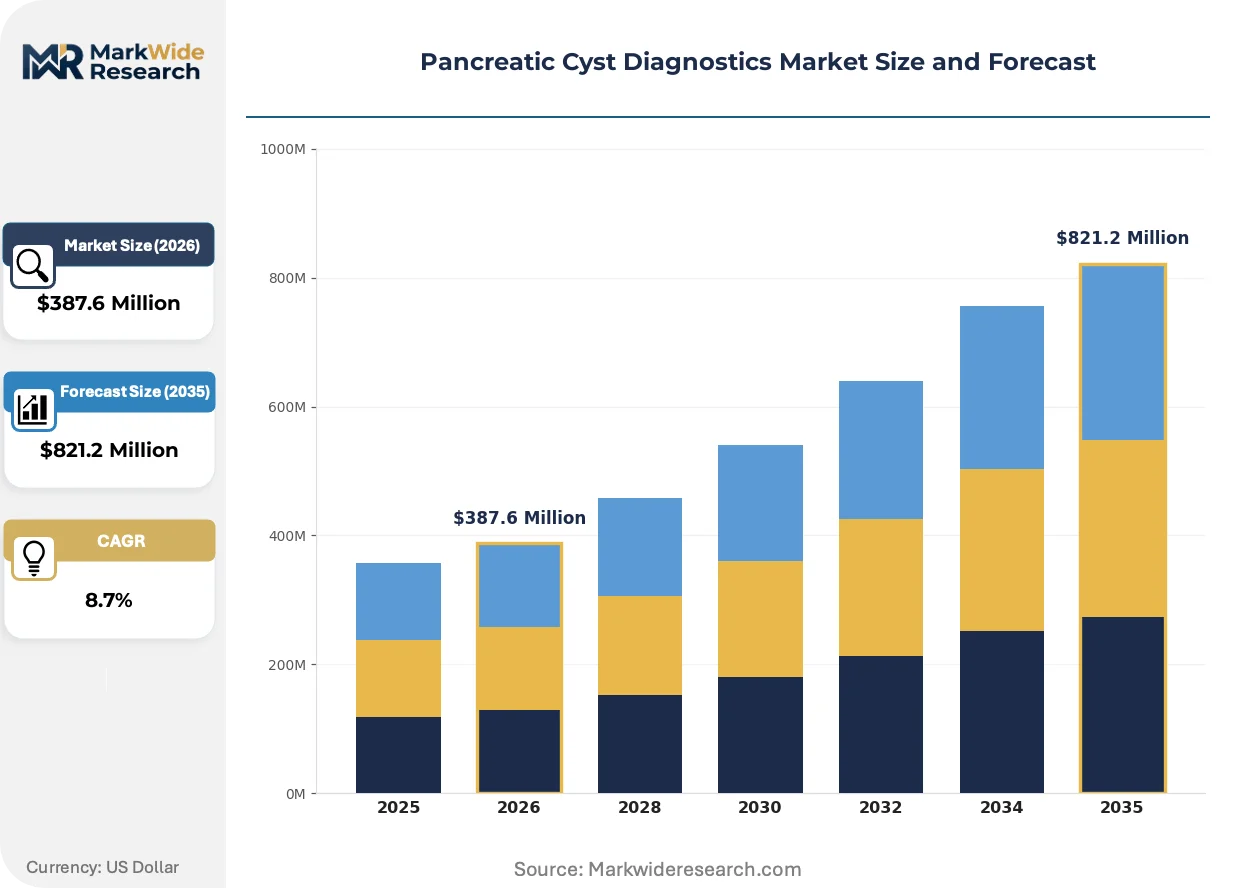
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, CT Scan, MRI, Endoscopic Ultrasound Technology: Radiology, Molecular Imaging, Image Processing, Telemedicine End User: Hospitals, Outpatient Clinics, Diagnostic Laboratories, Research Institutions Delivery Mode: On-premise, Cloud-based, Hybrid, Mobile |
| Companies Covered | GE Healthcare, Siemens AG, Koninklijke Philips N.V., Hitachi Medical System, Fujifilm Holdings Corporation, Carestream Health, Esaote SpA, Toshiba Corporation, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancreatic Cyst Diagnostics Market Evolving Landscape
Computational pathology and real-time molecular diagnostics are converging to redefine the standard of care for indeterminate pancreatic lesions, compressing the traditional multi-visit diagnostic pathway into single-session encounters.
Contrast-enhanced harmonic endoscopic ultrasound is rendering obsolete conventional B-mode imaging for detecting mural nodules in mucinous cysts. Academic medical centers in the United States are adopting this technology at accelerating rates as training protocols standardize. The modality is rendering obsolete the need for repeat procedures to confirm indeterminate findings, directly compressing revenue per patient for facilities still dependent on volume-based reimbursement.
The FDA's evolving framework for software as a medical device is forcing manufacturers to submit algorithm change control plans alongside initial 510(k) clearances. This regulatory expansion extends premarket preparation timelines but creates durable competitive positioning for first movers with approved adaptive algorithms. High-complexity academic centers are responding by consolidating purchasing authority under centralized AI governance committees.
Hospital networks are unbundling after-sales service contracts from equipment procurement, instead negotiating direct maintenance relationships with third-party clinical engineering firms. This disintermediation compresses OEM service margins while expanding price transparency for imaging platform buyers. The pattern is most visible in the southeastern United States, where regional health systems have pioneered cooperative purchasing consortiums for endoscopic ultrasound systems.
Pancreatic Cyst Diagnostics Market Segmentation
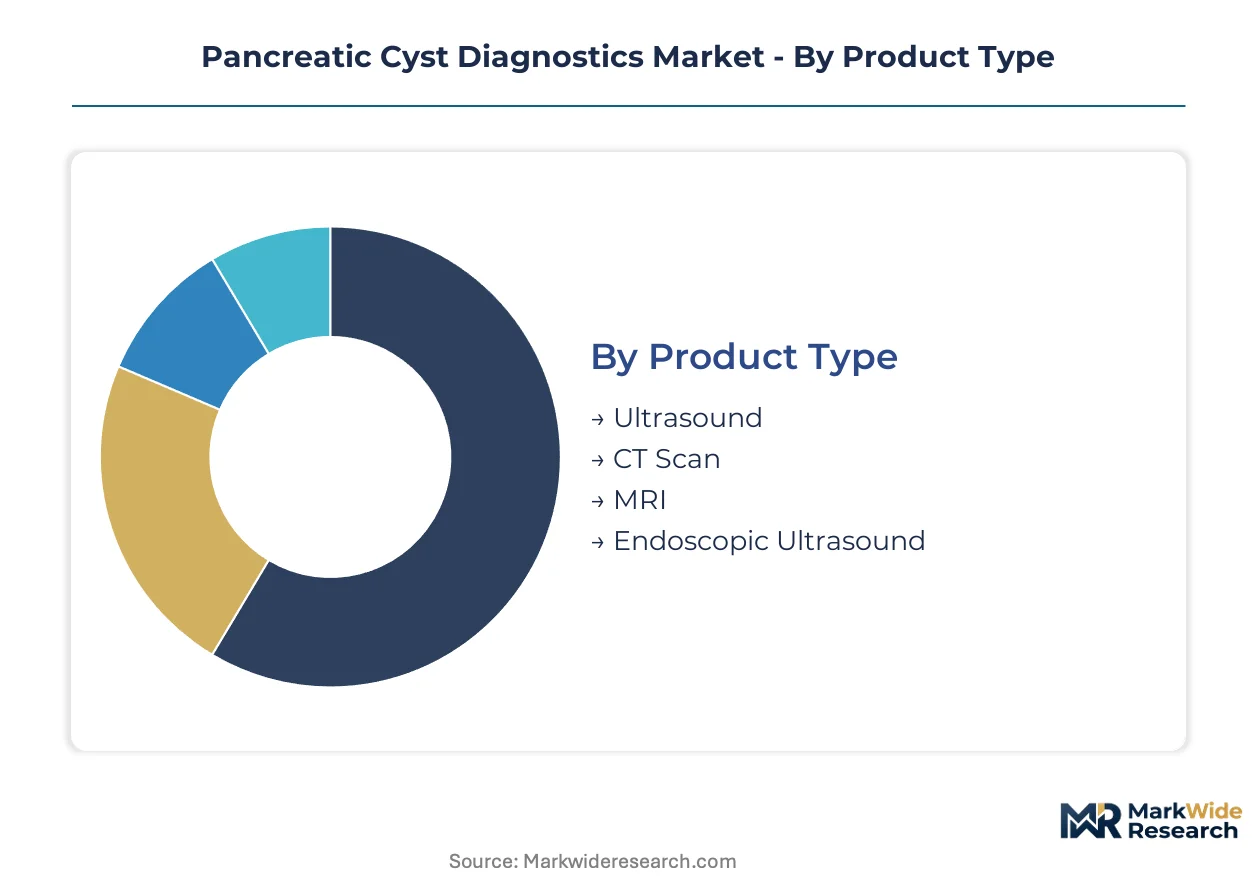
Pancreatic cyst diagnostics segments by product type and technology exhibit starkly different replacement cycles, with imaging hardware turning over every 7-10 years while software and AI modules refresh annually. Understanding these velocity differentials enables manufacturers to calibrate revenue models between capital equipment sales and recurring service streams.
Product Type:
Equipment refresh cycles vary dramatically across modalities, with emergency-deployed systems cycling fastest due to utilization intensity while specialized interventional platforms retain field service life longest.
- CT Scan:Helical multi-detector systems with sub-millimeter slice resolution dominate emergency department triage protocols. Demand concentrates in United States Level I trauma centers where rapid cyst characterization guides surgical consultation decisions. Replacement pressure intensifies as Medicare reimbursement shifts toward dose-optimized protocols.
- Endoscopic Ultrasound:Curved-linear echoendoscopes with electronic radial scanning capability enable simultaneous visualization and fine-needle aspiration. Academic medical centers in the United States drive procurement volume as therapeutic endoscopy fellowship programs expand training pipelines. Capital committees prioritize platforms with integrated elastography and contrast harmonic imaging.
- Ultrasound:Portable systems with specialized pancreatic presets serve initial screening workflows in community hospital settings.
- MRI:High-field systems with magnetic resonance cholangiopancreatography sequences anchor definitive characterization protocols at tertiary referral centers.
CT Scan dominates installed base across United States emergency departments. Endoscopic Ultrasound is where expansion concentrates as procedural volumes migrate from surgery suites to gastroenterology units.
Technology:
Cost tier stratification separates capital-intensive hardware platforms from software-enabled services that command recurring revenue without manufacturing overhead.
- Radiology:Conventional projection and tomographic imaging modalities utilizing ionizing radiation or magnetic fields to generate anatomical visualizations. Hospital networks in the United States consolidate purchasing authority under centralized radiology governance committees seeking interoperability guarantees. Procurement decisions prioritize DICOM compliance and AI-enabled workflow integration.
- Image Processing:Computational algorithms for noise reduction, segmentation, and three-dimensional reconstruction that reduce radiologist interpretation time. Outpatient clinics deploy these tools through teleradiology partnerships to access specialist-level analysis without on-site subspecialists. Cloud-native architectures enable fastest deployment timelines.
- Molecular Imaging:PET-CT and radiotracer-based modalities for metabolic characterization of cystic lesions.
- Telemedicine:Real-time video consultation and asynchronous image transmission platforms connecting rural providers with academic specialists.
Radiology commands the highest capital allocation per installation. Image Processing is gaining share fastest as health systems prioritize operational efficiency over equipment expansion.
End User:
Customer type determines procurement sophistication, with integrated delivery networks leveraging scale for price concessions while independent laboratories prioritize flexibility.
- Hospitals:Inpatient and outpatient facilities with 24-hour emergency services and surgical capabilities that anchor regional referral patterns. Tertiary care centers in the United States drive volume for advanced endoscopic ultrasound procedures requiring anesthesia support and on-site pathology. Capital budgets concentrate under value analysis committees with multi-year equipment planning horizons.
- Outpatient Clinics:Ambulatory settings focused on same-day procedures and diagnostic workups without overnight admission capabilities. Suburban and rural markets in the United States expand fastest through teleradiology partnerships that eliminate MRI infrastructure requirements. Procurement favors cloud-based delivery modes and subscription pricing.
- Diagnostic Laboratories:Standalone facilities processing cyst fluid cytology and molecular analysis.
- Research Institutions:Academic centers conducting clinical trials for novel biomarker validation and imaging algorithm development.
Hospitals dominate installed base for capital-intensive modalities. Outpatient Clinics represent the steepest expansion trajectory as procedural migration accelerates.
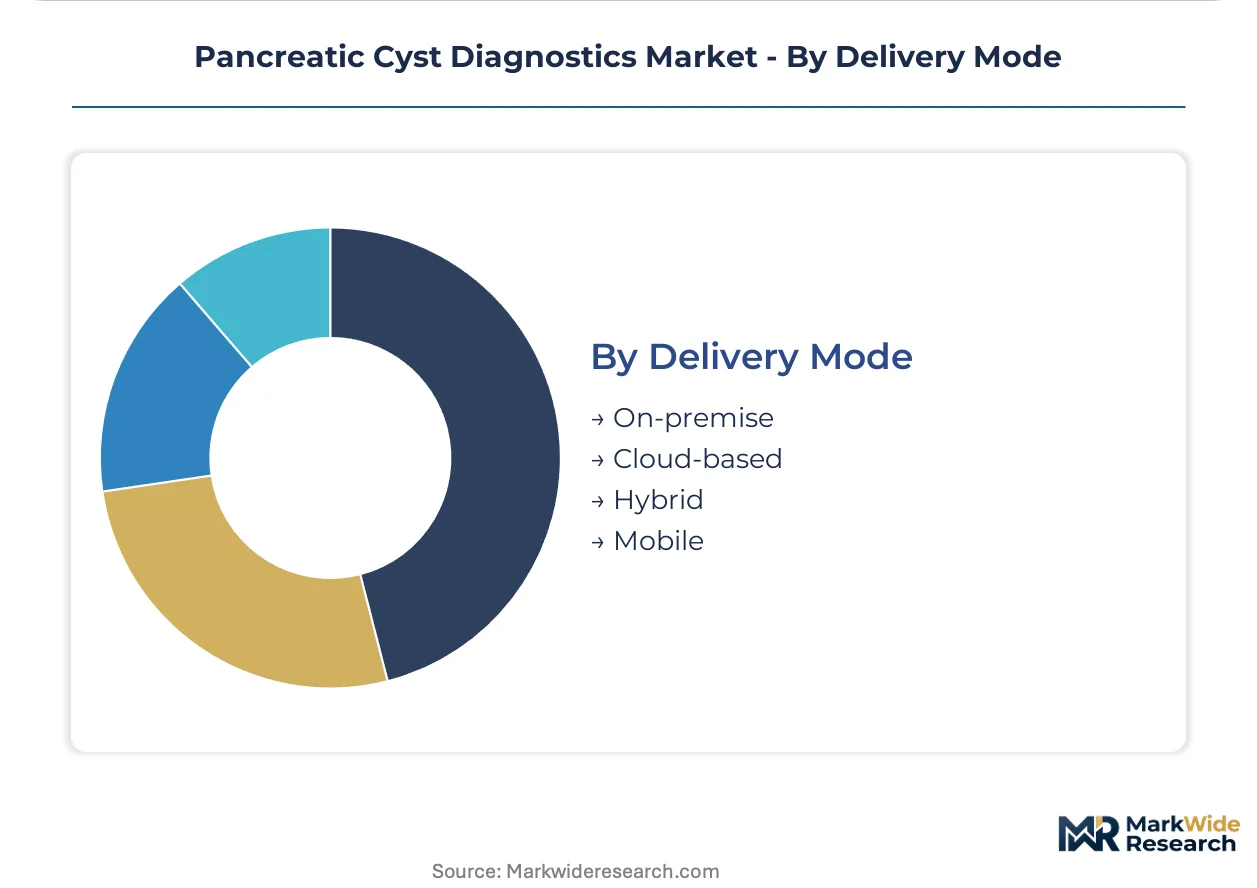
Delivery Mode:
Maturity gradients separate established on-premise deployments from emerging architectures that promise capital efficiency.
- Cloud-based:Software and image storage delivered through internet-connected infrastructure without local server hardware. United States outpatient clinics in suburban markets adopt this mode fastest to access specialist interpretation without radiologist employment costs. Cybersecurity compliance with HIPAA requirements shapes vendor selection.
- Hybrid:Architectures combining local image acquisition with cloud-based processing and storage that balance latency sensitivity with scalability. Regional health systems in the United States deploy hybrid models to maintain control of protected health information while leveraging computational resources. Implementation complexity extends deployment timelines.
- On-premise:Fully localized hardware and software installations within facility-controlled data centers.
- Mobile:Portable imaging units deployed to multiple sites through vehicle-based or modular configurations.
On-premise retains dominance in high-acuity settings with connectivity constraints. Cloud-based is climbing the fastest as rural network expansion proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing for pancreatic cyst diagnostics concentrates among three European chemical suppliers for contrast agents and a cluster of United States-based imaging OEMs. This supply-side geography shapes procurement patterns across major health systems. Regulatory frameworks diverge meaningfully across jurisdictions, creating compliance complexity for multinational device vendors.
United States
Tertiary care centers in the United States drive procedural volume for advanced endoscopic ultrasound with fine-needle aspiration. The FDA governs device clearance through 510(k) and De Novo pathways that shape time-to-market for novel imaging platforms. The Centers for Medicare & Medicaid Services determines reimbursement codes that directly influence hospital purchasing cycles in major metropolitan clusters.
Germany
German hospital networks anchor European demand for integrated CT-MRI workflows that streamline cyst characterization protocols. The EU Medical Device Regulation (MDR) imposes stringent conformity assessment requirements that extend certification timelines for new imaging algorithms. Industrial concentration in Baden-Württemberg hosts precision manufacturing capabilities for specialized echoendoscope components.
Japan
Japanese academic medical centers prioritize high-field MRI systems with magnetic resonance cholangiopancreatography sequences for definitive lesion characterization. The Pharmaceuticals and Medical Devices Agency (PMDA) maintains rigorous premarket approval standards that filter substandard imaging technologies. Tokyo and Osaka metropolitan areas concentrate installed base for contrast-enhanced harmonic endoscopic ultrasound platforms.
United Kingdom
National Health Service trusts in the United Kingdom consolidate radiology procurement under centralized imaging networks seeking interoperability guarantees. The Medicines and Healthcare products Regulatory Agency (MHRA) operates post-Brexit regulatory autonomy that diverges from EU MDR harmonization timelines. London and Southeast England clusters host the highest density of AI-enabled diagnostic algorithm validation trials.
China
Chinese tertiary hospitals expand installed capacity for endoscopic ultrasound systems as procedural volumes migrate from surgical to gastroenterology departments. The National Medical Products Administration (NMPA) accelerates review timelines for domestically manufactured imaging devices under innovation priority pathways. Yangtze River Delta metropolitan clusters concentrate manufacturing scale for portable ultrasound systems with specialized pancreatic presets.
Pancreatic Cyst Diagnostics Market Competitive Landscape
Diversified imaging conglomerates and specialized endoscopic device manufacturers split the market into distinct capability tiers. Consolidation pressure intensifies as hospital procurement committees prioritize single-vendor relationships for integrated workflow solutions. Three archetypes dominate: full-platform OEMs with installed base leverage, precision endoscope specialists with therapeutic focus, and AI-native software vendors with algorithmic differentiation. Competitive dynamics center on M&A activity targeting complementary imaging modalities and strategic partnerships bridging hardware-software gaps.
Among diversified health technology conglomerates, GE Healthcare, Siemens AG, and Koninklijke Philips N.V. occupy positions defined by installed base scale and service revenue capture. These entities exemplify the full-platform archetype through cross-modal portfolio breadth spanning CT, MRI, and ultrasound modalities. GE Healthcare leverages its ultrasound platform installed base to sustain recurring service relationships across academic medical centers. Siemens AG anchors market presence through workflow integration capabilities that reduce radiologist interpretation friction. Philips differentiates via advanced image processing software that compresses diagnostic timelines. Each represents a distinct strategic vector within the consolidated tier: service lock-in, workflow optimization, and computational differentiation.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens AG |
| Koninklijke Philips N.V. |
| Hitachi Medical System |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Esaote SpA |
| Toshiba Corporation |
| Bruker Corporation |
| Others |
Value Network & Pricing Analysis
European chemical suppliers in Belgium, Germany, and France concentrate manufacturing of gadolinium-based and iodinated contrast agents, anchoring margin capture upstream while imaging OEMs downstream compete on service-attach revenue rather than hardware premiums alone.
Pricing Analysis
FDA 510(k) and De Novo pathway classifications dictate the pricing tier structure across pancreatic cyst diagnostic platforms. Three-tier pricing separates AI-enabled premium platforms with adaptive algorithms from standard imaging hardware and economy-tier refurbished systems. Price differentiation rests on ISO 13485 certification status and integrated software companion capabilities. Pricing pressure stems from hospital procurement committees unbundling after-sales service contracts to third-party clinical engineering firms. Outpatient clinics exhibit highest price sensitivity due to capital constraints, while tertiary care centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Export-control regimes limiting semiconductor and precision optics flows constrain availability of advanced image processing chipsets for AI-enabled diagnostic platforms. Manufacturing concentrates in Germany for precision echoendoscope components, the United States for imaging system assembly, and China for portable ultrasound transducers. Supply chains draw from rare earth elements for MRI magnet fabrication, specialized optical glass for endoscope lenses, and high-purity contrast agent precursors. Single-source vulnerability concentrates in European chemical suppliers for contrast media. Distribution runs through integrated delivery networks consolidating vendor bases under long-term equipment and service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based image processing subscriptions and AI algorithm licensing are expanding faster than capital equipment sales, repositioning this market as a service-attach opportunity where recurring revenue streams eclipse one-time hardware transactions.
For Market Incumbents: Harden installed base retention through ISO 13485 certification lock-in and exclusive AI governance committee relationships at academic medical centers. Deepen backward integration into contrast agent supply through strategic sourcing agreements with European chemical manufacturers. Threaten margin compression from third-party clinical engineering firms disintermediating OEM service contracts demands preemptive channel control investments. For New Entrants and Emerging Players: Pursue community hospital penetration in United States secondary care facilities where endoscopic ultrasound services remain underdeveloped. Target suburban outpatient clinics seeking teleradiology partnerships without MRI infrastructure requirements. Deploy cloud-native image processing platforms with subscription pricing to bypass capital-intensive hardware competition. For Investors and Strategic Acquirers: Capital is best deployed toward AI-native software vendors with FDA-cleared adaptive algorithms and established hospital pilot programs. Long-term viability favors entities bridging hardware-software gaps through platform integration rather than pure-play equipment manufacturers. Watch for inflection signals in reimbursement code consolidation that would accelerate AI-enabled diagnostic adoption.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Submission | De Novo pathway clearance creates durable competitive positioning against adaptive algorithm competitors. |
| Hospital System Partnership | Academic medical center alliances secure training pipeline access and proctoring program expansion. |
| Software Companion Development | Cloud-based image processing modules capture recurring revenue without manufacturing overhead exposure. |
| Reimbursement Strategy | CMS code alignment for composite malignancy risk scoring commands premium private payer rates. |
| CE Marking Pathway | EU MDR conformity assessment opens German hospital network procurement for integrated CT-MRI workflows. |
Research Methodology
Operator-level perspectives from gastroenterologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, hospital procurement contract repositories, and ISO 13485 certification registries. Bottom-up segmentation modeling triangulated with top-down market sizing across equipment, software, and service revenue streams.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user facility class, and delivery mode architecture. CAGRs derived from equipment replacement cycle analysis, procedural volume migration trends, and cloud-based subscription adoption curves. Industry-specific forecast inputs incorporated echoendoscopist training pipeline throughput and AI regulatory classification evolution.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or CMS reimbursement rate adjustments would shift the trajectory. Forecasts reflect assumptions regarding FDA review timeline stability and contrast agent supply continuity. Material shifts in AI regulatory classification or European chemical supplier consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Sperm Count Test Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Asia-Pacific Autoimmune Disease Diagnostics Market
Diagnostics
Allergy Diagnostics Market