
 Global Rubella Diagnostic Testing Market | 2026-2036
Global Rubella Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubella Diagnostic Testing Market Intelligence
The integration of diagnostic services into national immunization and maternal health programs is reconfiguring test distribution channels. F. Hoffmann-La Roche leverages its extensive portfolio of high-throughput serological assays to serve large, centralized diagnostic laboratories. Abbott Laboratories competes with its range of rapid diagnostic tests designed for point-of-care settings and decentralized healthcare facilities, particularly in resource-limited regions.
Rubella diagnostic testing involves laboratory methods to detect rubella-specific antibodies, primarily IgM and IgG, or the viral RNA itself. These tests are essential for confirming acute infection, assessing immunity status post-vaccination, and screening pregnant women to prevent congenital rubella syndrome. ELISA kits remain the dominant product type for large-scale serological screening due to their cost-effectiveness, while PCR assays are used for confirmatory testing. Within applications, pregnancy screening constitutes the largest segment, driven by routine prenatal care protocols.
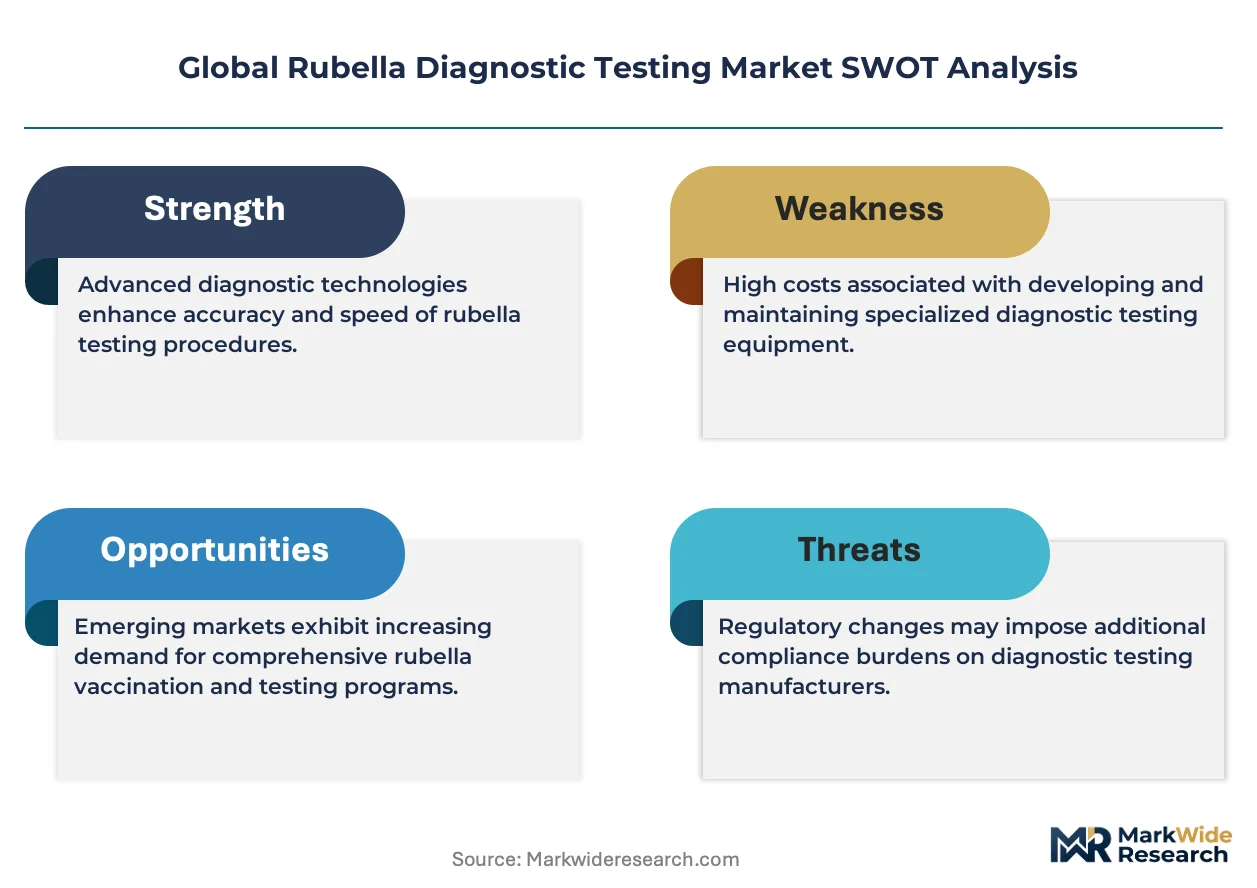
Regulatory oversight from bodies like the US FDA and the European Medicines Agency establishes stringent performance and quality standards for all diagnostic kits. Concurrently, World Health Organization prequalification and guidelines heavily influence procurement decisions by public health agencies in countries such as India and Brazil. Stakeholders must now decide how to balance investments between high-volume, centralized serology platforms and decentralized, rapid molecular diagnostics for outbreak response.
Market Dynamics
The integration of rubella screening into national maternal and child health programs represents the primary structural force shaping the market. This public health-driven shift reorients demand from reactive clinical diagnosis towards large-scale, preventative serological surveillance in high-birth-rate geographies.
Growth Catalysts
- Public Health Mandates:The World Health Organization's global elimination strategy provides a framework that encourages national governments in countries like India and Nigeria to fund and expand routine pregnancy screening programs.
- High-Incidence Geographies:Sustained demand for maternal screening is concentrated in countries with large annual birth cohorts, which are simultaneously scaling up their public health and primary care infrastructure.
- Assay Cost-Effectiveness:The accessibility and relatively low per-test cost of ELISA-based serological assays enable their deployment in mass screening initiatives managed by public health systems with constrained budgets.
Market Restraints
- Confirmatory Test Costs:The expense associated with PCR reagents and equipment for definitive viral RNA detection restricts its application primarily to centralized reference laboratories, limiting access in remote regions.
- Logistical Hurdles:Maintaining a consistent cold chain for temperature-sensitive reagents and patient samples poses a significant logistical and financial barrier for healthcare providers in parts of sub-Saharan Africa and Southeast Asia.
- Technical Limitations:The potential for cross-reactivity in serological assays, particularly IgM tests, can lead to false-positive results, requiring costly and time-consuming confirmatory testing that strains laboratory resources.
Strategic Opportunities
- Multiplex Assay Development:Combining rubella diagnostics with tests for other congenital infections, such as toxoplasmosis and cytomegalovirus, into a single multiplex panel offers significant workflow efficiencies for laboratories.
- Geographic Expansion:Public health systems in several Latin American countries, including Brazil and Mexico, are increasing investments in maternal health, opening new avenues for diagnostic test procurement.
- Point-of-Care Immunity Screening:Developing rapid, user-friendly tests to verify immunity status post-vaccination creates an opportunity to serve occupational health programs and individual patient needs outside of traditional laboratory settings.
Industry Challenges
- Skilled Personnel Shortage:A deficit of trained laboratory technologists capable of correctly performing and interpreting serological and molecular diagnostic tests persists in many regions with the highest disease burden.
- Regulatory Compliance Complexity:Manufacturers must navigate a dual-track validation process, meeting stringent performance standards from both national bodies like the US FDA and international programs like WHO Prequalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubella Diagnostic Testing Market |
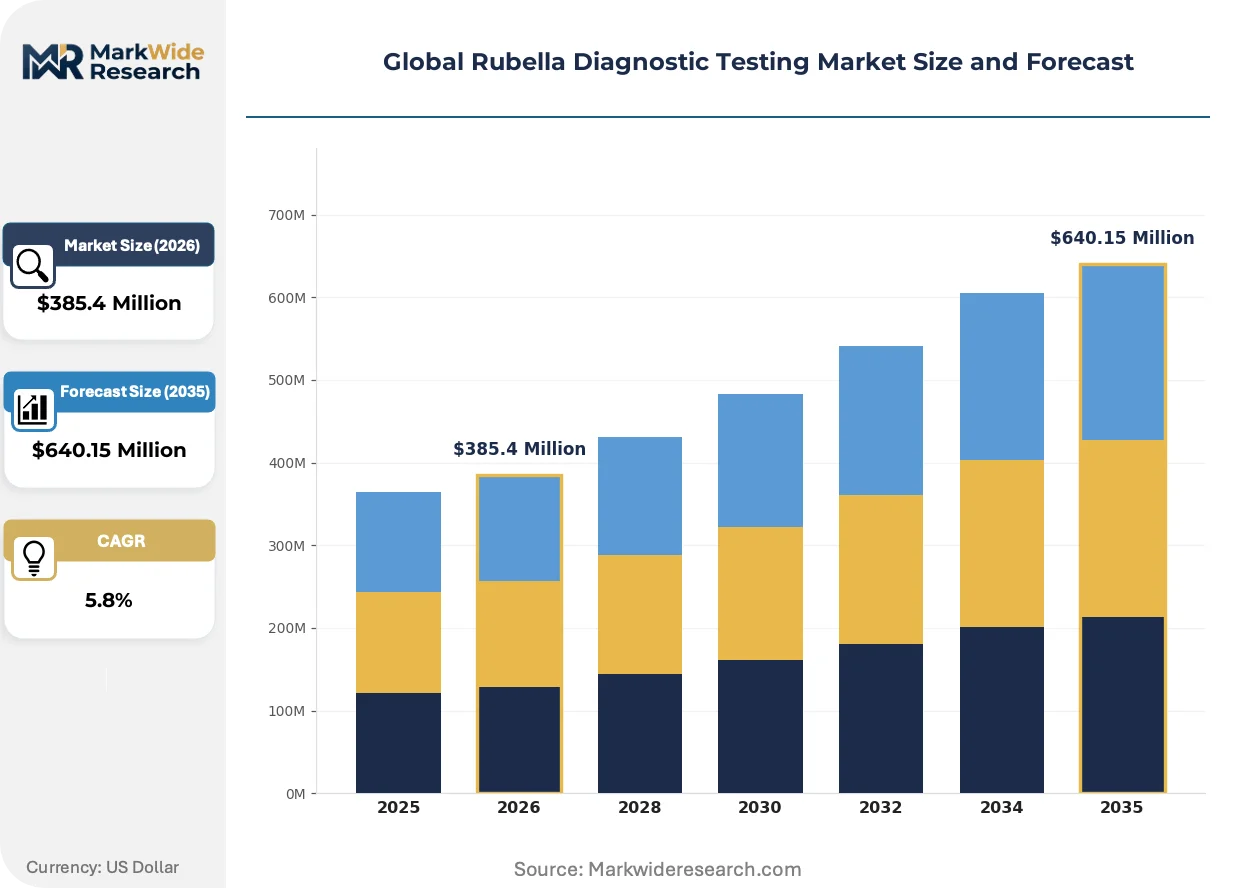
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Rapid Immunochromatographic Tests, PCR Assays, Immunofluorescence, Complement Fixation Tests Application: Pregnancy Screening, Neonatal Testing, Epidemiological Surveillance, Blood Donor Screening, Vaccine Efficacy Evaluation End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Public Health Agencies, Pharmaceutical Companies Technology: Serological Assays, Molecular Diagnostics, Lateral Flow Immunoassays, Chemiluminescence Immunoassays, Microarray Techniques |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche, Abbott Laboratories, Beckman Coulter, Ortho Clinical Diagnostics, Bio-Rad Laboratories, bioMérieux, ZEUS Scientific, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubella Diagnostic Testing Market Strategic Shifts & Innovations
The market is defined by a technological push towards decentralization and a strategic pull towards integrated diagnostic solutions. Testing workflows are evolving beyond single-pathogen analysis, embracing multiplex capabilities and platforms that serve both large-scale screening and rapid outbreak response needs.
Point-of-care molecular diagnostics provide rapid viral RNA detection outside of a traditional laboratory. These platforms are gaining traction in decentralized clinics and public health outposts for outbreak investigations where quick turnaround is critical. This technology is hybridizing the testing ecosystem by offering near-PCR accuracy with the speed of a rapid test, creating a new intermediate tier of diagnostic capability.
World Health Organization Prequalification for In Vitro Diagnostics (IVDs) is establishing a global standard for test quality, safety, and performance. This program simplifies procurement for large buyers like UNICEF and national health ministries, as it provides an independent benchmark of reliability. Manufacturers of rubella assays targeting public sector tenders in Africa and Asia increasingly view WHO prequalification as a mandatory market access requirement.
A notable shift in purchasing behavior involves moving from simple consumable-only orders to comprehensive reagent rental agreements. Under this model, laboratories receive instrumentation, reagents, and service bundled into a single per-test price, disrupting traditional distributors focused solely on kit sales. This trend is most apparent in large public health laboratory networks in Europe and North America seeking to standardize platforms and predict operational costs.
Global Rubella Diagnostic Testing Market Segmentation
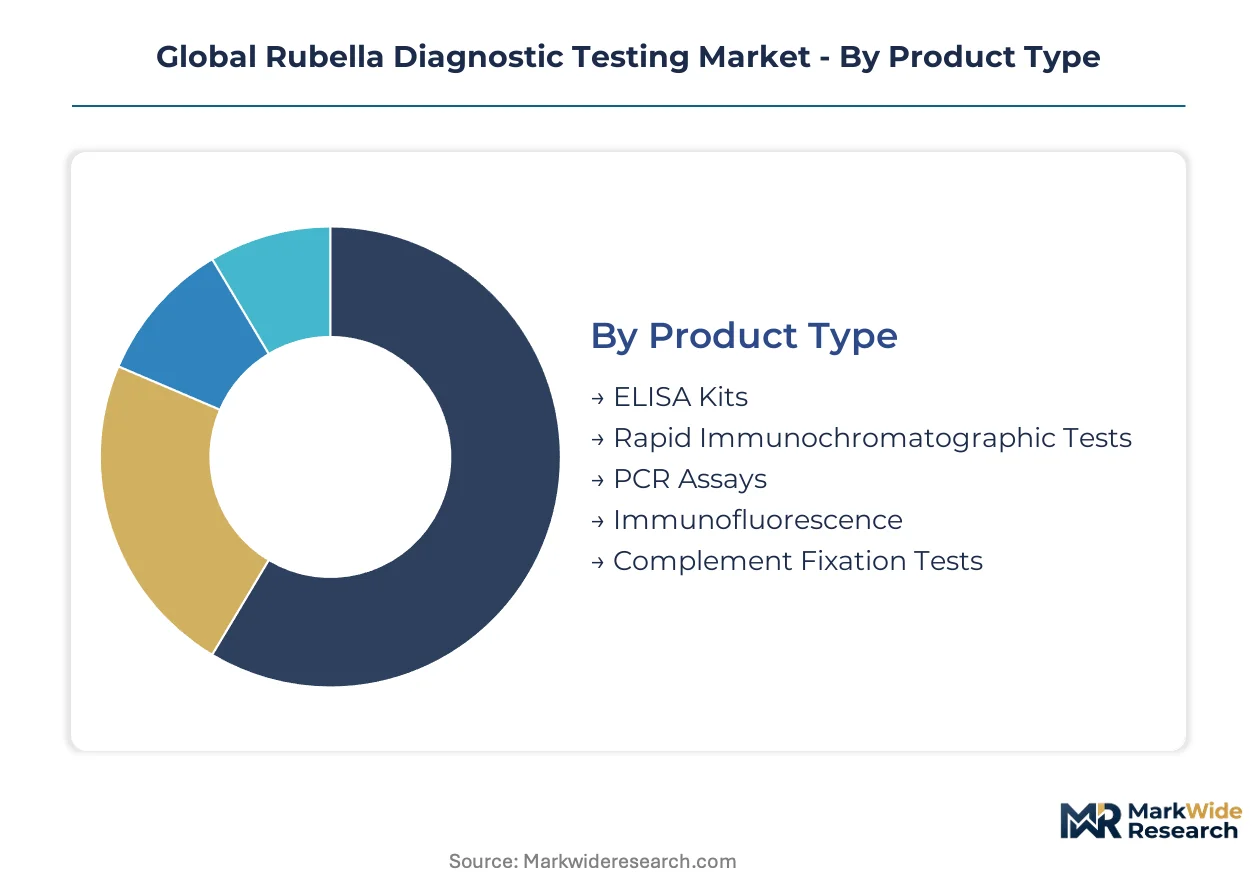
Understanding the segmentation of the global rubella diagnostic testing market reveals critical insights into procurement patterns and strategic investment areas. This detailed breakdown helps stakeholders identify specific demand drivers and technological preferences across various applications and end-user groups. Analyzing these segments is crucial for adapting product development and distribution strategies.
Product Type:
After-sales service intensity for rubella diagnostic products varies significantly based on their technical complexity and required infrastructure.
- ELISA Kits:These kits detect rubella-specific IgM and IgG antibodies through enzyme-linked immunosorbent assay technology. Demand concentrates in public health programs in India and Nigeria due to their cost-effectiveness for mass screening initiatives.
- Rapid Immunochromatographic Tests:Utilizing lateral flow technology, these tests provide quick, qualitative detection of rubella antibodies directly at the point of care. These rapid tests see high demand in decentralized healthcare facilities and resource-limited regions for immediate screening.
- PCR Assays:These assays detect rubella viral RNA directly, primarily used for confirmatory testing in centralized reference laboratories.
- Immunofluorescence:This method employs fluorescently labeled antibodies to visualize viral antigens or antibodies, often used for specialized confirmation.
- Complement Fixation Tests:An older serological method for detecting rubella antibodies, this technique has been largely superseded by more modern and efficient assays.
ELISA Kits hold the largest share; momentum sits with Rapid Immunochromatographic Tests.
Application:
The specific application for rubella diagnostic testing dictates the required sensitivity, turnaround time, and scale of testing needed by healthcare providers.
- Pregnancy Screening:Routine prenatal care protocols drive demand for rubella immunity status assessment in expectant mothers to prevent congenital rubella syndrome. This application concentrates in countries with established maternal health programs like Brazil and Mexico.
- Neonatal Testing:This involves screening newborns for congenital rubella syndrome, often requiring highly sensitive assays for early detection and intervention. Public health agencies in high-incidence geographies prioritize this testing.
- Epidemiological Surveillance:This application monitors rubella prevalence in populations to track disease trends and evaluate the effectiveness of vaccination campaigns.
- Blood Donor Screening:This ensures the safety of blood products by screening donors for active rubella infection before transfusion.
- Vaccine Efficacy Evaluation:This assesses seroconversion rates post-vaccination to determine the effectiveness of immunization programs across various demographics.
Pregnancy Screening drives the bulk of demand, while Neonatal Testing represents the steepest expansion trajectory.
End User:
Different end-user types procure rubella diagnostic tests based on their operational scale, regulatory environment, and specific patient population needs.
- Diagnostic Laboratories:Centralized facilities perform high-volume serological and molecular testing for rubella using automated platforms. These laboratories in Europe and North America often utilize comprehensive reagent rental agreements.
- Public Health Agencies:Government bodies manage mass screening programs and outbreak responses, influencing procurement decisions through World Health Organization prequalification. Countries like India and Nigeria are significant buyers for these agencies.
- Research Institutes:Academic and private research centers utilize specialized rubella assays for studying pathogenesis and vaccine development.
- Blood Banks:These institutions screen donated blood for rubella and other infectious agents to ensure transfusion safety standards are met.
- Pharmaceutical Companies:These companies employ rubella diagnostics during vaccine development and clinical trials to assess immune responses in test subjects.
Diagnostic Laboratories account for the largest volume, with Public Health Agencies showing substantial growth.
Technology:
The underlying technology for rubella diagnostics determines assay sensitivity, specificity, and suitability for various testing environments and clinical requirements.
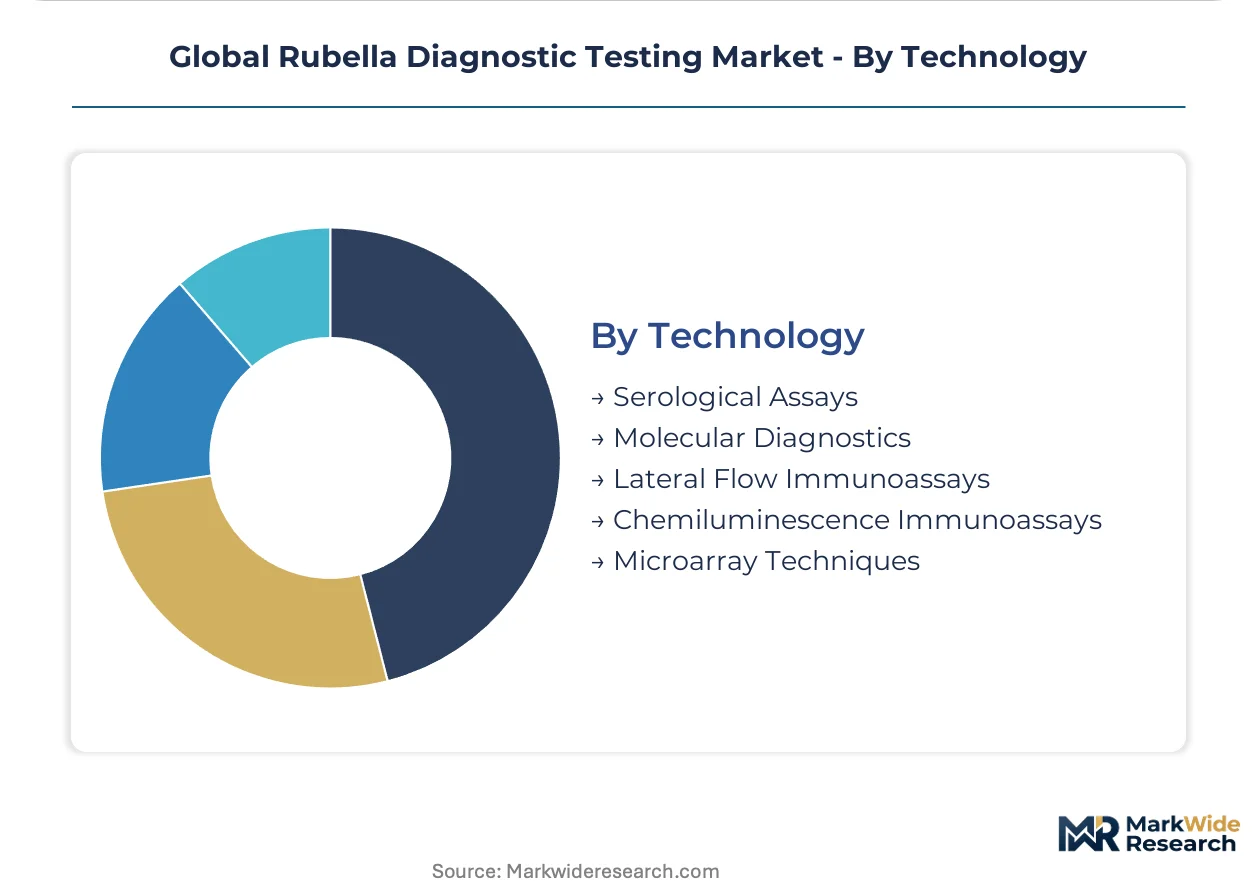
- Serological Assays:These assays detect antibodies (IgM, IgG) in patient samples, forming the backbone of large-scale immunity screening programs. ELISA-based serological assays are widely deployed by public health systems due to their cost-effectiveness.
- Molecular Diagnostics:This technology directly identifies rubella viral RNA, offering high specificity for confirming acute infections and congenital cases. Centralized reference laboratories in countries like the United States and Germany use these for definitive diagnosis.
- Lateral Flow Immunoassays:These provide rapid, qualitative results for point-of-care rubella antibody detection, particularly useful in remote settings.
- Chemiluminescence Immunoassays:These offer high sensitivity and automation for rubella antibody detection, often used in high-throughput laboratory settings.
- Microarray Techniques:These allow for multiplexed detection of multiple pathogens or antibodies simultaneously, enabling efficient screening for congenital infections.
Serological Assays dominate the market, while Molecular Diagnostics are gaining traction for confirmatory testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for rubella diagnostic tests exhibits asymmetry, with established markets like the United States dictating premium rates while countries such as India prioritize cost-effectiveness for mass screening. This dynamic shapes procurement strategies and technology adoption across diverse healthcare systems. Public health mandates and routine prenatal care protocols drive rubella diagnostic demand globally.
India
Rubella diagnostic demand in India stems from its large birth cohort and expanding maternal health programs. The country's Central Drugs Standard Control Organization (CDSCO) influences test kit approvals and public procurement. Public health agencies in states like Maharashtra and Uttar Pradesh are scaling up routine pregnancy screening using cost-effective ELISA kits.
Nigeria
National immunization efforts in Nigeria generate substantial demand for rubella testing, particularly for pregnant women. The National Agency for Food and Drug Administration and Control (NAFDAC) regulates diagnostic product quality and market access. Health ministries in populous regions like Lagos and Kano are implementing large-scale serological surveillance.
Brazil
Investments in maternal health services in Brazil are fueling demand for rubella immunity assessment. ANVISA, the national health surveillance agency, establishes stringent performance standards for diagnostic tests. Public health laboratories in São Paulo and Rio de Janeiro utilize both ELISA and molecular assays for comprehensive screening.
United States
Routine prenatal care and robust public health infrastructure drive rubella diagnostic testing in the United States. The US FDA ensures the safety and efficacy of all diagnostic kits through rigorous approval processes. Large reference laboratories in states like California and New York perform high-volume serological and confirmatory molecular testing.
Germany
Advanced healthcare systems in Germany prioritize rubella screening for pregnant women and vaccine efficacy evaluation. The European Medicines Agency (EMA) sets performance guidelines for diagnostic devices across the EU. Centralized diagnostic laboratories in cities like Berlin and Munich leverage high-throughput automated platforms.
Global Rubella Diagnostic Testing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying reagents and raw materials. The rubella diagnostic market exhibits a tiered structure, with global diversified players competing alongside specialized IVD manufacturers. Strategic archetypes include high-throughput serology providers and rapid point-of-care test developers. Geographic expansion into high-incidence regions and portfolio diversification into multiplex assays are dominant competitive moves.
Global diagnostic leaders like F. Hoffmann-La Roche and Abbott Laboratories exemplify the strategic tension between centralized high-volume testing and decentralized rapid diagnostics. F. Hoffmann-La Roche represents the archetype of a large-scale serology platform provider, leveraging extensive assay portfolios for reference laboratories in developed markets. Abbott Laboratories, on the other hand, occupies a position focused on rapid diagnostic tests, catering to point-of-care settings and resource-limited regions in emerging economies. Thermo Fisher Scientific further anchors the market through its broad portfolio spanning various diagnostic technologies and instruments, serving both research and clinical applications. These companies consistently invest in research to maintain their market presence and adapt to evolving diagnostic needs.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Beckman Coulter |
| Ortho Clinical Diagnostics |
| Bio-Rad Laboratories |
| bioMérieux |
| ZEUS Scientific |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Specialized reagent manufacturers, often concentrated in advanced economies, exert significant influence over downstream pricing for rubella diagnostic kits. This concentration shapes the availability and cost of critical components, impacting the final product pricing for public health systems globally.
Pricing Analysis
Configured-to-order pricing for high-throughput automated platforms contrasts with standard per-unit transactional pricing for ELISA kits. Price differentiation stems from the level of automation and required certifications like WHO Prequalification. Cost compression intensifies in high-volume public health tenders due to budget constraints. Public health agencies are highly price-sensitive for mass screening, while reference laboratories prioritize performance and after-sales service.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage cash flow for diagnostic kit manufacturers. Geographic supply concentration for raw materials like antibodies and enzymes centers in Europe and Asia. The supply chain relies on specialized plastics and chemical reagents. Logistics chokepoints for temperature-sensitive reagents and patient samples pose a structural risk in remote regions. Distribution runs through a dual model, involving direct sales to large laboratories and tender-based procurement for public health agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rubella diagnostic market requires a robust substitution defense as incumbents navigate the emergence of rapid point-of-care molecular diagnostics. This technological shift demands strategic adaptation from established players.
For Market Incumbents: Pre-empt the shift towards decentralized testing by investing in rapid molecular diagnostics and multiplex assay development. Diversify portfolios to include platforms suitable for both centralized laboratories and point-of-care settings, mitigating the threat of new entrants. Enhance R&D in assay miniaturization and automation to maintain competitive positioning against emerging technologies. Strengthen channel control in high-growth geographies like India and Nigeria.
For New Entrants and Emerging Players: Establish a beachhead in underserved public health segments by focusing on accessible, rapid point-of-care solutions. Target occupational health screening and remote immunity verification as white-space opportunities. Develop low-cost, user-friendly rapid tests that can achieve WHO Prequalification for market access. Leverage digital health platforms to integrate testing results and improve patient follow-up in resource-limited regions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized IVD manufacturers focusing on niche molecular diagnostic technologies or point-of-care platforms. The market demonstrates long-term viability, sustained by global health mandates for disease elimination over a 5-10 year window. Identify acquisition targets with strong intellectual property in multiplex assays or established distribution networks in Latin America. Increased procurement by large intergovernmental organizations for new diagnostic formats serves as a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Assay Development | Integrates multiple tests into one panel, driving laboratory workflow efficiencies and reducing per-test costs. |
| WHO Prequalification Pursuit | Secures market access in public health tenders, validating product quality for national health ministries. |
| Reagent Rental Model Expansion | Reduces upfront capital expenditure for laboratories, standardizing operational costs for high-volume users. |
| Point-of-Care Platform Integration | Enables rapid viral RNA detection in decentralized clinics, improving outbreak response times. |
| Geographic Expansion into Latin America | Captures new demand from increasing investments in maternal health programs across the region. |
Research Approach
Desk research of regulatory filings, public health reports, and scientific publications preceded structured interviews with diagnostic laboratory directors and public health officials. This initial data collection was complemented by discussions with regulatory affairs specialists and maternal health program managers. Bottom-up and top-down triangulation ensured data accuracy and consistency across various market segments.
Assumptions regarding global vaccination coverage and public health funding levels were held fixed, while technological adoption rates were varied across the projection horizon. The analytical framework integrated historical data with projected trends over the modeling period. Segmentation dimensions modeled included product type, application, end-user, technology, and regional public health spending. Compound annual growth rates were derived from volume and value projections, considering market saturation and new product introductions, with vaccination coverage rates and maternal health program budgets as key inputs.
Stress conditions across disease outbreak severity and regulatory policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these underlying assumptions. Unforeseen pandemic events or significant changes in global health priorities represent specific risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
IVD Antibody Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Spain in-Vitro Diagnostics Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Mycoplasma Detection System Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Veterinary Diagnostics Market