
 Asia Pacific in Vitro Diagnostics Market | 2026-2036
Asia Pacific in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific in Vitro Diagnostics Market Analysis
The EU Green Deal is recalibrating procurement standards for medical device supply chains serving Asia Pacific markets. Sysmex Corporation leverages its hematology automation dominance across Japanese hospital networks. Abbott sustains competitive positioning through point-of-care immunoassay specialization in Southeast Asian clinics. Danaher Corporation anchors regional molecular diagnostics growth via integrated reagent-instrument platforms.
In vitro diagnostics encompasses clinical testing of biological specimens outside the living organism, employing reagent-mediated biochemical reactions, optical detection systems, and software-controlled assay protocols to identify disease markers, metabolic states, or therapeutic responses. The primary commercial purpose centers on enabling clinicians to diagnose conditions, monitor treatment efficacy, and guide precision medicine decisions with reproducible accuracy. Reagents capture the dominant margin pool given recurring consumption tied to instrument installed bases, while molecular diagnostics represents the fastest-expanding technology segment driven by oncology and infectious disease applications. Point-of-care units emerge as the highest-growth end-user channel, particularly in rural and semi-urban geographies where centralized laboratory access remains constrained.
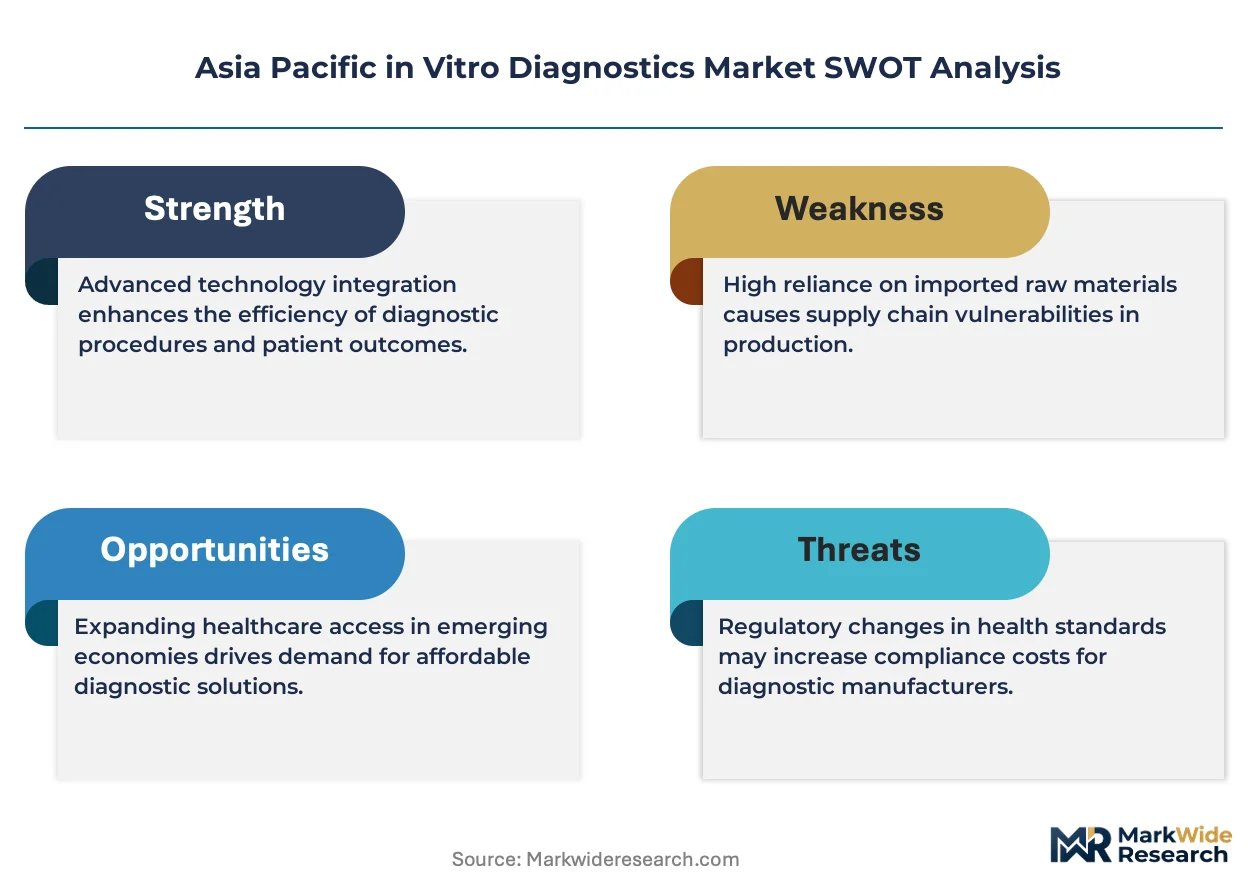
Japan's PMDA, Australia's TGA, and India's CDSCO collectively shape product registration timelines, quality certification requirements, and post-market surveillance obligations across the region. PMDA's streamlined review pathways for companion diagnostics accelerate oncology test commercialization, while CDSCO's phased strengthening of medical device rules elevates compliance costs for imported instruments. Stakeholders must monitor divergent national regulatory maturation rates when allocating manufacturing localization and clinical validation investments.
Market Dynamics
Japan's PMDA companion diagnostic fast-track pathways are compressing product launch timelines while India's CDSCO medical device rule strengthening forces manufacturing localization decisions across Southeast Asian supply chains.
Growth Catalysts
- Automated hematology workflows:Japanese hospital networks deploy closed-system analyzers to reduce manual slide review. Reagent consumption locks in recurring revenue streams.
- CDSCO regulatory maturation:India's phased medical device rules elevate quality certification requirements. Importers must establish local validation infrastructure.
- Point-of-care immunoassay expansion:Southeast Asian clinics adopt cartridge-based platforms for fever and metabolic panels. Rural access constraints drive decentralized testing demand.
Market Restraints
- Reagent import dependency:Specialized enzymes and antibodies concentrate in North American and European supplier bases. Currency volatility amplifies landed cost uncertainty.
- Instrument capital intensity:Molecular diagnostics platforms require substantial upfront equipment investment. Mid-tier laboratories face financing constraints for integrated systems.
- Fragmented regulatory timelines:Australia's TGA, Japan's PMDA, and India's CDSCO maintain divergent clinical evidence requirements. Parallel submission strategies drain regulatory resources.
Strategic Opportunities
- Tier-two Indian city penetration:Private laboratory networks expand fever and metabolic panels in Lucknow, Indore, and Coimbatore. Underpenetrated patient populations exceed metro saturation levels.
- EU Green Deal procurement alignment:Medical device supply chains serving Asia Pacific markets face recalibrated sustainability certification requirements. Early adopters capture preferential vendor status.
- Companion diagnostic convergence:Oncology biomarker testing integrates with therapeutic selection workflows. PMDA streamlined pathways accelerate biomarker-instrument co-development timelines.
Industry Challenges
- Multiplex assay validation complexity:Simultaneous detection of multiple disease markers demands extensive analytical performance studies. Laboratories struggle with verification resource allocation.
- Legacy LIS integration friction:New instrument platforms must interface with entrenched laboratory information systems. Middleware development extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific in Vitro Diagnostics Market |
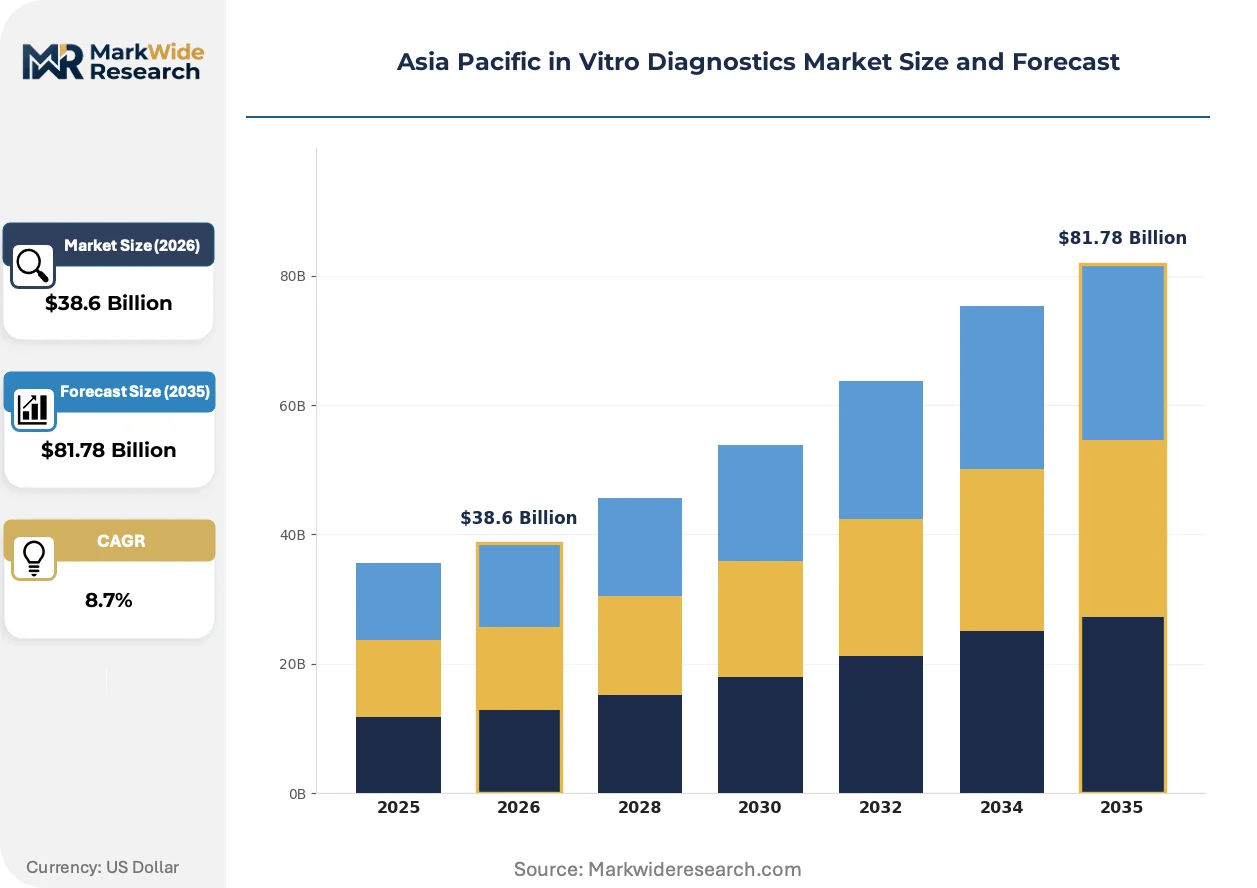
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables End User: Hospitals, Diagnostic Laboratories, Research Institutions, Point-of-Care Units Technology: Molecular Diagnostics, Immunoassays, Hematology, Clinical Chemistry Application: Oncology, Infectious Diseases, Metabolic Disorders, Cardiac Conditions |
| Companies Covered | Sysmex Corporation, NIHON KOHDEN CORPORATION, Shimadzu Corporation, Abbott, Roche, Siemens Healthineers, bioMérieux, Thermo Fisher Scientific, Danaher Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific in Vitro Diagnostics Market Emerging Trajectories
Three forces are actively restructuring Asia Pacific diagnostics: instrument architecture is fragmenting into interchangeable modules, regulatory jurisdictions are harmonizing quality benchmarks, and procurement authority is migrating from centralized laboratories to distributed clinical settings.
Integrated reagent-instrument platforms are modularizing molecular diagnostics workflows. Mid-sized hospital laboratories in South Korea and Thailand adopt component-based systems that separate nucleic acid extraction from amplification detection. This architecture compresses capital deployment while preserving assay menu flexibility.
Japan's PMDA has implemented streamlined review pathways for companion diagnostics that compress oncology test commercialization timelines. The industrial consequence accelerates biomarker-driven therapeutic selection in gastric and lung cancer segments. Korean MFDS and Australian TGA are observing PMDA precedent for potential pathway alignment.
Procurement authority for diagnostic instruments is decentralizing from hospital central laboratories to individual department heads and clinic operators. In India's tier-two cities, physician-entrepreneurs now directly negotiate point-of-care device contracts. This shift fragments vendor concentration and elevates after-sales service responsiveness as a selection criterion.
Asia Pacific in Vitro Diagnostics Market Segmentation
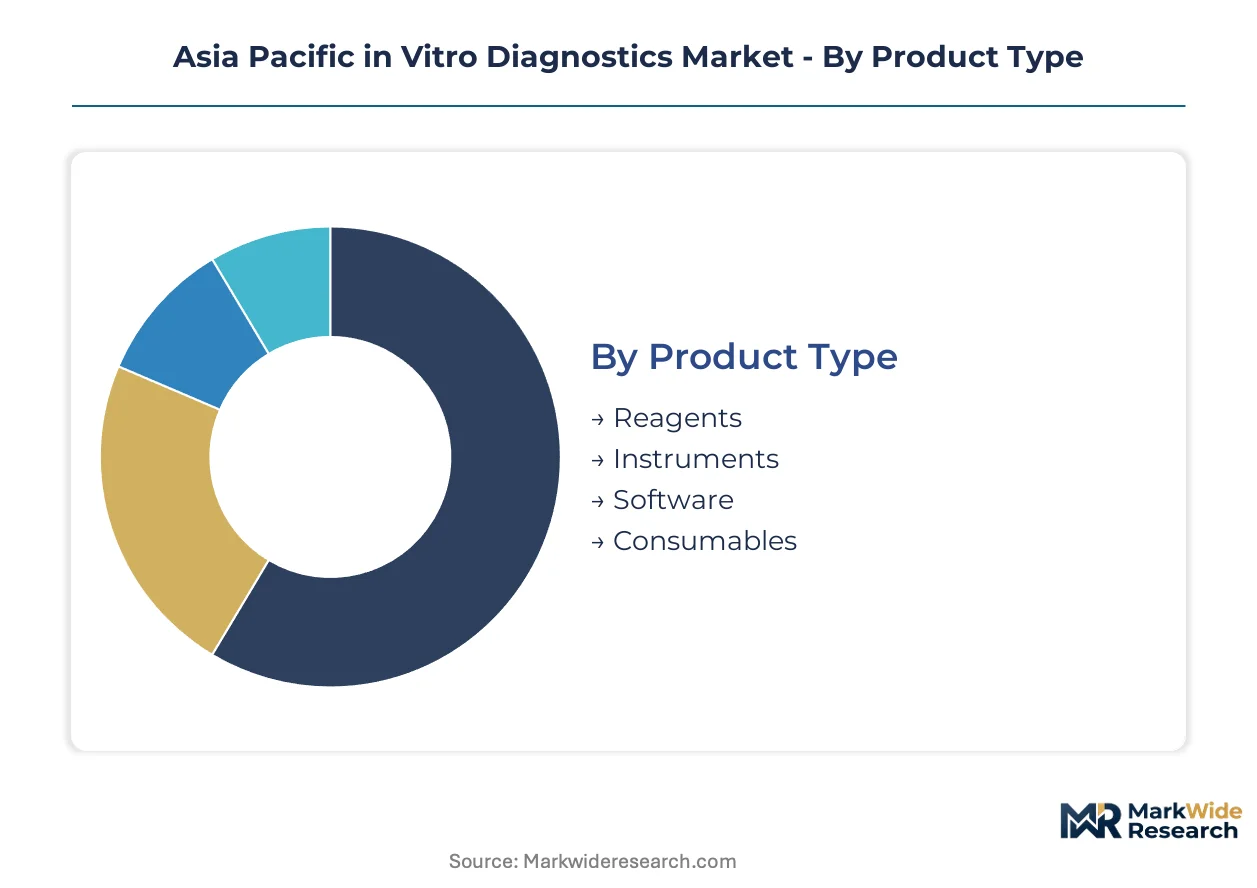
Segmentation in Asia Pacific in vitro diagnostics reveals how regulatory complexity, capital intensity, and care delivery models fragment procurement behavior across product categories. Each dimension carries distinct certification burdens and margin structures that shape vendor strategy.
Product Type:
Japan's PMDA and India's CDSCO impose divergent quality system requirements on instruments versus reagents, with software modules now facing standalone cybersecurity validation.
- Reagents:Enzyme and antibody formulations constitute the recurring revenue anchor, with consumption tied directly to installed instrument bases. Japanese hospital networks lock in multi-year reagent supply contracts alongside hematology analyzer deployments, while Indian private laboratories negotiate spot purchasing for metabolic panels in tier-two cities.
- Instruments:Closed-system analyzers dominate Japanese procurement, requiring PMDA quality certification and local technical validation. Capital intensity constrains mid-tier laboratory adoption across Southeast Asia, where leasing arrangements and reagent-rental bundles predominate.
- Software:Assay protocol management and LIS middleware face emerging cybersecurity mandates under Australia's TGA and Japan's PMDA software-as-medical-device guidance.
- Consumables:Cartridges, tips, and sample containers capture volume share in point-of-care channels, with supply security concerns driving dual-sourcing requirements.
Reagents sit at the top of the volume ranking, with software climbing the fastest as regulatory jurisdictions expand digital health oversight.
End User:
Procurement authority concentrates differently across settings: hospital central laboratories negotiate enterprise contracts, while point-of-care operators purchase through distributor networks with limited technical support.
- Hospitals:Japanese tertiary centers deploy integrated reagent-instrument platforms under PMDA-approved quality systems. Automated hematology workflows reduce manual slide review, locking in vendor relationships through consumable dependency.
- Diagnostic Laboratories:India's private network operators in Lucknow, Indore, and Coimbatore expand fever and metabolic panel capacity. CDSCO medical device rule strengthening forces local validation infrastructure investment.
- Research Institutions:Academic medical centers in South Korea and Australia drive companion diagnostic co-development with pharmaceutical sponsors.
- Point-of-Care Units:Southeast Asian clinics adopt cartridge-based immunoassay platforms for decentralized fever diagnosis. Rural access constraints elevate after-sales responsiveness as a selection criterion.
Hospitals command the highest absolute spending, with point-of-care units expanding most quickly as procurement authority decentralizes to physician-entrepreneurs.
Technology:
Technology selection correlates with disease burden and reimbursement pathways: oncology biomarker testing integrates with therapeutic selection, while infectious disease panels address outbreak surveillance mandates.
- Molecular Diagnostics:Nucleic acid amplification and sequencing platforms enable precision oncology workflows. PMDA streamlined pathways accelerate biomarker-instrument co-development timelines for gastric and lung cancer applications.
- Immunoassays:Antibody-mediated detection dominates point-of-care channels across Southeast Asian clinics. Cartridge-based platforms reduce operator training requirements in resource-constrained settings.
- Hematology:Sysmex Corporation's automation dominance spans Japanese hospital networks. Closed-system analyzers minimize manual intervention.
- Clinical Chemistry:Spectrophotometric and ion-selective electrode methods support routine metabolic panel testing in high-throughput laboratories.
Hematology leads current installed base volume, with molecular diagnostics gaining share fastest through oncology biomarker convergence.
Application:
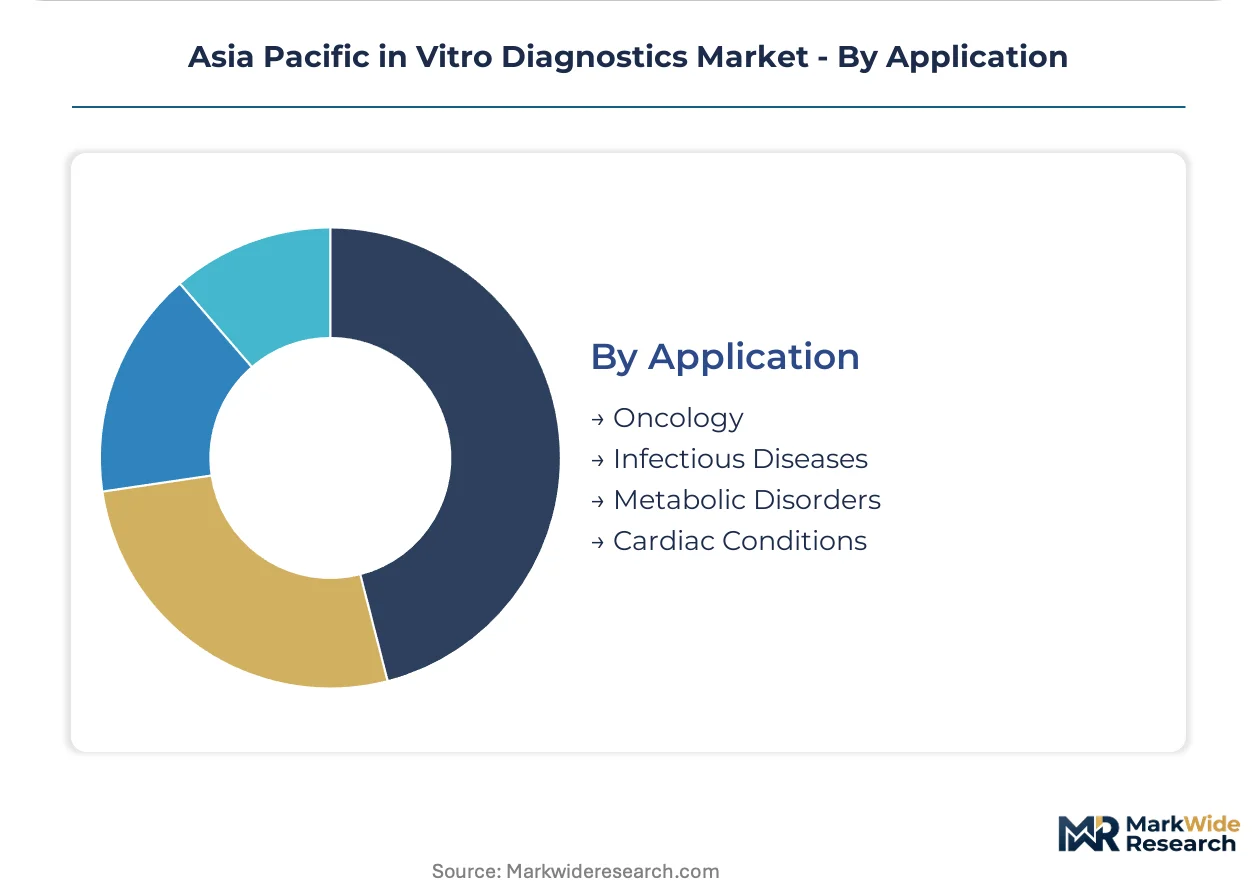
Application segmentation reflects epidemiological priorities and therapeutic pipeline concentration, with infectious disease and oncology commanding disproportionate R&D investment.
- Oncology:Companion diagnostic integration with therapeutic selection workflows reshapes Japanese and Korean clinical practice. Biomarker testing for gastric and lung cancer segments accelerates under PMDA fast-track pathways.
- Infectious Diseases:Fever panel expansion drives point-of-care adoption across India's tier-two cities and Southeast Asian clinics. Outbreak surveillance requirements sustain centralized laboratory investment.
- Metabolic Disorders:Diabetes and thyroid testing volumes concentrate in diagnostic laboratory networks. Indian private operators expand panel menus in underpenetrated urban centers.
- Cardiac Conditions:Troponin and natriuretic peptide testing supports emergency department triage, with assay standardization challenges across multi-vendor installations.
Infectious diseases anchor current test volume, with oncology applications climbing fastest through companion diagnostic regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered automated hematology analyzer commercialization during the 1980s, establishing quality benchmarks that shaped subsequent regulatory frameworks across Asia Pacific. That industrial foundation now diffuses through Korean and Chinese manufacturing clusters while Indian entrepreneurs adapt point-of-care platforms for resource-constrained settings.
Japan
Japanese tertiary hospitals deploy closed-system hematology analyzers to minimize manual slide review, locking vendors into multi-year reagent supply contracts. PMDA streamlined review pathways compress companion diagnostic commercialization timelines for gastric and lung cancer biomarkers. Tokyo-Osaka corridor laboratories anchor precision oncology testing volumes.
India
Private diagnostic networks expand fever and metabolic panel capacity across Lucknow, Indore, and Coimbatore as physician-entrepreneurs negotiate direct point-of-care device contracts. CDSCO phased medical device rule strengthening forces importers to establish local validation infrastructure and quality certification systems. Tier-two city laboratory construction outpaces metro saturation.
South Korea
Mid-sized hospital laboratories adopt modular molecular diagnostics platforms that separate nucleic acid extraction from amplification detection. Korean MFDS observes PMDA companion diagnostic precedent for potential regulatory pathway alignment. Seoul academic medical centers drive biomarker-instrument co-development with pharmaceutical sponsors.
Australia
TGA cybersecurity mandates for software-as-medical-device now govern assay protocol management and LIS middleware validation requirements. Australian reference laboratories maintain infectious disease surveillance panels that anchor regional outbreak response coordination. Sydney-Melbourne diagnostic procurement concentrates enterprise contract negotiation authority.
Thailand
Southeast Asian clinics adopt cartridge-based immunoassay platforms for decentralized fever diagnosis where rural access constraints persist. Thai hospital procurement authorities evaluate EU Green Deal sustainability certification requirements for imported instrument supply chains. Bangkok laboratory networks serve as distribution hubs for neighboring Mekong economies.
Asia Pacific in Vitro Diagnostics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reagent-instrument bundling sophistication, with Japanese and Western multinationals commanding closed-system installed bases while regional assemblers compete on point-of-care cartridge pricing. Market structure consolidates around hematology automation specialists, molecular diagnostics platform integrators, and immunoassay point-of-care deployers. Three archetypes dominate: integrated reagent-instrument vendors locking hospitals into consumable streams, modular molecular diagnostics suppliers enabling menu flexibility, and decentralized testing specialists serving clinic-direct procurement channels. Competitive moves concentrate on manufacturing localization partnerships and reagent supply security arrangements.
Among Japan-based precision instrument manufacturers, Sysmex Corporation and NIHON KOHDEN CORPORATION occupy positions within the hematology automation archetype, while Shimadzu Corporation exemplifies diversified analytical equipment production. Abbott and Roche represent Western multinational presence across immunoassay and molecular diagnostics segments. These named entities anchor competitive tiering without exhaustively mapping strategic positioning.
| Leading Market Players |
|---|
| Sysmex Corporation |
| NIHON KOHDEN CORPORATION |
| Shimadzu Corporation |
| Abbott |
| Roche |
| Siemens Healthineers |
| bioMérieux |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Captive reagent production anchored in Japanese and Western manufacturing clusters secures margin control for closed-system hematology vendors while locking hospital buyers into long-term consumable commitments. This integration pattern insulates premium-tier suppliers from spot-price volatility in enzyme and antibody feedstocks, though CDSCO localization mandates and currency fluctuation in Southeast Asian procurement channels introduce cost compression pressures at the mid-market tier.
Pricing Analysis
Subscription-based reagent-instrument bundling dominates Japanese tertiary hospital procurement, with multi-year contracts tying analyzer placement to minimum annual consumable volumes. Price differentiation separates PMDA-certified closed systems from CDSCO-registered open platforms, while after-sales service responsiveness commands premium positioning in India's tier-two city clinic segment. Cost compression in Southeast Asian point-of-care channels intensifies as physician-entrepreneurs negotiate direct distributor contracts, with diagnostic laboratories exhibiting highest price sensitivity and research institutions showing lowest.
Supply Chain Analysis
Freight cost escalation on temperature-controlled antibody and enzyme shipments from North American and European supplier bases amplifies landed cost uncertainty for Southeast Asian and Indian importers. Manufacturing concentrates in Japan, Germany, and the United States for precision optical components and specialized reagent formulations, while plastic consumables and electronic subassemblies source from Chinese and South Korean production hubs. Single-source vulnerability in rare earth-doped optical detection modules threatens instrument assembly timelines, with distribution running through Bangkok and Singapore regional hubs serving Mekong and archipelago markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific in vitro diagnostics market compounds steadily as chronic disease prevalence and precision oncology adoption sustain recurring reagent consumption across hospital installed bases. Automated workflow penetration in Japanese networks and point-of-care expansion in Indian tier-two cities anchor volume visibility.
For Market Incumbents: Deepen reagent supply security through backward integration into enzyme fermentation capacity or captive antibody production partnerships, defending against emerging modular molecular diagnostics suppliers that displace closed-system architectures. Prioritize CDSCO manufacturing localization investments to preempt regulatory compliance cost escalation in Indian procurement channels. For New Entrants and Emerging Players: The mid-tier price-point gap between Sysmex-Roche premium hematology bundles and regional assembler economy platforms creates white-space opportunity for cartridge-based immunoassay specialists. Target India's Lucknow-Indore-Coimbatore laboratory construction wave with fever panel menu differentiation, deploying distributor-direct sales models that bypass entrenched GPO contract structures. For Investors and Strategic Acquirers: Roll-up economics work for point-of-care immunoassay platform specialists because procurement authority decentralization to physician-entrepreneurs fragments vendor concentration and elevates after-sales responsiveness as a selection criterion. Acquire modular molecular diagnostics component suppliers with nucleic acid extraction-amplification separation architectures, watching PMDA-MFDS regulatory pathway alignment as inflection signal for biomarker-instrument co-development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Manufacturing Localization | Establishes quality certification infrastructure preempting India's phased medical device rule strengthening. |
| Reagent Supply Security Partnership | Captures enzyme and antibody feedstock stability insulating against currency-driven landed cost volatility. |
| Point-of-Care Cartridge Expansion | Penetrates India's tier-two city physician-entrepreneur procurement channels with fever panel menus. |
| Companion Diagnostic Co-Development | Leverages PMDA streamlined pathways accelerating gastric and lung cancer biomarker commercialization timelines. |
| Software Cybersecurity Certification | Aligns LIS middleware with Australia's TGA and Japan's PMDA software-as-medical-device guidance mandates. |
Methodological Framework
Bottom-up hospital and diagnostic laboratory modeling reconciled against top-down instrument shipment and reagent import tracking forms the analytical core. Primary interviews with hospital purchasing committee members, biomedical engineers, private laboratory network operators, and GPO contracts managers combine with secondary validation against PMDA approval databases, CDSCO medical device registration filings, hospital procurement records, and customs trade data for diagnostic instrument and reagent categories.
Input-output matrices segment volume and value across technology type, end-user setting, application area, and regulatory jurisdiction cluster throughout the forecast period. CAGRs derive from instrument installed base expansion rates, reagent consumption intensity per analyzer, and point-of-care unit deployment trajectories in underpenetrated geographies. Forecast inputs incorporate companion diagnostic regulatory pathway alignment, CDSCO rule implementation phasing, and EU Green Deal sustainability certification diffusion.
Caveats apply where PMDA-MFDS harmonization delays, CDSCO enforcement intensity variations, or reagent import tariff adjustments could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Microdialysis Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
E.Coli Latex Agglutination Test Kits Market
Diagnostics
LDL Test Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Home Diagnostics Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market