
 Pressure Bandages Market | 2026-2036
Pressure Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Bandages Market Intelligence
The integration of digital wound monitoring platforms as a value-added service is realigning the traditional product-centric sales model. Smith & Nephew leverages its extensive clinical network to promote advanced wound care solutions. 3M competes on material science innovation, offering a diverse portfolio of adhesive technologies. Mölnlycke Health Care AB differentiates through its focus on gentle-adhesion technologies for sensitive skin applications.
Pressure bandages are medical dressings designed to apply controlled compression to a specific body part. These products are engineered to deliver precise pressure levels, often measured in millimeters of mercury (mmHg), to manage swelling, support circulation, and prevent hematoma formation. Cohesive bandages represent a significant product segment due to their ease of use without requiring clips or tape. In applications, demand for venous ulcer management remains a primary driver, while post-surgical care is a consistently high-volume area.
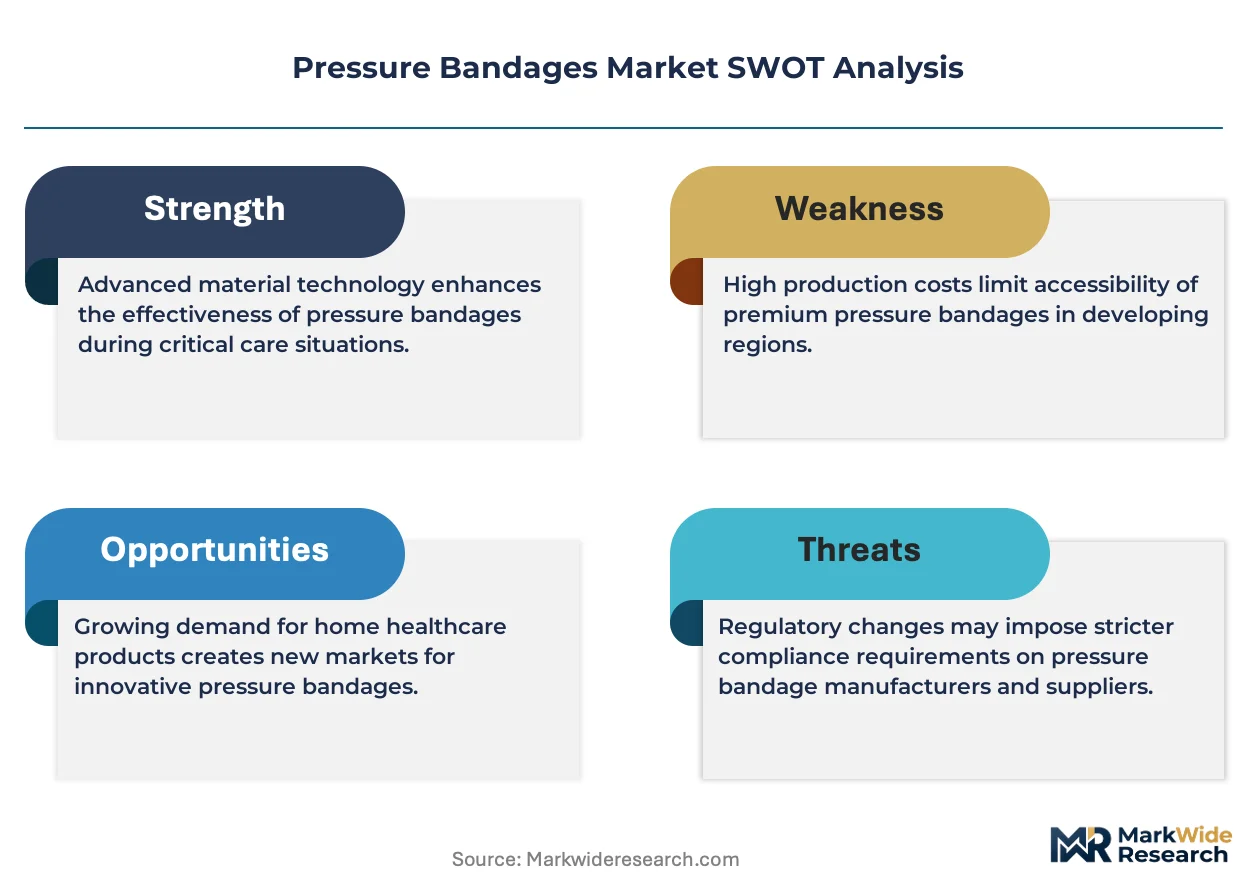
Medical device regulations, such as those from the US FDA and the EU's EMA under the MDR, mandate stringent testing for material biocompatibility and performance claims. In Japan, compliance with standards overseen by the PMDA is essential for market entry. Suppliers must now decide whether to invest in smart bandage technologies or focus on optimizing cost-effectiveness for institutional procurement.
Market Dynamics
The central force shaping the market is the decentralization of care from hospitals to home settings. This shift necessitates products that are not only effective but also simple for patients or non-specialist caregivers to apply, driving innovation in user-friendly materials.
Growth Catalysts
- Geriatric Population Expansion:The rising prevalence of chronic conditions like venous leg ulcers in aging populations, particularly in developed economies, provides a sustained demand floor for compression therapies.
- Advanced Material Science:Development of latex-free, self-adherent, and breathable fabrics improves patient comfort and reduces skin irritation, encouraging higher compliance rates for long-term treatment protocols.
- Stringent Clinical Guidelines:The EU's MDR, along with similar standards, creates a high barrier to entry that favors established manufacturers who can prove clinical efficacy, solidifying their market position.
Market Restraints
- Reimbursement Pressure:In many public healthcare systems, reimbursement policies for advanced and specialty bandages are restrictive, limiting adoption in favor of lower-cost traditional options.
- Alternative Treatment Modalities:The availability of negative pressure wound therapy (NPWT) and advanced skin substitutes for certain severe wounds can displace the need for long-term pressure bandaging.
- High Compliance Costs:Meeting the stringent biocompatibility and performance testing requirements mandated by regulators like the US FDA and Japan's PMDA adds significant cost and time to product development.
Strategic Opportunities
- Smart Bandage Integration:Incorporating micro-sensors to monitor pressure application, moisture levels, or wound healing progress presents a significant opportunity to add value and link to digital health platforms.
- Sports Medicine Niche:There is a growing opportunity in sports medicine for both injury prevention and post-injury recovery, requiring bandages with specific elasticity and durability characteristics.
- Emerging Market Healthcare:Expanding healthcare infrastructure and a rising middle class in regions like Southeast Asia and Latin America create new markets for essential medical supplies, including pressure bandages.
Industry Challenges
- Supply Chain Sterility:Maintaining the integrity and sterility of the supply chain for medical-grade textiles and adhesives across diverse global climates and logistics networks is a persistent operational challenge.
- MDR Transition Complexity:Manufacturers face significant operational hurdles in recertifying their entire product portfolios to comply with the EU's Medical Device Regulation (MDR), diverting resources from new R&D.
- Lack of Data Standardization:For emerging smart bandages, the absence of universal standards for data output and communication protocols hinders interoperability with different electronic health record (EHR) systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Bandages Market |
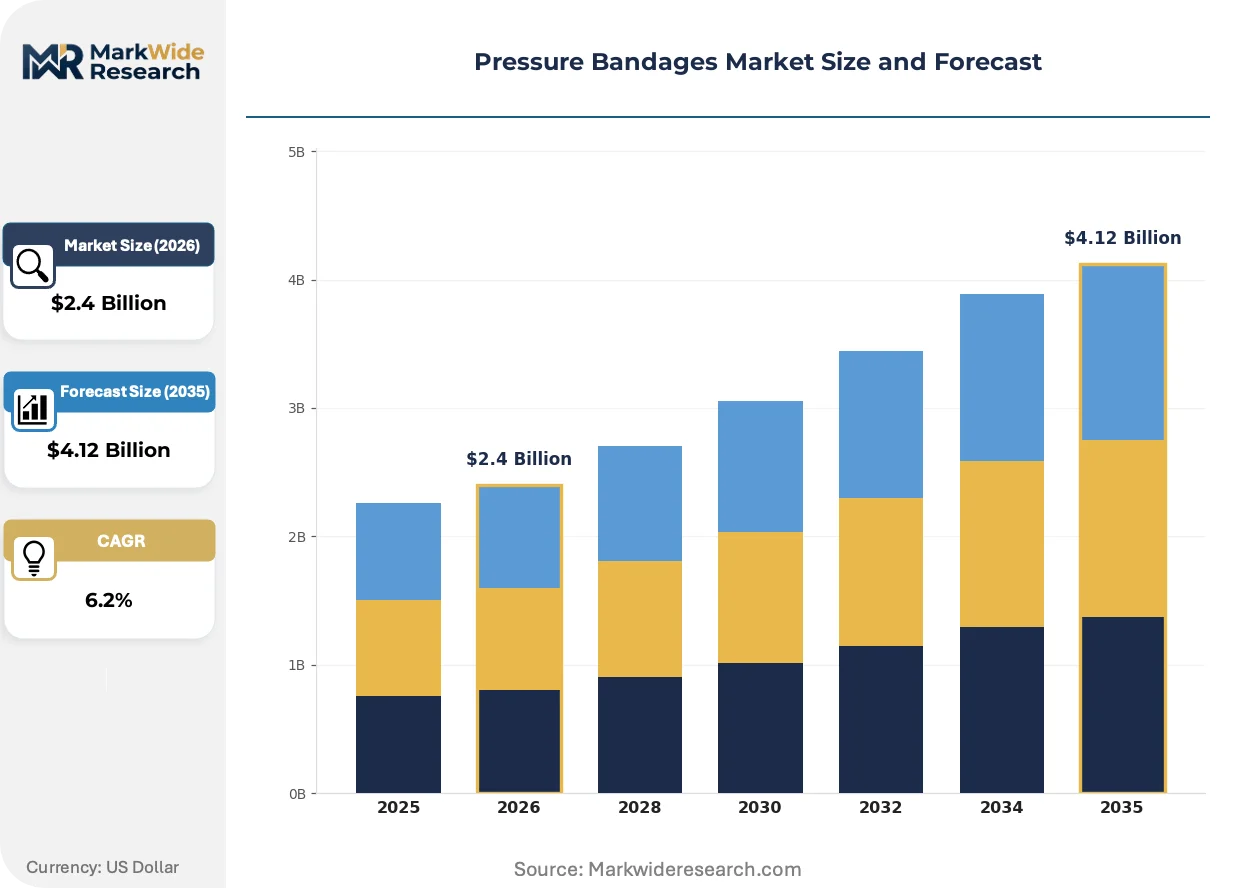
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Bandages, Cohesive Bandages, Adhesive Bandages, Foam Bandages, Others Application: Venous Ulcers, Hematoma Management, Post-Surgical Care, Lymphedema Treatment, Trauma Care End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Clinics, Emergency Medical Services, Home Care Providers Distribution Channel: Pharmacies, Medical Supply Stores, Online Retailers, Direct Sales, Healthcare Institutions |
| Companies Covered | Smith & Nephew, 3M, BSN Medical, Medtronic, ConvaTec, Cardinal Health, Johnson & Johnson, Paul Hartmann AG, Mölnlycke Health Care AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Bandages Market Strategic Shifts & Innovations
The evolution from a passive wound covering to an active therapeutic tool defines the current innovation cycle. Material science advancements and digital connectivity are transforming the product's role in the continuum of care, particularly for chronic wound management.
Advanced cohesive fabrics that offer consistent compression without adhering to skin or hair are a key innovation. Home care providers and outpatient clinics are rapidly adopting these materials due to their ease of application and removal, which reduces patient discomfort. This technology is integrating the bandage more seamlessly into a patient's life, improving therapy adherence and reducing the need for frequent clinical visits.
Regulatory scrutiny under frameworks like the European Union's Medical Device Regulation (MDR) is reshaping product development. This regulation mandates more extensive clinical evidence and rigorous post-market surveillance for devices previously considered low-risk. Consequently, manufacturers targeting the EU are forced to invest heavily in generating clinical data, which affects product pipelines and increases time-to-market for new innovations.
A preference for bundled procurement models is altering purchasing behavior in institutional settings. Hospitals and large clinic networks are moving away from buying bandages as standalone commodities, instead seeking integrated wound care solutions that include training, support, and data services. This shift is most visible in developed markets like the United States, where providers are evaluated on patient outcomes and total cost of care.
Pressure Bandages Market Segmentation
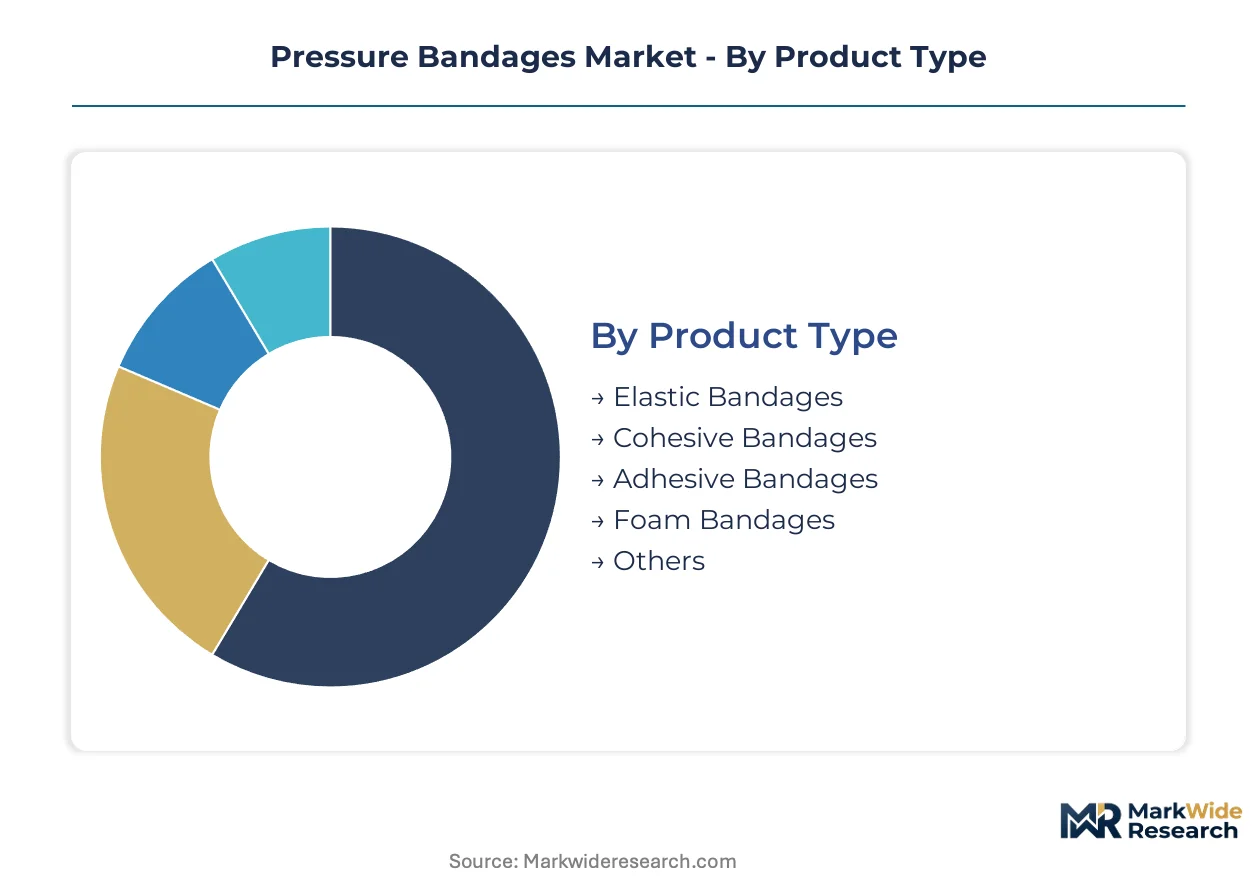
Segmentation analysis provides a granular understanding of the Pressure Bandages Market, dissecting it into distinct categories that reflect product characteristics, clinical applications, end-user profiles, and distribution mechanisms. This detailed breakdown illuminates specific areas of demand concentration and technological emphasis, guiding strategic development for manufacturers and suppliers.
Product Type:
Product type segmentation reflects the diverse material science and functional properties engineered into pressure bandages.
- Cohesive Bandages:Engineered with a self-adhering property, these bandages stick to themselves without requiring external fasteners or adhesives, simplifying application. Demand for cohesive bandages is particularly strong among home care providers in Germany, driven by their simplicity for non-specialist application.
- Elastic Bandages:Composed of stretchable woven fabrics, these bandages provide variable compression when applied, conforming to body contours for adaptable pressure control. Post-surgical care facilities in the United States frequently procure elastic bandages for edema management due to their adaptable pressure control.
- Adhesive Bandages:These bandages feature an adhesive backing for secure placement, often used for smaller wounds or securing primary dressings.
- Foam Bandages:Constructed from soft, conformable foam materials, these bandages offer cushioning and consistent pressure for sensitive areas.
- Others:This category encompasses specialized pressure bandage designs, including those with unique material compositions or advanced features for specific clinical needs.
Elastic Bandages lead on scale; Cohesive Bandages lead on momentum.
Application:
Application segments delineate the primary medical conditions and clinical scenarios where pressure bandages are clinically indicated.
- Venous Ulcers:Pressure bandages are critical for managing chronic venous insufficiency, providing sustained compression to reduce edema and promote healing. Demand for venous ulcer management is concentrated in developed economies with aging populations, such as Japan, due to the high prevalence of chronic conditions.
- Post-Surgical Care:These applications involve using bandages to reduce swelling, prevent hematoma formation, and support healing after various surgical procedures. Hospitals in the United Kingdom consistently utilize pressure bandages for post-operative recovery across multiple surgical specialties.
- Hematoma Management:Pressure bandages help prevent and reduce hematoma formation by applying localized compression to injured tissues.
- Lymphedema Treatment:Specialized compression bandages are integral for reducing limb swelling and maintaining fluid balance in patients with lymphedema.
- Trauma Care:Pressure bandages provide immediate compression for acute injuries, controlling bleeding and stabilizing affected areas in emergency settings.
Venous Ulcers represent a foundational application; Lymphedema Treatment demonstrates expanding clinical need.
End User:
End user segmentation differentiates primary purchasing entities based on their operational model and patient care delivery.
- Hospitals:These large institutional settings represent a high-volume procurement channel for a wide array of pressure bandages, used across surgical, emergency, and general medical departments. Hospitals in France maintain consistent demand for diverse bandage types to support a broad patient demographic.
- Home Care Providers:This segment includes agencies and individual caregivers delivering medical services in patients' residences, requiring user-friendly and effective solutions. The shift towards decentralized care in Canada drives significant demand from home care providers for simpler application bandages.
- Ambulatory Surgical Centers:These facilities focus on outpatient surgical procedures, requiring efficient and effective pressure bandages for post-operative recovery.
- Rehabilitation Clinics:Pressure bandages are essential in rehabilitation settings for managing edema and supporting injured tissues during physical therapy.
- Emergency Medical Services:EMS personnel utilize pressure bandages for immediate wound compression and stabilization at accident scenes and during patient transport.
Hospitals remain the largest volume consumer; Home Care Providers exhibit the steepest expansion trajectory.
Distribution Channel:
Distribution channel analysis outlines the varied pathways through which pressure bandages reach their diverse end users.
- Healthcare Institutions:This channel involves direct procurement by hospitals, clinics, and other medical facilities from manufacturers or large distributors, often through bundled contracts. Institutional procurement in the United States prioritizes cost-effectiveness and integrated wound care solutions.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer and business-to-business sales, offering convenience and a broad product selection for smaller clinics and home users. The convenience and broader reach of online retailers in Australia support increasing sales volumes.
- Pharmacies:Retail pharmacies serve as accessible points of sale for over-the-counter pressure bandages, catering to individual consumer needs.
- Medical Supply Stores:These specialized retail outlets offer a comprehensive range of medical devices and supplies, including various professional-grade pressure bandages.
- Direct Sales:Manufacturers directly engage with large institutional clients or specialized clinics, providing tailored solutions and technical support.
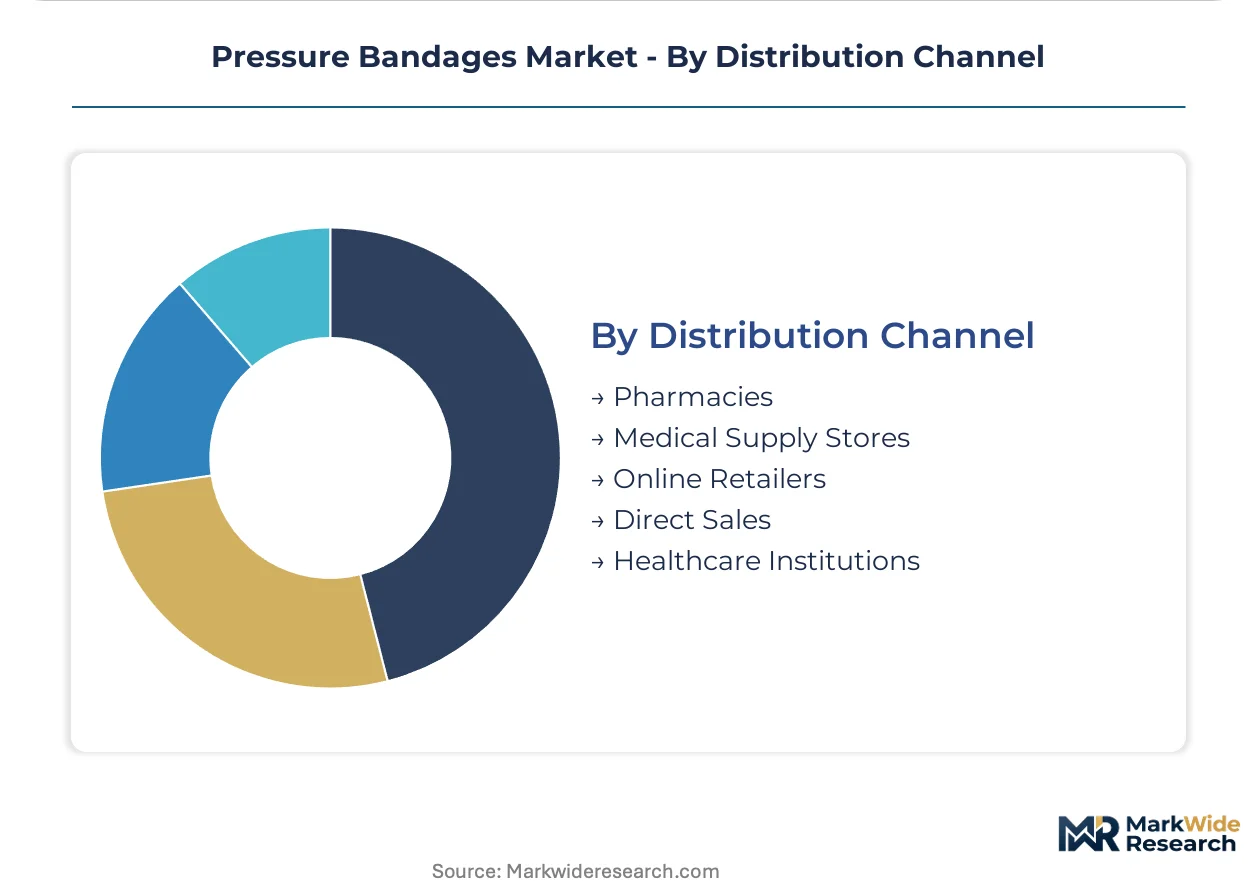
Healthcare Institutions represent the dominant supply route; Online Retailers are gaining market share most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The stringent clinical guidelines and regulatory frameworks, such as the EU's Medical Device Regulation (MDR), create significant compliance costs for pressure bandage manufacturers. This regulatory burden encourages some production to migrate to regions with less complex or costly approval processes. However, established markets with robust healthcare infrastructure continue to attract high-value product development and innovation.
Germany
Germany's substantial geriatric population drives sustained demand for compression therapies, particularly for venous leg ulcers. The country's strict adherence to EU MDR standards ensures high product quality and clinical evidence requirements. Medical technology clusters in regions like Bavaria actively develop advanced wound care solutions, integrating digital monitoring capabilities.
Japan
An aging demographic in Japan fuels the need for effective venous ulcer management, making pressure bandages a critical component of chronic care. Compliance with standards overseen by the Pharmaceuticals and Medical Devices Agency (PMDA) is essential for market entry. Leading medical device companies in Tokyo focus on developing innovative, user-friendly bandages for home care settings.
United States
The United States exhibits high demand for pressure bandages across post-surgical care and trauma management applications. US FDA regulations mandate stringent testing for material biocompatibility and performance claims. Healthcare innovation hubs in Boston and California lead the development of smart bandage technologies and integrated digital health platforms.
United Kingdom
Hospitals in the United Kingdom consistently utilize pressure bandages for post-operative recovery across multiple surgical specialties. The National Health Service (NHS) procurement policies often prioritize cost-effectiveness alongside clinical efficacy. MedTech innovation centers in London and Cambridge explore new material science for enhanced patient comfort and compliance.
Canada
Canada's shift towards decentralized care significantly drives demand from home care providers for simpler application bandages. Health Canada regulates medical devices, ensuring safety and performance standards for all market offerings. Medical device manufacturing in Ontario focuses on producing user-friendly and effective solutions for non-specialist caregivers.
Pressure Bandages Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the pressure bandages market. The market exhibits a tiered structure, with global medical device conglomerates competing with specialized wound care providers. These archetypes include innovation-driven leaders, cost-effective volume producers, and niche players focusing on specific material science. Companies often engage in strategic partnerships for distribution and continuously invest in material science innovation.
Smith & Nephew, a prominent global medical technology company, represents a leader leveraging extensive clinical networks to promote advanced wound care solutions. This British-based firm often emphasizes its broad portfolio and established clinical efficacy. 3M, an American multinational conglomerate, exemplifies innovation in material science, particularly adhesive technologies, offering a diverse portfolio across various applications. Its competitive strategy often involves continuous research and development into new material formulations. Mölnlycke Health Care AB, a Swedish medical solutions company, occupies a distinct position by focusing on gentle-adhesion technologies for sensitive skin applications. This specialization allows it to differentiate products for patients with fragile skin, improving comfort and compliance.
| Leading Market Players |
|---|
| Smith & Nephew |
| 3M |
| BSN Medical |
| Medtronic |
| ConvaTec |
| Cardinal Health |
| Johnson & Johnson |
| Paul Hartmann AG |
| Mölnlycke Health Care AB |
Cost & Logistics Intelligence
Medical-grade textile costs, a primary input for pressure bandages, influence pricing tiers from upstream material suppliers to downstream institutional buyers. This cost component directly impacts manufacturers' margins and the final price points for various product segments.
Pricing Analysis
Distributor margins significantly influence the final cost of pressure bandages, particularly for smaller clinics and home care providers. The dominant pricing model is per-unit transactional, often supplemented by long-term contract-based agreements for large institutional clients. Price differentiation stems from material quality certifications, such as biocompatibility standards, and the volume scale of procurement. Pricing pressure stems from stringent reimbursement policies in public healthcare systems, favoring cost-effective traditional options. Hospitals and public health systems are generally the most price-sensitive buyers, while private clinics seeking advanced solutions show less sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from healthcare institutions drive manufacturers to diversify their supplier base for critical components like medical adhesives and specialized fabrics. Geographic supply concentration for these materials largely rests in Germany, the United States, and specific Asian manufacturing hubs. The supply chain depends on specialized medical-grade polymers and sterile packaging components. Maintaining sterility throughout complex global logistics networks represents a persistent structural risk. Distribution runs through a hybrid model, combining direct procurement for large hospitals with indirect channels via medical distributors for smaller facilities and online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU's Medical Device Regulation (MDR) driving a focus on clinical evidence and product quality, thereby shaping demand. This regulatory milestone creates a high barrier to entry and favors established players.
For Market Incumbents: Lock in long-term procurement contracts with major hospital networks, leveraging existing clinical relationships to counter emerging cost-effective alternatives. Invest heavily in R&D for smart bandage technologies that integrate digital monitoring, addressing the threat of alternative wound care modalities. Pursue strategic acquisitions of specialized material science firms to deepen vertical integration and control critical input costs, reinforcing market share.
For New Entrants and Emerging Players: A price-point gap exists between premium, feature-rich bandages and basic, commodity options, creating an entry point for value-focused products. Target the rapidly expanding home care segment in regions like Canada and Southeast Asia, offering user-friendly, self-adherent designs. Focus on developing products that simplify application for non-specialist caregivers, enabling a go-to-market angle through digital health platforms and direct-to-consumer online channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs disproportionately burden smaller manufacturers, making them attractive acquisition targets. Focus on acquiring specialized firms with strong intellectual property in advanced material science or digital wound monitoring solutions. The long-term viability of the market is strong, driven by aging demographics and the decentralization of care. Watch for shifts in reimbursement policies for advanced wound care as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Smart Bandage R&D | Integrates digital health platforms, enhancing patient outcomes and data-driven care. |
| Expand Clinical Network Partnerships | Strengthens market access and promotes advanced wound care solutions through trusted channels. |
| Acquire Material Science Specialists | Secures proprietary technologies and optimizes production costs for next-generation products. |
| Obtain Global Regulatory Certifications | Ensures market access and compliance in key regions, mitigating operational risks. |
| Develop User-Friendly Home Care Solutions | Addresses the growing demand for simplified application products in decentralized care settings. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming the bedrock of this market analysis. Primary research involved in-depth discussions with wound care specialists, hospital procurement managers, home care agency directors, and medical device engineers. Secondary validation drew from regulatory filings, medical journal databases, healthcare expenditure reports, and relevant trade association publications, employing both bottom-up and top-down triangulation.
The forecast framework anchored the projection horizon to historical reference periods, establishing a consistent basis for trend analysis. The analysis modeled segmentation dimensions including product type, application, end-user, distribution channel, and geographic region across the analysis window. Compound annual growth rates were derived through a combination of regression analysis and expert-validated growth rate projections. Key industry-specific forecast inputs included geriatric population growth rates and chronic wound prevalence data.
Caveats apply where new regulatory mandates, unforeseen technological breakthroughs, or significant shifts in healthcare reimbursement policies could materially shift the outlook. Forecasts reflect assumptions regarding market evolution and stakeholder behavior. Deviation in these external factors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Wound Closure Devices Market
Wound Care
Wound Healing Supplement Market
Wound Care
Wound Drainage Devices Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
South Korea Wound Care Market
Wound Care
Gauze Bandage Rolls Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Animal Wound Care Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
US Wound Irrigation System Market
Wound Care
Wound Cleanser Products Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Wound Debridement (Wound Cleaning) Market