
 US Wound Irrigation System Market | 2026-2036
US Wound Irrigation System Market Size, Share, and Industry Trends Forecast 2026-2036
US Wound Irrigation System Market Intelligence
Domestic sterile solution production is decoupling from legacy pharmaceutical supply chains as regional manufacturers build dedicated US-based filling capacity. Medline Industries leverages its vertically integrated distribution network to control hospital supply contracts across the Midwest and Southeast. Stryker Corporation sustains technology leadership through proprietary pressurized delivery platforms that target orthopedic and trauma applications. Becton, Dickinson and Company anchors the saline solutions segment with large-scale manufacturing infrastructure that serves both acute and ambulatory channels.
A wound irrigation system delivers sterile fluids to debride contaminants, reduce bioburden, and maintain moist wound environments through gravity-fed, pressurized, or automated mechanisms operating at controlled flow rates and temperatures. Saline solutions dominate product type volume due to tissue compatibility and formulary standardization, while pressurized systems capture premium positioning through improved debris clearance efficiency in trauma and surgical applications. Automated delivery devices represent the fastest-expanding delivery mode as hospitals seek to standardize irrigation protocols and reduce variability in acute care settings.
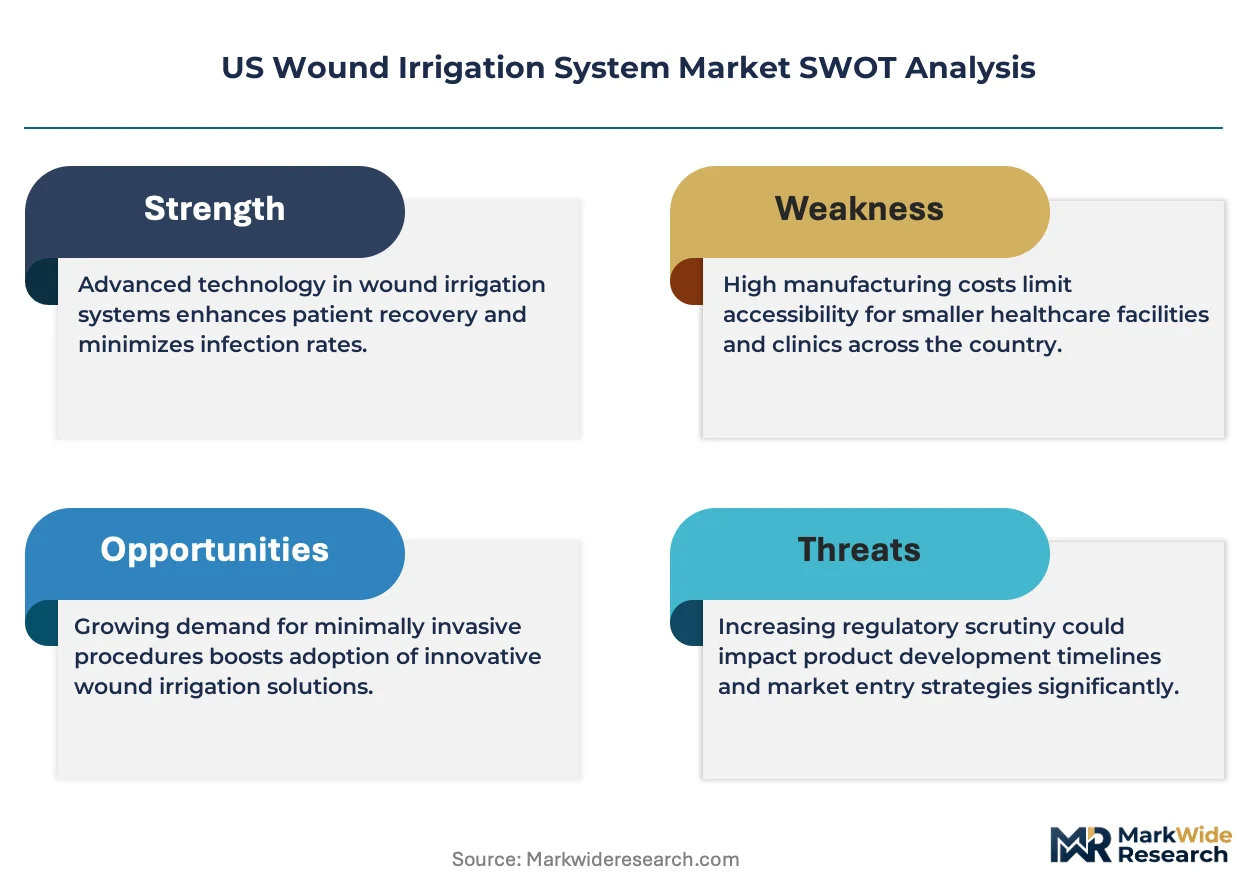
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern device commercialization, while CMS reimbursement policies for outpatient wound care procedures directly influence hospital procurement budgets and technology adoption timelines. The Joint Commission's infection control standards further shape product specifications by mandating sterile fluid handling and single-use components in clinical environments. Stakeholders must monitor evolving FDA guidance on antimicrobial irrigation solutions and CMS site-of-service payment differentials between hospital outpatient departments and ambulatory surgery centers.
Market Dynamics
Hospital outpatient departments are consolidating wound care protocols around pressurized irrigation devices as CMS reimbursement differentials between site-of-service locations compress procurement timelines and standardize device specifications.
Growth Catalysts
- CMS Site-of-Service Payment Differentials:Reimbursement advantages for hospital outpatient departments over ambulatory surgery centers are accelerating capital equipment replacement cycles in southeastern health systems.
- Aging Demographics in the Southeast:Florida, Georgia, and North Carolina are expanding ambulatory surgery center networks to serve Medicare-eligible populations with higher chronic wound incidence.
- Automated Delivery Mechanisms:Device manufacturers are embedding flow-rate sensors and temperature controls that reduce protocol variability in acute trauma settings.
Market Restraints
- Saline Solution Input Volatility:USP-grade sodium chloride supply concentrates with three domestic chemical processors, exposing contract manufacturers to price spikes during agricultural harvest disruptions.
- FDA 510(k) Clinical Validation Burden:Updated clearance requirements for class II pressurized devices are extending time-to-market by 14-18 months for novel irrigation platforms.
- Gravity-Fed Device Substitution:Low-cost bulb syringes and squeeze bottles retain preference in rural emergency departments with constrained capital budgets.
Strategic Opportunities
- Antimicrobial Irrigation Solutions:FDA draft guidance on povidone-iodine and hypochlorous acid formulations is creating first-mover advantage for sponsors completing safety studies.
- Veterans Health Administration Networks:Underpenetrated VA hospital systems in the Mountain West present concentrated procurement volume for standardized device contracts.
- Disposable Cartridge Integration:Convergence of single-use fluid reservoirs with Bluetooth-enabled pressure monitoring is enabling outcome tracking in value-based care arrangements.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Fluid dynamics specialists with ISO 13485 quality management experience command premium compensation in Minneapolis and Boston medical device clusters.
- Legacy EHR Integration Complexity:Automated irrigation systems require HL7 FHIR connectivity investments that strain IT budgets at mid-size community hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wound Irrigation System Market |
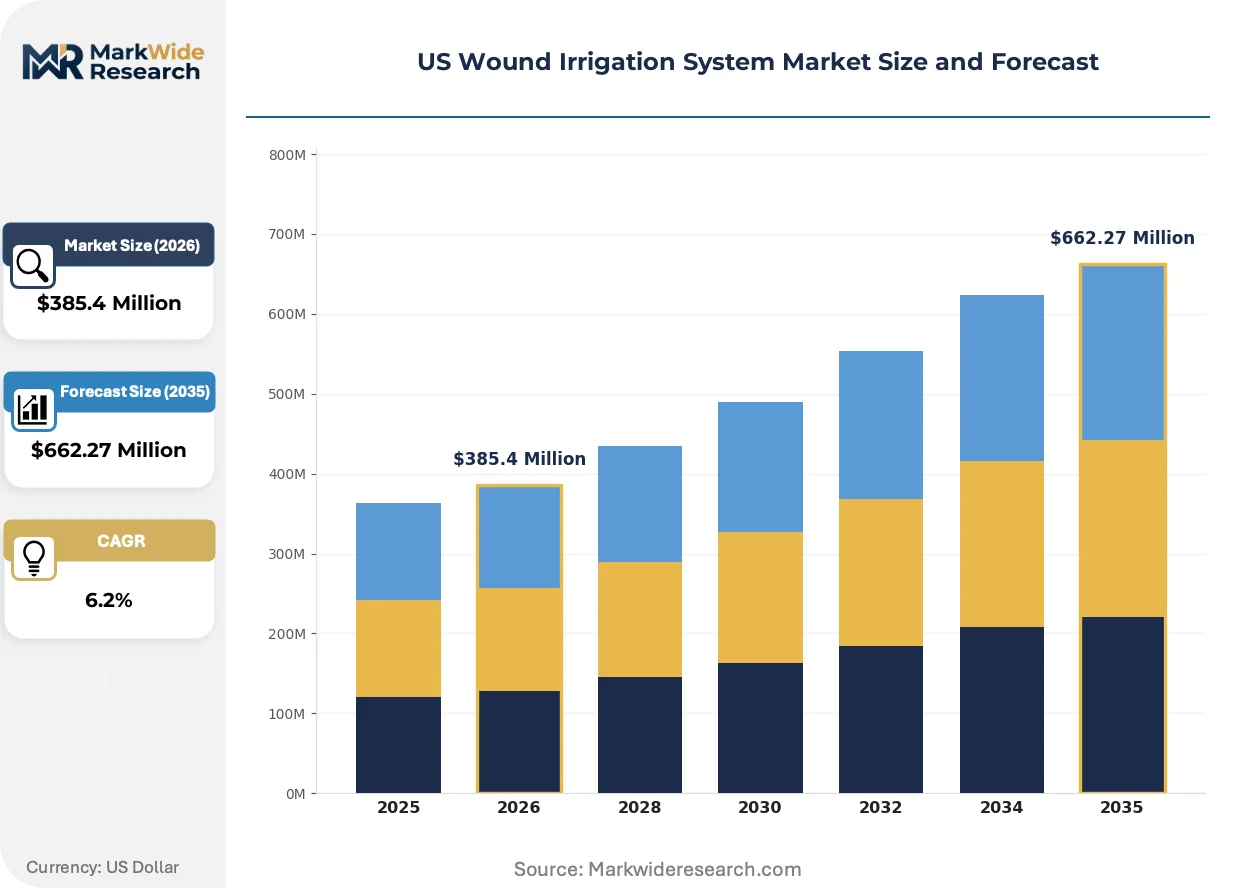
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Solutions, Antiseptic Solutions, Sterile Water, Saline Solutions Delivery Mode: Gravity Systems, Pressurized Systems, Hand-held Devices, Automated Systems End User: Hospitals, Clinics, Long-term Care Facilities, Homecare Application: Trauma Care, Surgical Wounds, Chronic Ulcers, Burn Treatment |
| Companies Covered | Medline Industries, LP, Westmed Products, Stryker Corporation, Centurion Medical Products, Bionix LLC, Zimmer Biomet Holdings, Inc., CooperSurgical, Inc., IrriMax Corporation, Becton, Dickinson and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wound Irrigation System Market Strategic Shifts & Innovations
Device architecture is pivoting from capital-intensive fixed installations toward modular, data-integrated platforms that align with hospital cost-per-procedure accounting and remote monitoring requirements.
Battery-powered portable pressurized units are decentralizing wound irrigation from centralized sterile processing departments to bedside and field applications. Emergency medical services in Texas and Arizona are deploying these devices for pre-hospital trauma stabilization. The shift is compressing rental revenue models for traditional capital equipment while expanding disposable cartridge attach rates.
FDA's updated 510(k) clearance pathway for antimicrobial irrigation solutions is accelerating clinical validation investments among solution manufacturers. The industrial consequence is a bifurcation between legacy saline-only suppliers and hybrid device-solution platforms seeking combination product designation. Orthopedic and trauma surgical centers are responding by consolidating vendor relationships around vertically integrated suppliers.
Hospital purchasing committees are unbundling device procurement from solution supply contracts, reversing decade-old bundled arrangements. Independent ambulatory surgery centers in the Carolinas are sourcing saline solutions through group purchasing organizations while negotiating direct device leases with manufacturers. The disintermediation is most visible in metropolitan Atlanta, where three competing health systems have launched separate irrigation standardization initiatives.
US Wound Irrigation System Market Segmentation
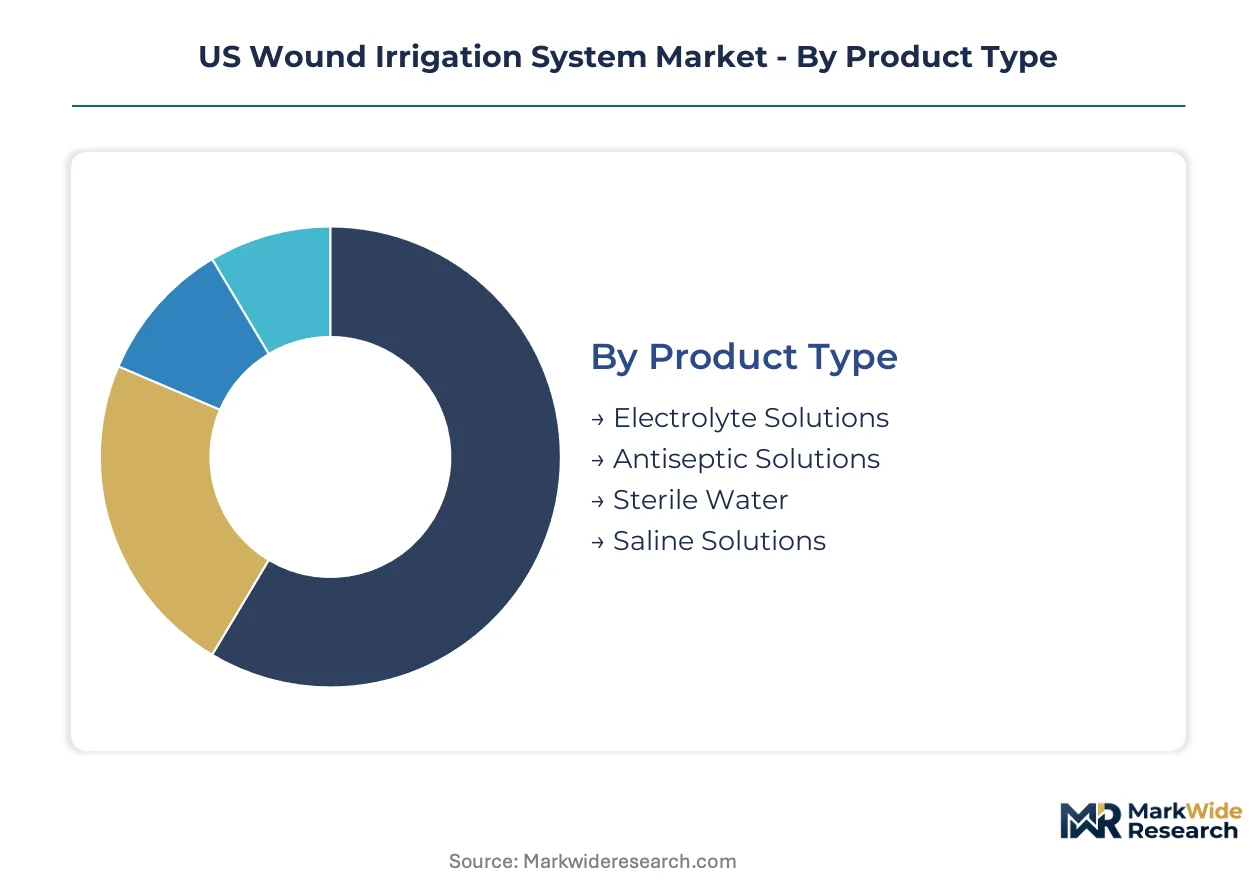
Segmentation in the US wound irrigation system market reveals distinct procurement patterns across fluid chemistry, delivery mechanics, and care settings. Hospital purchasing committees evaluate segments through divergent lenses: capital equipment committees assess pressurized platforms, while pharmacy and therapeutics committees govern solution formularies.
Product Type:
Capital intensity varies sharply across fluid formulations, with antiseptic solutions requiring the most substantial upfront investment in FDA combination product validation and specialized manufacturing infrastructure.
- Saline Solutions:Isotonic sodium chloride formulations dominate hospital formularies due to established tissue compatibility and streamlined procurement through group purchasing organizations. Demand concentrates in southeastern ambulatory surgery centers where Medicare-eligible populations drive high procedure volumes for orthopedic and trauma applications.
- Antiseptic Solutions:Povidone-iodine and hypochlorous acid formulations demand dedicated filling lines and extensive clinical safety documentation under FDA draft guidance for antimicrobial irrigation. Academic medical centers in Boston and Minneapolis are piloting these solutions in trauma protocols, though formulary adoption remains constrained by reimbursement uncertainty.
- Electrolyte Solutions:Buffered potassium and magnesium formulations serve specialized burn centers requiring precise ionic balance.
- Sterile Water:Low-cost option retains presence in rural emergency departments with constrained pharmacy budgets.
Saline solutions absorb the bulk of installed capacity; antiseptic solutions are expanding most quickly as FDA guidance clarifies.
Delivery Mode:
Cost tier stratification separates disposable gravity systems from capital-intensive automated platforms, with pressurized devices occupying the contested middle ground where rental versus purchase decisions hinge on procedure volume thresholds.
- Pressurized Systems:Proprietary pump mechanisms deliver controlled flow rates between 8-15 PSI for effective debris clearance in contaminated wounds. Southeastern hospital outpatient departments are consolidating procurement around these devices as CMS reimbursement differentials compress capital replacement cycles.
- Automated Systems:Embedded flow-rate sensors and temperature controls standardize irrigation protocols across nursing shifts. Texas and Arizona emergency medical services are deploying portable battery-powered variants for pre-hospital trauma stabilization, expanding disposable cartridge attach rates.
- Gravity Systems:Bulb syringes and squeeze bottles persist in rural facilities with limited capital equipment budgets.
- Hand-held Devices:Manual pressurized canisters serve field applications where electrical power is unavailable.
Pressurized systems command the largest installed base; automated systems are climbing the fastest as value-based care arrangements demand outcome tracking.
End User:
Customer type determines contract structure, with hospitals negotiating enterprise-wide device leases while ambulatory sites favor flexible rental terms tied to procedure volume.
- Hospitals:Integrated delivery networks in the Southeast leverage scale to unbundle device procurement from solution supply contracts. The Joint Commission's infection control standards mandate sterile fluid handling and single-use components, shaping capital allocation toward automated platforms with disposable cartridges.
- Clinics:Independent ambulatory surgery centers in metropolitan Atlanta source saline through group purchasing organizations while negotiating direct device leases, reversing decade-old bundled arrangements.
- Long-term Care Facilities:Skilled nursing facilities in Florida face staffing constraints that favor simplified gravity-fed protocols.
- Homecare:Medicare home health agencies in Georgia are piloting portable pressurized units for chronic ulcer management.
Hospitals retain the dominant procurement volume; clinics are gaining share fastest as site-of-service migration accelerates.
Application:
Volume concentration in surgical wounds contrasts with margin opportunity in trauma care, where premium device positioning aligns with acute reimbursement codes.
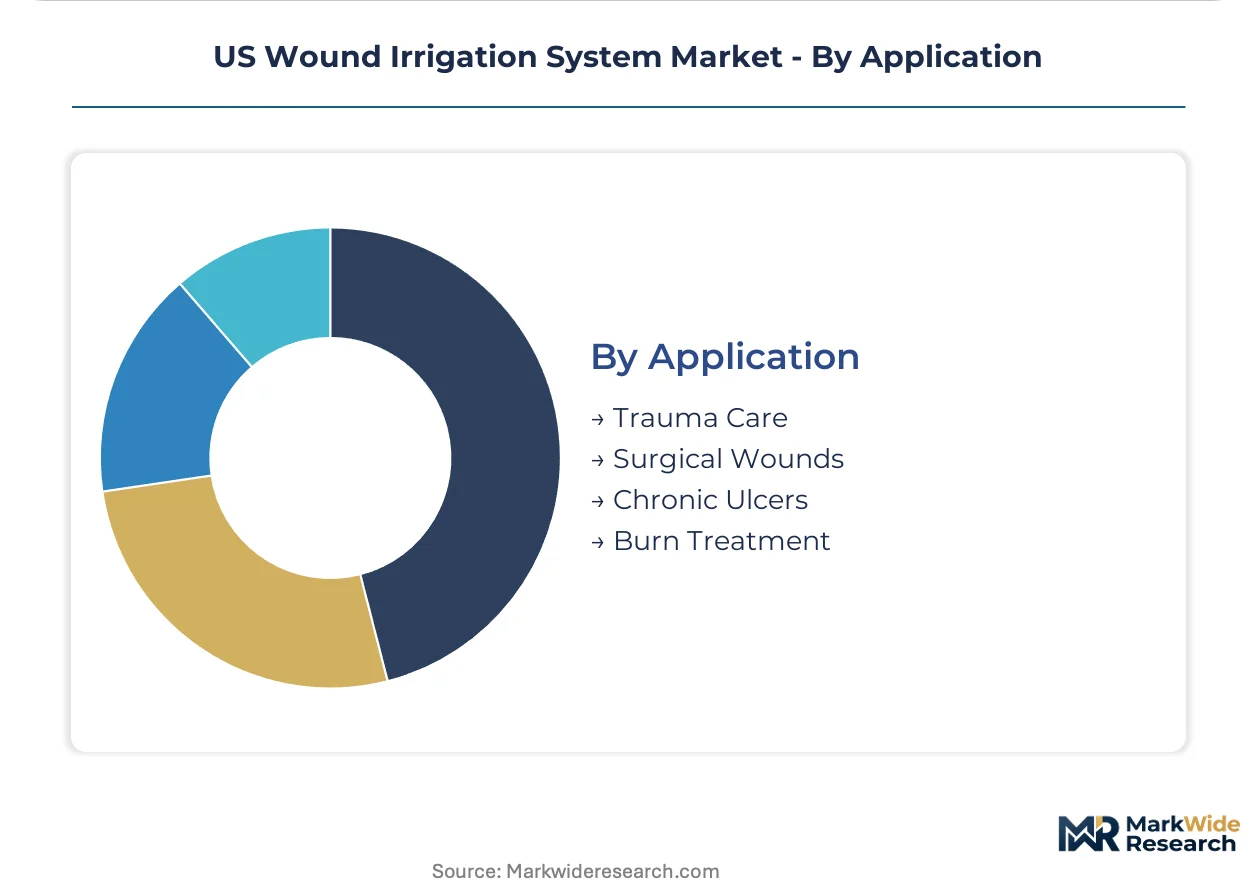
- Surgical Wounds:Orthopedic and general surgery protocols standardize on pressurized irrigation for joint replacement and abdominal procedures. Demand clusters in southeastern ambulatory surgery centers expanding networks to serve aging Medicare populations.
- Trauma Care:Emergency departments require rapid debris clearance under time pressure, favoring automated systems with preset flow parameters. Level I trauma centers in Texas are embedding Bluetooth-enabled pressure monitoring for quality documentation.
- Chronic Ulcers:Diabetic foot and venous stasis protocols favor gravity-fed systems in long-term care settings.
- Burn Treatment:Specialized centers demand precise temperature-controlled delivery for thermal injury management.
Surgical wounds account for the largest procedure volume; trauma care is expanding most rapidly as pre-hospital deployment extends device utility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USP-grade sodium chloride supply anchors the southeastern United States, where agricultural processing corridors in Louisiana and Texas feed regional pharmaceutical-grade chemical production.
Southeast
Florida, Georgia, and North Carolina are expanding ambulatory surgery center networks to serve Medicare-eligible populations with elevated chronic wound incidence. The Joint Commission's infection control standards mandate sterile fluid handling protocols that accelerate automated platform adoption. Metropolitan Atlanta hosts three competing health system irrigation standardization initiatives that are unbundling device procurement from solution contracts.
Southwest
Texas emergency medical services deploy battery-powered portable pressurized units for pre-hospital trauma stabilization, extending device utility beyond hospital walls. CMS site-of-service reimbursement differentials favor hospital outpatient departments over freestanding ambulatory centers. Dallas-Fort Worth medical device clusters concentrate fluid dynamics engineering talent for next-generation delivery platform development.
Midwest
Illinois and Michigan integrated delivery networks leverage scale to negotiate enterprise-wide device leases with vertically integrated suppliers. FDA 510(k) clearance requirements for class II pressurized devices drive clinical validation study investments among regional manufacturers. Minneapolis anchors biomedical engineering talent pools with ISO 13485 quality management specialization.
Mountain West
Veterans Health Administration networks in Colorado and Arizona present concentrated procurement volume for standardized device contracts. Rural emergency departments in New Mexico retain gravity-fed bulb syringe preference due to constrained capital equipment budgets. Salt Lake City medical device clusters focus on disposable cartridge integration with Bluetooth-enabled pressure monitoring.
Northeast
Massachusetts academic medical centers pilot povidone-iodine and hypochlorous acid formulations in trauma protocols under evolving FDA draft guidance. Boston biomedical engineering clusters command premium compensation for fluid dynamics specialists. New York Metro hospital purchasing committees evaluate automated systems with HL7 FHIR connectivity for EHR integration compliance.
US Wound Irrigation System Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue antimicrobial solution-device combination platforms. The vendor base stratifies across three tiers: diversified medical device conglomerates with orthopedic specialization, vertically integrated distribution networks controlling hospital supply contracts, and regional solution manufacturers building dedicated US-based filling capacity. Dominant competitive moves include backward integration into sterile solution production and strategic partnerships for disposable cartridge technology licensing.
Within the diversified device tier, Stryker Corporation and Zimmer Biomet Holdings exemplify capital-intensive platform developers targeting surgical and trauma applications. Medline Industries anchors the vertically integrated distribution archetype, leveraging captive supply networks to control hospital contracts across the Midwest and Southeast. Becton, Dickinson and Company represents the large-scale solution manufacturing archetype with infrastructure serving acute and ambulatory channels simultaneously.
| Leading Market Players |
|---|
| Medline Industries, LP |
| Westmed Products |
| Stryker Corporation |
| Centurion Medical Products |
| Bionix LLC |
| Zimmer Biomet Holdings, Inc. |
| CooperSurgical, Inc. |
| IrriMax Corporation |
| Becton, Dickinson and Company |
| Others |
Cost & Logistics Intelligence
USP-grade sodium chloride spot pricing volatility cascades through contract manufacturing tiers into three distinct procurement bands: automated pressurized platforms with disposable cartridges, mid-range rental devices, and gravity-fed disposables.
Pricing Analysis
Warranty and preventive maintenance bundling separates capital equipment lessors from bare-metal device vendors in hospital procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification status, and geographic service coverage density. Pricing pressure stems from group purchasing organization consolidation in the Southeast, where contract manufacturers face compressed margins on saline solution supply. Rural emergency departments exhibit highest price sensitivity, favoring unbundled gravity-fed systems; Level I trauma centers show lowest sensitivity, prioritizing outcome documentation capabilities.
Supply Chain Analysis
Single-source vulnerability sits with Louisiana and Texas agricultural processing corridors, where three domestic chemical processors concentrate USP-grade sodium chloride production. The supply chain draws from Gulf Coast salt dome extraction, Midwest pharmaceutical-grade chemical synthesis, and Southeast regional filling capacity. Tariff exposure on imported raw materials compounds hurricane-season disruption risk at Port of New Orleans logistics nodes. Distribution runs through vertically integrated hospital supply networks, group purchasing organizations, and direct manufacturer leases to ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's updated 510(k) clearance requirements for class II pressurized devices erect a cost-of-compliance barrier that entrenches incumbents with clinical validation infrastructure while filtering undercapitalized entrants.
For Market Incumbents: Deepen backward integration into sterile solution production to capture margin compression from chemical processor concentration. Fortify southeastern hospital system partnerships before CMS site-of-service reimbursement differentials fully compress; automated platform vendors with disposable cartridge attach rates face substitution threat from portable battery-powered entrants in Texas and Arizona emergency medical services.
For New Entrants and Emerging Players: Enter via antimicrobial irrigation solution-device combination platforms under FDA draft guidance for povidone-iodine and hypochlorous acid formulations. Target Veterans Health Administration networks in the Mountain West, where standardized device contracts remain underpenetrated and procurement committees prioritize single-vendor simplicity over multi-source complexity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional solution manufacturers with dedicated US-based filling capacity and ISO 13485 quality management infrastructure in Minneapolis and Boston clusters. Long-term viability hinges on convergence with value-based care arrangements requiring Bluetooth-enabled outcome tracking; monitor FDA final guidance on antimicrobial irrigation solutions as inflection indicator for combination product valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for pressurized devices with embedded flow-rate sensors in southeastern hospital systems. |
| Hospital System Partnership | Locks in enterprise-wide device leases with integrated delivery networks consolidating procurement around automated platforms. |
| Backward Integration | Captures margin from USP-grade sodium chloride supply concentration by building captive regional filling capacity. |
| Software Companion Development | Enables HL7 FHIR connectivity for EHR integration compliance at mid-size community hospitals with constrained IT budgets. |
| Reimbursement Strategy | Aligns device positioning with CMS site-of-service payment differentials favoring hospital outpatient departments. |
Research Approach
Document review covered FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, and hospital procurement records, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and fluid dynamics specialists. Secondary validation drew from SEC filings of publicly traded device manufacturers, The Joint Commission infection control standards, and regional health system capital expenditure disclosures. Bottom-up triangulation across installed base estimates and top-down validation against procedure volume projections ensured cross-verification.
Segment-level outputs across product type, delivery mode, end user, and application dimensions were generated through the projection horizon. CAGRs were derived from logistic adoption curves fitted to pressurized device penetration rates and automated platform replacement cycles. Forecast inputs incorporated CMS site-of-service policy trajectories, FDA guidance timelines for antimicrobial solutions, and regional ambulatory surgery center expansion plans.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA guidance acceleration or delay scenarios. Deviation in USP-grade sodium chloride supply disruption frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Surgical Wound Care Market
Wound Care
Advanced Wound Management Market
Wound Care
Wound Care Biologics Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Maggot Debridement Market
Wound Care
Belgium and Netherlands Advanced Wound Care Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Wound Management Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Liquid Bandages Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
US Wound Care Management Devices Market