
 North America Over the Counter Drugs Market | 2026-2036
North America Over the Counter Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
North America Over the Counter Drugs Market Analytics
Digital therapeutics integration is tilting how OTC products reach consumers, with AI-powered symptom checkers and telehealth referrals now routing patients toward non-prescription alternatives. Kenvue leverages its heritage brand portfolio to sustain shelf dominance across mass retail channels. Haleon anchors its position through pharmacy-led distribution networks that prioritize pharmacist recommendation programs. Bayer competes on R&D intensity, particularly in topical analgesic formulations that blend pharmaceutical rigor with consumer accessibility.
Over the counter drugs comprise non-prescription pharmaceutical formulations regulated for consumer self-selection, typically containing active ingredients at dosages below prescription thresholds and manufactured through validated processes ensuring batch-to-batch consistency. These products serve the primary commercial purpose of enabling consumers to treat self-diagnosed conditions without clinician oversight, reducing healthcare system burden while capturing margin from routine ailment management. Pain relievers occupy the deepest margin pools due to chronic condition prevalence and repeat purchase frequency, while antihistamines represent the fastest-expanding category as seasonal allergy incidence intensifies across temperate climate zones. Online stores are displacing traditional pharmacy traffic for replenishment purchases, though supermarkets retain strength in impulse-driven categories like antacids.
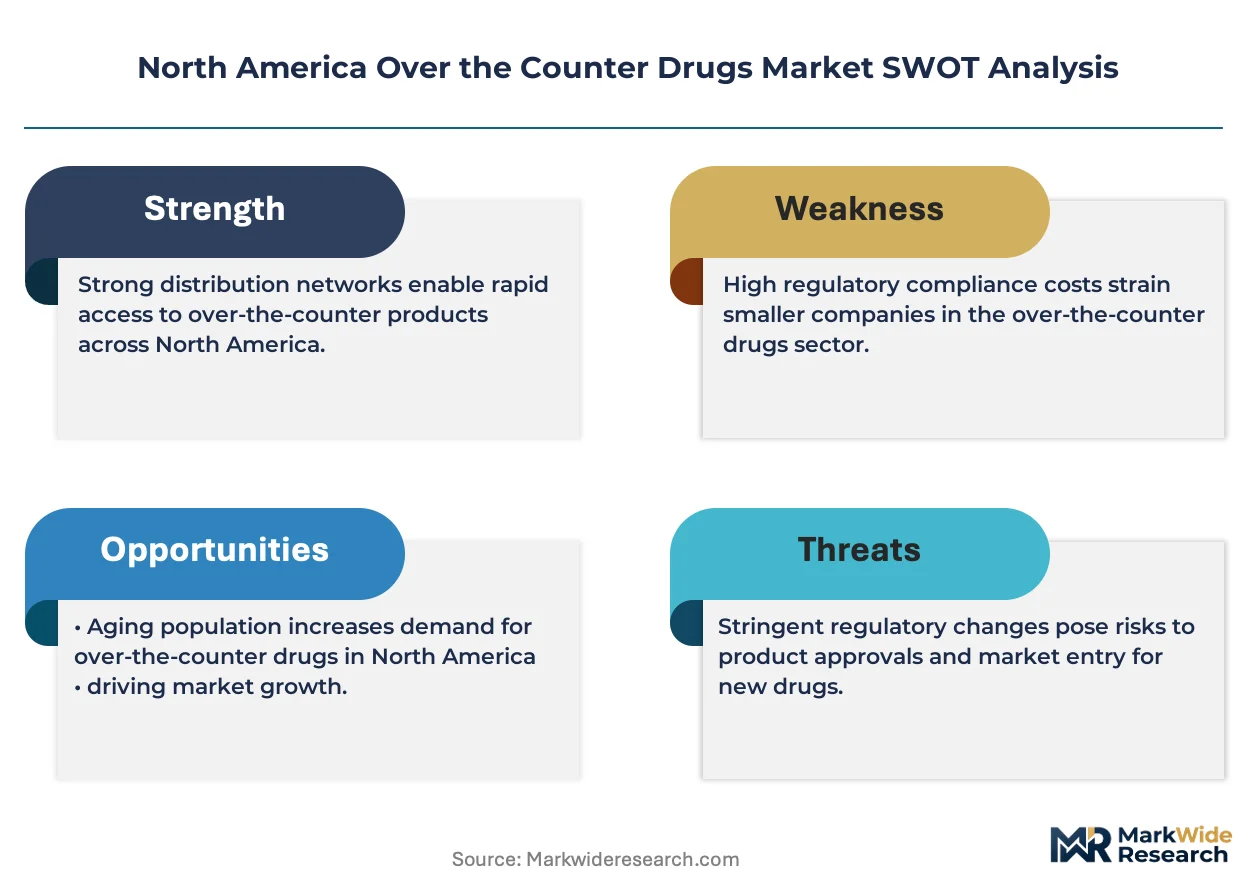
The FDA oversees OTC monograph modernization, while Health Canada applies the Natural Health Product framework to borderline formulations, and state-level pharmacy boards govern point-of-sale counseling requirements that shape retail staffing models. These regulatory layers collectively elevate compliance costs for new entrants while rewarding incumbents with established quality management systems and documented adverse event surveillance. Stakeholders must monitor how FDA finalizes its proposed administrative order pathway for monograph reform, as this will determine whether legacy ingredients face market withdrawal or accelerated competitive entry.
Market Dynamics
The FDA's OTC monograph reform is compressing approval timelines for legacy ingredients while forcing reformulation investments across established portfolios. This regulatory recalibration is redistributing competitive advantage toward manufacturers with documented adverse event surveillance and quality management infrastructure already in place.
Growth Catalysts
- Self-Medication Among Aging Adults:Adults over 65 in the United States and Canada are managing chronic conditions through non-prescription alternatives, expanding the addressable population for pain relievers and digestive health products.
- Telehealth Integration:Digital health platforms in the United States now route symptom-checked patients toward OTC alternatives, creating new prescription-to-OTC conversion pathways.
- Monograph Modernization:Health Canada's Natural Health Product framework and the FDA's administrative order pathway are streamlining ingredient approvals, reducing time-to-market for reformulated products.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing for ibuprofen and acetaminophen concentrates in Asian manufacturing clusters, exposing formulators to freight cost volatility and customs delays.
- Retailer Consolidation:Pharmacy chain mergers across the United States and Canada are compressing shelf access for mid-tier brands, elevating slotting fee requirements and promotional spend thresholds.
- Substitution Threat:Generic private-label formulations at mass retailers are capturing price-sensitive volume in analgesics and antacids, eroding branded margin pools.
Strategic Opportunities
- Underpenetrated Rural Markets:Independent pharmacies and dollar stores in the United States Mountain West and Canadian Prairie provinces remain underserved by specialty digestive and respiratory OTC products.
- AI-Powered Personalization:Machine learning recommendation engines deployed through pharmacy apps are creating white space for condition-specific product bundles tailored to individual purchase histories.
- Regulatory Tailwind:The FDA's proposed switch mechanisms for prescription-to-OTC transitions are opening pathways for intranasal corticosteroids and lower-dose proton pump inhibitors.
Industry Challenges
- Talent Scarcity in Regulatory Affairs:The convergence of FDA monograph reform and Health Canada's evolving borderline classification rules is outstripping the supply of professionals fluent in both jurisdictions.
- Legacy System Integration:ERP upgrades required for lot-level traceability under DSCSA in the United States are forcing capital allocation trade-offs against R&D spending.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Over the Counter Drugs Market |
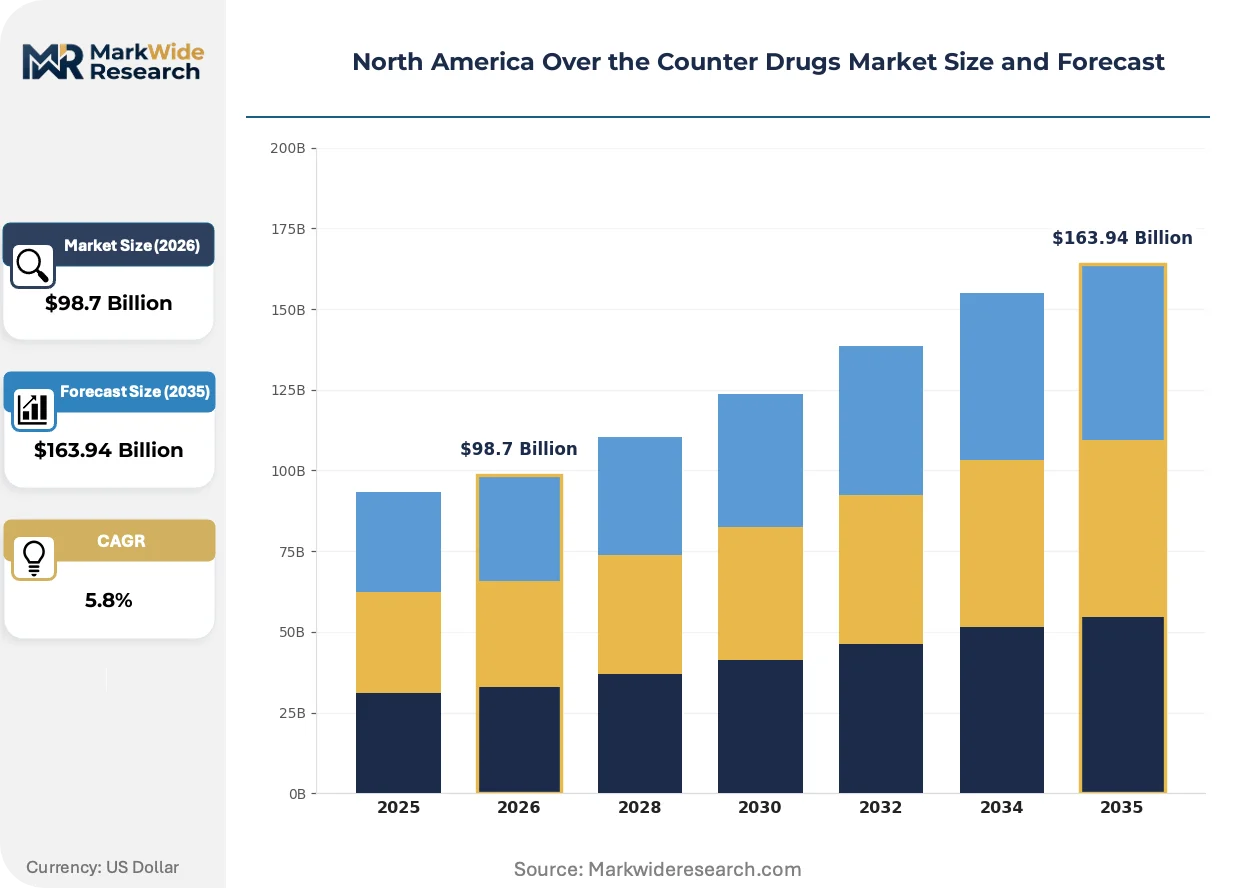
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cough Syrups, Antihistamines, Antacids End User: Adults, Children, Seniors, Pregnant Women Distribution Channel: Pharmacies, Supermarkets, Online Stores, Hospitals Packaging Type: Bottles, Blister Packs, Jar Containers, Sachets |
| Companies Covered | Kenvue, Haleon, Bayer, Procter & Gamble, Reckitt, Sanofi, Perrigo, Pfizer, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Over the Counter Drugs Market Evolving Landscape
Digital infrastructure is rewiring how consumers discover, validate, and purchase non-prescription therapies. Three interconnected developments are compressing traditional pharmacy traffic while elevating the importance of data-driven personalization and regulatory agility.
Connected diagnostic devices paired with smartphone applications are digitizing the symptom-to-treatment pathway. Consumers in the United States are adopting Bluetooth-enabled thermometers and blood pressure monitors that feed data into pharmacy-owned apps, which then surface relevant OTC recommendations. This convergence is digitizing the point of care, shifting purchase initiation from in-store aisles to pre-visit digital touchpoints.
The FDA's proposed administrative order framework for OTC monograph reform is forcing manufacturers to submit new safety and efficacy data for ingredients grandfathered under older standards. This regulatory tightening is accelerating withdrawal decisions for legacy formulations containing phenylephrine and other challenged actives. Analgesic and cough-cold segments are responding with accelerated R&D pipelines targeting replacement ingredients with clearer efficacy profiles.
Subscription replenishment models through e-commerce platforms are capturing routine purchase occasions previously dominated by supermarket and drugstore channels. Consumers managing chronic conditions like seasonal allergies or arthritis in the United States are opting into auto-delivery programs that bypass traditional retail entirely. This behavioral shift is most visible in suburban markets where pharmacy deserts and delivery density create favorable economics for direct-to-patient distribution.
North America Over the Counter Drugs Market Segmentation
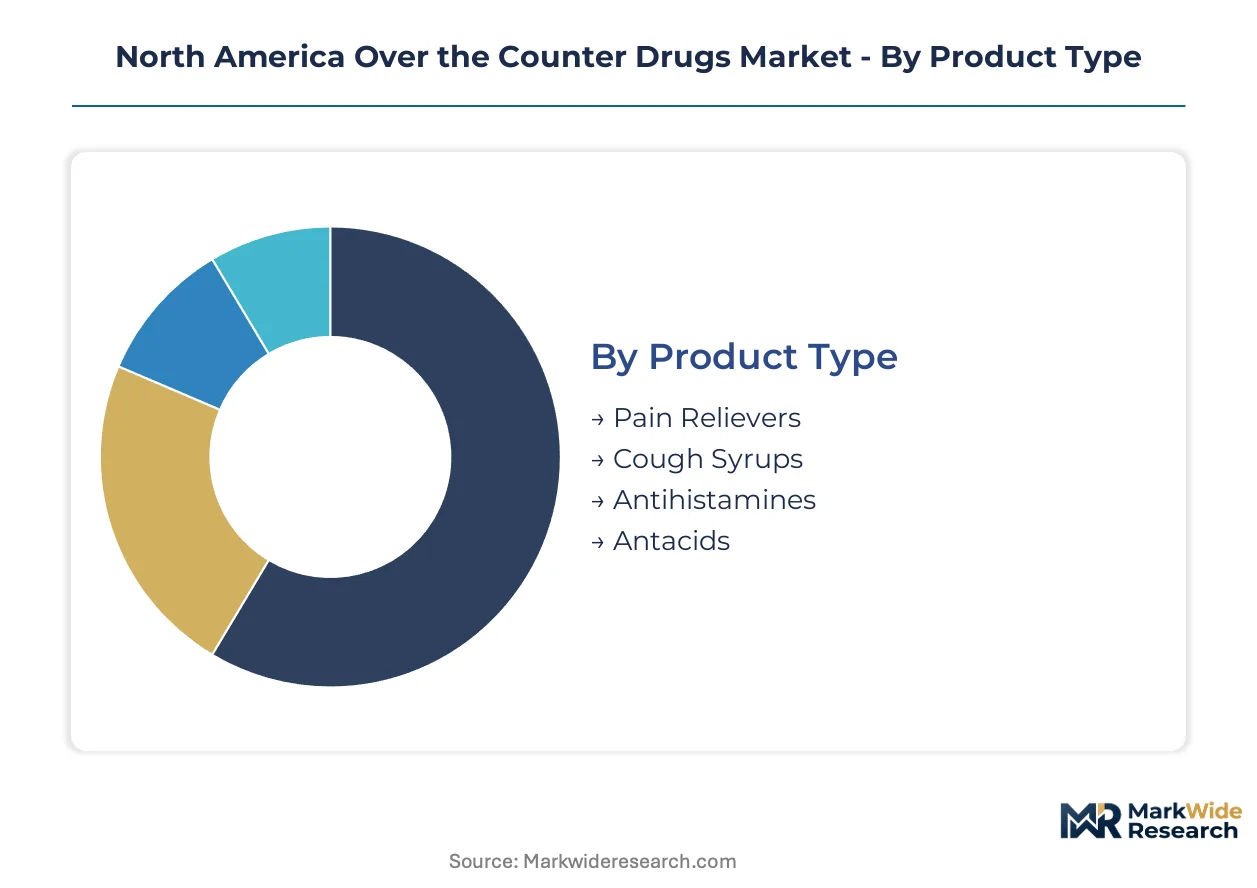
Segmentation in the North America Over the Counter Drugs Market reveals how formulation specifications, patient demographics, and channel economics fragment purchasing behavior. Understanding these divisions exposes where margin pools concentrate and where regulatory complexity creates defensive moats for prepared manufacturers.
Product Type:
The use-case spectrum spans acute symptom relief to chronic condition management, with each category carrying distinct regulatory pathways and repeat purchase cadences.
- Pain Relievers:Formulations containing ibuprofen, acetaminophen, and naproxen sodium dominate household medicine cabinets across the United States and Canada. Chronic arthritis and tension-type headache prevalence in adults over 50 drives replenishment frequency, while pharmacy chains capture the majority of volume through front-end placement strategies.
- Antihistamines:Second-generation non-sedating formulations with loratadine and cetirizine are climbing the fastest as pollen season extension intensifies seasonal allergy burden in temperate climate zones. Direct-to-consumer advertising and pharmacist recommendation programs channel demand toward branded extended-release variants.
- Cough Syrups:Expectorant and suppressant formulations face reformulation pressure as FDA scrutiny of phenylephrine efficacy challenges legacy active ingredients.
- Antacids:Calcium carbonate and H2 blocker tablets serve impulse-driven purchase occasions in supermarket checkout lanes and convenience stores.
Established volume favors pain relievers; emerging adoption favors antihistamines.
End User:
Patient physiology and regulatory safeguards create tiered formulation requirements that reshape manufacturing complexity and labeling obligations.
- Adults:Standard-strength formulations with adult dosing instructions constitute the baseline commercial reference for OTC development, with FDA monograph compliance centered on this population's metabolic capacity.
- Seniors:Polypharmacy risk and renal clearance reduction in patients over 65 necessitate lower-dose packaging and enhanced drug interaction warnings, creating specialized SKU requirements for pharmacy chains serving retirement communities in Florida and Arizona.
- Children:Liquid suspensions and chewable tablets with weight-based dosing require precise measurement devices and pediatric labeling compliant with FDA guidance on accidental ingestion prevention.
- Pregnant Women:Category-specific safety labeling and acetaminophen-preferred positioning address teratogenic risk concerns, with pharmacist counseling requirements varying by state pharmacy board regulations.
Volume concentration sits with adults; formulation complexity intensifies for seniors.
Distribution Channel:
Channel economics determine whether products compete on price transparency, professional validation, or impulse accessibility.
- Pharmacies:CVS, Walgreens, and independent drugstores anchor professional recommendation ecosystems where pharmacist counseling drives category substitution and upsell to higher-margin house brands.
- Online Stores:Amazon and pharmacy-owned e-commerce platforms are displacing traditional traffic for replenishment purchases, with subscription models capturing chronic condition management occasions.
- Supermarkets:Kroger and Albertsons leverage high-frequency grocery trips for impulse categories like antacids and analgesics through strategic end-cap placement.
- Hospitals:Discharge prescription protocols and emergency department retail partnerships create controlled access points for specific therapeutic categories.
Professional validation favors pharmacies; convenience economics favor online stores.
Packaging Type:
Packaging specifications balance child safety compliance, dosing precision, and shelf differentiation across retail environments.
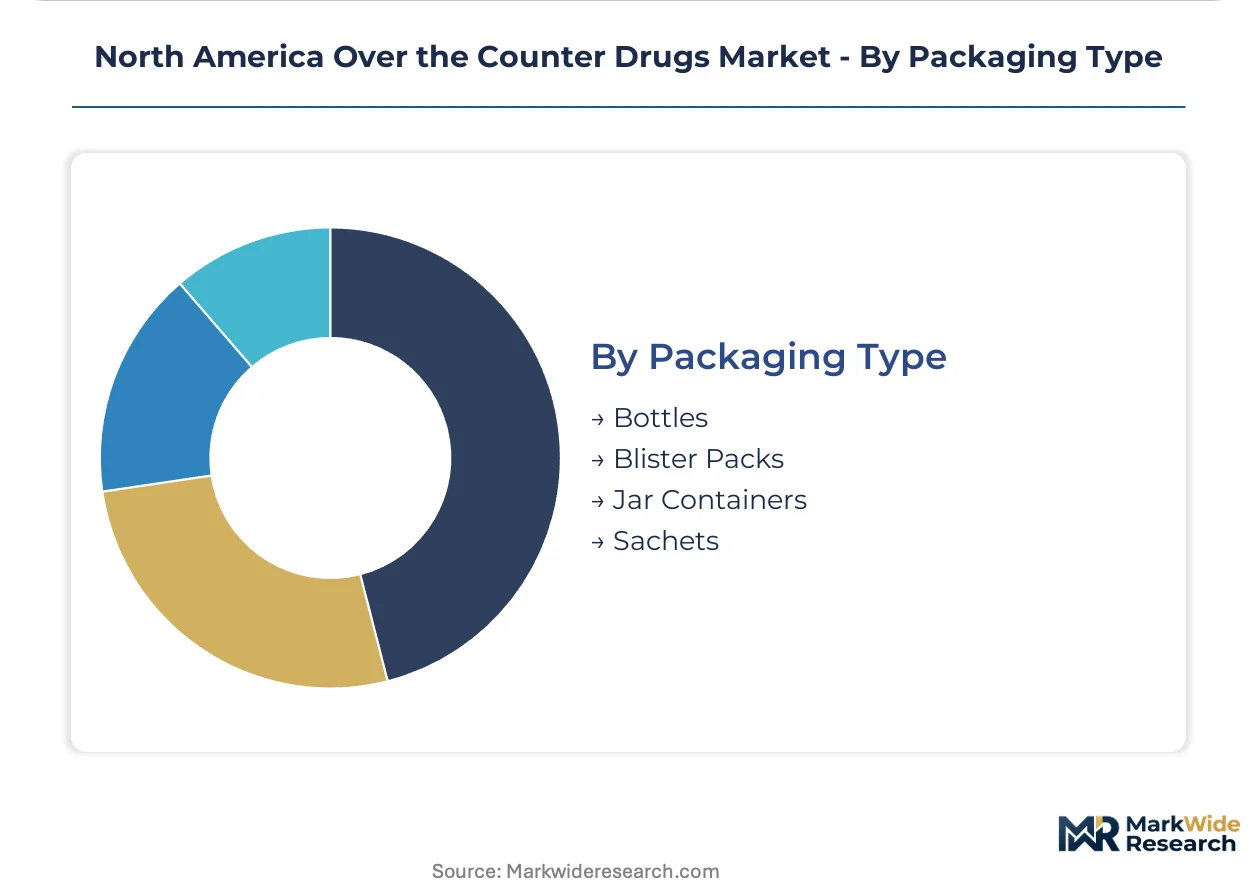
- Blister Packs:Unit-dose aluminum-plastic configurations with push-through foil satisfy FDA child-resistant packaging mandates while enabling precise adherence tracking for daily medication regimens.
- Bottles:HDPE containers with tamper-evident closures and dosing cups dominate liquid formulations, with CVS and Walgreens specifying proprietary bottle shapes for shelf differentiation.
- Jar Containers:Wide-mouth polypropylene vessels serve effervescent tablets and powder formulations requiring scoop access.
- Sachets:Single-serve foil pouches enable travel-size compliance and sample distribution through physician offices and direct mail programs.
Regulatory compliance favors blister packs; portability economics favor sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmacy chains and independent drugstores concentrate purchasing power among health-conscious aging adults across North American metropolitan corridors. Telehealth platforms and AI symptom checkers redirect patient flows toward non-prescription alternatives in suburban and rural catchments. Regulatory divergence between national frameworks creates compliance complexity for cross-border formulators.
United States
Adults over 65 manage chronic arthritis and hypertension through self-selected analgesics and digestive aids, expanding household medicine cabinet replenishment cycles. FDA monograph modernization under the administrative order pathway accelerates ingredient approval timelines while forcing reformulation investments. CVS and Walgreens anchor distribution concentration in Florida retirement communities and Arizona senior living clusters.
Canada
Seasonal allergy incidence intensifies across temperate Prairie provinces and Ontario corridors, driving antihistamine adoption among working-age populations. Health Canada applies the Natural Health Product framework to borderline formulations, creating distinct classification pathways from FDA standards. Toronto and Vancouver pharmacy networks prioritize pharmacist recommendation programs for cough-cold and analgesic categories.
Mexico
Urban middle-class households in Mexico City and Monterrey embrace self-medication for routine ailment management, reducing public health system burden. COFEPRIS regulatory alignment with FDA standards streamlines cross-border ingredient approvals for multinational formulators. Guadalajara pharmaceutical manufacturing clusters supply private-label formulations to domestic pharmacy chains and northern border retailers.
Pacific Northwest
Tech-savvy consumers in Seattle and Portland metro areas adopt subscription replenishment models for chronic condition management, bypassing traditional pharmacy traffic. State-level pharmacy board regulations in Washington and Oregon govern point-of-sale counseling requirements that shape retail staffing investments. Digital health platform integration with pharmacy apps concentrates in this corridor, routing symptom-checked patients toward OTC alternatives.
Southeast United States
Allergy season extension across Georgia and the Carolinas sustains antihistamine demand through expanded retail pharmacy networks. State Medicaid formulary restrictions on prescription medications push cost-conscious patients toward non-prescription substitutes. Independent pharmacies in Atlanta and Charlotte suburbs remain underserved by specialty digestive and respiratory OTC product lines.
North America Over the Counter Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across pharmacy, supermarket, and digital distribution vectors. The vendor base stratifies into three tiers: heritage consumer health portfolios with mass retail shelf dominance, pharmacy-led distribution networks prioritizing professional recommendation, and private-label formulators capturing price-sensitive volume. Strategic moves concentrate on portfolio diversification through prescription-to-OTC switches and backward integration into active pharmaceutical ingredient sourcing.
Within the heritage portfolio tier, Kenvue and Haleon occupy positions defined by brand recognition and retail channel penetration. Bayer exemplifies the R&D-intensive archetype, competing on formulation innovation in topical therapeutic categories. These three entities represent distinct competitive postures: mass retail shelf dominance, pharmacy network anchoring, and pharmaceutical rigor applied to consumer accessibility.
| Leading Market Players |
|---|
| Kenvue |
| Haleon |
| Bayer |
| Procter & Gamble |
| Reckitt |
| Sanofi |
| Perrigo |
| Pfizer |
| Novartis |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang manufacturing clusters anchor global ibuprofen and acetaminophen API production, concentrating upstream capacity in a narrow geographic band that amplifies formulator pricing power during freight disruptions. Their output fluctuations transmit directly into North American contract negotiations, where long-term offtake agreements carry force majeure clauses tied to port congestion indices.
Pricing Analysis
Cost-plus contracts with API indexation dominate procurement between North American formulators and Asian suppliers, embedding raw material volatility directly into finished goods pricing. Price differentiation rests on FDA monograph compliance tier and pharmacist recommendation program participation, with pharmacy chain house brands capturing the most price-sensitive volume. Pricing pressure stems from private-label substitution at mass retailers, compressing branded margin pools in analgesics. Least price-sensitive buyers cluster in hospital discharge and telehealth-referred segments where professional validation overrides cost considerations.
Supply Chain Analysis
Upstream feedstock production of ibuprofen intermediates and acetaminophen precursors concentrates in India and China, with secondary sourcing from South Korea for specialty excipients. Active pharmaceutical ingredients, packaging films, and child-resistant closures form the critical input trinity. Single-source vulnerability runs through the Ningbo pharmaceutical corridor, where customs delays cascade into batch release backlogs. Distribution runs through pharmacy chain distribution centers and Amazon fulfillment networks, with direct-to-patient subscription models bypassing traditional wholesale entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in rural pharmacy networks and AI-personalized subscription models, as digital health platform integration splinters traditional channel concentration into niche serviceable addressable markets.
For Market Incumbents: Harden adverse event surveillance infrastructure to defend against FDA monograph reform withdrawals, while securing captive API supply through backward integration into Indian pharmaceutical manufacturing. Kenvue and Haleon heritage portfolios face substitution threat from private-label formulators; vertical control over loratadine and cetirizine feedstock anchors margin defense.
For New Entrants and Emerging Players: Independent pharmacies in the United States Mountain West and Canadian Prairie provinces represent the most penetrable entry point, with dollar store distribution partnerships unlocking underserved respiratory and digestive categories. AI-powered symptom checker integrations through pharmacy apps offer the sharpest go-to-market angle, routing digitally-native consumers toward condition-specific product bundles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory agility play because FDA administrative order pathways and Health Canada Natural Health Product frameworks will continuously reshape competitive moats. Acquisition targets with documented quality management systems and existing monograph compliance infrastructure command defensive premiums. The signal to watch is FDA finalization of phenylephrine efficacy determinations, which will force portfolio restructuring across cough-cold incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Prescription-to-OTC Switch Pipeline | FDA administrative order pathways for intranasal corticosteroids expand addressable markets beyond legacy analgesics. |
| API Backward Integration | Captive supply of ibuprofen and acetaminophen precursors from Indian manufacturing clusters insulates against freight volatility. |
| AI Symptom Checker Partnership | Digital health platform integrations with CVS and Walgreens apps route patients toward non-prescription alternatives pre-visit. |
| Subscription Replenishment Launch | Auto-delivery models for seasonal allergy and arthritis management capture chronic condition occasions from retail pharmacy traffic. |
| Regulatory Affairs Talent Acquisition | FDA monograph reform and Health Canada borderline classification convergence outstrips professional supply, creating defensive capability scarcity. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with drug development executives, regulatory affairs leads, formulary directors, and pharmacy chain procurement managers; and secondary validation through FDA OTC monograph filings, Health Canada Natural Health Product submissions, ClinicalTrials.gov switch studies, and Nielsen retail audit data. Bottom-up volume modeling across dosage forms and patient populations triangulated against top-down category spend estimates from hospital procurement databases and GPO contracts.
Forecast inputs span product type, end user physiology tier, distribution channel, and regional regulatory cluster across the analysis window. CAGRs derive from segment-level growth rate blending weighted by baseline volume share. Modeled assumptions incorporate FDA administrative order timeline scenarios, pollen season extension climatology, and pharmacy chain merger consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in freight cost indices, API import tariff schedules, or Medicaid formulary restriction severity would shift the trajectory. Cross-checking against CMS Medicare Part D non-prescription substitution rates and provincial pharmacy board counseling requirement changes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Italy OTC Drugs Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market