
 Wound Cleanser Products Market | 2026-2036
Wound Cleanser Products Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Cleanser Products Market Intelligence
The increasing stringency of hospital infection control protocols is repositioning advanced, sterile cleansers against traditional bulk saline solutions. Mölnlycke Health Care AB specializes in antiseptic-based formulations for complex wounds. B. Braun SE leverages its scale in manufacturing to compete in the high-volume saline and antiseptic segments. Smith & Nephew differentiates through its integrated wound management portfolio, including advanced cleansers.
Wound cleanser products are sterile or non-sterile solutions designed to remove foreign material and reduce microbial load from acute and chronic wounds. These formulations are often pH-balanced and isotonic to avoid damaging healing tissue during irrigation. Spray and gel formats are gaining share over traditional liquids due to their controlled application and longer contact time. Hospitals remain the largest end-user segment by volume, but home care settings represent the fastest-growing channel for these products.
In the United States, the FDA classifies wound cleansers as medical devices, dictating stringent premarket approval pathways. Similarly, Europe's Medical Device Regulation (MDR) and CE marking requirements impose strict clinical evidence and post-market surveillance obligations. Manufacturers must therefore decide whether to invest in clinical data for high-margin antiseptic claims or compete on cost and volume in the saline solution space.
Market Dynamics
The central dynamic shaping the wound cleanser market is the clinical and regulatory push away from non-sterile, bulk solutions toward sterile, single-use formats. Infection control standards mandated by bodies like the US FDA and Europe's MDR are forcing this transition.
Growth Catalysts
- Regulatory Harmonization:Europe's Medical Device Regulation (MDR) elevates clinical evidence requirements, creating a preference for antiseptic cleansers with proven efficacy data and pushing out products with unsubstantiated claims.
- Demographic Shifts:Aging populations in developed nations like Japan and Germany are leading to a higher prevalence of chronic wounds, such as diabetic ulcers and pressure sores, which require consistent, high-quality wound management in home care settings.
- Product Innovation:The development of spray and gel formats is improving clinical outcomes by enabling more controlled application and longer contact time on the wound bed, which is favored by clinicians over traditional liquid irrigation.
Market Restraints
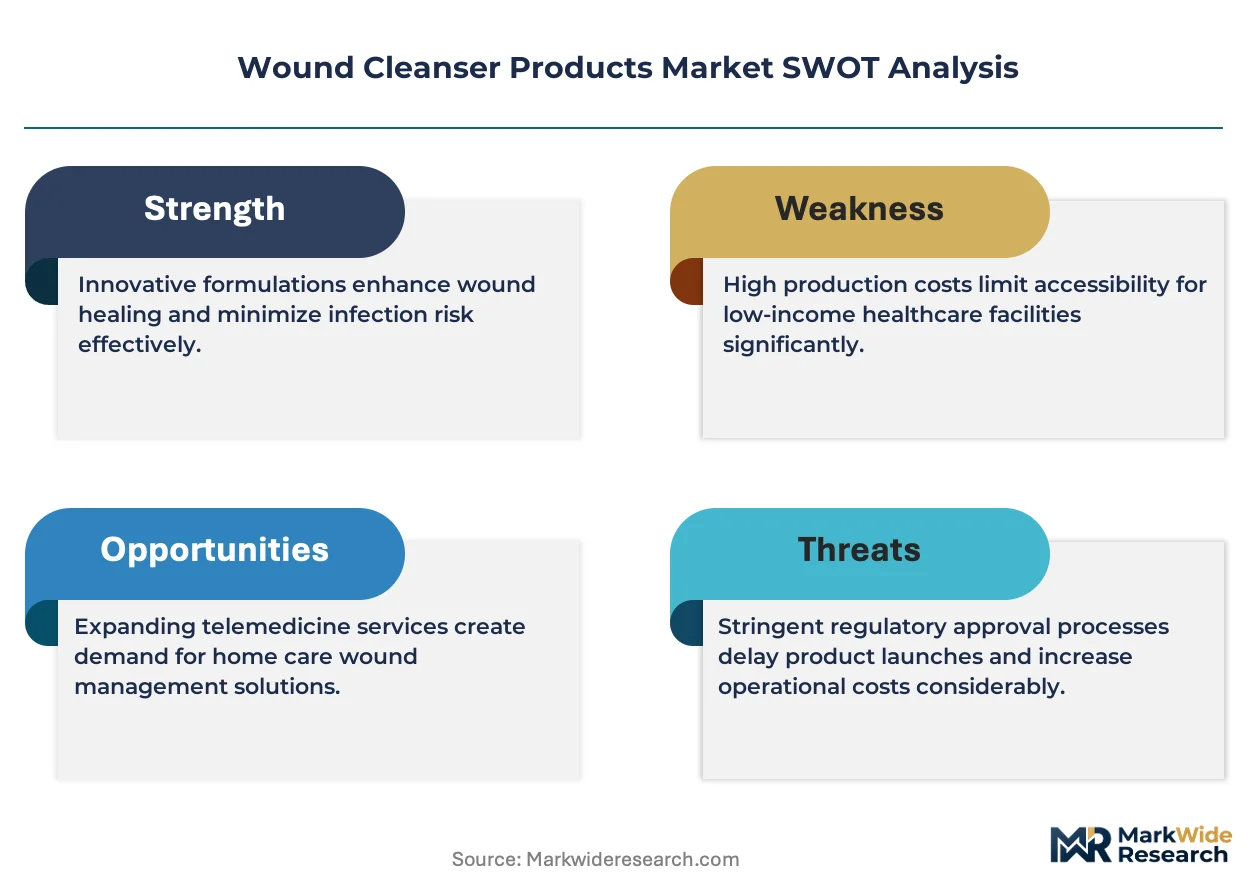
- Cost Containment Pressures:Hospital budget constraints often lead to the continued use of low-cost bulk saline solutions for general wound irrigation, limiting the uptake of more expensive, advanced antiseptic cleansers in high-volume settings.
- Substitution by Basic Solutions:In non-critical care environments or home settings without professional oversight, the use of simple tap water or basic saline as a substitute remains a persistent barrier to the adoption of specialized commercial cleansers.
- Clinical Evidence Burden:The significant financial investment and time required to conduct clinical trials for FDA or CE mark approval for antiseptic claims deters smaller manufacturers and slows innovation.
Strategic Opportunities
- Geographic Expansion:Markets such as Brazil and India, with their expanding healthcare infrastructure and growing middle class, represent significant, underpenetrated opportunities for advanced wound cleanser products.
- Specialized Formulations:There is an opportunity to develop cleansers targeted at specific, challenging wound types, such as those with heavy biofilm or those associated with compromised patient populations like oncology patients.
- Telehealth Integration:Digital health platforms can be used to guide patients and home caregivers in the proper selection and application of wound cleansers, creating a new channel for product education and sales.
Industry Challenges
- Distribution Complexity:Maintaining the stability and sterility of advanced formulations, particularly those with biological components, across complex global supply chains presents a significant logistical and cost challenge for manufacturers.
- Clinician Training Gaps:Ensuring that healthcare professionals, especially in the fast-growing home care sector, are adequately trained on the protocols for using new antiseptic and biofilm-disrupting cleansers is a continuous operational hurdle.
- Lack of Protocol Standardization:Divergent clinical guidelines for wound irrigation across different healthcare systems and regions create market fragmentation and complicate efforts to establish a universal standard of care.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Cleanser Products Market |
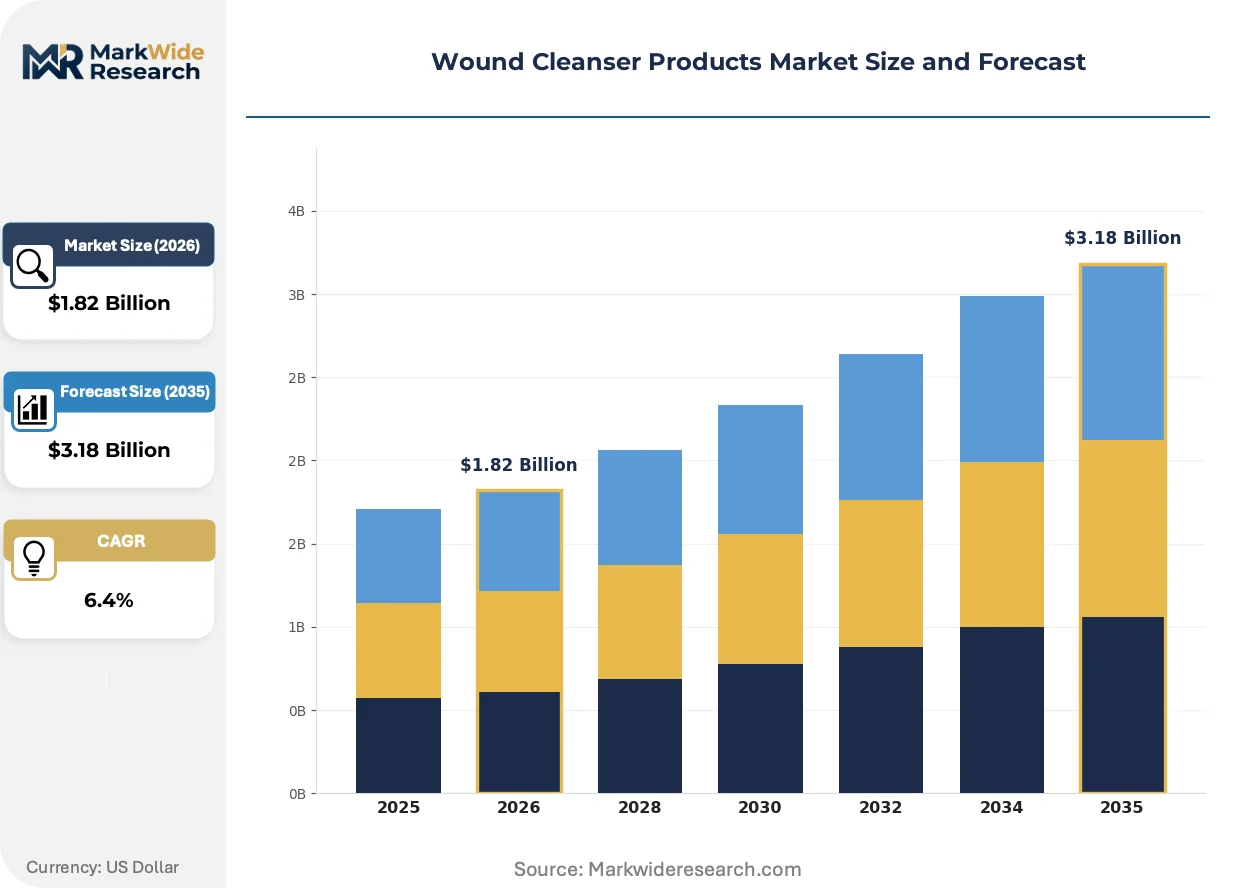
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Foam, Spray, Gel Active Ingredient: Hydrogen Peroxide, Saline, Iodine, Antiseptic End User: Hospitals, Home Care, Clinics, Nursing Homes Packaging Type: Bulk Containers, Single-Use Packets, Bottles, Squeeze Tubes |
| Companies Covered | 3M, Johnson & Johnson Services, Inc., Coloplast Corp, Smith & Nephew, B. Braun SE, Mölnlycke Health Care AB, Medline Industries, Inc., ConvaTec Group PLC, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Cleanser Products Market Strategic Shifts & Innovations
Product development is increasingly centered on creating formulations that actively support the healing process rather than simply cleaning the wound. This shift is driven by a deeper clinical understanding of the wound microenvironment and supported by regulatory frameworks that reward evidence-based claims.
Advanced gel-based formulations provide a moist, pH-balanced environment conducive to healing. Home care providers and outpatient wound clinics are rapidly adopting these products due to their ease of use and reduced application frequency. This technology is expanding into the management of difficult-to-treat chronic wounds, such as venous leg ulcers, where sustained contact and moisture donation are paramount for progress.
Europe's Medical Device Regulation (MDR) imposes stringent post-market surveillance and clinical evidence obligations on manufacturers. This regulation elevates the barrier to entry, forcing companies to invest significantly in generating robust data to support product claims. The antiseptic cleanser segment is most affected, now requiring a level of clinical proof comparable to some pharmaceuticals to maintain market access in the EU.
A shift from single-product purchasing to bundled solutions for entire episodes of care is altering hospital procurement. This change disadvantages standalone cleanser suppliers and favors integrated wound care companies that can offer a complete portfolio of dressings, debridement tools, and cleansers. This trend is most prominent within large, consolidated hospital networks in the United States and Germany seeking to standardize care and control costs.
Wound Cleanser Products Market Segmentation
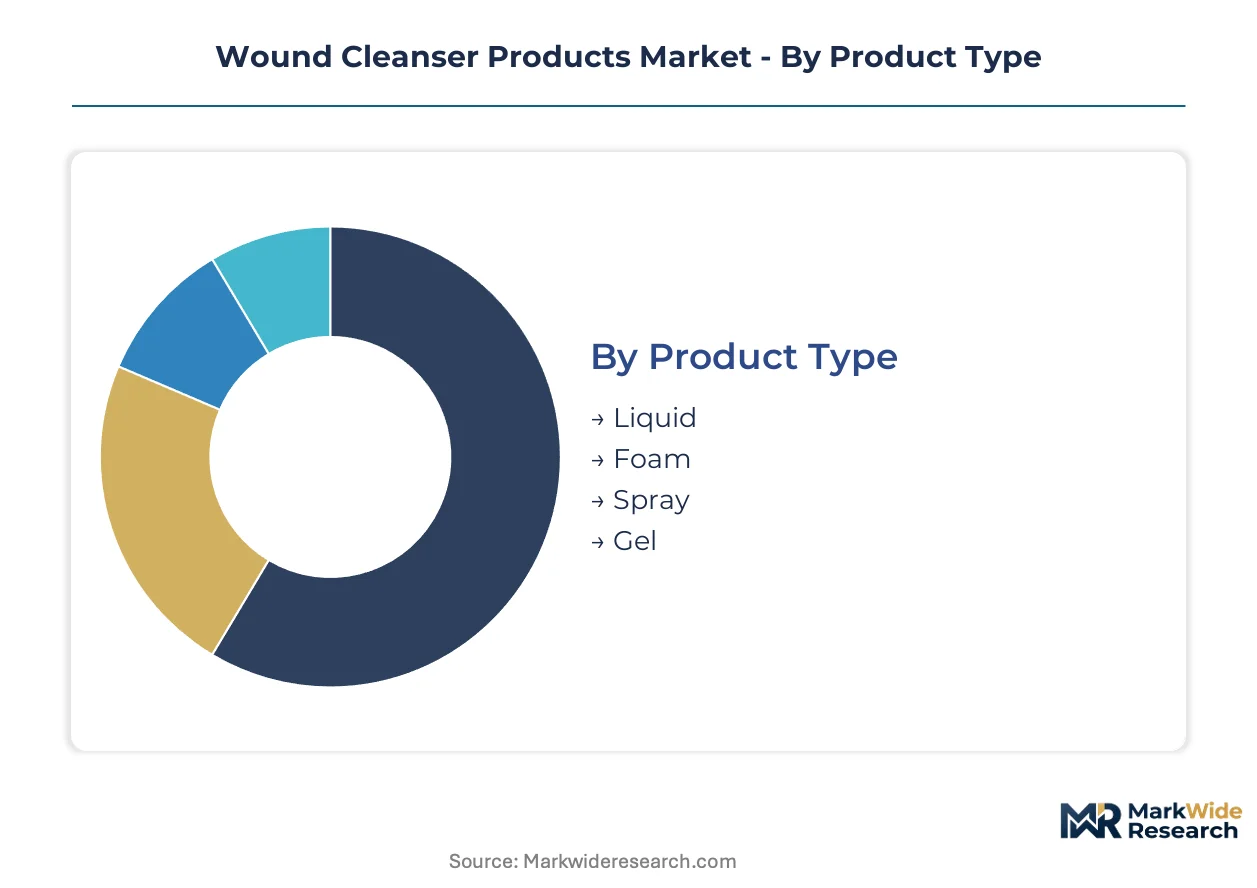
The wound cleanser products market stratifies across several critical dimensions, reflecting both clinical needs and regulatory mandates. Understanding these segments helps manufacturers tailor product development and market entry strategies, especially concerning the balance between advanced formulations and cost-effective solutions.
Product Type:
The product type spectrum ranges from highly customized spray and gel formats to more standardized liquid and foam solutions.
- Spray:These products deliver a fine mist, ensuring even distribution and controlled application across the wound bed. Demand for spray formats is concentrating in outpatient clinics and home care settings, driven by their ease of use and reduced risk of cross-contamination.
- Gel:Gel formulations provide sustained contact with the wound surface, creating a moist, pH-balanced environment conducive to healing. Outpatient wound clinics and home care providers in Germany and Japan are rapidly adopting gel cleansers for chronic wound management.
- Liquid:Traditional liquid cleansers, often saline-based, serve as the foundational products for general wound irrigation in hospital environments.
- Foam:Foam cleansers offer gentle application and can be particularly effective for sensitive skin areas or superficial wounds.
Most installed capacity flows through Liquid formulations. Expansion is steepest in Gel products.
Active Ingredient:
The active ingredient segment reflects a tension between broad-spectrum antimicrobial action and gentle tissue compatibility, often influencing clinical preference.
- Saline:Isotonic saline solutions are the most widely used cleansers, primarily for mechanical debridement and irrigation without chemical interference. Hospitals globally consume large volumes of saline due to its low cost and safety profile.
- Antiseptic:These formulations contain antimicrobial agents designed to reduce microbial load and prevent infection in complex or contaminated wounds. Regulatory bodies like the US FDA and Europe's MDR demand rigorous clinical evidence for antiseptic claims, particularly for high-margin products.
- Hydrogen Peroxide:Hydrogen peroxide offers effervescent cleaning action, suitable for removing debris from acute wounds, though its use is often limited by potential tissue toxicity.
- Iodine:Iodine-based cleansers provide broad-spectrum antimicrobial activity, frequently employed in surgical settings for skin preparation and wound disinfection.
Regulatory scrutiny heavily influences the adoption of Antiseptic cleansers, while Saline maintains its baseline utility.
End User:
The end-user segmentation highlights where wound care products are consumed, with varying demands for product sophistication and volume.
- Hospitals:Hospitals represent the largest volume segment, requiring a wide array of wound cleansers for surgical, emergency, and inpatient care. Procurement in large hospital networks in the United States and Germany increasingly favors bundled solutions.
- Home Care:Home care settings are the fastest-growing channel, driven by aging populations and the need for chronic wound management outside clinical environments. Patients in Japan and Germany rely on home care providers for consistent wound cleanser application.
- Clinics:Outpatient clinics, including specialized wound care centers, utilize advanced cleansers for routine debridement and follow-up care.
- Nursing Homes:Nursing homes require cleansers for managing pressure ulcers and other chronic wounds prevalent among elderly residents.
The segment of Hospitals drives significant revenue, whereas Home Care is experiencing substantial expansion due to demographic shifts.
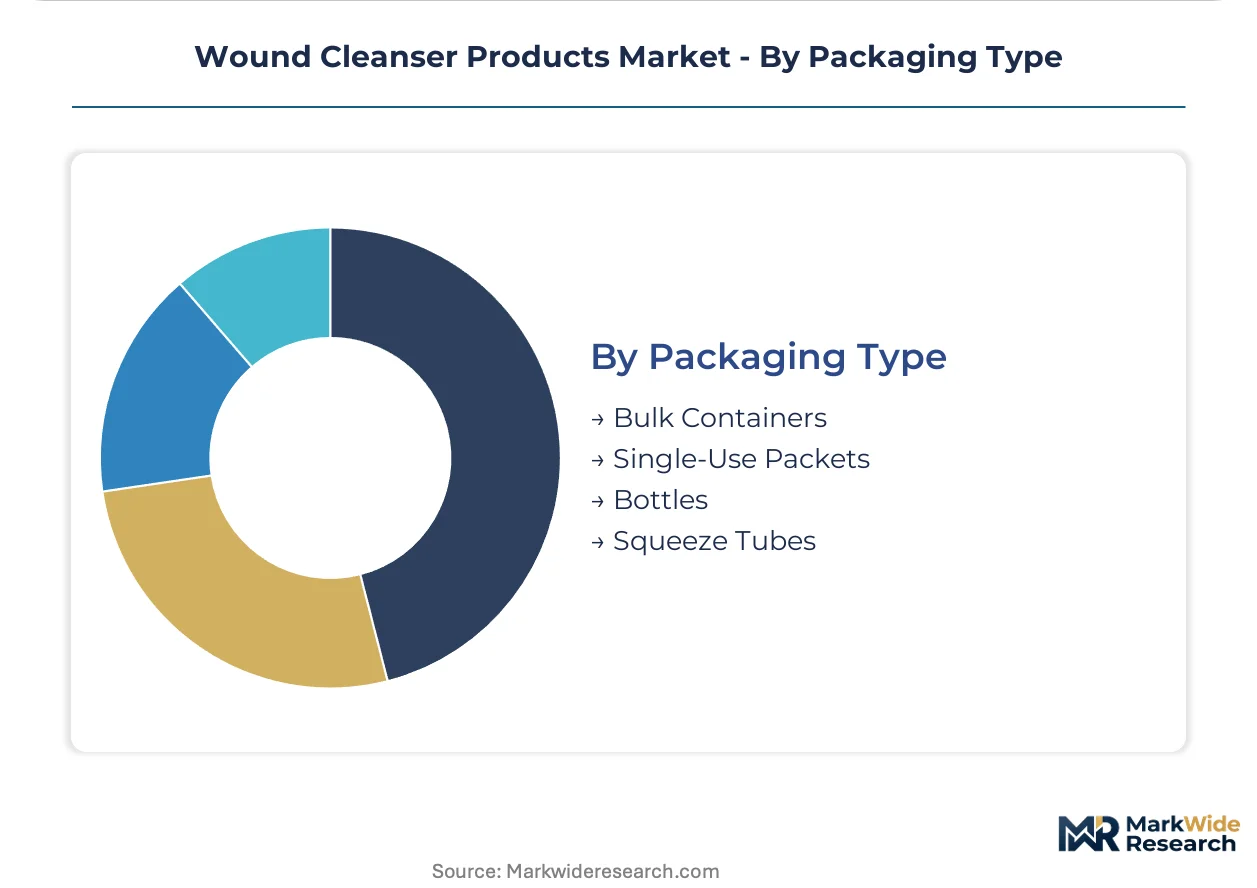
Packaging Type:
Packaging type influences product sterility, application method, and cost-effectiveness across different clinical environments.
- Single-Use Packets:These sterile, pre-measured packets minimize the risk of cross-contamination and are increasingly preferred in hospital and home care settings. Infection control standards from the US FDA and Europe's MDR favor single-use formats.
- Bulk Containers:Large-volume containers, typically for saline solutions, offer cost efficiencies for high-volume irrigation in hospital emergency departments. Cost containment pressures often lead hospitals to utilize these formats for general wound care.
- Bottles:Bottles provide a balance between volume and controlled dispensing, commonly used for liquid cleansers in various clinical and home care environments.
- Squeeze Tubes:Squeeze tubes are primarily associated with gel and viscous cleansers, enabling precise application and reducing product waste.
Procurement strategies are increasingly favoring Single-Use Packets for infection control, but Bulk Containers remain critical for cost-sensitive applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialized medical workforce in developed economies influences the uptake of advanced wound cleanser products, especially for chronic wound management. These regions often possess robust healthcare infrastructures and stringent regulatory frameworks that favor high-quality, evidence-based solutions. Demographic shifts, particularly aging populations, further concentrate demand for sophisticated wound care.
United States
High healthcare expenditure and a focus on infection control protocols fuel demand for single-use, sterile cleansers. The US FDA mandates rigorous premarket approval pathways for medical devices, including advanced wound cleansers. Boston's biotech hub leads research into novel wound healing formulations and advanced application methods.
Germany
Demand for advanced cleansers rises with an aging population and a high prevalence of chronic wounds, particularly in home care settings. Europe's Medical Device Regulation (MDR) ensures product quality and efficacy standards for market access. Major medical technology clusters like Erlangen foster innovation in wound care solutions.
Japan
An extensive home care infrastructure and a rapidly aging demographic increase demand for user-friendly gel and spray cleansers. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates product safety and efficacy for medical devices. Tokyo's medical device industry actively develops new application formats to meet clinical needs.
Brazil
Expanding healthcare infrastructure and a growing middle class increase the need for effective wound management solutions across hospital and clinic settings. ANVISA, the national health surveillance agency, oversees medical device registration and market access. São Paulo's medical device manufacturing sector is expanding its production capabilities.
India
Rising awareness of advanced wound care and an increasing burden of chronic diseases drive product penetration, particularly in urban centers. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing standards. Bengaluru's medical technology parks are attracting investment in wound care product development.
Wound Cleanser Products Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized manufacturers compete in niche areas. The market structure exhibits a tiered consolidation, with global healthcare conglomerates alongside focused wound care innovators. Key strategic archetypes include diversified medical device giants, advanced wound care specialists, and cost-efficient volume producers. Dominant competitive moves involve strategic partnerships for distribution and continuous portfolio diversification to meet evolving clinical needs.
Specialists in integrated wound management, Smith & Nephew and Mölnlycke Health Care AB, represent the advanced cleanser segment. Smith & Nephew exemplifies comprehensive wound care solutions, including advanced cleansers within its broader portfolio. Mölnlycke Health Care AB anchors the antiseptic-based formulations, focusing on complex wound management. B. Braun SE, a German-based company, occupies a position in both high-volume saline and antiseptic segments due to its manufacturing scale and extensive distribution network.
| Leading Market Players |
|---|
| 3M |
| Johnson & Johnson Services, Inc. |
| Coloplast Corp |
| Smith & Nephew |
| B. Braun SE |
| Mölnlycke Health Care AB |
| Medline Industries, Inc. |
| ConvaTec Group PLC |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
Infection control standards mandated by the US FDA and Europe's MDR favor single-use packaging formats, which increases manufacturing complexity and directly impacts product pricing. This shift necessitates supply chain adjustments to ensure sterility and efficient distribution, influencing overall market costs.
Pricing Analysis
Hospital procurement increasingly seeks bundled solutions for wound care, shifting pricing from transactional per-unit sales to value-based contracts for comprehensive packages. Price differentiation stems from robust clinical evidence supporting antiseptic claims and the guaranteed sterility of packaging formats. Cost containment pressures from hospital budgets intensify price sensitivity for basic saline solutions, particularly in high-volume settings. Conversely, advanced antiseptic cleansers with proven efficacy command premium pricing due to their clinical benefits.
Supply Chain Analysis
Reverse logistics for medical devices, particularly sterile wound cleansers, primarily involves managing product recalls and waste disposal according to strict environmental regulations. Supply concentration for advanced wound cleansers centers on Germany and the United States, while China and India provide basic components and bulk chemicals. Raw material dependencies include specialized polymers for gel and spray formats, alongside active pharmaceutical ingredients for antiseptic solutions. Regulatory hurdles for sterile manufacturing processes pose a structural risk. Distribution runs through specialized medical distributors and direct-to-hospital channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wound cleanser products market functions as a stable compounder, with demographic shifts towards aging populations consistently driving demand for chronic wound management solutions.
For Market Incumbents: Acquire specialized formulation intellectual property to counter the threat of niche innovators and evolving regulatory demands for clinical evidence. Consolidate distribution networks in emerging markets like Brazil to leverage existing infrastructure and expand reach. Invest in robust clinical data generation for antiseptic claims to defend premium pricing against cost-effective alternatives. Control over key raw material sourcing provides a lever against commodity price volatility.
For New Entrants and Emerging Players: Begin with targeted product development for specific challenging wound types, such as those with heavy biofilm, to penetrate underserved niches. Focus on home care settings in Japan with user-friendly gel and spray formats, leveraging telehealth integration for patient education. A go-to-market angle involves partnering with specialized wound care clinics to gain clinical validation and rapid adoption. Emphasize ease of use and reduced application frequency for home caregivers.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized wound care innovators possessing robust clinical data for advanced antiseptic formulations. These firms demonstrate strong intellectual property and regulatory compliance, ensuring long-term market access. Monitor the increasing integration of digital health platforms into home care, as this signals evolving patient engagement and potential for new sales channels. Acquisition targets should exhibit strong R&D pipelines and established clinical efficacy.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA/CE Mark Investment | Ensures market access for advanced antiseptic cleansers in regulated markets like the US and Europe. |
| Home Care Channel Expansion | Addresses the fastest-growing end-user segment driven by aging populations in Germany and Japan. |
| Specialized Formulation R&D | Targets specific wound types, improving clinical outcomes for complex cases like chronic diabetic ulcers. |
| Bundled Solutions Development | Meets hospital procurement preferences for comprehensive wound management portfolios, standardizing care. |
| Telehealth Platform Integration | Guides home caregivers on proper product application, expanding education and sales reach for new products. |
Research Approach
Direct dialogue with wound care clinicians, hospital procurement managers, home care providers, and regulatory affairs specialists informed the qualitative understanding of market dynamics. This primary research was validated against secondary data from US FDA filings, Europe MDR guidance documents, and medical device industry reports. The approach combined bottom-up data aggregation with top-down market sizing to ensure comprehensive coverage.
The quantitative model generated volume and value projections segmented by product type, active ingredient, end user, and packaging type across the analysis window. Compound annual growth rates were derived from historical trends and projected adoption rates, considering demographic shifts and regulatory impacts. Key forecast inputs included prevalence rates of chronic wounds and healthcare expenditure patterns in developed nations.
Several conditions sit outside the modeled scope, including specific regional reimbursement policies and unforeseen global health crises. Forecasts reflect assumptions regarding regulatory stability and technological advancements in wound care. Practitioners should monitor shifts in healthcare budget allocations and new clinical guideline adoptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Wound Closure Strips Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Burn Care Centers Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Wound Retractor Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
France Wound Care Market
Wound Care
Maggot Debridement Market
Wound Care
Chronic Wound Care Market
Wound Care
Surgery Medical Bandage Market