
 Renal Insufficiency Treatment Market | 2026-2036
Renal Insufficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Insufficiency Treatment Market Analytics
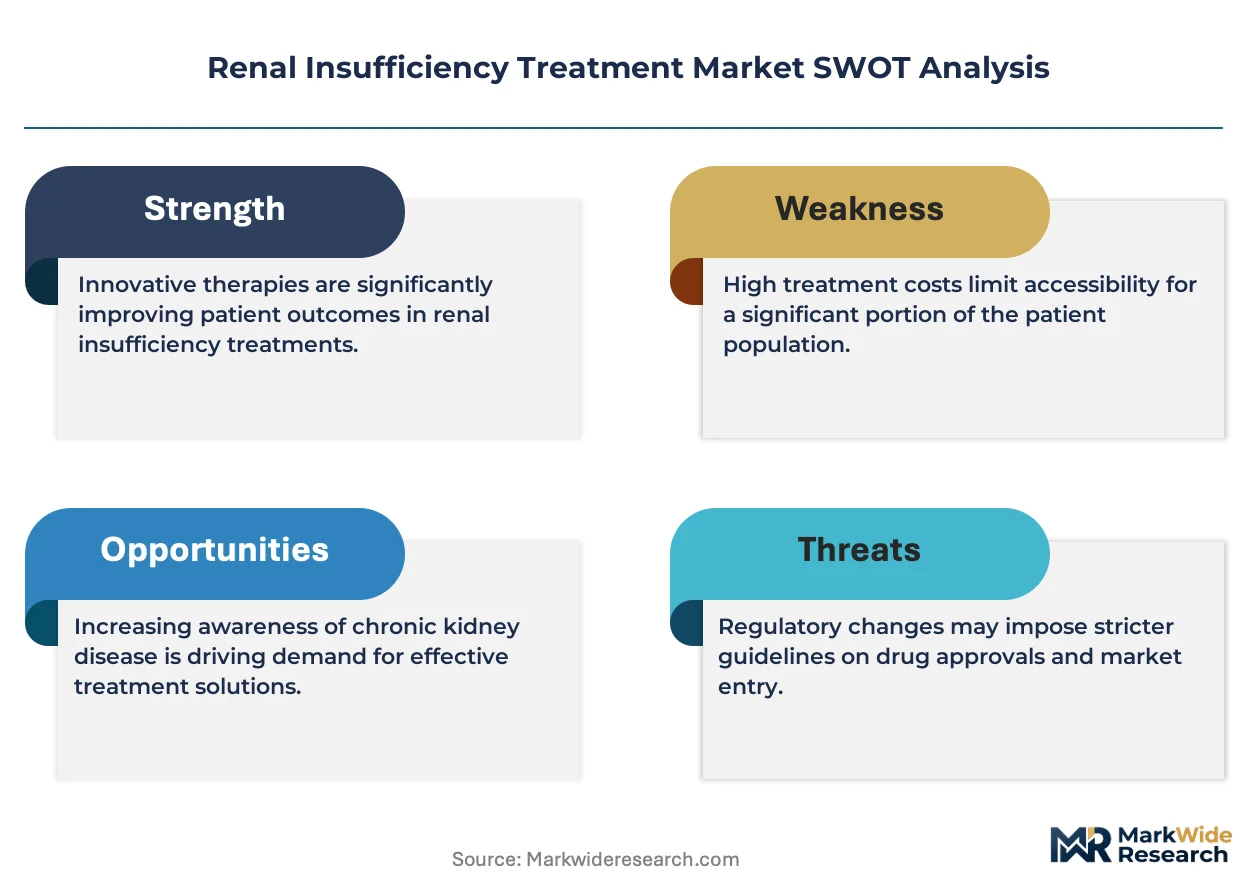
Home hemodialysis technology is fragmenting the traditional clinic-centric delivery model. Fresenius Medical Care AG leverages integrated dialysis systems to sustain its position across Europe and North America. Baxter anchors its portfolio in peritoneal dialysis solutions while competing on disposable supply economics. Asahi Kasei Medical Co., Ltd. specializes in hollow-fiber membrane technology that differentiates its dialyzers in high-flux segments.
Renal insufficiency treatment encompasses therapeutic interventions that compensate for declining glomerular filtration rate, including extracorporeal blood purification using semipermeable membranes with pore sizes typically ranging from 1 to 3 nanometers for uremic toxin clearance. These modalities serve patients with end-stage kidney disease by removing metabolic wastes, correcting electrolyte imbalances, and managing fluid overload. Hemodialysis equipment commands the largest installed base among product types, while home care settings represent the fastest-growing end user channel as reimbursement shifts favor decentralized delivery. Medications for renal anemia and mineral bone disorder concentrate margin pools due to chronic administration requirements and limited biosimilar penetration.
The FDA regulates dialysis devices as Class II or Class III medical products requiring 510(k) clearance or PMA approval, while the EMA's MDR framework imposes stricter clinical evidence standards for reusable renal replacement components. Japan's PMDA maintains distinct pharmacovigilance protocols for dialyzers that shape product registration timelines and post-market surveillance obligations. Stakeholders must monitor evolving reimbursement codes for home dialysis training and remote patient monitoring as these determine adoption velocity and capital allocation across delivery settings.
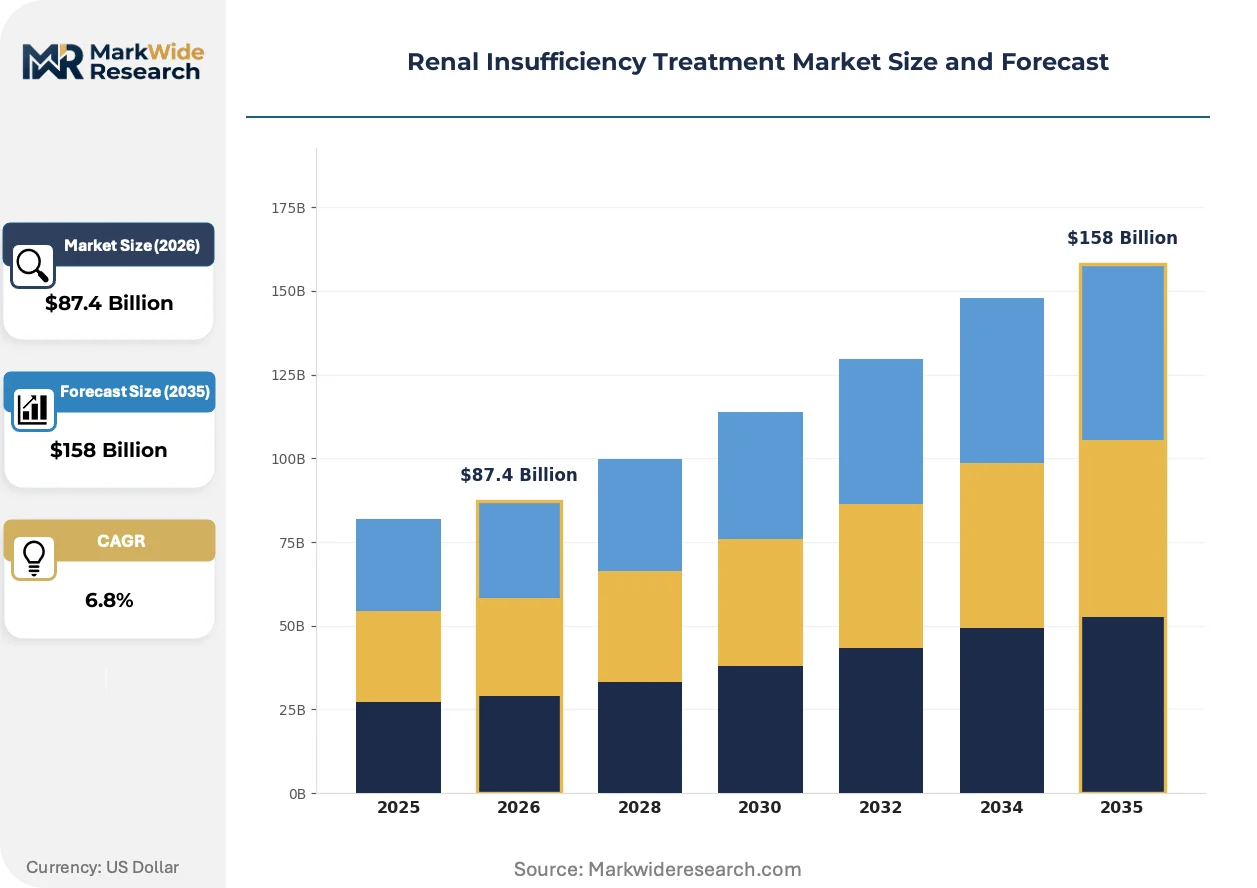
Market Dynamics
Home-based dialysis is fragmenting the traditional clinic-centric delivery model as reimbursement frameworks in the United States, Germany, and Japan increasingly favor decentralized renal replacement therapy. This structural shift is compressing capital deployment timelines for outpatient infrastructure while elevating remote patient monitoring capabilities as a competitive differentiator.
Growth Catalysts
- FDA breakthrough device pathway:The accelerated approval mechanism for novel renal therapies compresses time-to-market for innovative dialyzers and wearable artificial kidneys, stimulating R&D investment in blood purification technologies.
- Elderly patient preference shift:Aging demographics in Japan and Germany are driving demand for peritoneal dialysis solutions that enable treatment flexibility outside institutional settings.
- Hollow-fiber membrane advances:High-flux dialyzer performance improvements are expanding clearance efficiency for middle-molecular-weight uremic toxins, improving clinical outcomes in long-term hemodialysis populations.
Market Restraints
- Polymer supply concentration:Specialized polysulfone and polyethersulfone membrane materials concentrate among a limited supplier base in Germany and Japan, creating input cost volatility for dialyzer manufacturers.
- EMA MDR clinical evidence requirements:Stricter documentation standards for reusable renal replacement components extend registration timelines and elevate compliance expenditures for European market entry.
- Peritoneal dialysis catheter infection rates:Technical limitations in connection technology sustain hospitalization risks that constrain home therapy penetration among immunocompromised patient segments.
Strategic Opportunities
- Remote patient monitoring integration:Telehealth infrastructure expansion in the United States creates white space for cloud-connected dialysis machines that transmit treatment data to nephrology care teams in real time.
- Japan's PMDA pharmacovigilance protocols:Distinct post-market surveillance obligations for dialyzers favor manufacturers with established quality management systems, creating regulatory tailwinds for compliant entrants.
- Wearable artificial kidney convergence:Miniaturization of sorbent regeneration technology and battery efficiency gains are enabling ambulatory renal replacement outside fixed infrastructure.
Industry Challenges
- Bioengineered vascular access skill scarcity:Surgeon training programs for arteriovenous fistula creation lag patient need, creating bottlenecks in hemodialysis initiation timelines.
- Legacy EMR integration complexity:Home dialysis equipment data formats lack standardization with hospital electronic medical record systems, complicating care coordination across delivery settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Insufficiency Treatment Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialisys Machines, Dialysis Solutions, Renal Replacement Therapy Devices, Medications End User: Hospitals, Outpatient Clinics, Home Care Settings, Dialysis Centers Treatment Type: Hemodialysis, Peritoneal Dialysis, Kidney Transplantation, Conservative Management Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Fresenius Medical Care AG, Baxter, NIPRO, Medtronic, B. Braun SE, Asahi Kasei Medical Co., Ltd., AbbVie Inc., Nikkiso Co., Ltd., JMS Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Insufficiency Treatment Market Evolving Landscape
Sensor-enabled dialysis systems are digitizing treatment parameter optimization. This technological wave is compressing the gap between clinical prescription and real-time therapy adjustment, while regulatory frameworks scramble to accommodate software-as-medical-device classifications for algorithm-driven blood purification.
Artificial intelligence is digitizing ultrafiltration rate prediction in next-generation hemodialysis machines. Nephrology departments in academic medical centers are piloting these systems to reduce intradialytic hypotension episodes. The structural consequence is a shift from reactive symptom management to preemptive fluid removal modulation, compressing adverse event rates and hospitalization frequency.
The FDA's breakthrough device designation pathway is accelerating novel renal therapy approvals by permitting rolling review of clinical evidence packages. This regulatory mechanism compresses premarket submission timelines for innovative dialyzers and sorbent systems. Wearable artificial kidney developers are the primary beneficiaries, leveraging the pathway to secure earlier commercial dialogue with agency reviewers.
Hospital procurement departments are unbundling dialysis supply contracts from equipment lease agreements. This purchasing behavior change disrupts the traditional bundled-rental model that locked providers into single-source disposable relationships. The United States exhibits the most visible manifestation of this shift, where integrated delivery networks negotiate direct sourcing agreements for dialyzers and bloodlines separate from machine maintenance contracts.
Renal Insufficiency Treatment Market Segmentation
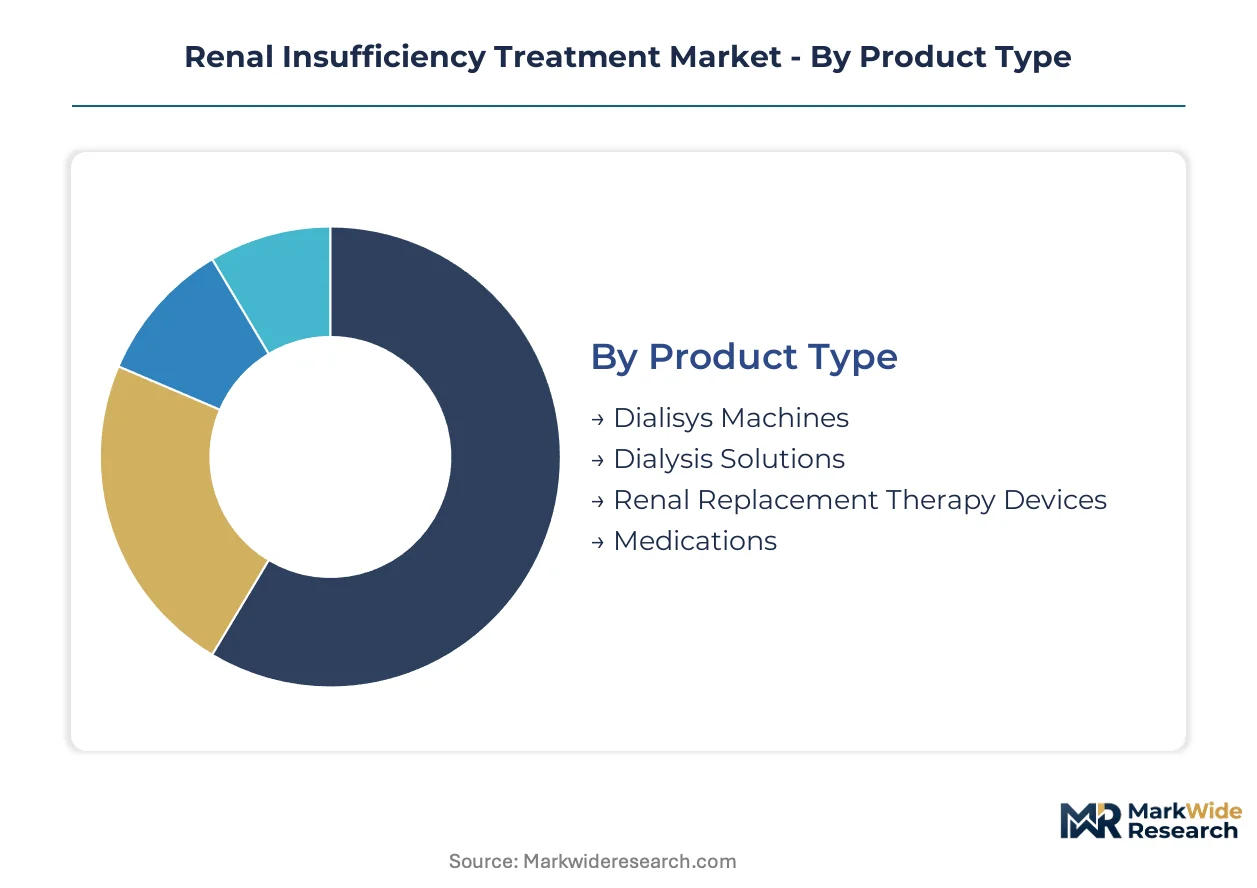
Renal insufficiency treatment markets fragment across four structural dimensions that determine capital deployment cycles and margin capture. Equipment-intensive segments command extended replacement timelines while consumable categories turn inventory faster and concentrate recurring revenue pools.
Product Type:
Dialysis machines stretch capital cycles across seven-to-ten-year depreciation schedules while disposable dialyzers and solutions compress replenishment windows to single sessions or monthly intervals.
- Dialysis Machines:Integrated hemodialysis systems incorporate volumetric ultrafiltration control, conductivity monitoring, and heparin pumps for automated anticoagulation. United States hospital procurement departments favor lease-to-own structures that bundle preventive maintenance, constraining pure equipment sales velocity.
- Dialysis Solutions:Acid concentrate and bicarbonate cartridges constitute the highest-turnover product class with per-treatment consumption driving recurring revenue density. German outpatient clinics negotiate multi-year supply agreements that lock acetate-free formulations at contracted price tiers.
- Renal Replacement Therapy Devices:Continuous renal replacement therapy machines for acute kidney injury operate in intensive care settings with intermittent utilization patterns.
- Medications:Erythropoiesis-stimulating agents and phosphate binders sustain chronic administration models in Japan's reimbursement framework.
Dialysis solutions anchor the volume base while renal replacement therapy devices gain share at the steepest rate in acute care expansion.
End User:
Site-of-care economics diverge sharply between fixed infrastructure investments and decentralized delivery models that shift reimbursement risk toward patients and caregivers.
- Hospitals:Academic medical centers maintain captive dialysis units for complex comorbid patients requiring on-site surgical and interventional nephrology support. These facilities concentrate high-acuity cases with elevated staffing ratios and overnight dialysis capabilities.
- Home Care Settings:Peritoneal dialysis and home hemodialysis programs eliminate facility overhead while demanding intensive training infrastructure and remote monitoring investments. United States Medicare reimbursement for home training creates margin expansion versus in-center equivalents.
- Outpatient Clinics:Freestanding dialysis centers operate on standardized treatment protocols with optimized patient throughput.
- Dialysis Centers:Large chain-affiliated facilities leverage purchasing scale across consumable categories.
Hospitals retain the highest revenue per treatment while home care settings climb fastest as reimbursement tilts toward decentralized models.
Treatment Type:
Modality selection locks patients into distinct supply ecosystems with varying technical complexity and lifestyle flexibility tradeoffs.
- Hemodialysis:Extracorporeal blood purification through arteriovenous access requires thrice-weekly facility attendance or substantial home infrastructure investment. Vascular access maintenance and intradialytic complication management concentrate clinical resource intensity in this modality.
- Peritoneal Dialysis:Continuous ambulatory and automated peritoneal dialysis exploit the peritoneal membrane as native filtration surface, enabling daytime mobility or overnight cycler therapy. Catheter-related peritonitis risk constrains penetration among diabetic patient populations with immunocompromise.
- Kidney Transplantation:Immunosuppression protocols and organ procurement logistics limit scalability despite superior long-term outcomes.
- Conservative Management:Palliative symptom control without renal replacement serves frail elderly patients declining invasive therapy.
Hemodialysis holds the dominant patient share while peritoneal dialysis expands most quickly in aging European and Japanese populations prioritizing autonomy.
Distribution Channel:
Channel structure reflects regulatory control intensity with prescription requirements and reimbursement gatekeeping determining flow patterns.
- Hospital Pharmacies:Captive dispensing of dialysis-related medications and emergency dialyzer reserves integrates with electronic medical record systems for allergy screening and dosing verification. These units prioritize formulary compliance over price competition.
- Direct Sales:Original equipment manufacturers deploy field service engineers and clinical specialists to negotiate machine placement and disposable supply contracts. This channel captures the highest-value transactions with multi-year commitment structures.
- Retail Pharmacies:Community dispensing of oral phosphate binders and vitamin D analogs serves stable outpatient populations.
- Online Pharmacies:Emerging digital channels for consumable home delivery face reimbursement complexity and cold-chain logistics constraints.
Hospital pharmacies dominate high-acuity medication flow while direct sales command equipment and bundled supply economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dialyzer manufacturers export hollow-fiber membrane systems to United States outpatient networks, establishing a transatlantic trade corridor in renal replacement technology.
United States
Medicare reimbursement for home dialysis training and remote patient monitoring drives decentralized care adoption. The FDA breakthrough device pathway accelerates approvals for wearable artificial kidney prototypes. Boston and Minneapolis anchor medical device clusters where nephrology startups pilot sensor-enabled dialysis systems.
Germany
Outpatient clinic networks demand high-flux dialyzers with acetate-free formulations for aging patient populations. The EMA MDR framework imposes stricter clinical evidence standards for reusable renal components. Baden-Württemberg concentrates polysulfone membrane manufacturing facilities serving European dialysis supply chains.
Japan
Elderly demographics prioritize peritoneal dialysis autonomy over institutional hemodialysis. The PMDA maintains distinct pharmacovigilance protocols for dialyzers that shape registration timelines. Tokyo and Osaka host integrated delivery networks negotiating direct sourcing agreements for consumables separate from equipment leases.
China
Expanding end-stage kidney disease patient pools strain existing hemodialysis infrastructure. The NMPA regulates dialysis devices as Class III medical products requiring extensive clinical trials. Shanghai and Beijing medical centers pilot cloud-connected dialysis machines for real-time nephrology oversight.
India
Chronic kidney disease prevalence rises among diabetic populations in urban corridors. The CDSCO streamlines import licensing for dialysis equipment while prioritizing local manufacturing incentives. Maharashtra and Karnataka host hospital chains expanding captive dialysis unit capacity.
Renal Insufficiency Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base clusters around three strategic archetypes: integrated dialysis system providers, hollow-fiber membrane specialists, and pharmaceutical adjunct therapy suppliers. Consolidation pressure intensifies as hospital procurement departments unbundle supply contracts from equipment leases. Competitive moves concentrate on strategic partnerships for remote patient monitoring integration and geographic licensing agreements for sorbent regeneration technology.
Among integrated system providers, Fresenius Medical Care AG and Baxter exemplify channel-control archetypes that bundle equipment placement with consumable supply commitments. Asahi Kasei Medical Co., Ltd. occupies a specialist position representing membrane technology differentiation in high-flux dialyzer segments.
| Leading Market Players |
|---|
| Fresenius Medical Care AG |
| Baxter |
| NIPRO |
| Medtronic |
| B. Braun SE |
| Asahi Kasei Medical Co., Ltd. |
| AbbVie Inc. |
| Nikkiso Co., Ltd. |
| JMS Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on German and Japanese polysulfone membrane suppliers determines both pricing tier spreads and supply chain shape, compressing margin buffers for dialyzer manufacturers while elevating acetate-free formulation premiums in outpatient procurement negotiations.
Pricing Analysis
High-flux dialyzer generations command substantial premiums over conventional low-flux alternatives, with sensor-enabled systems introducing subscription-style remote monitoring fees atop equipment leases. Pricing stratifies across premium, standard, and economy tiers based on membrane flux performance and FDA breakthrough device certification status. Cost compression in standard-tier dialyzers is intensifying because hospital procurement departments unbundle supply contracts from equipment maintenance agreements. Dialysis centers affiliated with large chains exhibit lowest price sensitivity due to volume-scale purchasing power, while independent outpatient clinics face acute margin pressure from reimbursement rate stagnation.
Supply Chain Analysis
Extended payment terms from integrated delivery networks in the United States force hollow-fiber membrane manufacturers to deploy supply-chain finance facilities, elevating working capital intensity across tier-two suppliers. Production gravity centers on Germany, Japan, and the United States for specialized polysulfone and polyethersulfone materials, with Baden-Württemberg hosting concentrated membrane extrusion capacity. Raw material dependencies span medical-grade polymers, heparin coatings, and sterilization packaging components. Single-source vulnerability in German polysulfone feedstock creates tariff exposure risk for transatlantic dialyzer shipments. Distribution runs through direct sales channels with field service engineers negotiating multi-year equipment placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of bioengineered vascular access surgical capability constrains hemodialysis initiation capacity, creating structural bottlenecks that favor stakeholders controlling fistula creation training pipelines and remote patient monitoring infrastructure.
For Market Incumbents: Build regulatory data moats through FDA breakthrough device pathway submissions for wearable artificial kidney platforms, preempting emerging sorbent regeneration specialists from securing accelerated review timelines. Deepen backward integration into hollow-fiber membrane manufacturing to capture polysulfone supply chain margins currently leaking to German chemical suppliers. Channel control through bundled lease-to-own structures defends against procurement department unbundling initiatives. For New Entrants and Emerging Players: Build out cloud-connected dialysis machine capabilities targeting United States Medicare reimbursement codes for home training and remote monitoring, the most penetrable reimbursement white space. Peritoneal dialysis catheter infection prevention technology represents underserved clinical need with limited incumbent R&D focus. Go-to-market positioning through nephrology academic medical center pilot programs generates clinical evidence for downstream GPO contract eligibility. For Investors and Strategic Acquirers: Hollow-fiber membrane specialists with established PMDA pharmacovigilance compliance systems offer durable acquisition targets as Japanese regulatory barriers sustain quality management premiums. Long-term viability across the analysis window rests on convergence toward ambulatory renal replacement outside fixed infrastructure. Watch FDA breakthrough device designation grants to wearable artificial kidney developers as inflection indicator for sorbent technology commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress premarket approval cycles for novel dialyzer formats. |
| Remote Patient Monitoring Integration | Cloud-connected dialysis machines transmit real-time treatment data to nephrology care teams. |
| Backward Integration into Membrane Manufacturing | Captive polysulfone production insulates margin structures from German supplier concentration. |
| Hospital System Partnership | Academic medical center pilots generate clinical evidence for GPO contract eligibility. |
| Reimbursement Strategy Development | Medicare home training codes determine adoption velocity for decentralized delivery models. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dialysis equipment procurement managers, nephrology department heads, biomedical engineers, and GPO contracts administrators; and secondary validation against FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement contract repositories, and EMA MDR technical documentation. Bottom-up patient volume modeling across treatment modalities triangulated with top-down manufacturer revenue segmentation.
Forecast inputs span hemodialysis and peritoneal dialysis modality splits, home care versus institutional delivery setting trajectories, and high-flux versus low-flux dialyzer penetration curves across the projection horizon. Segmentation dimensions include product type, end user channel, treatment modality, and geographic regulatory cluster. CAGRs derive from installed base replacement cycles, reimbursement code evolution, and patient demographic projections without year-specific anchoring.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by hollow-fiber membrane specialists or rapid sorbent regeneration technology advances by emerging entrants would shift outcomes beyond modeled ranges. Macroeconomic deviation in healthcare reimbursement, regulatory tightening in EMA MDR clinical evidence requirements, or technological disruption from wearable artificial kidney commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Dialysis Centers Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Plasmapheresis Market
Nephrology
Kidney Transplant Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
US Dialysis Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Renal Denervation Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
End Stage Renal Disease Market