
 Global Diabetic Foot Ulcers Market | 2026-2036
Global Diabetic Foot Ulcers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Foot Ulcers Market Foresight
Modular dressing kits that combine antimicrobial layers with offloading components is hardening as the default procurement format for hospital wound care programs. Smith & Nephew Plc leverages its integrated advanced wound management portfolio to anchor large accountable care organization contracts in the United States. ConvaTec Group Plc competes through specialized ostomy and wound care expertise that extends into diabetic foot protocols across European national health systems. Mölnlycke Health Care AB dominates Nordic and British hospital purchasing through direct channel control and sustained clinician education investments.
Diabetic foot ulcers are chronic wounds of the lower extremity resulting from neuropathy, ischemia, and repetitive mechanical stress, typically graded by depth and infection status using the Wagner or University of Texas classification systems. These lesions require moisture-balanced dressings, periodic debridement, infection management, and pressure redistribution to prevent progression to osteomyelitis or amputation. Wound dressings and skin substitutes capture the deepest margin pools where bioactive and antimicrobial formulations command premium positioning against commodity gauze alternatives. Negative pressure wound therapy and growth factor therapy represent the fastest-expanding treatment technology segments as outpatient and home healthcare providers adopt portable systems that reduce hospital length of stay.
FDA 510(k) and PMA pathways for cellular and tissue-based products shape R&D investment timelines and clinical trial design for manufacturers seeking US market access. EMA medical device regulation and MDR conformity requirements in Europe impose additional biocompatibility and post-market surveillance obligations on dressing and implant suppliers. Stakeholders must monitor reimbursement shifts toward value-based wound care bundles and anticipate how FDA digital health guidance for remote patient monitoring may reshape home healthcare provider economics and technology partnerships.
Market Dynamics
Hospital procurement teams are consolidating advanced wound care spend into bundled contracts that tie dressing costs to healing outcomes, forcing manufacturers to restructure pricing and service models around episode-based reimbursement rather than unit sales.
Growth Catalysts
- CMS bundled payment expansion:Medicare's mandatory bundled payment models for lower extremity joint replacement are extending into diabetic foot care episodes, creating financial incentives for hospitals to invest in comprehensive wound management protocols.
- Negative pressure portability:Lightweight battery-powered negative pressure wound therapy systems are enabling home healthcare providers to manage complex diabetic foot ulcers outside acute settings, reducing readmission penalties for hospitals.
- Germany's specialized limb salvage centers:Concentrated investment in multidisciplinary diabetic foot clinics across Bavaria and North Rhine-Westphalia is generating standardized referral pathways that concentrate demand for advanced dressings and bioactive grafts.
Market Restraints
- Silver and antimicrobial raw material volatility:Fluctuations in silver nitrate and iodine compound costs compress margins on antimicrobial dressings, particularly for mid-tier manufacturers without long-term supply agreements.
- FDA PMA pathway duration:Cellular and tissue-based skin substitutes face 24-36 month approval timelines with substantial clinical evidence requirements, delaying commercialization for novel bioengineered products.
- Commodity gauze substitution:Basic hydrocolloid and foam dressings face pricing pressure from low-cost Asian manufacturers, eroding revenue pools in price-sensitive institutional segments.
Strategic Opportunities
- Japan's aging diabetic population:Metropolitan Tokyo and Osaka healthcare networks are expanding outpatient wound centers with limited domestic advanced dressing production, creating import demand for European and North American suppliers.
- Remote patient monitoring convergence:Integration of temperature-sensing dressings with cloud-based wound tracking platforms is opening subscription revenue models for device manufacturers partnering with telehealth providers.
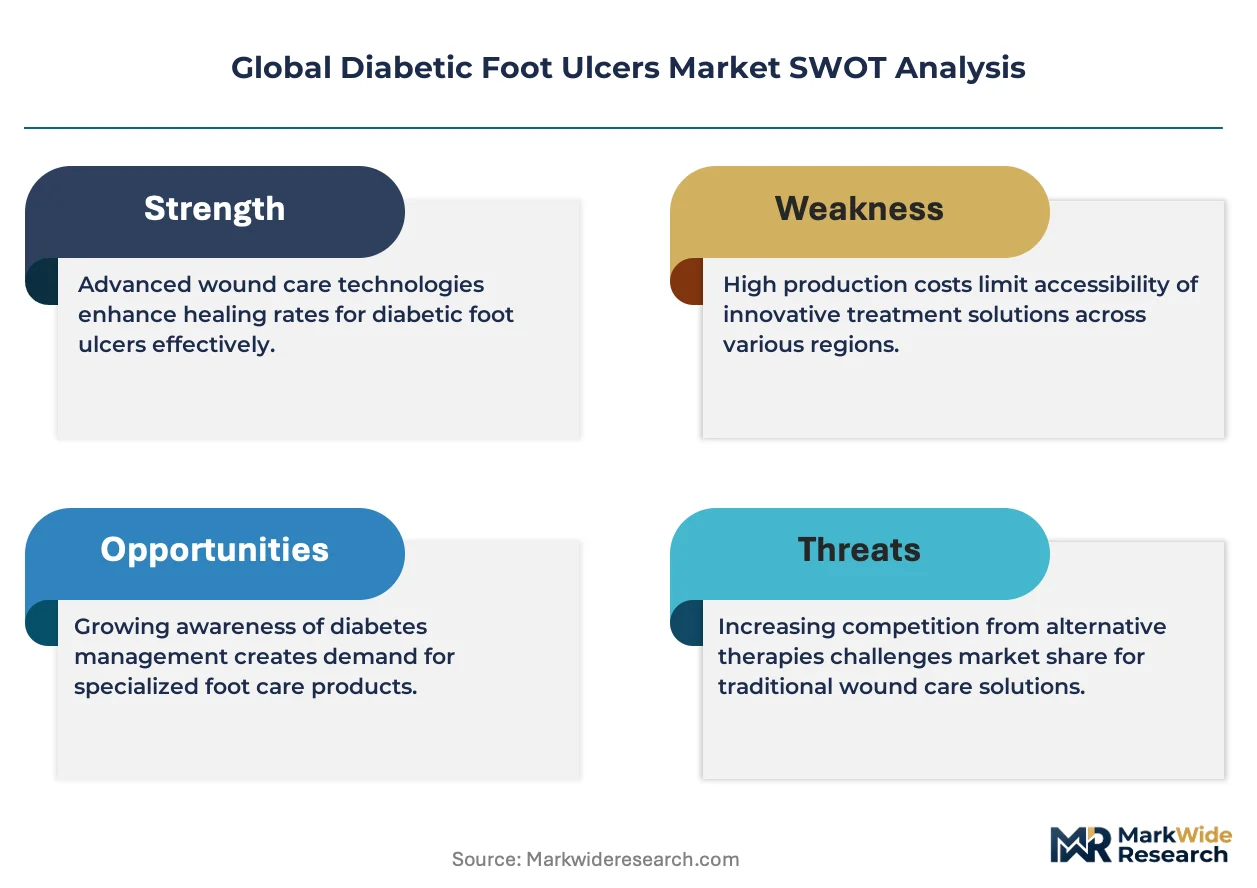
- EU MDR notified body scarcity:Bottlenecks in CE marking certification for class III wound care devices are creating first-mover advantages for manufacturers with established conformity assessment partnerships.
Industry Challenges
- Wound care specialist workforce gaps:Shortages of certified wound ostomy continence nurses in United States rural markets limit adoption of complex dressing protocols requiring trained application.
- Interoperability with electronic health records:Digital wound measurement tools face integration friction with legacy hospital information systems, delaying deployment of AI-assisted healing prediction algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diabetic Foot Ulcers Market |
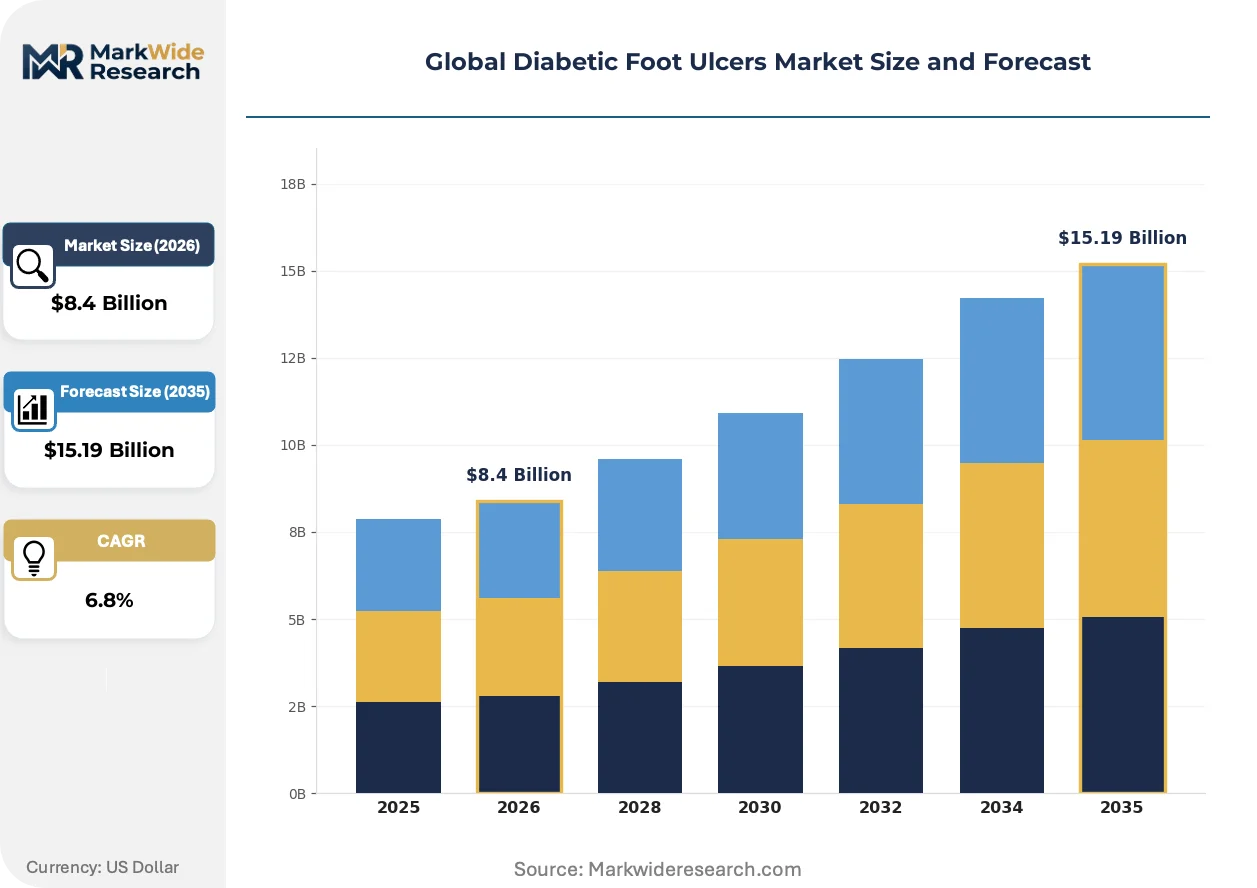
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wound Dressings, Therapeutic Footwear, Surgical Implants, Skin Substitutes, Topical Agents Application: Ulcer Prevention, Debridement, Infection Control, Tissue Regeneration, Pressure Redistribution End User: Hospitals, Specialty Clinics, Long-Term Care Facilities, Home Healthcare Providers Treatment Technology: Negative Pressure Wound Therapy, Hyperbaric Oxygen Therapy, Growth Factor Therapy, Electrical Stimulation |
| Companies Covered | Smith & Nephew Plc, ConvaTec Group Plc, 3M Health Care, Coloplast A/S, Mölnlycke Health Care AB, B. Braun Melsungen AG, Organogenesis Inc., Integra LifeSciences, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Foot Ulcers Market Shifts & Advancements
Biomaterial science and digital connectivity are converging to transform diabetic foot ulcer management from reactive dressing changes into predictive, data-driven care pathways that compress healing timelines and reduce amputation rates.
Antimicrobial peptides synthesized from recombinant human proteins are expanding into standard-of-care protocols for infected Wagner grade 3 and 4 ulcers. Academic medical centers in the United States and university hospitals in Sweden are adopting these bioactive dressings ahead of formal guideline updates, attracted by reduced biofilm formation compared to traditional silver-based alternatives. This technology is expanding into outpatient settings previously restricted to systemic antibiotic therapy, enabling earlier hospital discharge.
EMA's Medical Device Regulation is tightening post-market surveillance requirements for skin substitutes and bioactive dressings marketed in European Union member states. Manufacturers must now submit periodic safety update reports and maintain vigilance systems capable of tracking device performance across distributed healthcare networks. Small and mid-sized wound care companies with limited regulatory affairs capacity are outsourcing compliance functions or withdrawing from EU markets entirely.
Accountable care organizations in United States Medicare programs are unbundling wound care supplies from procedure reimbursement, creating direct purchasing relationships with manufacturers that bypass traditional distributor markups. Hospital systems in Texas and Florida are negotiating multi-year sole-source agreements for advanced dressing portfolios, exchanging volume commitments for price protection and clinical training support. This restructuring concentrates procurement power among integrated delivery networks with sufficient patient volume to justify dedicated supply chain infrastructure.
Global Diabetic Foot Ulcers Market Segmentation
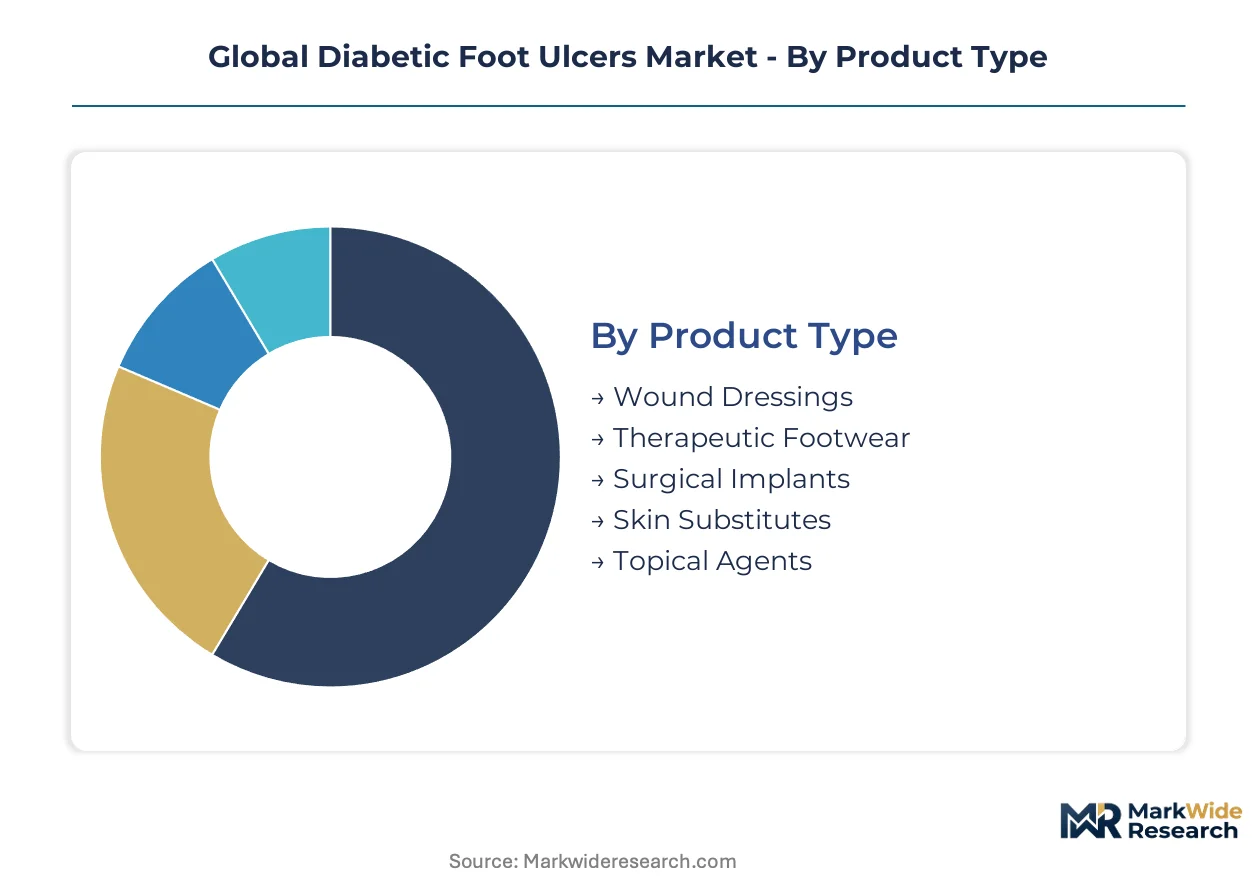
Product differentiation in diabetic foot ulcer management separates high-margin bioactive technologies from commodity consumables, with procurement bundling increasingly collapsing multiple categories into episode-based contracts that reward healing outcomes over unit volume.
Product Type:
Wound dressings dominate unit volume while skin substitutes command the steepest price premiums per procedure.
- Wound Dressings:Foam, hydrocolloid, alginate, and antimicrobial formulations provide moisture balance and infection control across Wagner grades 1-4. Hospital systems in the United States and Germany are consolidating annual contracts for advanced dressing portfolios that include silver-impregnated and PHMB-based alternatives.
- Skin Substitutes:Cellular and tissue-based products derived from human dermis, porcine collagen, or bioengineered matrices close recalcitrant wounds refractory to standard care. Academic medical centers in Japan and specialized limb salvage clinics in Bavaria drive adoption of bilayer living cellular constructs despite reimbursement variability.
- Therapeutic Footwear:Custom-molded depth-inlay shoes and pressure-relief orthotics prevent ulcer recurrence in neuropathic patients. Medicare therapeutic shoe program reimbursement sustains volume in United States retail and podiatry channels.
- Surgical Implants:Internal fixation hardware and external fixation systems stabilize Charcot foot deformities and enable limb-sparing procedures. Orthopedic and podiatric surgical suites in metropolitan Tokyo and Dallas-Fort Worth health networks concentrate demand.
- Topical Agents:Growth factors, collagenase ointments, and antimicrobial solutions complement dressing protocols for infected or necrotic wounds. Outpatient wound centers in Florida and North Rhine-Westphalia prescribe these adjuncts within standardized order sets.
Today's leader: Wound Dressings. Tomorrow's challenger: Skin Substitutes.
Application:
Prevention and tissue regeneration sit at opposite ends of the clinical value chain, with the former capturing population-scale volume and the latter delivering per-patient margin concentration.
- Ulcer Prevention:Risk stratification protocols, offloading interventions, and patient education programs target high-risk diabetic populations before tissue breakdown occurs. United States accountable care organizations and German statutory health insurance disease management programs fund preventive services that reduce downstream amputation costs.
- Tissue Regeneration:Advanced biologics, cellular therapies, and bioactive scaffolds accelerate closure in chronic wounds exceeding twelve weeks. University hospital networks in Sweden and specialized wound centers in Osaka prefecture are expanding regenerative medicine protocols ahead of formal reimbursement expansion.
- Debridement:Surgical, enzymatic, autolytic, and biologic methods remove necrotic tissue to prepare wound beds for healing. Outpatient clinic volume in Texas and Florida supports dedicated debridement service lines.
- Infection Control:Topical antimicrobials, systemic antibiotics, and biofilm-disrupting technologies manage bacterial colonization in Wagner grade 2-4 ulcers. FDA and EMA post-market surveillance requirements are tightening evidence standards for antimicrobial claims.
- Pressure Redistribution:Total contact casting, removable cast walkers, and specialized mattresses eliminate mechanical stress from weight-bearing surfaces. Home healthcare providers in Japan and long-term care facilities in the United Kingdom are adopting portable offloading systems.
Prevention absorbs the largest patient population. Tissue regeneration claims the fastest margin expansion.
End User:
Site-of-care migration is redistributing volume from inpatient surgical suites toward outpatient and home settings where reimbursement favors lower-acuity management.
- Hospitals:Academic medical centers and community hospitals manage complex Wagner grade 3-4 ulcers, osteomyelitis, and limb salvage procedures. Bundled payment models in United States Medicare programs are compressing length of stay and pushing stable cases to outpatient settings.
- Home Healthcare Providers:Skilled nursing visits and portable negative pressure systems enable wound management outside institutional walls. Medicare home health prospective payment system revisions are expanding episode-based reimbursement for diabetic foot care in rural United States markets.
- Specialty Clinics:Multidisciplinary diabetic foot clinics combine podiatry, vascular surgery, infectious disease, and wound nursing expertise. Germany's limb salvage center network and Japan's metropolitan outpatient wound hubs concentrate advanced dressing and graft consumption.
- Long-Term Care Facilities:Nursing homes and assisted living settings manage lower-extremity wounds in frail elderly populations with limited mobility. Staffing constraints and formulary limitations restrict adoption of complex dressing protocols in these environments.
Hospitals retain the highest acuity cases. Home healthcare providers are expanding their addressable patient base fastest.
Treatment Technology:
Device-based modalities command capital investment and recurring consumable revenue, creating stickier supplier relationships than pharmaceutical alternatives.
- Negative Pressure Wound Therapy:Vacuum-assisted closure systems remove exudate, reduce edema, and promote granulation tissue formation through mechanotransduction. Portable battery-powered units from Smith & Nephew and ConvaTec are displacing institutional systems in United States and European home care markets.
- Growth Factor Therapy:Recombinant human platelet-derived growth factor and epidermal growth factor preparations stimulate cellular proliferation in chronic wounds. FDA PMA pathway requirements limit competition to established manufacturers with completed clinical trials.
- Hyperbaric Oxygen Therapy:Pressurized chamber sessions increase tissue oxygen tension in ischemic wounds with compromised perfusion. United States hospital-based wound centers and German outpatient hyperbaric facilities maintain dedicated suites for diabetic foot indications.
- Electrical Stimulation:Low-intensity direct current and pulsed electromagnetic field devices modulate cellular activity and enhance wound healing. Physical therapy and wound clinic adoption in Japan and Australia is expanding beyond post-surgical applications.
Negative pressure wound therapy owns the installed base. Growth factor therapy is climbing the fastest toward mainstream protocol inclusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern diabetic foot ulcer management industry traces its clinical foundations to limb salvage programs established in United States academic medical centers during the 1980s, with subsequent protocol standardization spreading through German and Japanese healthcare systems in the following decades.
United States
Medicare bundled payment expansion for lower extremity episodes concentrates procurement power among integrated delivery networks in Texas and Florida. FDA 510(k) and PMA pathways shape commercialization timelines for cellular skin substitutes seeking market access. Metropolitan wound centers in Dallas-Fort Worth and Houston anchor advanced dressing consumption for complex Wagner grade 3-4 ulcers.
Germany
Statutory health insurance disease management programs fund preventive foot screening that reduces downstream amputation costs across diabetic populations. EMA medical device regulation and MDR conformity requirements impose biocompatibility obligations on dressing suppliers serving EU markets. Specialized limb salvage centers in Bavaria and North Rhine-Westphalia generate standardized referral pathways for bioactive grafts and advanced wound protocols.
Japan
Metropolitan Tokyo and Osaka healthcare networks are expanding outpatient wound centers with limited domestic advanced dressing production capacity. PMDA regulatory frameworks govern approval pathways for imported skin substitutes and negative pressure systems. Academic medical centers in Kansai region are adopting regenerative medicine protocols ahead of formal reimbursement expansion for cellular therapies.
United Kingdom
NHS integrated care systems are consolidating wound care spend into regional procurement frameworks that reward healing outcomes over unit volume. MHRA post-Brexit regulatory alignment with EU MDR creates transitional certification requirements for dressing manufacturers. Mölnlycke Health Care AB maintains direct channel control across Nordic and British hospital purchasing through sustained clinician education investments.
Sweden
University hospital networks in Stockholm and Gothenburg are adopting antimicrobial peptide dressings ahead of formal guideline updates for infected Wagner grade 3-4 ulcers. The country's national pharmaceutical regulator enforces vigilance systems for medical device performance tracking across distributed healthcare networks. Academic medical centers anchor bioactive dressing adoption that is expanding into outpatient settings previously restricted to systemic antibiotic therapy.
Global Diabetic Foot Ulcers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology-evidence spectrum, with bioactive and cellular products commanding price multiples over basic hydrocolloid and foam alternatives. The vendor base clusters around three strategic archetypes: integrated advanced wound management portfolios, specialized ostomy-wound hybrid expertise, and focused skin substitute biologics. M&A activity concentrates on cellular and tissue-based product capabilities, while geographic expansion targets Japan's import-dependent outpatient wound center networks.
Within the integrated portfolio tier, Smith & Nephew Plc and ConvaTec Group Plc exemplify divergent competitive positions. Smith & Nephew Plc, a UK-based public limited company, anchors large accountable care organization contracts through bundled advanced wound management offerings. ConvaTec Group Plc, similarly UK-structured, competes through specialized ostomy and wound care expertise extending into diabetic foot protocols across European national health systems. Mölnlycke Health Care AB, a Swedish aktiebolag, occupies a distinct position through direct channel control and clinician education investments dominating Nordic and British hospital purchasing.
| Leading Market Players |
|---|
| Smith & Nephew Plc |
| ConvaTec Group Plc |
| 3M Health Care |
| Coloplast A/S |
| Mölnlycke Health Care AB |
| B. Braun Melsungen AG |
| Organogenesis Inc. |
| Integra LifeSciences |
| Medline Industries |
| Others |
Supply & Pricing Matrix
EU MDR post-market surveillance mandates now gate qualified supply access for advanced wound care manufacturers, with compliance investments separating premium-tier pricing from commodity alternatives as hospitals consolidate procurement around validated suppliers.
Pricing Analysis
Episode-based bundled contracts now dominate hospital procurement, with pricing stratifying across premium bioactive grafts, standard antimicrobial dressings, and economy hydrocolloid tiers. Price differentiation hinges on FDA PMA certification status and clinical evidence depth, with silver-impregnated formulations facing compression from PHMB alternatives. Cost compression in the commodity tier is intensifying because low-cost Asian manufacturers flood institutional segments. Home healthcare providers exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to outcome-based reimbursement incentives.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan operate hub-and-spoke patterns that position inventory within 48 hours of metropolitan wound centers. Manufacturing concentrates in Ireland, Sweden, and the United States for sterile dressing production, with porcine collagen sourcing anchored in agricultural processing networks across Denmark and the Netherlands. Supply chain risk centers on single-source vulnerability for recombinant human protein inputs used in antimicrobial peptide synthesis. Distribution runs through specialized medical-surgical distributors with cold-chain capabilities for cellular products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Diabetic Foot Ulcers Market functions as a stable compounder, with aging diabetic populations across developed economies providing non-discretionary demand that resists cyclical downturns.
For Market Incumbents: Cement dominance in bundled payment corridors by deepening direct hospital system partnerships and securing sole-source agreements with integrated delivery networks in Texas and Florida. Invest in backward integration into recombinant protein manufacturing to offset raw material volatility threatening antimicrobial dressing margins. Prioritize M&A targeting cellular therapy platforms to defend against emerging biologics entrants. For New Entrants and Emerging Players: Telehealth platform partnerships offer the lowest-friction route to patient access, bypassing entrenched distributor relationships that lock out small manufacturers. Target Japan's metropolitan outpatient wound centers, where limited domestic production creates import demand for European and North American suppliers. Pursue white-label arrangements with home healthcare agencies seeking differentiated dressing portfolios for Medicare home health episodes. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized wound care specialists because EU MDR compliance costs are forcing sub-scale competitors toward exit, creating consolidation opportunities at reasonable multiples. Cellular and tissue-based product capabilities command scarcity premiums within the 5-10 year window as regenerative medicine protocols expand. Monitor FDA digital health guidance for remote patient monitoring as the signal indicating when temperature-sensing dressing platforms will achieve reimbursement parity with traditional modalities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR notified body scarcity creates first-mover advantage for manufacturers with established conformity partnerships. |
| Hospital System Partnership | Multi-year sole-source agreements with Texas and Florida integrated delivery networks bypass traditional distributor markups. |
| Software Companion Development | Cloud-based wound tracking platforms enable subscription revenue models for temperature-sensing dressing manufacturers. |
| Reimbursement Strategy | Medicare bundled payment alignment secures preferred positioning within episode-based procurement frameworks. |
| FDA Submission | PMA pathway completion for cellular skin substitutes locks out competitors lacking clinical evidence capacity. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Sweden, with primary inputs from each market combining structured interviews with wound care clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation draws from FDA 510(k) and PMA filings, EMA medical device registration databases, CMS Medicare claims data, and hospital procurement contract disclosures. Bottom-up patient volume modeling triangulates against top-down healthcare expenditure analysis.
Granularity extends to product type, application, end user, and treatment technology dimensions, with additional modeling of reimbursement pathway clusters across regional regulatory frameworks. CAGRs derive from fitted trend analysis calibrated to historical episode volume trajectories and projected diabetic population incidence curves. Forecast inputs incorporate negative pressure wound therapy adoption curves and skin substitute reimbursement expansion assumptions across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for antimicrobial peptide dressings would alter the outlook if clinical guideline updates accelerate ahead of projected timelines. Forecasts reflect documented assumptions regarding bundled payment expansion velocity and MDR compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Acute Wound Care Market
Wound Care
Wound Healing Market
Wound Care
Wound Retractor Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Surgical Wound Care Market
Wound Care
Italy Wound Care Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Wound Care Centers Market