
 Optic Neuritis Treatment Market | 2026-2036
Optic Neuritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Optic Neuritis Treatment Market Analytics
Combination therapy bundling is recalibrating how payers and clinicians evaluate acute versus maintenance protocols. Novartis AG leverages its immunology infrastructure to sustain access across specialty clinic networks. Mallinckrodt Pharmaceuticals anchors hospital formularies with corticosteroid supply chain reliability. Genentech competes on neuro-ophthalmology protocol development through academic medical center partnerships.
Optic neuritis treatment encompasses pharmacological and procedural interventions targeting inflammatory demyelination of the optic nerve, with high-dose intravenous methylprednisolone remaining the standard acute intervention to accelerate visual recovery. The primary purpose is to reduce axonal damage, restore visual acuity, and prevent progression to multiple sclerosis in seropositive patients. Corticosteroids occupy the largest revenue share due to entrenched emergency department protocols and generic cost structures. Monoclonal antibodies represent the fastest-expanding segment as anti-CD20 and anti-IL-6 pathways demonstrate efficacy in preventing recurrent attacks. Intravenous therapy dominates treatment method revenue, though homecare oral maintenance protocols are gaining protocol acceptance for stable patients.
FDA neurodegenerative disease guidance and EMA's multiple sclerosis therapeutic guidelines shape trial endpoints and labeling requirements for new entrants. The country's national pharmaceutical regulator in Japan, PMDA, imposes distinct biomarker validation standards that delay parallel submissions. Stakeholders must monitor evolving blood-brain barrier penetration claims and real-world evidence requirements that will determine formulary positioning without regard to calendar milestones.
Market Dynamics
The convergence of blood-brain barrier penetration technologies with adaptive trial designs is compressing development timelines for neuroprotective candidates while forcing established corticosteroid protocols into defensive positioning.
Growth Catalysts
- FDA Neurodegenerative Disease Guidance:Streamlined endpoints for visual function preservation accelerate approval pathways for first-in-class therapies targeting axonal protection.
- Specialty Clinic Networks:Concentrated referral patterns in the United States, Germany, and Japan create predictable patient funneling for protocol-driven interventions.
- Anti-CD20 Monoclonal Antibodies:Prophylactic administration protocols demonstrate sustained prevention of recurrent optic neuritis episodes in seropositive cohorts.
Market Restraints
- Plasma-Derived Biologics Supply:Fractionation capacity constraints in North American and European collection networks limit scalable production of immunoglobulin-based alternatives.
- PMDA Biomarker Validation Requirements:Japan's distinct evidentiary standards for neuroimaging surrogates delay parallel submission strategies and fragment development budgets.
- Generic Corticosteroid Price Compression:Methylprednisolone commoditization in emergency department formularies erodes margin recovery for acute episode management.
Strategic Opportunities
- Homecare Oral Maintenance Protocols:Stable patient cohorts in the United States and Germany are transitioning from intravenous infusion centers to supervised home administration models.
- Real-World Evidence Mandates:EMA's expanded acceptance of registry-derived safety data reduces reliance on placebo-controlled trial infrastructure for label extensions.
- Neuro-Ophthalmology-AI Convergence:Automated perimetry interpretation tools are integrating with electronic health record systems to compress diagnostic-to-treatment intervals.
Industry Challenges
- Neuro-Ophthalmology Fellowship Pipeline:Subspecialty training program contraction in the United States and Germany concentrates diagnostic expertise in academic medical centers.
- Multi-Site Trial Coordination:Heterogeneous MRI acquisition protocols across European investigative sites introduce variability into optic nerve atrophy endpoint measurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optic Neuritis Treatment Market |
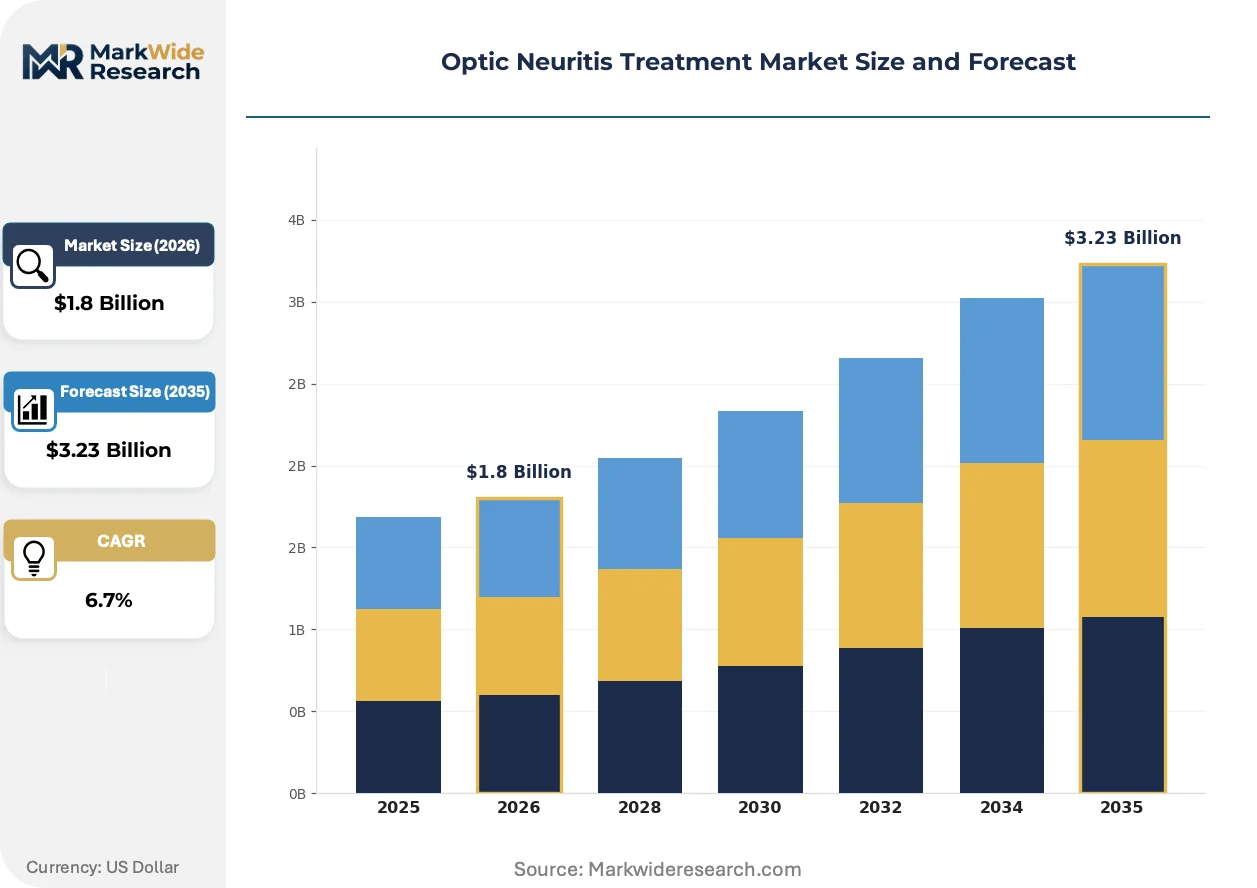
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Immunomodulators, Monoclonal Antibodies, Plasma Exchange Treatment Method: Intravenous Therapy, Oral Therapy, Combination Therapy, Supportive Care End User: Hospitals, Specialty Clinics, Homecare, Rehabilitation Centers Patient Age Group: Pediatric, Adult, Geriatric, Adolescent |
| Companies Covered | Mallinckrodt Pharmaceuticals, Novartis AG, Teijin Pharmaceutical Limited, AbbVie, AdvaCare Pharma, Santen Pharmaceuticals, Trethera Corporation, Genentech, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optic Neuritis Treatment Market Evolving Landscape
Neuroprotective agent development is accelerating as blood-brain barrier engineering and biomarker validation converge to challenge corticosteroid dominance in acute episode management.
Extended-release methylprednisolone formulations are integrating depot delivery mechanisms that sustain therapeutic concentrations across 72-hour windows. Academic medical centers in Germany and Japan are adopting these platforms to reduce nursing burden in infusion suites. The technology is integrating corticosteroid administration into outpatient settings previously reserved for observation protocols.
EMA's Multiple Sclerosis Therapeutic Guidelines revision introduced visual evoked potential as a co-primary endpoint for neuroprotective label claims. Pharmaceutical developers must now demonstrate statistically significant latency improvement alongside traditional acuity metrics. European trial sponsors are responding by retrofitting existing protocols with standardized electrophysiology equipment.
Hospital procurement committees are unbundling acute episode management from longitudinal multiple sclerosis care contracts. United States specialty pharmacy networks are capturing stable patients previously retained within hospital-owned infusion centers. This disintermediation concentrates in markets where managed care organizations operate captive specialty pharmacy assets.
Optic Neuritis Treatment Market Segmentation
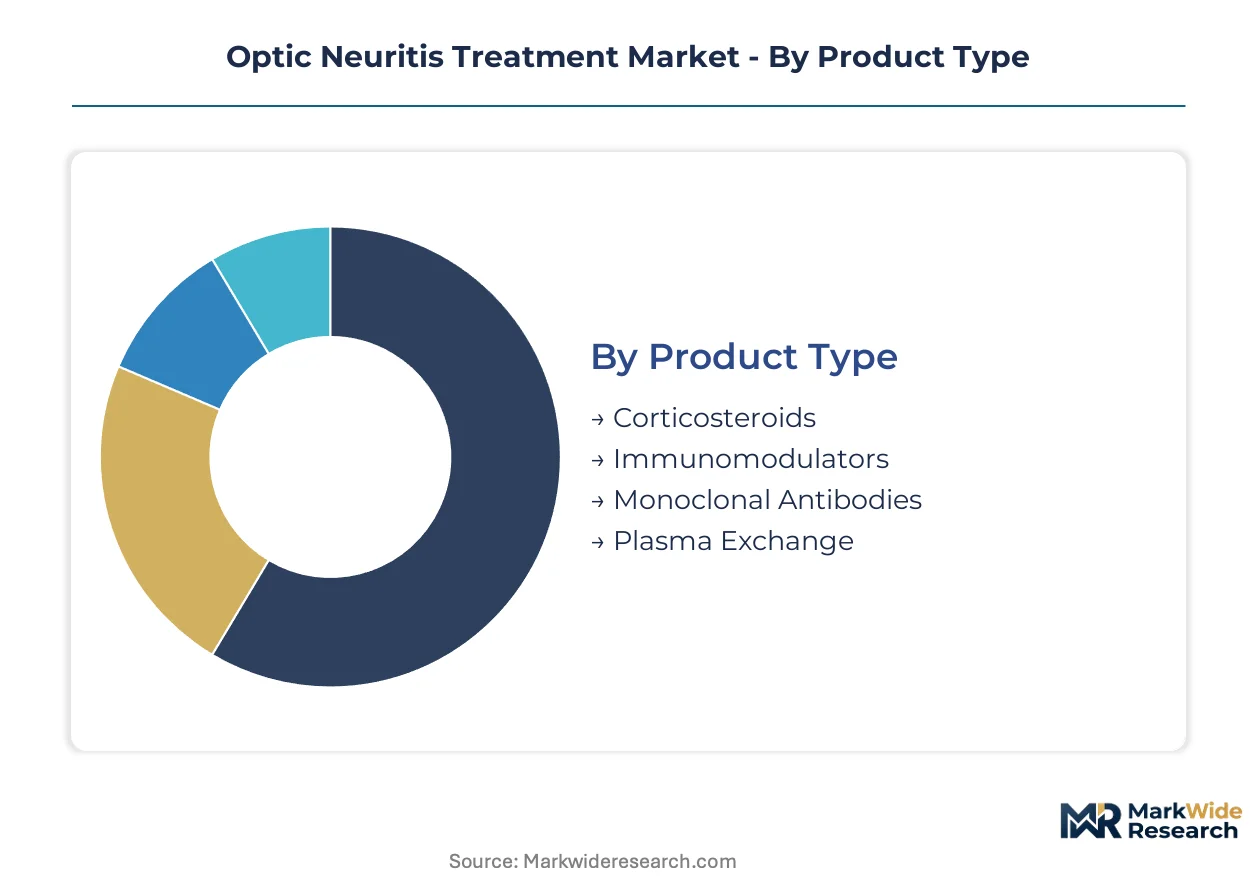
Optic neuritis treatment protocols fragment across pharmacological classes, delivery modalities, and care settings. Understanding segment boundaries clarifies where development budgets concentrate and which patient cohorts drive protocol evolution.
Product Type:
Replacement cycles in acute episode management are shortening as neuroprotective candidates challenge corticosteroid protocols that have dominated emergency departments for decades.
- Corticosteroids:High-dose intravenous methylprednisolone remains the emergency department standard for acute demyelinating attacks. Hospital formularies in the United States and Germany anchor procurement around generic cost structures and established nursing protocols.
- Monoclonal Antibodies:Anti-CD20 and anti-IL-6 pathway agents are displacing corticosteroids for recurrent attack prevention in seropositive multiple sclerosis patients. Specialty clinic networks in Japan concentrate demand for these prophylactic protocols.
- Immunomodulators:Small-molecule agents targeting sphingosine-1-phosphate receptors offer oral maintenance alternatives to infusion-dependent biologics.
- Plasma Exchange:Apheresis protocols serve corticosteroid-refractory cases through tertiary referral centers with specialized collection infrastructure.
Corticosteroids sit at the top of the volume ranking, with monoclonal antibodies climbing the fastest.
Treatment Method:
Cost tier differentiation separates acute intervention from longitudinal maintenance, with reimbursement structures dictating site-of-care migration.
- Intravenous Therapy:Hospital-based infusion suites deliver methylprednisolone and biologics under observation protocols. Academic medical centers in Germany and the United States concentrate this capacity.
- Combination Therapy:Bundled acute corticosteroid administration with subsequent monoclonal antibody prophylaxis is reshaping payer evaluation frameworks. Managed care organizations in the United States favor these protocols for reduced hospital readmission rates.
- Oral Therapy:Home-based maintenance regimens reduce nursing burden for stable patients with confirmed multiple sclerosis diagnoses.
- Supportive Care:Visual rehabilitation and low-vision services address residual functional deficits outside pharmacological intervention.
Intravenous therapy commands the highest reimbursement per episode, though oral protocols are gaining share fastest in stable cohorts.
End User:
Customer type concentration determines distribution infrastructure requirements and regulatory compliance burdens across the care continuum.
- Hospitals:Emergency departments and neurology services manage acute optic neuritis episodes through established corticosteroid protocols. United States hospital systems anchor volume through bundled payment structures.
- Specialty Clinics:Neuro-ophthalmology and multiple sclerosis centers in Germany and Japan coordinate longitudinal care and clinical trial access.
- Homecare:Supervised oral maintenance and subcutaneous biologic administration are migrating stable patients from infusion centers. Specialty pharmacy networks in the United States capture this disintermediation.
- Rehabilitation Centers:Visual therapy services address persistent deficits in patients with incomplete recovery from initial attacks.
Hospitals retain the highest episode volume, with homecare expanding most quickly as site-of-care economics shift.
Patient Age Group:
Application requirements vary sharply across developmental stages, with pediatric protocols demanding specialized formulation and dosing validation.
- Adult:Patients aged 18-55 represent the core demographic for multiple sclerosis-associated optic neuritis. Clinical trial infrastructure concentrates on this cohort for regulatory submission.
- Pediatric:Acute demyelinating encephalomyelitis and pediatric multiple sclerosis drive distinct formulation requirements. PMDA and FDA pediatric investigation plans impose additional evidentiary standards.
- Adolescent:Transitional care protocols bridge pediatric and adult service lines, with adherence challenges distinct from younger or older cohorts.
- Geriatric:Ischemic optic neuropathy and giant cell arteritis masquerade as inflammatory demyelination, requiring diagnostic discrimination protocols.
Adult patients dominate trial enrollment and commercial volume, with pediatric indications representing the steepest regulatory climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-dose corticosteroid protocols for acute demyelinating optic neuritis first achieved scale in United States academic medical centers during the 1980s. Germany and Japan subsequently developed parallel specialist networks that now concentrate global clinical trial infrastructure. Regulatory divergence across FDA, EMA, and PMDA pathways shapes where neuroprotective candidates launch first.
United States
Multiple sclerosis-associated optic neuritis drives referrals to neuro-ophthalmology centers in Boston, Baltimore, and San Francisco. FDA neurodegenerative disease guidance streamlines visual function preservation endpoints for axonal protection therapies. Managed care organizations in California and New York operate captive specialty pharmacy assets that disintermediate hospital infusion centers for stable patients.
Germany
Bundled payment structures in North Rhine-Westphalia and Bavaria anchor hospital procurement of acute corticosteroid protocols. EMA multiple sclerosis therapeutic guidelines mandate visual evoked potential as a co-primary endpoint, forcing trial sponsors to retrofit electrophysiology equipment across Munich and Heidelberg sites. Extended-release methylprednisolone depot formulations are migrating administration from infusion suites to outpatient settings in Berlin.
Japan
PMDA biomarker validation requirements for neuroimaging surrogates delay parallel submission strategies for neuroprotective candidates. Tokyo and Osaka academic medical centers concentrate demand for anti-CD20 prophylactic protocols in seropositive multiple sclerosis patients. The country's national pharmaceutical regulator imposes distinct evidentiary standards that fragment development budgets across Kanto and Kansai clusters.
United Kingdom
NHS England neuro-ophthalmology referral pathways concentrate diagnostic expertise in London, Oxford, and Manchester teaching hospitals. MHRA alignment with EMA guidelines accelerates label recognition for monoclonal antibody prophylaxis. Scottish multiple sclerosis registry data supports real-world evidence submissions for maintenance therapy extensions.
Switzerland
Swissmedic's streamlined authorization procedures attract European trial sponsors seeking early market access for blood-brain barrier penetration technologies. Basel and Zurich host contract research organizations coordinating multi-site MRI standardization across Alpine investigative sites. The country's precision medicine infrastructure supports biomarker-stratified enrollment for neuroprotective candidates.
Optic Neuritis Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the acute-to-maintenance care continuum, with neuroprotective developers commanding valuation multiples above generic corticosteroid suppliers. The vendor base organizes around three archetypes: diversified immunology platforms, hospital formulary anchors, and neuro-ophthalmology protocol specialists. Consolidation pressures concentrate in the monoclonal antibody segment where anti-CD20 and anti-IL-6 pathways compete for prophylactic positioning. Dominant competitive moves include strategic partnerships with academic medical centers and portfolio diversification into homecare oral maintenance.
Within the diversified immunology tier, Novartis AG and AbbVie occupy positions spanning multiple sclerosis and broader autoimmune portfolios. Mallinckrodt Pharmaceuticals anchors hospital formulary relationships through corticosteroid supply chain reliability. Genentech sits within the neuro-ophthalmology protocol development segment, leveraging academic medical center partnerships. Pfizer represents the scale-driven pharmaceutical archetype with cross-therapeutic area infrastructure. Teijin Pharmaceutical Limited exemplifies the Japan-focused specialist model addressing PMDA-specific evidentiary requirements.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Novartis AG |
| Teijin Pharmaceutical Limited |
| AbbVie |
| AdvaCare Pharma |
| Santen Pharmaceuticals |
| Trethera Corporation |
| Genentech |
| Pfizer |
| Others |
Value Network & Pricing Analysis
Neuro-ophthalmology fellowship concentration in Boston, Baltimore, and San Francisco creates labor-cost differentials that widen pricing spreads between academic medical centers and community hospital networks. Corticosteroid administration protocols in Germany and Japan command premium reimbursement rates due to specialized nursing certification requirements, while generic methylprednisolone commoditization in United States emergency departments compresses margins at the economy tier.
Pricing Analysis
Three-tier pricing structure across premium neuroprotective agents, standard monoclonal antibody prophylaxis, and economy generic corticosteroids separates acute episode management from longitudinal care. Price differentiation rests on FDA breakthrough therapy designation status and blood-brain barrier penetration claims. Cost compression in the corticosteroid tier intensifies because hospital procurement committees unbundle acute management from MS care contracts. Community hospitals exhibit highest price sensitivity; academic medical centers with captive specialty pharmacy assets show lowest.
Supply Chain Analysis
Reverse logistics for refrigerated biologics and corticosteroid vial returns flow through specialty pharmacy networks in the United States and Germany. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for corticosteroid precursors and monoclonal antibody cell lines. Finished formulation draws from Italian, Irish, and Singaporean fill-finish facilities. Single-source vulnerability in plasma-derived immunoglobulin fractionation threatens prophylactic protocol availability. Distribution runs through hospital-owned infusion centers, specialty clinic direct purchasing, and homecare pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in optic neuritis treatment hinges on neuroprotective agent premiumization displacing commodity corticosteroid protocols, with blood-brain barrier engineering reducing manufacturing cost intensity for second-generation candidates.
For Market Incumbents: Cement formulary anchoring through extended-release methylprednisolone depot formulations that reduce nursing burden and outpatient migration. Fortify anti-CD20 prophylactic positioning against anti-IL-6 pathway challengers by deepening academic medical center partnership density in Tokyo and Osaka. Vertical integration into biomarker validation services addresses PMDA evidentiary fragmentation. For New Entrants and Emerging Players: Homecare oral maintenance patients in United States managed care networks represent the most penetrable buyer archetype for subcutaneous biologic alternatives. Pediatric acute demyelinating encephalomyelitis indications offer white-space positioning given FDA and PMDA pediatric investigation plan requirements that deter established players. Pursue EMA real-world evidence pathway acceptance for registry-derived safety submissions to compress trial infrastructure requirements. For Investors and Strategic Acquirers: Diversified immunology platforms with existing multiple sclerosis infrastructure are the most active acquirer in this space, seeking neuro-ophthalmology protocol development capabilities. Five-to-ten year viability favors developers with blood-brain barrier penetration platforms and parallel FDA-EMA-PMDA submission strategies. Monitor visual evoked potential endpoint standardization across European trial sites as inflection indicator for neuroprotective label claim feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Neuroprotective Clinical Trial Advancement | FDA neurodegenerative disease guidance streamlines visual function preservation endpoints for axonal protection therapies. |
| Extended-Release Formulation Development | Depot delivery mechanisms sustain therapeutic concentrations across 72-hour windows in German outpatient settings. |
| Academic Medical Center Partnership | Concentrated referral patterns in Boston, Baltimore, and San Francisco create predictable patient funneling infrastructure. |
| Real-World Evidence Registry Investment | EMA expanded acceptance of registry-derived safety data reduces placebo-controlled trial infrastructure reliance. |
| Specialty Pharmacy Network Acquisition | United States managed care captive assets disintermediate hospital infusion centers for stable patient cohorts. |
Research Methodology
Multiple input streams — neuro-ophthalmology fellowship program directors, hospital pharmacy procurement managers, specialty clinic formulary directors, and payer access specialists — were reconciled against FDA filings, EMA submission documents, ClinicalTrials.gov protocols, and Japanese PMDA review reports. Secondary validation drew from hospital procurement databases, GPO contracts, and CMS Medicare reimbursement data. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates across treatment method, product type, and end user dimensions.
Cross-referencing historical corticosteroid protocol adoption curves against expert panel input on neuroprotective candidate penetration shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include pharmacological class, delivery modality, care setting, and regional regulatory cluster. CAGRs were derived from patent expiry timelines, biosimilar entry assumptions, and site-of-care migration elasticity. Blood-brain barrier penetration technology maturation and anti-CD20 versus anti-IL-6 pathway competition intensity served as key forecast inputs.
Underlying measurement precision varies by segment; intravenous therapy and adult patient cohorts carry tighter precision than pediatric indications and plasma exchange protocols. Forecasts reflect assumptions regarding PMDA biomarker validation timeline convergence with FDA standards and EMA visual evoked potential endpoint adoption. Practitioners should monitor MRI acquisition protocol standardization progress across European investigative sites and homecare oral maintenance reimbursement policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Moyamoya Disease Market
Neurology
Neurology Devices Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Movement Disorder Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Chronic Brain Damage Management Market
Neurology
Netherlands Neurology Devices Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
North America Neurology Monitoring Market
Neurology
Global Acoustic Neuroma Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Acute Repetitive Seizures Market
Neurology
Europe Neurology Monitoring Market