
 South Korea Wound Care Market | 2026-2036
South Korea Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Wound Care Market Insights
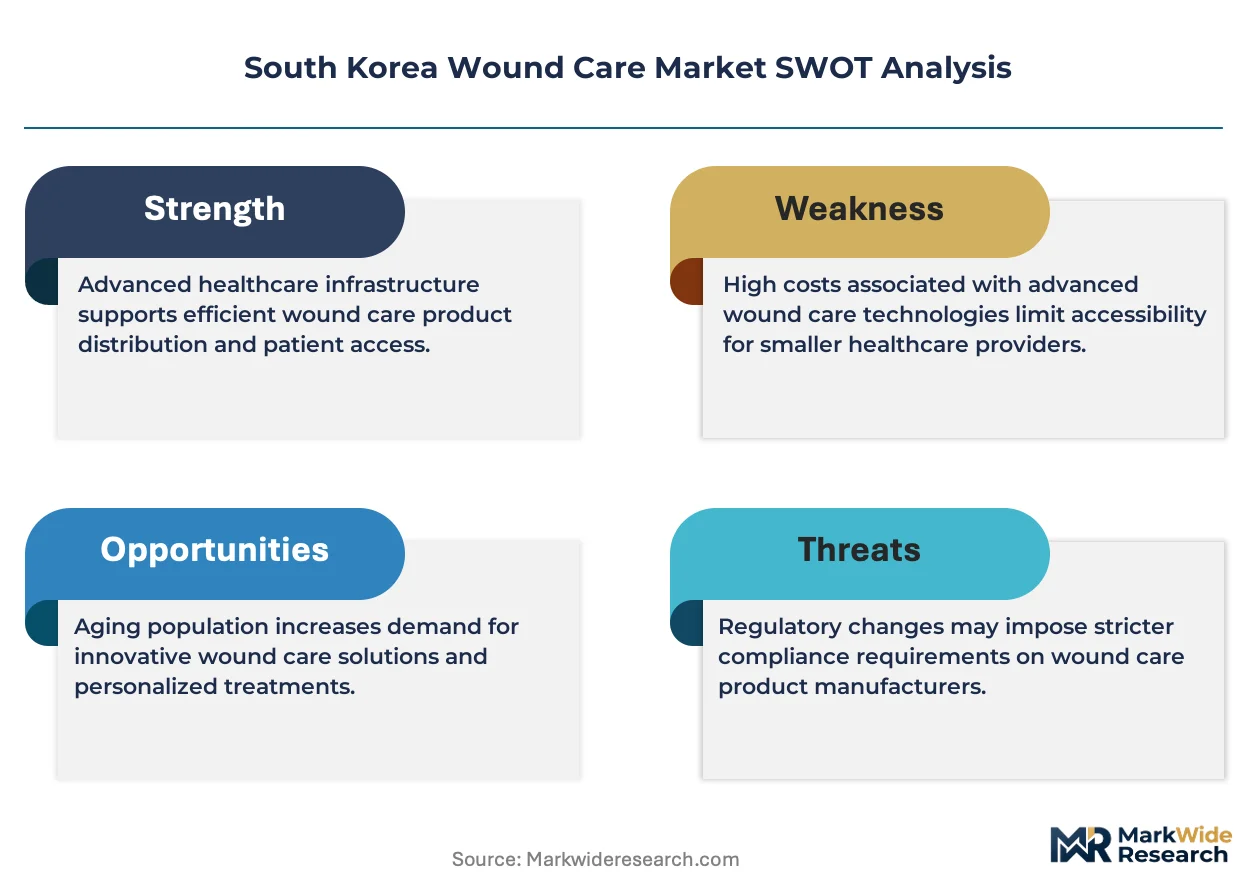
Advanced antimicrobial dressing tiers is bifurcating the competitive landscape between premium absorbency segments and basic gauze alternatives. Smith & Nephew leverages its hydrofiber technology portfolio to sustain leadership in surgical site infection prevention. Coloplast anchors its position through specialized ostomy and wound interface products tailored to Korean hospital protocols. Mölnlycke Health Care differentiates via silicone-adhesive platforms that reduce trauma during dressing changes for burn and chronic wound patients.
Wound care encompasses absorbent and non-absorbent materials, antimicrobial agents, and biologically active substrates engineered to maintain moist healing environments while preventing bacterial colonization across partial- and full-thickness tissue defects. These products serve to accelerate re-epithelialization, manage exudate, and reduce complications in post-operative, diabetic, and pressure injury pathways. Dressing formats command the deepest margin pools due to recurring consumption and upgrade cycles from basic cotton to hydrocolloid and alginate constructions. Chronic wound applications represent the fastest-expanding addressable space as Korea's diabetic population drives demand for long-term ambulatory management protocols.
MFDS medical device registration requirements shape product entry timelines and clinical evidence standards for novel wound healing technologies distributed through Korean channels. The Korean Ministry of Food and Drug Safety enforces Good Manufacturing Practice audits that filter out lower-tier suppliers from hospital tender participation. KFDA-equivalent biocompatibility testing protocols align with ISO 10993 frameworks to ensure cytotoxicity and sensitization benchmarks for dermal-contact materials. Stakeholders must monitor reimbursement classification shifts for negative pressure wound therapy and bioengineered skin substitutes as these modalities transition from premium cash-pay to National Health Insurance coverage determinations.
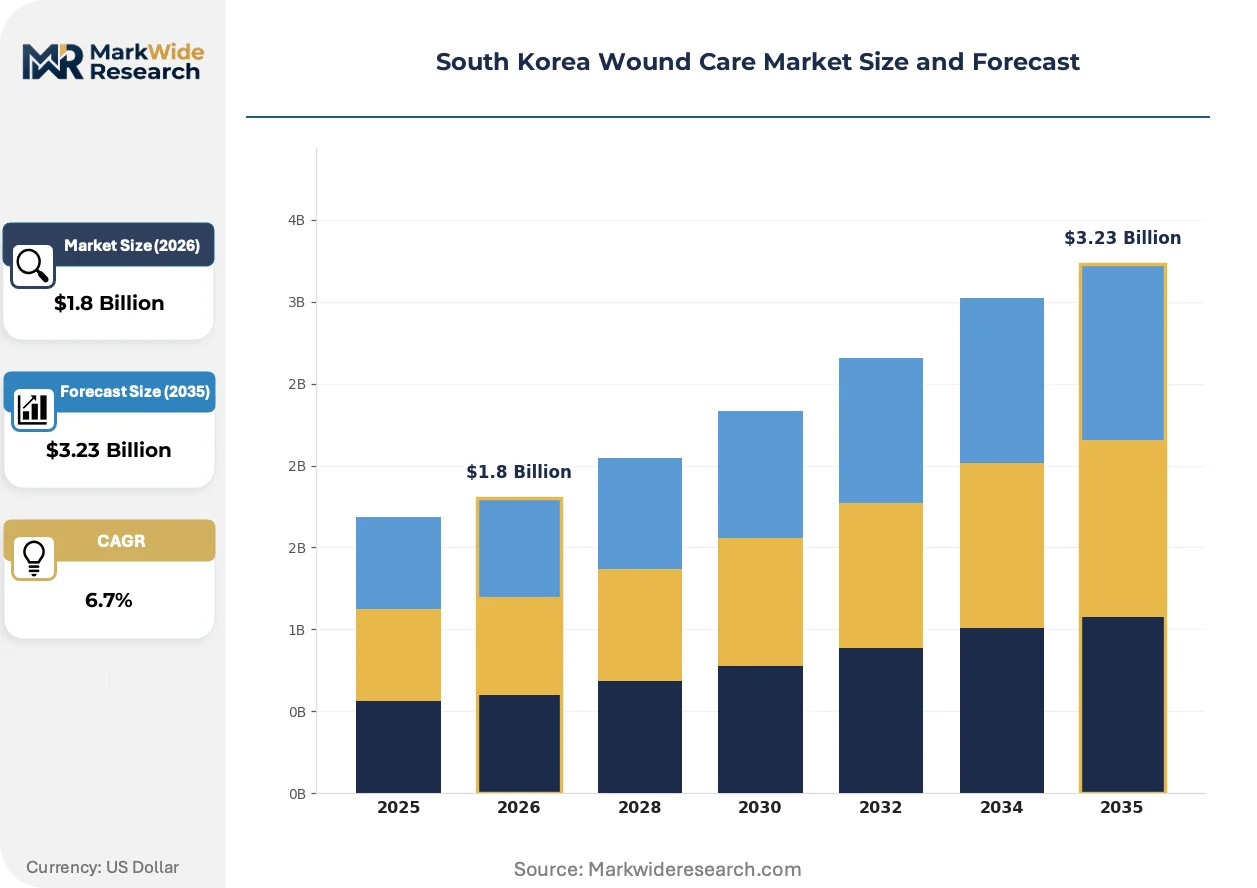
Market Dynamics
MFDS tightening of medical device quality standards is bifurcating hospital procurement tiers, forcing suppliers to choose between premium biologics investment or exit from tertiary care tenders. Seoul's concentration of advanced wound centers concentrates demand for hydrofiber and silicone-adhesive platforms while compressing margins for basic gauze alternatives.
Growth Catalysts
- MFDS GMP Audits:The Korean Ministry of Food and Drug Safety enforces manufacturing practice standards that filter lower-tier suppliers from hospital participation, creating protected margin pools for compliant manufacturers.
- Diabetic Population Expansion:Chronic wound applications in ambulatory protocols are pulling alginate and hydrocolloid consumption as Korea's diabetes burden extends treatment durations beyond acute care episodes.
- Seoul Tertiary Clustering:Concentration of university hospitals in the capital region generates concentrated demand for biologics-enabled healing solutions that accelerate re-epithelialization in complex cases.
Market Restraints
- Biocompatibility Testing Costs:ISO 10993-aligned cytotoxicity and sensitization protocols impose substantial validation burdens on novel dermal-contact materials before MFDS registration.
- Reimbursement Transition Friction:Negative pressure wound therapy and bioengineered skin substitutes remain in cash-pay limbo pending National Health Insurance coverage determinations, constraining volume penetration.
- Advanced Dressing Price Compression:Basic cotton gauze alternatives compete on cost in rural and secondary care settings where procurement budgets limit upgrade cycles to hydrofiber constructions.
Strategic Opportunities
- Busan-Ulsan Manufacturing Belt:Industrial zones outside Seoul offer production cost advantages for silicone-adhesive platform manufacturing serving domestic and export demand.
- Telemedicine Integration:Remote wound monitoring protocols are opening channel innovation for dressing subscription models that pair consumable supply with digital assessment tools.
- Biologics Reimbursement Expansion:Pending National Health Insurance coverage shifts for skin substitutes represent a regulatory tailwind that would convert premium cash-pay segments to reimbursed volume.
Industry Challenges
- Clinical Evidence Generation:MFDS registration timelines for novel healing technologies require prospective trial data that extends product launch cycles and consumes R&D capital.
- Legacy System Integration:Hospital procurement platforms in Korea's fragmented provider landscape resist standardization, forcing suppliers to maintain multiple tender documentation formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Wound Care Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressing, Bandages, Topical Agents, Sutures Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns End User: Hospitals, Clinics, Home Healthcare, Rehabilitation Centers Distribution Channel: Online, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Smith & Nephew, Coloplast, Medtronic, ConvaTec, Johnson & Johnson, Mölnlycke Health Care, 3M, Daewoong Pharmaceutical, Genewel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Wound Care Market Trends and Innovations
Antimicrobial dressing tiers are actively splitting competitive positioning between premium absorbency segments and commodity alternatives. Technology convergence and regulatory recalibration are compressing traditional procurement cycles while elevating clinical evidence requirements.
Silicone-adhesive wound contact layers are displacing traditional acrylic adhesives in burn and chronic wound protocols. Tertiary care centers in Seoul and Daegu are adopting these platforms at accelerated pace due to reduced trauma during dressing changes. This displacement is compressing market share for conventional adhesive technologies while expanding margin pools for trauma-minimizing constructions.
MFDS alignment with MDR-equivalent clinical evidence standards is extending registration timelines for novel wound healing technologies. The industrial consequence is a filtering effect that advantages established suppliers with existing trial infrastructure. Bioengineered skin substitutes and antimicrobial-enabled dressings face the steepest compliance burdens, with manufacturers responding through prospective Korean-site studies.
Hospital procurement consolidation is rotating demand toward integrated supply contracts that bundle advanced dressings with clinical training and outcome monitoring. Group purchasing organizations in the Seoul metropolitan area are displacing fragmented individual hospital tenders. This concentration is most visible in tertiary care networks where standardization protocols favor single-source relationships over multi-vendor fragmentation.
South Korea Wound Care Market Segmentation
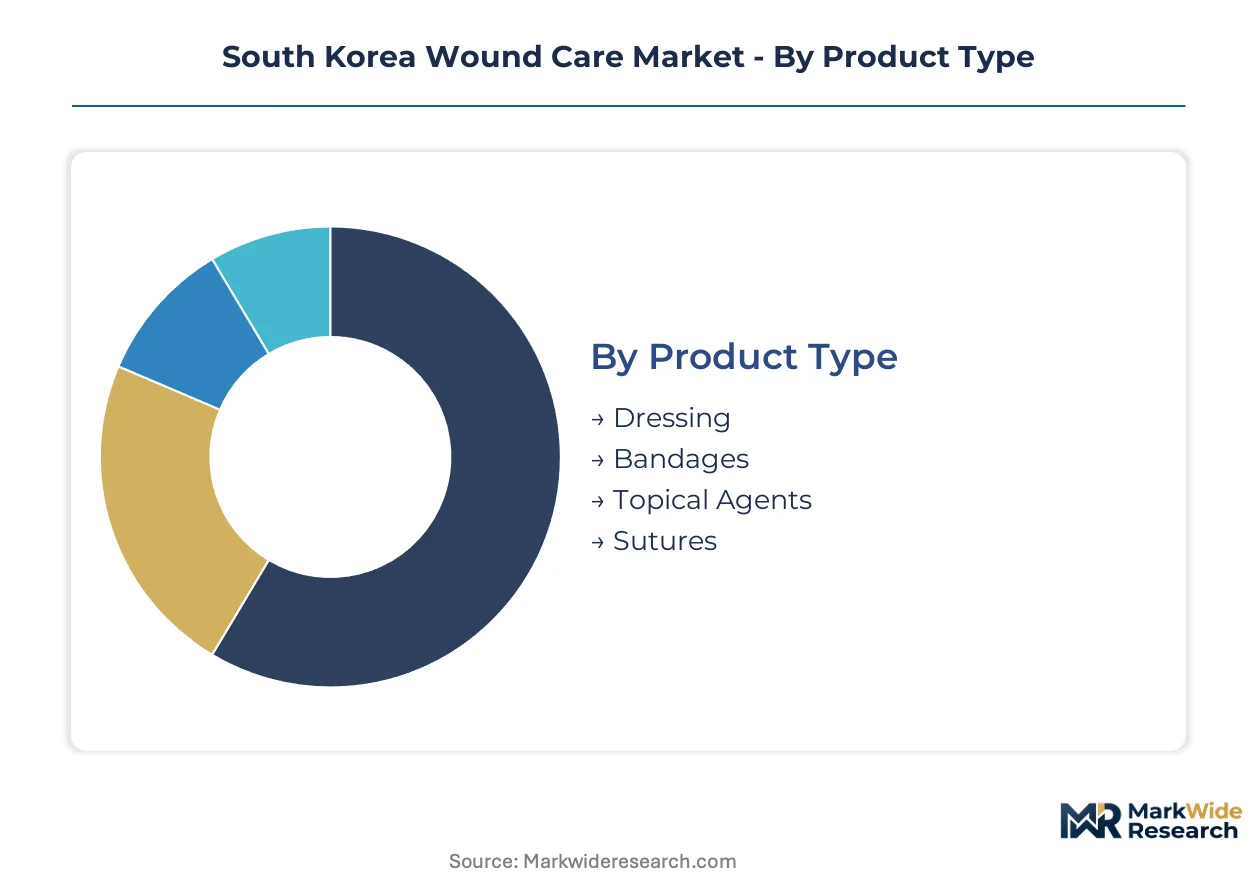
Segmentation in South Korea's wound care market reveals how procurement bifurcation between Seoul's tertiary centers and regional facilities creates divergent margin structures. Each dimension—product format, clinical application, care setting, and channel—exposes distinct competitive dynamics shaped by MFDS compliance burdens and reimbursement classifications.
Product Type:
Margin pools concentrate in advanced dressing constructions where hydrofiber and silicone-adhesive platforms command recurring consumption premiums over commodity alternatives.
- Dressing:Hydrocolloid, alginate, and hydrofiber constructions engineered for moist wound healing environments generate the deepest recurring revenue streams. Seoul's university hospitals concentrate procurement of these advanced formats for surgical site infection prevention and diabetic ulcer management, with MFDS GMP audits filtering lower-tier suppliers from tender participation.
- Bandages:Elastic and cohesive compression wraps serve ambulatory chronic wound protocols and post-operative stabilization. Demand concentrates in Busan-Ulsan manufacturing belt facilities supplying domestic hospital networks and export markets, with cost pressures compressing margins for basic cotton constructions in secondary care settings.
- Topical Agents:Antimicrobial creams and enzymatic debriders complement dressing regimens in outpatient protocols.
- Sutures:Absorbable and non-absorbable wound closure products anchor surgical supply bundles in tertiary care procurement.
Dressing holds installed capacity. Bandages is rotating up the share rankings.
Application:
Volume distribution tracks South Korea's disease burden, with chronic conditions extending treatment durations beyond acute episodes into ambulatory revenue streams.
- Chronic Wounds:Diabetic foot ulcers, pressure injuries, and venous leg defects requiring months-long management protocols. Daegu and Gwangju regional hospitals are expanding dedicated wound centers for these cases, pulling alginate and foam dressing consumption as Korea's diabetic population ages.
- Surgical Wounds:Post-operative incision care across orthopedic, cardiac, and abdominal procedures. Seoul's concentrated tertiary cluster generates concentrated demand for antimicrobial-enabled dressings that reduce hospital-acquired infection rates and shorten length-of-stay metrics.
- Traumatic Wounds:Acute injury management in emergency departments and trauma centers.
- Burns:Specialized silicone-adhesive and silver-impregnated protocols for thermal and chemical injuries.
Surgical wounds holds installed capacity. Chronic wounds is climbing the fastest.
End User:
Customer type determines pricing power, with integrated hospital networks extracting volume discounts unavailable to fragmented outpatient providers.
- Hospitals:Tertiary and secondary acute care facilities commanding group purchasing leverage. Seoul metropolitan area networks are consolidating procurement through standardized formulary protocols that favor single-source relationships with MFDS-compliant manufacturers offering clinical training bundles.
- Clinics:Outpatient wound care centers and specialty practices managing debridement and dressing changes. These settings concentrate demand for cost-efficient hydrocolloid and foam alternatives as National Health Insurance reimbursement constraints limit premium product adoption.
- Home Healthcare:Visiting nurse services and self-administered chronic wound protocols.
- Rehabilitation Centers:Long-term care facilities managing pressure injury prevention and treatment.
Hospitals holds installed capacity. Home healthcare is rotating up the share rankings.
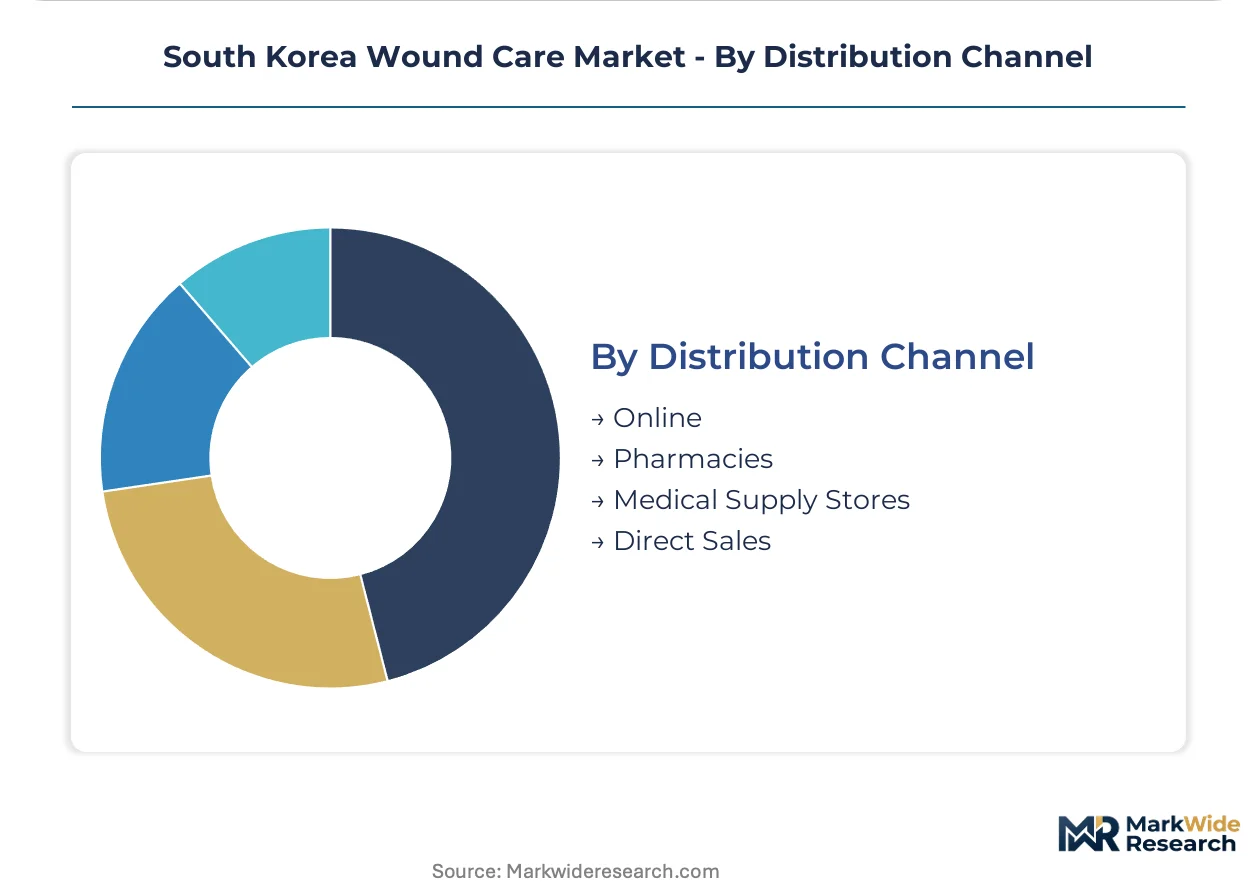
Distribution Channel:
Channel structure reflects procurement centralization trends, with direct sales and integrated supply contracts displacing fragmented retail purchasing in institutional segments.
- Direct Sales:Manufacturer-to-hospital relationships for advanced dressings and biologics. These channels capture premium margin pools through outcome-based contracting and clinical specialist support, with Seoul tertiary networks leading adoption of integrated supply models.
- Online:E-commerce platforms serving home healthcare consumers and small clinic replenishment. Telemedicine integration is opening subscription-based dressing delivery paired with remote wound monitoring tools in Seoul and Busan metropolitan areas.
- Pharmacies:Retail drugstore chains stocking basic bandages and over-the-counter topical agents.
- Medical Supply Stores:Specialized distributors serving outpatient clinics and nursing facilities.
Direct sales holds installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for advanced wound care materials clusters heavily in the Seoul Capital Area and Busan-Ulsan corridor, with regulatory compliance burdens under MFDS shaping where production facilities locate and which suppliers access hospital procurement networks.
Seoul Capital Area
Tertiary care demand concentrates in Seoul's university hospital networks, driving procurement of hydrofiber and silicone-adhesive platforms for surgical site infection prevention. MFDS Good Manufacturing Practice audits filter supplier participation in these tenders, creating protected margin pools for compliant manufacturers. The metropolitan region's wound care centers are expanding dedicated diabetic foot ulcer protocols that extend alginate dressing consumption into ambulatory settings.
Busan-Ulsan
The southeastern manufacturing belt hosts production facilities serving domestic hospital networks and export markets across Northeast Asia. Industrial zones here offer cost advantages for silicone-adhesive platform manufacturing while maintaining proximity to port infrastructure. Local suppliers face pressure from MFDS quality standard tightening that advantages established multinationals with existing compliance infrastructure.
Daegu-Gyeongbuk
Regional hospital networks in this southeastern cluster are expanding dedicated chronic wound centers as Korea's diabetic population ages. National Health Insurance reimbursement constraints limit premium product adoption in these secondary care settings, compressing margins for advanced dressings relative to Seoul's tertiary networks. Daegu medical device distributors are consolidating procurement through standardized formulary protocols.
Daejeon-Sejong
Central government presence in this administrative corridor shapes regulatory interpretation and reimbursement policy development for wound care technologies. The Korean Ministry of Food and Drug Safety headquarters location influences how clinical evidence standards propagate to regional MFDS offices. Local hospitals serve as trial sites for prospective studies supporting novel dressing registrations.
Gwangju-Honam
Southwestern regional facilities manage pressure injury prevention and treatment in long-term care settings where procurement budgets limit upgrade cycles from basic cotton gauze. Telemedicine integration is opening remote wound monitoring protocols in this area, pairing dressing supply with digital assessment tools. Rural healthcare networks here represent underpenetrated terrain for advanced dressing adoption pending reimbursement expansion.
South Korea Wound Care Market Competitive Landscape
Concentration sits with multinational medical device manufacturers possessing established MFDS registration portfolios and clinical trial infrastructure. The vendor landscape stratifies into three tiers: premium biologics suppliers serving Seoul's tertiary networks, mid-tier advanced dressing manufacturers competing on silicone-adhesive and hydrofiber platforms, and commodity gauze producers facing margin compression in secondary care settings. Competitive moves center on outcome-based contracting bundles and geographic expansion through Busan-Ulsan production facilities.
Among the premium-tier suppliers, Smith & Nephew and Coloplast exemplify archetypes built on specialized technology portfolios and hospital protocol integration. Mölnlycke Health Care occupies a position emphasizing trauma-minimizing adhesive platforms. These three represent distinct strategic postures: hydrofiber-based surgical infection prevention, ostomy-wound interface specialization, and silicone-adhesive chronic wound management respectively.
| Leading Market Players |
|---|
| Smith & Nephew |
| Coloplast |
| Medtronic |
| ConvaTec |
| Johnson & Johnson |
| Mölnlycke Health Care |
| 3M |
| Daewoong Pharmaceutical |
| Genewel |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Busan-Ulsan silicone-adhesive manufacturing facilities shapes both supply concentration and price floors for advanced dressings. Scale economies in hydrofiber production anchor premium tier pricing while compressing margins for smaller gauze converters serving secondary care networks.
Pricing Analysis
MFDS GMP audit requirements dictate the pricing tier structure across South Korea's wound care procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates biologics-enabled platforms from hydrofiber constructions and basic cotton alternatives. Pricing pressure stems from National Health Insurance reimbursement constraints that limit premium product adoption in regional hospital networks. Secondary care facilities exhibit highest price sensitivity due to budget fragmentation, while Seoul tertiary centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Container availability fluctuations along the Busan-Shanghai trade lane influence inbound raw material costs for alginate and hydrocolloid substrates. Manufacturing capacity concentrates in South Korea, China, and Japan, with domestic facilities drawing from petrochemical feedstocks and marine-derived biopolymers. Single-source vulnerability sits with specialized silicone resin suppliers serving adhesive platform production. Distribution runs through integrated hospital supply contracts and GPO networks in the Seoul metropolitan area.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS alignment with MDR-equivalent clinical evidence standards is accelerating competitive filtering, creating high-growth disruption for compliant manufacturers with existing trial infrastructure.
For Market Incumbents: Shield market position through backward integration into silicone resin production and captive supply of hydrofiber raw materials. Invest in Korean-site prospective studies to extend MFDS registration portfolios ahead of smaller competitors. Prioritize outcome-based contracting bundles with Seoul tertiary networks to lock in formulary preference. For New Entrants and Emerging Players: Telemedicine-enabled remote wound monitoring represents an under-served service layer where incumbents lack digital integration capabilities. Target Gwangju-Honam rural healthcare networks for ambulatory dressing subscription models paired with remote assessment tools. Pursue white-label manufacturing partnerships with Busan-Ulsan industrial zone facilities to bypass capital-intensive GMP infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among silicone-adhesive platform manufacturers serving chronic wound protocols with monthly replenishment cycles. Long-term viability centers on acquisition targets possessing established MFDS registrations and clinical training relationships with university hospital networks. Monitor National Health Insurance coverage determinations for bioengineered skin substitutes as the critical inflection signal for premium segment volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Registration Acceleration | Expedited clinical evidence generation compresses product launch timelines against slower competitors. |
| Hospital System Partnership | Integrated supply contracts with Seoul tertiary networks secure formulary lock-in and recurring revenue. |
| Telemedicine Platform Integration | Remote wound monitoring capabilities differentiate ambulatory service offerings from commodity suppliers. |
| Backward Integration into Raw Materials | Captive silicone resin production insulates margin structure from petrochemical feedstock volatility. |
| Reimbursement Strategy Development | National Health Insurance coverage pathway conversion unlocks premium segment volume penetration. |
Research Methodology
The analysis maps advanced dressing formats, chronic wound applications, and distribution channel structures, each validated through procurement directors at Seoul tertiary hospitals and GPO contracts managers. Primary interviews with biomedical engineers, wound care clinicians, and MFDS regulatory affairs specialists combined with secondary validation against hospital procurement databases, GPO tender documentation, and MFDS registration filings. Bottom-up unit consumption modeling and top-down market sizing triangulated across manufacturer shipment data and import-export customs records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product construction tier, clinical application pathway, end-user facility type, and regional procurement cluster. CAGRs derived from regression analysis of historical consumption patterns and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporate diabetic population demographic trajectories and MFDS audit compliance timelines.
Material uncertainties — reimbursement classification shifts, raw material supply disruptions, and regulatory interpretation changes — sit outside the modeled envelope. Forecasts reflect assumptions about continuity in current policy frameworks and competitive structure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Interactive Wound Dressing Market
Wound Care
Belgium and Netherlands Advanced Wound Care Market
Wound Care
Patch Based Wound Healing Products Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
Vascular Dressings Market
Wound Care
US Wound Care Centers Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Wound Healing Market
Wound Care
Europe Compression Bandages Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Biopatches Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
Animal Wound Care Market