
 Preparative Chromatography Market | 2026-2036
Preparative Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Preparative Chromatography Market Analytics
Direct procurement from original equipment manufacturers is reshaping how pharmaceutical buyers access preparative chromatography systems and consumables. Danaher Corporation leverages its Pall Life Sciences integration to control membrane and resin supply chains for bioprocessing customers. Thermo Fisher Scientific anchors its position through captive chromatography media production tied to analytical instrument platforms. Merck KGaA competes by extending its MilliporeSigma distribution network into emerging biologics manufacturing clusters.
Preparative chromatography employs packed columns with stationary phases of defined particle size and pore structure to separate and purify target compounds at production scale from complex feed streams. Systems operate at pressures from 50 to 400 bar with flow rates calibrated to gram-to-kilogram batch loads, serving biopharmaceutical purification as their primary commercial purpose. High-Performance Liquid Chromatography dominates capital expenditure due to its established validation protocols in regulated drug manufacturing, while Preparative Supercritical Fluid Chromaotgraphy represents the fastest-growing technology segment as chiral separation demands intensify for small-molecule APIs. Pharmaceutical application volumes sustain the largest margin pool across consumables and service contracts, though Biotech end users are expanding fastest as gene therapy and cell culture processes scale.
FDA enforces current Good Manufacturing Practice standards that mandate documented batch-to-batch consistency for chromatography resins used in parenteral drug production. EMA's MDR and REACH frameworks govern column hardware materials and solvent disposal protocols across European manufacturing sites. Stakeholders must monitor how evolving biosimilar approval pathways and single-use system regulations in multiple jurisdictions alter equipment qualification requirements and long-term capital planning.
Market Dynamics
Biopharmaceutical purity thresholds are tightening faster than resin manufacturing capacity can scale, forcing manufacturers into shorter column replacement cycles and captive media production strategies.
Growth Catalysts
- FDA cGMP batch consistency mandates:Documented resin reproducibility requirements for parenteral production are compelling facilities to upgrade chromatography infrastructure ahead of scheduled replacement timelines.
- Gene therapy manufacturing expansion:Viral vector purification workflows are scaling from clinical to commercial volumes, creating dedicated demand for preparative HPLC systems with validated cleaning protocols.
- Chiral API synthesis growth:Small-molecule drug pipelines are concentrating on enantiopure compounds, accelerating adoption of preparative supercritical fluid chromatography for stereoselective separations.
Market Restraints
- Protein A resin supply concentration:Three suppliers control over eighty percent of high-performance affinity media, exposing bioprocessors to allocation risk during demand surges.
- Stainless steel hardware cost inflation:Column vessels, distribution systems, and sanitary fittings face sustained nickel and specialty alloy price volatility.
- EMA REACH solvent disposal protocols:Organic mobile phase waste handling requirements add operational complexity and facility capital burden for European manufacturing sites.
Strategic Opportunities
- India biologics manufacturing clusters:CDMO capacity expansion in Hyderabad and Bangalore is creating first-time system procurement demand among domestic and multinational sponsors.
- Single-use chromatography systems:Modular, pre-qualified hardware configurations are reducing facility qualification timelines for multi-product bioprocessing suites.
- Continuous processing integration:Perfusion cell culture coupled with periodic counter-current chromatography is compressing downstream residence times and facility footprints.
Industry Challenges
- Resin lifetime validation expertise:Documenting cleaning effectiveness and performance decay curves requires specialized analytical chemists in short supply across contract manufacturing organizations.
- Legacy system interoperability:Brownfield facilities struggle to integrate modern chromatography data systems with existing distributed control architectures without extensive custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preparative Chromatography Market |
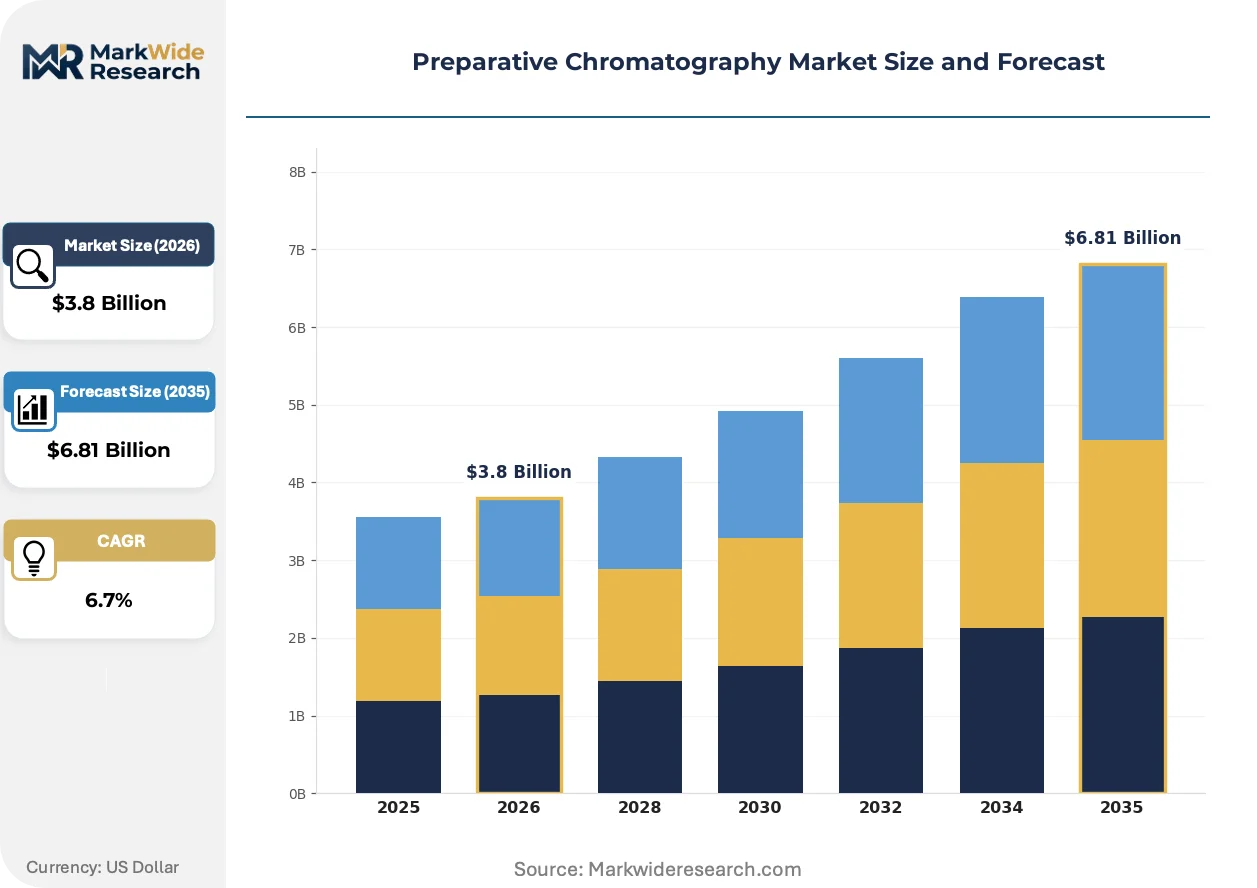
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance Liquid Chromatography, Flash Chromatography, Preparative Supercritical Fluid Chromatography, Vacuum Chromatography Application: Pharmaceuticals, Biotech, Food & Beverage, Environmental Analysis End User: Research Laboratories, Pharmaceutical Companies, Biotech Firms, Food Testing Labs Technology: Liquid Chromatography, Gas Chromatography, Ion Chromatography, Thin Layer Chromatography |
| Companies Covered | Danaher Corporation, Thermo Fisher Scientific, Merck KGaA, Waters Corporation, Agilent Technologies, Sartorius AG, Bio-Rad Laboratories, Repligen Corporation, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preparative Chromatography Market Evolving Landscape
Preparative chromatography is transitioning from batch purification toward integrated continuous bioprocessing, with hardware architecture and resin chemistry co-evolving to support real-time release paradigms.
Multimodal chromatography resins are hybridizing stationary phase chemistries to achieve orthogonal selectivity in single-column configurations. Bioprocessors at commercial scale are adopting these media to reduce downstream step counts from traditional three-column trains to two-column processes. This compression is hybridizing facility design standards and challenging established validation templates for monoclonal antibody purification.
EMA's Medical Device Regulation is reclassifying chromatography skids as Class IIa devices when used for blood fractionation, triggering notified body involvement in equipment qualification. Manufacturers serving plasma-derived protein markets must now maintain technical documentation and post-market surveillance systems previously reserved for therapeutic devices. German and Swiss fractionators are responding by consolidating supplier relationships to reduce audit burden across their installed base.
Direct resin procurement from media manufacturers is displacing traditional distributor channels for high-volume bioprocessing accounts. Multi-ton protein A resin contracts are now negotiated directly with suppliers, bypassing regional equipment distributors who historically bundled consumables with hardware sales. This pattern is most pronounced in United States and Irish manufacturing clusters where CDMO consolidation has concentrated purchasing power among fewer procurement decision-makers.
Preparative Chromatography Market Segmentation
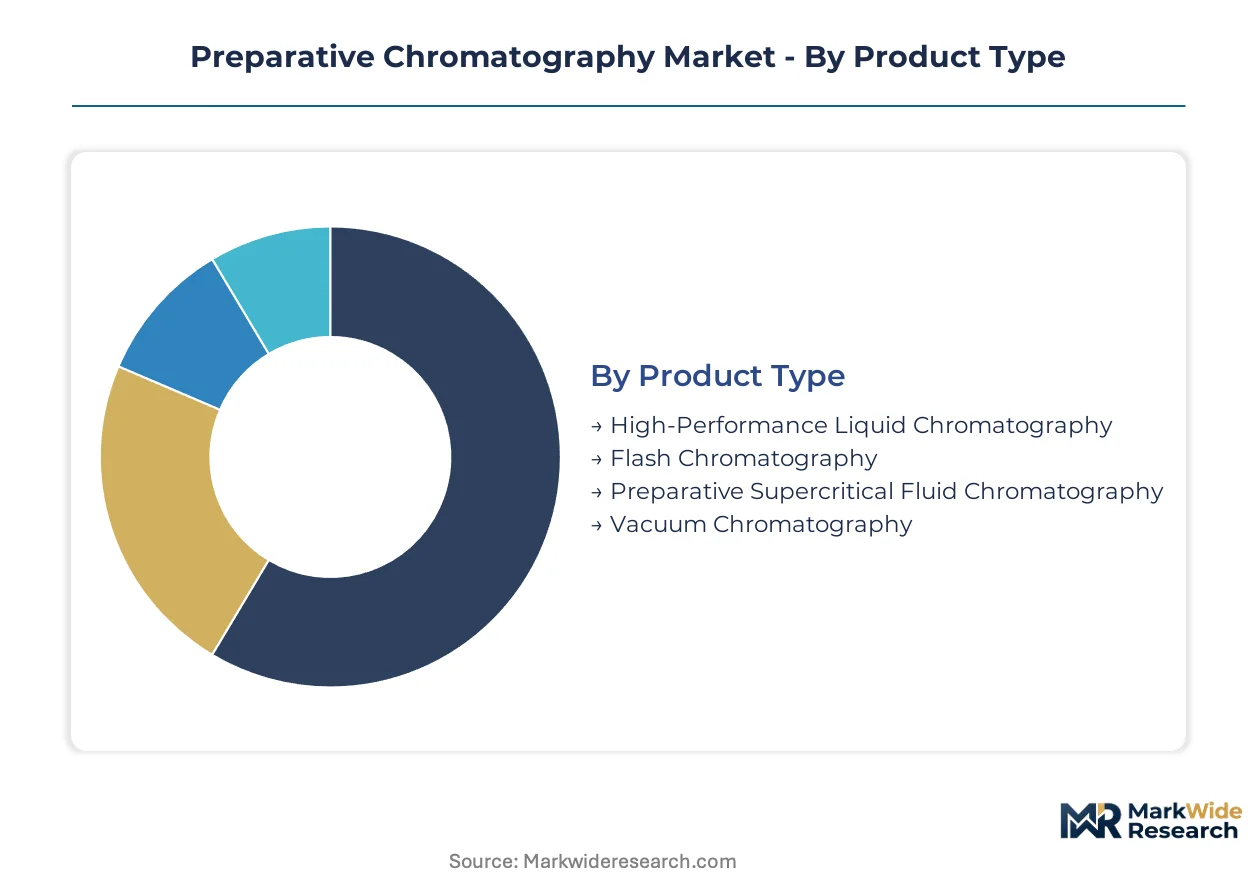
Segmentation in preparative chromatography reveals how purification technology, application intensity, and procurement authority intersect to shape vendor strategy. Equipment specifications, regulatory validation requirements, and batch scale vary dramatically across these divides, forcing suppliers to maintain parallel product architectures.
Product Type:
Cost tier determines capital deployment patterns and margin structures across purification platforms, with pressure ratings and automation levels driving price stratification.
- High-Performance Liquid Chromatography:Systems operate at 50-400 bar with precise flow control for gram-to-kilogram batch purification. Pharmaceutical manufacturers in the United States and Germany dominate procurement, compelled by FDA cGMP batch consistency mandates to upgrade infrastructure ahead of replacement timelines.
- Preparative Supercritical Fluid Chromatography:CO2-based mobile phase systems enable stereoselective separations with reduced solvent waste. Small-molecule API manufacturers scaling chiral synthesis pipelines are expanding fastest as enantiopure compound demand intensifies.
- Flash Chromatography:Low-pressure systems serve rapid purification needs in medicinal chemistry workflows.
- Vacuum Chromatography:Gravity-assisted separation for preparative-scale natural product isolation.
High-Performance Liquid Chromatography holds installed capacity. Preparative Supercritical Fluid Chromatography is rotating up the share rankings.
Application:
Application intensity correlates directly with regulatory scrutiny depth and consumables attach rates, creating divergent customer lifetime value profiles.
- Pharmaceuticals:Parenteral drug purification demands validated cleaning protocols and documented resin reproducibility. Facilities across Ireland and Switzerland sustain the largest margin pool through multi-year service contracts and captive media procurement.
- Biotech:Viral vector and monoclonal antibody workflows require specialized affinity media. Gene therapy manufacturing expansion in Massachusetts and California is climbing the fastest as clinical pipelines convert to commercial scale.
- Food & Beverage:Contaminant detection and natural compound isolation for quality verification.
- Environmental Analysis:Pollutant quantification and remediation sample preparation protocols.
Pharmaceuticals commands validation-intensive procurement. Biotech is gaining share fastest on gene therapy manufacturing expansion.
End User:
Customer type shapes decision-making unit composition, with research laboratories emphasizing flexibility and pharmaceutical companies prioritizing regulatory defensibility.
- Pharmaceutical Companies:Integrated manufacturing organizations with dedicated downstream processing groups. CDMO consolidation in the United States and Ireland has concentrated purchasing power among fewer procurement decision-makers, displacing traditional distributor channels.
- Biotech Firms:Venture-backed developers scaling from clinical to commercial manufacturing. Hyderabad and Bangalore clusters are creating first-time system procurement demand among domestic and multinational sponsors.
- Research Laboratories:Academic and government institutions with project-based funding cycles.
- Food Testing Labs:Contract analytical services with high sample throughput requirements.
Pharmaceutical Companies anchor hardware revenue. Biotech Firms are rotating up the share rankings.
Technology:
Technology maturity determines supplier competitive moats, with established platforms enjoying validation protocol advantages and novel methods requiring extensive customer education.
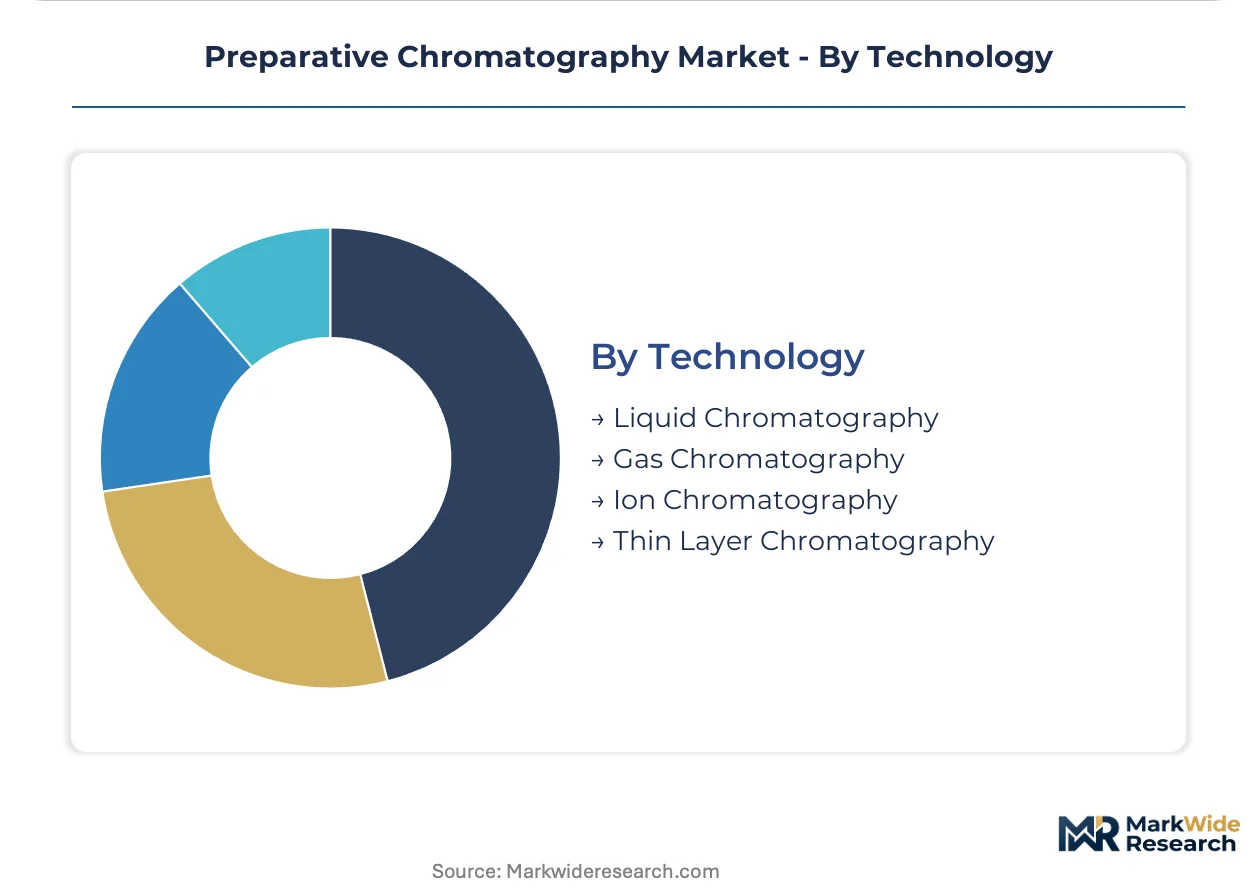
- Liquid Chromatography:Dominant preparative modality with established hardware and resin ecosystems. High-Performance Liquid Chromatography capital expenditure sustains vendor margins through consumables lock-in and service contract renewals.
- Ion Chromatography:Specialized for charged molecule separation in biologics downstream processing. Protein A resin supply concentration constrains deployment timelines for affinity purification workflows.
- Gas Chromatography:Volatile compound separation with limited preparative scale applicability.
- Thin Layer Chromatography:Analytical-scale screening with minimal preparative utility.
Liquid Chromatography holds installed capacity. Ion Chromatography is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP mandates for batch consistency anchor United States demand, while EMA REACH protocols and China's NMPA biologics guidelines reshape procurement patterns across manufacturing clusters.
United States
Gene therapy viral vector manufacturing scales from clinical to commercial volumes in Massachusetts and California. FDA cGMP resin reproducibility requirements compel facilities to upgrade chromatography infrastructure ahead of scheduled replacement timelines. Greater Boston hosts concentrated CDMO consolidation that displaces traditional distributor channels for multi-ton protein A resin contracts.
Germany
Plasma-derived protein fractionators respond to EMA Medical Device Regulation reclassification of chromatography skids as Class IIa devices. REACH solvent disposal protocols add operational complexity for organic mobile phase waste handling. Bavarian and Swiss fractionators consolidate supplier relationships to reduce audit burden across installed equipment bases.
China
NMPA biologics manufacturing guidelines tighten purity thresholds for monoclonal antibody production. Dual carbon goals accelerate adoption of supercritical fluid chromatography to reduce organic solvent consumption. Yangtze River Delta bioprocessing clusters expand captive resin production strategies to mitigate supply concentration risk.
India
CDMO capacity expansion in Hyderabad and Bangalore creates first-time system procurement demand among domestic and multinational sponsors. CDSCO quality guidelines for biologics manufacturing drive validation-intensive equipment selection. Karnataka and Telangana clusters attract gene therapy contract manufacturing investment from Western sponsors seeking cost-optimized downstream processing.
Switzerland
Swissmedic oversight of blood product manufacturing sustains premium service contract attach rates for validated chromatography systems. Basel-area biologics manufacturers leverage proximity to German resin suppliers for direct procurement negotiations. Alpine fractionation facilities invest in continuous processing integration to compress downstream residence times.
Preparative Chromatography Market Competitive Landscape
Diversified life science conglomerates and specialized bioprocessing suppliers split the market between platform ecosystem control and application-specific depth. Three structural tiers emerge: integrated conglomerates with captive media production, mid-scale specialists with regional distribution density, and niche innovators with single-technology focus. Consolidation through Pall Life Sciences integration and MilliporeSigma network extension represents dominant competitive moves alongside direct resin procurement channel displacement.
Among diversified conglomerates, Danaher Corporation and Thermo Fisher Scientific exemplify platform-anchored strategies where analytical instrument ecosystems lock in downstream consumables demand. Merck KGaA occupies a position bridging German chemical heritage with bioprocessing application depth through distribution network control. These three entities represent the integrated tier where backward integration into resin manufacturing creates procurement leverage against pure-play hardware competitors.
| Leading Market Players |
|---|
| Danaher Corporation |
| Thermo Fisher Scientific |
| Merck KGaA |
| Waters Corporation |
| Agilent Technologies |
| Sartorius AG |
| Bio-Rad Laboratories |
| Repligen Corporation |
| Shimadzu Corporation |
| Others |
Value Network & Pricing Analysis
Protein A resin supply concentration exposes bioprocessors to allocation risk that widens pricing spreads between standard catalog media and configured-to-order affinity resins while compressing margins for hardware vendors dependent on commodity stainless steel columns.
Pricing Analysis
Configured-to-order protein A resin contracts command substantial premiums over standard catalog pricing due to validated batch documentation and dedicated manufacturing slots. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated resins with full regulatory support from research-grade and bulk unvalidated alternatives. Cost compression in stainless steel hardware is intensifying because nickel alloy price volatility and energy-intensive vessel fabrication erode vendor margins. CDMOs in Ireland and Massachusetts exhibit lowest price sensitivity due to regulatory compliance imperatives, while academic research laboratories face severe budget constraints that drive demand toward refurbished systems and generic resin alternatives.
Supply Chain Analysis
Extended payment terms from major bioprocessing accounts have become standard procurement practice, with CDMOs negotiating 90-120 day cycles that strain working capital for resin manufacturers and column fabricators alike. Protein A resin production concentrates in the United States, Germany, and Sweden where specialized fermentation capacity and regulatory-compliant facilities anchor global supply. Chromatography hardware draws from Japanese precision engineering for pump systems, German stainless steel fabrication for pressure vessels, and Swiss automation components for control systems. Single-source vulnerability in agarose bead substrates for affinity media creates chokepoint exposure during demand surges for gene therapy manufacturing. Distribution runs through direct manufacturer relationships for high-volume accounts, with regional distributors serving fragmented research and development segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preparative chromatography operates as a defensive-moat market where regulatory entrenchment through validated resin supply agreements creates switching costs that protect incumbent positions across multi-year contract cycles.
For Market Incumbents: Insulate market position by deepening backward integration into agarose substrate production to mitigate single-source supply risk for affinity media. Expand captive resin manufacturing capacity in the Yangtze River Delta to serve Chinese biologics clusters with localized regulatory documentation. Threats from continuous processing technologies and single-use system alternatives demand proactive certification investment in periodic counter-current chromatography platforms.
For New Entrants and Emerging Players: Build out specialized expertise in multimodal resin chemistry to capture share in downstream process compression applications where established vendors lack hybrid stationary phase portfolios. Target Hyderabad and Bangalore CDMO clusters where first-time system procurement demand outpaces incumbent service capacity. Go-to-market positioning should emphasize rapid column qualification protocols and modular pre-validated hardware configurations that reduce facility commissioning timelines.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of niche resin innovators with differentiated selectivity chemistries. Long-term viability over the coming decade rests on exposure to gene therapy viral vector purification workflows and continuous bioprocessing integration capabilities. Acquisition target archetype includes mid-scale specialists with captive manufacturing in regulatory-stringent jurisdictions. Signal to watch is FDA guidance evolution on real-time release testing for continuous chromatography systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Manufacturing Scale-Up | Danaher's Pall integration demonstrates backward integration into membrane supply chains. |
| Continuous Processing Technology Licensing | Periodic counter-current chromatography reduces downstream facility footprints for mAb production. |
| Single-Use System Pre-Qualification Programs | Modular hardware configurations compress multi-product suite validation timelines. |
| Multimodal Resin Chemistry Development | Hybrid stationary phases enable two-column purification trains replacing traditional three-step processes. |
| Direct Procurement Channel Establishment | MilliporeSigma network extension displaces regional distributors for high-volume bioprocessing accounts. |
Research Methodology
A spread of perspectives from downstream processing engineers, regulatory affairs specialists at biologics manufacturers, resin chemists at media suppliers, and procurement directors at CDMOs converged on the working assumptions. Primary interviews combined with secondary validation from FDA cGMP guidance documents, EMA MDR technical specifications, NMPA biologics manufacturing guidelines, and SEC filings from diversified life science conglomerates. Bottom-up equipment installation tracking and top-down consumables demand modeling provided triangulation across the analysis window.
Demand-supply-balance framing anchored the analytical approach, with biopharmaceutical purification intensity, gene therapy manufacturing expansion, and chiral API synthesis growth serving as primary demand drivers across the projection horizon. Segmentation dimensions modeled include technology platform, application intensity, end-user procurement authority, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and consumables attach rate projections. Industry-specific forecast inputs encompassed protein A resin manufacturing capacity expansion and stainless steel commodity price trajectory assumptions.
Practitioners should monitor resin allocation announcements, EMA MDR enforcement patterns, and NMPA biologics guideline revisions for early signals of forecast deviation. The analysis reflects assumptions about regulatory trajectory, supply chain stability, and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Global Baking Soda Substitute Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Europe Non-Phthalate Plasticizers Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Undecylenic Acid Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Isostearyl Alcohol Market