
 Supercritical Fluid Chromatography Market | 2026-2036
Supercritical Fluid Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Supercritical Fluid Chromatography Market Analytics
Software-defined method libraries and cloud-based data analytics is decoupling instrument hardware from analytical workflow value, shifting vendor revenue toward recurring service architectures. Waters Corporation leverages its informatics ecosystem to anchor long-term contracts in regulated pharmaceutical environments. Bruker Corporation differentiates through high-resolution detection modules that extend platform utility across research and quality control settings. Agilent Technologies competes by integrating SFC modules into broader chromatography portfolios that occupy centralized lab procurement budgets.
Supercritical fluid chromatography employs carbon dioxide above its critical point as the primary mobile phase, often modified with polar co-solvents such as methanol or acetonitrile to elute analytes across packed columns at pressures typically ranging from 100 to 400 bar. The technique achieves rapid separations of thermally labile and non-volatile compounds for pharmaceutical purity testing, natural product characterization, and environmental contaminant screening. System hardware captures the dominant share of product-type revenue due to capital-intensive platform sales, while detector modules represent the fastest-growing segment as labs demand mass spectrometry hyphenation and charged aerosol detection. Automated technology configurations are displacing traditional manual systems in high-throughput pharmaceutical quality control, whereas hybrid platforms that combine SFC with preparative scale-up functions command premium positioning in contract research settings.
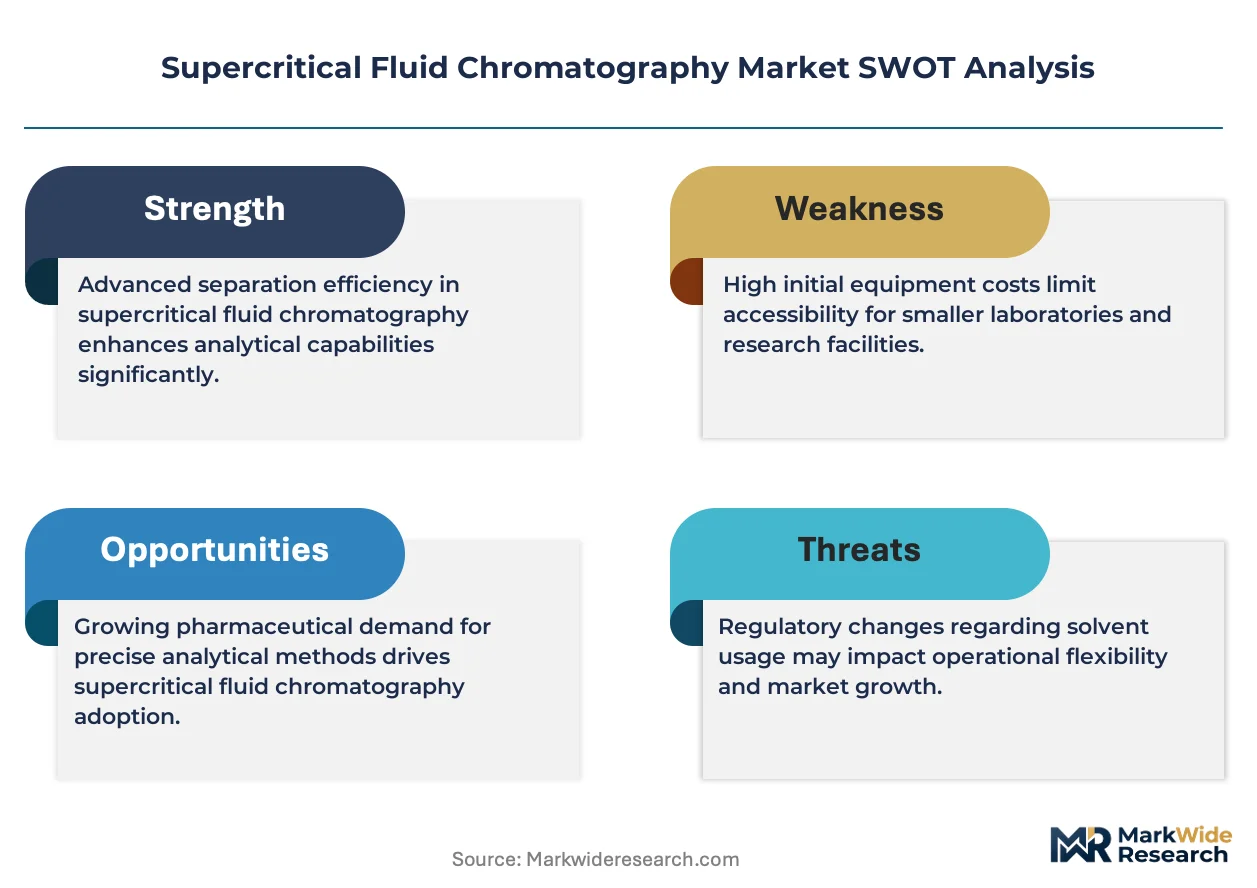
FDA bioanalytical method validation guidelines and EMA quality requirements under the EU MDR framework compel pharmaceutical laboratories to demonstrate reproducible separation performance, directly stimulating instrument upgrade demand and column replacement cycles. EPA methods for semivolatile organic compound analysis and ISO 17025 accreditation standards further shape environmental testing laboratory procurement specifications. Stakeholders must monitor evolving regulatory acceptance of SFC as a substitute for normal-phase HPLC in compendial methods, since this determination will reshape validation service demand and training revenue pools.
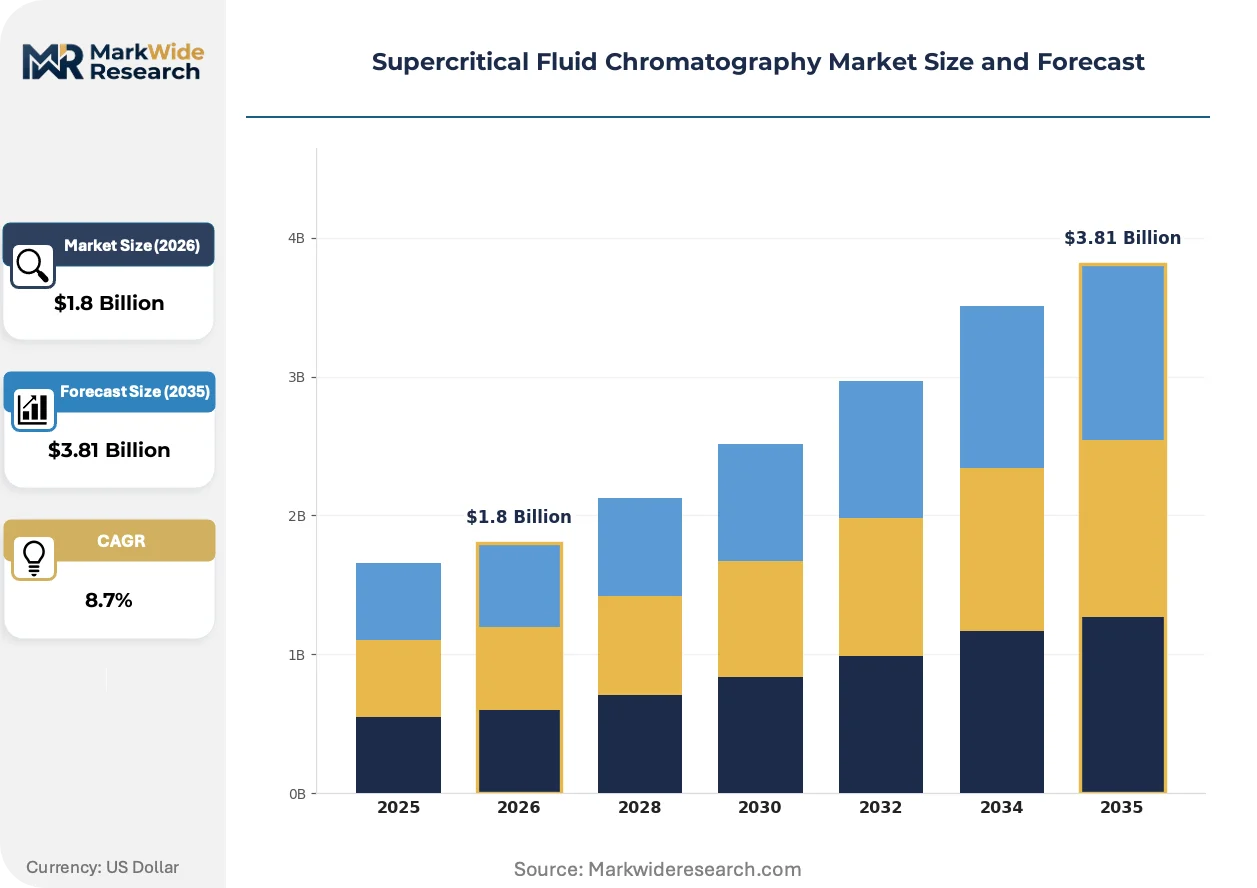
Market Dynamics
Software-defined method libraries are decoupling analytical workflow value from instrument hardware, compressing replacement cycles and shifting vendor revenue toward recurring service architectures anchored by regulatory compliance requirements.
Growth Catalysts
- EMA quality requirements under EU MDR:Pharmaceutical laboratories must demonstrate reproducible separation performance, stimulating instrument upgrade demand and column replacement cycles across European manufacturing sites.
- Chiral separations in drug development:Biotech clusters in Massachusetts and Baden-Württemberg are expanding SFC deployment for enantiomeric purity testing of therapeutic candidates.
- Carbon dioxide mobile phase technology:Supercritical CO2 systems achieve rapid separations of thermally labile compounds, displacing normal-phase HPLC in high-throughput quality control environments.
Market Restraints
- Capital intensity of platform sales:System hardware captures dominant revenue share, requiring substantial upfront investment that delays adoption in mid-sized contract research organizations.
- Technical limitation in method transfer:Reproducibility across different SFC instrument configurations remains inconsistent, complicating multi-site pharmaceutical validation protocols.
- Substitution threat from improved HPLC:Advances in sub-2-micron particle UHPLC columns narrow the separation speed gap for non-chiral applications in environmental testing laboratories.
Strategic Opportunities
- Preparative scale-up hybrid platforms:Contract research settings command premium positioning for systems combining analytical SFC with purification functions, opening service revenue pools.
- Mass spectrometry hyphenation demand:Detector modules represent the fastest-growing segment as laboratories seek high-resolution detection for complex natural product characterization.
- Cloud-based data analytics integration:Informatics ecosystems enable long-term service contracts by embedding method libraries within regulated pharmaceutical quality management systems.
Industry Challenges
- Specialized operator skill requirements:Supercritical fluid handling at 100-400 bar pressures demands trained chromatographers, creating recruitment bottlenecks in high-growth biotech clusters.
- Compendial method validation timelines:FDA acceptance of SFC as substitute for normal-phase HPLC remains pending, delaying validation service revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supercritical Fluid Chromatography Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: System, Column, Detector, Accessories End User: Pharmaceuticals, Environmental Testing, Food & Beverage, Research Institutions Application: Drug Development, Quality Control, Environmental Analysis, Nutraceuticals Technology: Traditional, Automated, Hybrid, Miniaturized |
| Companies Covered | JASCO Corporation, Bruker Corporation, Waters Corporation, Fluitron Inc., Supercritical Fluid Technologies Inc., Shimadzu Scientific Instruments, Thar Process Inc., SFT Inc., Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supercritical Fluid Chromatography Market Evolving Landscape
Automation architectures and detection module advances are compressing analytical timelines while regulatory frameworks accelerate instrument refresh cycles across pharmaceutical quality control networks.
Automated technology configurations are eliminating manual sample handling in high-throughput pharmaceutical quality control. Large molecule drug manufacturers in the Boston-Cambridge corridor are deploying these systems at accelerated pace to meet batch release timelines. The technology is automating method execution, reducing operator-dependent variability and enabling 24-hour continuous operation in regulated environments.
EPA methods for semivolatile organic compound analysis are expanding SFC applicability in environmental contaminant screening. Industrial laboratories must demonstrate ISO 17025 accreditation compliance, reshaping procurement specifications toward platforms with embedded audit trail functionality. Environmental testing facilities in Germany's chemical corridor are responding by prioritizing systems with pre-validated method libraries.
Service unbundling from hardware sales is restructuring vendor-customer relationships in centralized laboratory procurement. Pharmaceutical quality control departments now purchase detector modules and software subscriptions separately from base platform capital expenditure. This pattern is most visible in North American biopharmaceutical manufacturing, where procurement teams negotiate multi-year informatics contracts independent of instrument replacement schedules.
Supercritical Fluid Chromatography Market Segmentation
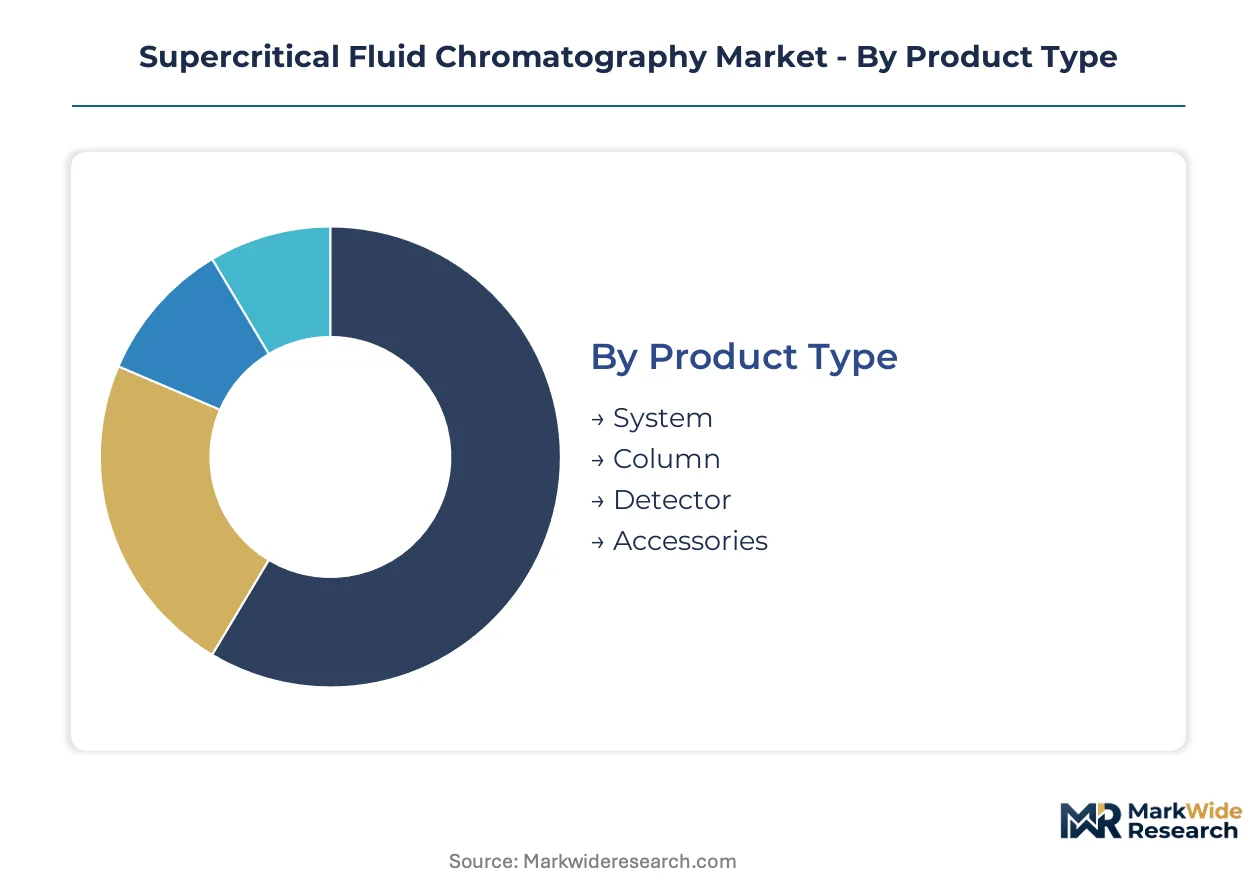
Segmentation in supercritical fluid chromatography reveals distinct procurement patterns between integrated platform buyers and modular component purchasers. Pharmaceutical manufacturers prioritize end-to-end systems while contract research organizations mix standalone detectors with existing infrastructure.
Product Type:
Standalone platforms dominate capital expenditure budgets, yet detector modules increasingly ship as retrofits to installed base systems.
- System:Complete instrument platforms integrate pumps, ovens, and back-pressure regulators for turnkey deployment. German chemical corridor manufacturers favor these configurations for validated quality control workflows under EMA guidelines.
- Detector:Mass spectrometry and charged aerosol detection modules extend analytical capability without full platform replacement. Massachusetts biotech clusters drive demand for these upgrades to accelerate batch release timelines.
- Column:Packed columns with chiral stationary phases require frequent replacement in enantiomeric purity testing.
- Accessories:Back-pressure regulators, sample loops, and solvent delivery modules support maintenance cycles.
System sales lead volumes today; Detector modules are gaining share fastest.
End User:
Cost tier stratification separates regulated pharmaceutical manufacturers from price-sensitive environmental laboratories.
- Pharmaceuticals:Large molecule drug developers deploy SFC for chiral separations and impurity profiling. FDA bioanalytical validation requirements compel these buyers toward automated configurations with embedded audit trails.
- Environmental Testing:Industrial laboratories screen semivolatile organic compounds under EPA methods. ISO 17025 accreditation pressures these facilities toward pre-validated method libraries.
- Food & Beverage:Natural product characterization and contaminant screening drive adoption in quality assurance laboratories.
- Research Institutions:Academic centers prioritize hybrid platforms offering both analytical and preparative scale-up functions.
Pharmaceuticals anchor revenue concentration; Environmental Testing is expanding most quickly.
Application:
Volume concentration clusters in high-throughput quality control, while drug development commands premium pricing for method flexibility.
- Quality Control:Batch release testing for enantiomeric purity dominates operational deployment. Boston-Cambridge biotech manufacturers run these systems continuously to meet compressed regulatory submission timelines.
- Drug Development:Early-stage therapeutic candidates require chiral separation for pharmacokinetic profiling. Baden-Württemberg pharmaceutical corridors invest here to accelerate candidate selection.
- Environmental Analysis:Contaminant screening for semivolatile organics expands under EPA method frameworks.
- Nutraceuticals:Natural product characterization supports botanical supplement standardization.
Quality Control leads operational deployment; Drug Development shows steepest expansion trajectory.
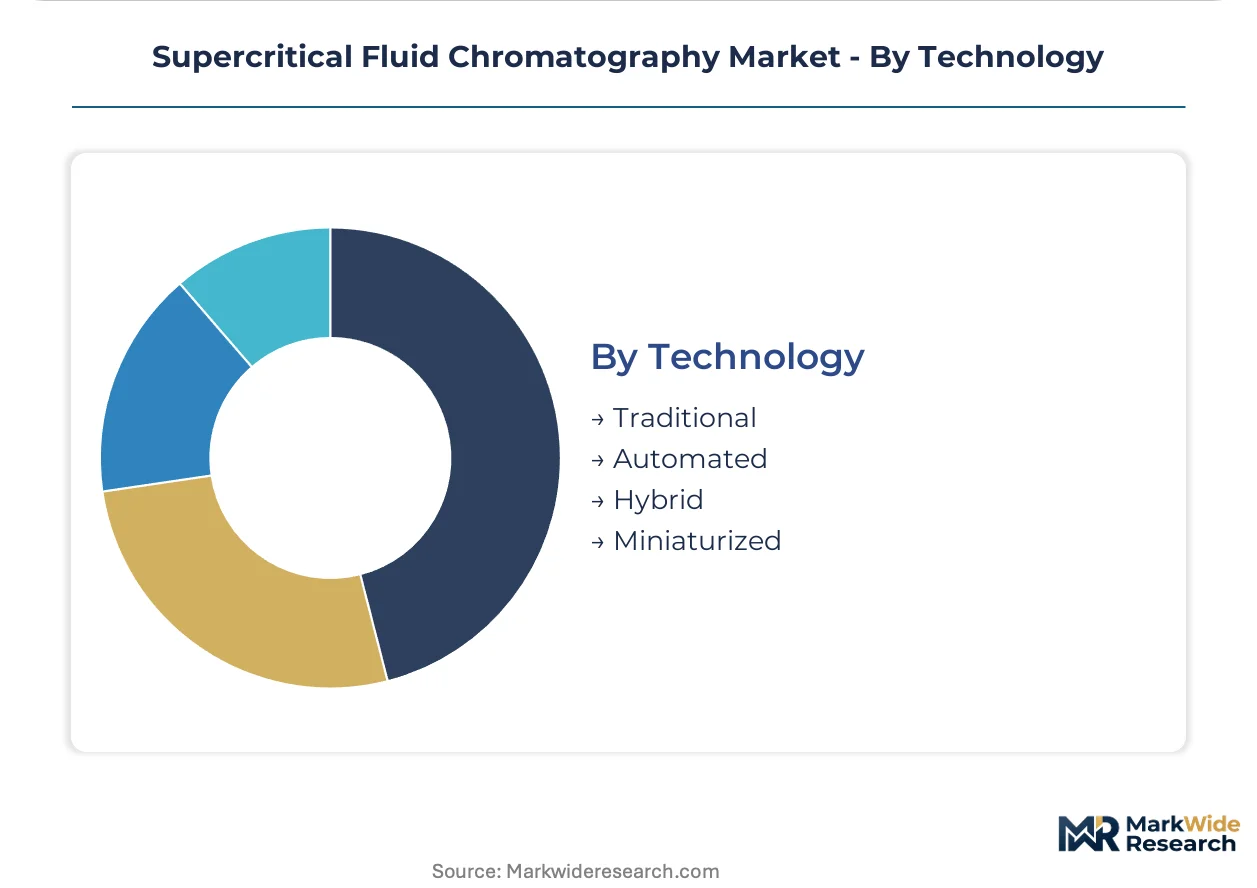
Technology:
Maturity gradients separate established manual configurations from emerging automated architectures reshaping operator requirements.
- Automated:Robotic sample handling and method execution eliminate operator-dependent variability. North American biopharmaceutical manufacturers deploy these systems for 24-hour continuous operation in regulated environments.
- Hybrid:Combined analytical and preparative functions enable scale-up without platform changeover. Contract research organizations in Germany's chemical corridor pay premiums for this flexibility.
- Traditional:Manual injection and method adjustment persists in budget-constrained academic settings.
- Miniaturized:Reduced-scale systems target field deployment and point-of-need analysis.
Traditional configurations retain installed base dominance; Hybrid platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed base of SFC systems in Europe, while the United States generates the highest absolute revenue from pharmaceutical quality control deployments. Regulatory divergence between FDA bioanalytical guidelines and EMA quality requirements under EU MDR is creating distinct procurement cycles across Atlantic markets.
United States
Massachusetts biotech manufacturers drive detector module upgrades for chiral separations in large molecule drug development. FDA bioanalytical method validation guidelines compel laboratories toward automated configurations with embedded audit trails. The Boston-Cambridge corridor operates SFC systems continuously to meet compressed regulatory submission timelines.
Germany
Baden-Württemberg pharmaceutical corridors invest in hybrid platforms combining analytical and preparative functions for contract research settings. EMA quality requirements under EU MDR stimulate instrument replacement cycles across manufacturing sites. The country's chemical corridor prioritizes systems with pre-validated method libraries for ISO 17025 accreditation compliance.
Switzerland
Swiss pharmaceutical manufacturers deploy SFC for natural product characterization and impurity profiling in therapeutic candidate selection. Swissmedic oversight of analytical method validation shapes procurement toward platforms with comprehensive audit trail functionality. Basel-based quality control laboratories anchor regional demand for mass spectrometry hyphenation modules.
Japan
PMDA quality requirements for bioanalytical method validation accelerate instrument refresh cycles in pharmaceutical quality control networks. METI industrial standards support SFC adoption for environmental contaminant screening under tightened emission protocols. The Kanto region's pharmaceutical manufacturing base concentrates demand for automated technology configurations.
India
CDSCO quality guidelines for pharmaceutical exports drive SFC adoption in active pharmaceutical ingredient testing laboratories. The country's national pharmaceutical regulator emphasizes reproducible separation performance for international market access. Maharashtra-based contract research organizations invest in preparative scale-up hybrid platforms to serve global drug development programs.
Supercritical Fluid Chromatography Market Competitive Landscape
Top-tier vendors anchor the premium instrumentation tier, while mid-scale specialists occupy modular component and service contract segments. The market structure reflects consolidated platform sales alongside fragmented detector and column replacement markets. Three archetypes dominate: full-system integrators, detection module specialists, and informatics-anchored service providers. Competitive moves concentrate on strategic partnerships for mass spectrometry hyphenation and geographic expansion through distributor networks in Asia-Pacific.
Among North American instrumentation vendors, Waters Corporation and Agilent Technologies exemplify the full-system integrator archetype through chromatography portfolio breadth. Bruker Corporation occupies a position within the detection specialist tier, anchoring high-resolution module development. These three companies represent distinct strategic vectors: informatics ecosystem lock-in, centralized lab procurement capture, and detection technology differentiation.
| Leading Market Players |
|---|
| JASCO Corporation |
| Bruker Corporation |
| Waters Corporation |
| Fluitron Inc. |
| Supercritical Fluid Technologies Inc. |
| Shimadzu Scientific Instruments |
| Thar Process Inc. |
| SFT Inc. |
| Agilent Technologies |
| Others |
Value Network & Pricing Analysis
Carbon dioxide commodity pricing volatility cascades through SFC instrument manufacturing, compressing margins on economy-tier systems while premium platforms absorb input fluctuations through service bundling. German pump manufacturers and Japanese detector specialists translate feedstock pressure into tiered hardware offerings that stratify pharmaceutical buyers from environmental laboratories.
Pricing Analysis
Capacity additions in Massachusetts and Baden-Württemberg are reshaping price floors for automated SFC platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated configurations from ISO 17025-compliant systems and entry-level academic units. Cost compression in the economy tier stems from modular detector retrofits displacing full-platform purchases. Contract research organizations exhibit highest price sensitivity, while large molecule drug manufacturers prioritize compliance over capital expenditure.
Supply Chain Analysis
ISO 17025 and FDA 21 CFR Part 11 certification requirements gate component sourcing for regulated pharmaceutical deployments. Precision pump assemblies concentrate in Germany and Switzerland, while detector electronics feed from Japan and South Korea. The supply chain rests on high-pressure valve subassemblies and chiral stationary phase chemistries as critical inputs. Single-source vulnerability persists in supercritical CO2 back-pressure regulator technology. Distribution runs through authorized service networks that embed validation documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical fluid chromatography has matured into a quality-driven replacement market where pharmaceutical laboratories prioritize validated performance over initial capital savings. The demand shift toward mass spectrometry hyphenation and cloud-integrated method libraries elevates specification sensitivity across all buyer tiers.
For Market Incumbents: Cement ecosystem lock-in through informatics subscriptions that embed method libraries within customer quality management systems. Invest in backward integration into chiral stationary phase manufacturing to secure column replacement revenue against generic suppliers. The threat of UHPLC substitution for non-chiral applications demands defensive patenting around SFC-specific detection interfaces. For New Entrants and Emerging Players: Miniaturized field-deployable SFC systems offer a technology-first wedge into environmental monitoring agencies and food safety inspectors underserved by laboratory-centric vendors. Target India's CDSCO-compliant API testing laboratories with preparative-analytical hybrid platforms. A service-led go-to-market emphasizing method development partnerships bypasses capital-intensive direct instrument competition. For Investors and Strategic Acquirers: Asymmetric upside sits with detector module specialists possessing mass spectrometry hyphenation IP. Long-term viability hinges on recurring service revenue ratios rather than hardware shipment volumes. Acquisition targets should demonstrate embedded positions in pharmaceutical quality control networks with multi-year informatics contracts. The signal to watch is FDA acceptance of SFC as compendial substitute for normal-phase HPLC, which would trigger accelerated replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Hyphenation Partnership | Waters Corporation leverages detection integration to anchor long-term pharmaceutical service contracts. |
| Cloud-Based Method Library Deployment | Software-defined analytics shift vendor revenue toward recurring subscription architectures. |
| Preparative Scale-Up Platform Launch | Hybrid systems command premium positioning in Germany's contract research corridor. |
| Chiral Stationary Phase Backward Integration | Captive column supply secures replacement revenue against generic competitors. |
| Regulatory Validation Service Expansion | FDA bioanalytical compliance requirements stimulate instrument upgrade and training demand. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's pharmaceutical manufacturing and analytical instrumentation clusters. The approach combines structured interviews with drug development executives, regulatory affairs leads, quality control directors, and chromatography procurement managers with secondary validation from FDA filings, EMA submissions, EPA method databases, and ISO accreditation records. Bottom-up instrument shipment data triangulates against top-down pharmaceutical R&D expenditure trends.
Rate-of-change decomposition separates volume effects from mix shifts and pricing dynamics across the projection horizon. Segmentation dimensions include product type, end-user industry, application purpose, and technology configuration alongside regional regulatory cluster. CAGRs derive from instrument replacement cycle analysis, column consumption rates, and service contract renewal patterns. Forecast inputs incorporate EMA MDR implementation timelines and EPA method expansion trajectories.
The model holds under stable regulatory acceptance of SFC for compendial methods; deviation in FDA substitution rulings or EMA quality requirement enforcement would shift replacement demand timing. Forecasts reflect assumptions regarding pharmaceutical laboratory automation adoption and environmental testing accreditation expansion. A model refresh is warranted upon material change in carbon dioxide supply cost structures or mass spectrometry vendor partnership dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Global Rheometer and Viscometer Market