
 Ferrous Gluconate Market | 2026-2036
Ferrous Gluconate Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrous Gluconate Market Foresight
Contract manufacturing and toll-processing services is consolidating as the decisive layer in ferrous gluconate supply, shifting value from bulk chemical sales to validated production partnerships. Jost Chemical leverages cGMP-certified facilities to anchor North American pharmaceutical supply chains. Dr. Paul Lohmann sustains European market presence through precipitate-grade specialization for parenteral applications. Aditya Chemicals competes on cost-engineered powder production serving generic tablet manufacturers across emerging markets.
Ferrous gluconate is a coordination compound of iron(II) with gluconic acid, typically supplied as dihydrate (C12H22FeO14·2H2O) with 11.6% elemental iron content, manufactured through controlled reaction of ferrous salts with sodium gluconate followed by crystallization and spray-drying for pharmaceutical and nutritional applications. Tablets dominate volume throughput due to established oral anemia therapy protocols, while injectable formulations command premium positioning in hospital settings where gastrointestinal intolerance or malabsorption precludes oral administration. The liquid form segment is gaining traction in pediatric and geriatric populations, with effervescent formats emerging as a compliance-enhancing alternative in European pharmacy channels.
FDA Current Good Manufacturing Practice regulations and EMA GMP guidelines for active pharmaceutical ingredients govern ferrous gluconate production, with USP and EP monographs defining assay limits, impurity profiles, and microbial specifications that determine market access for finished dosage form suppliers. India's CDSCO mandates manufacturing licenses under the Drugs and Cosmetics Act for domestic producers, while China's NMPA requires registration of imported API sources through its chemical drug master file system. Stakeholders must monitor evolving pharmacopeial harmonization initiatives and bioequivalence study requirements for generic iron supplements, as regulatory convergence between FDA and EMA pathways will reshape competitive qualification timelines for new market entrants.
Market Dynamics
Contract manufacturing consolidation is redrawing competitive boundaries in ferrous gluconate supply, as pharmaceutical-grade certification requirements push bulk chemical producers toward validated production partnerships with toll processors.
Growth Catalysts
- India's National Iron Plus Initiative:Government-mandated iron supplementation programs for pregnant women and adolescents are driving bulk procurement of pharmaceutical-grade ferrous gluconate through centralized tendering.
- FDA bioequivalence tightening:Stricter purity benchmarks for generic mineral salts are disqualifying uncertified producers and expanding addressable market for cGMP-compliant manufacturers.
- Parenteral nutrition expansion:Hospital networks in China are expanding injectable iron capacity to serve malabsorption cases where oral therapy fails.
Market Restraints
- Ferrous sulfate substitution:Lower-cost iron salts capture volume in over-the-counter segments where bioequivalence requirements do not apply, compressing ferrous gluconate's accessible market.
- API import dependency in Europe:Limited indigenous precipitate-grade production forces reliance on Asian suppliers, exposing formulation manufacturers to customs delays and currency volatility.
- Elemental iron assay variability:Hydration state inconsistencies in dihydrate raw material complicate tablet potency validation and batch release timelines.
Strategic Opportunities
- Pediatric liquid formulations:Palatability-engineered drops and syrups address compliance gaps in India's anganwadi nutrition centers where tablet administration fails.
- Effervescent tablet channels:European pharmacy chains are expanding self-selection aisles for compliance-enhancing formats that bypass swallowing difficulties in geriatric populations.
- EMA-FDA pharmacopeial harmonization:Converging USP and EP monograph specifications will reduce dual-registration costs for API suppliers seeking transatlantic market access.
Industry Challenges
- Analytical method transfer:Complexometric titration protocols for ferrous content assay require specialized technician training that contract laboratories struggle to staff.
- Container closure integrity:Oxygen-sensitive dihydrate formulations demand nitrogen-flushed packaging investments that generic tablet manufacturers resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrous Gluconate Market |
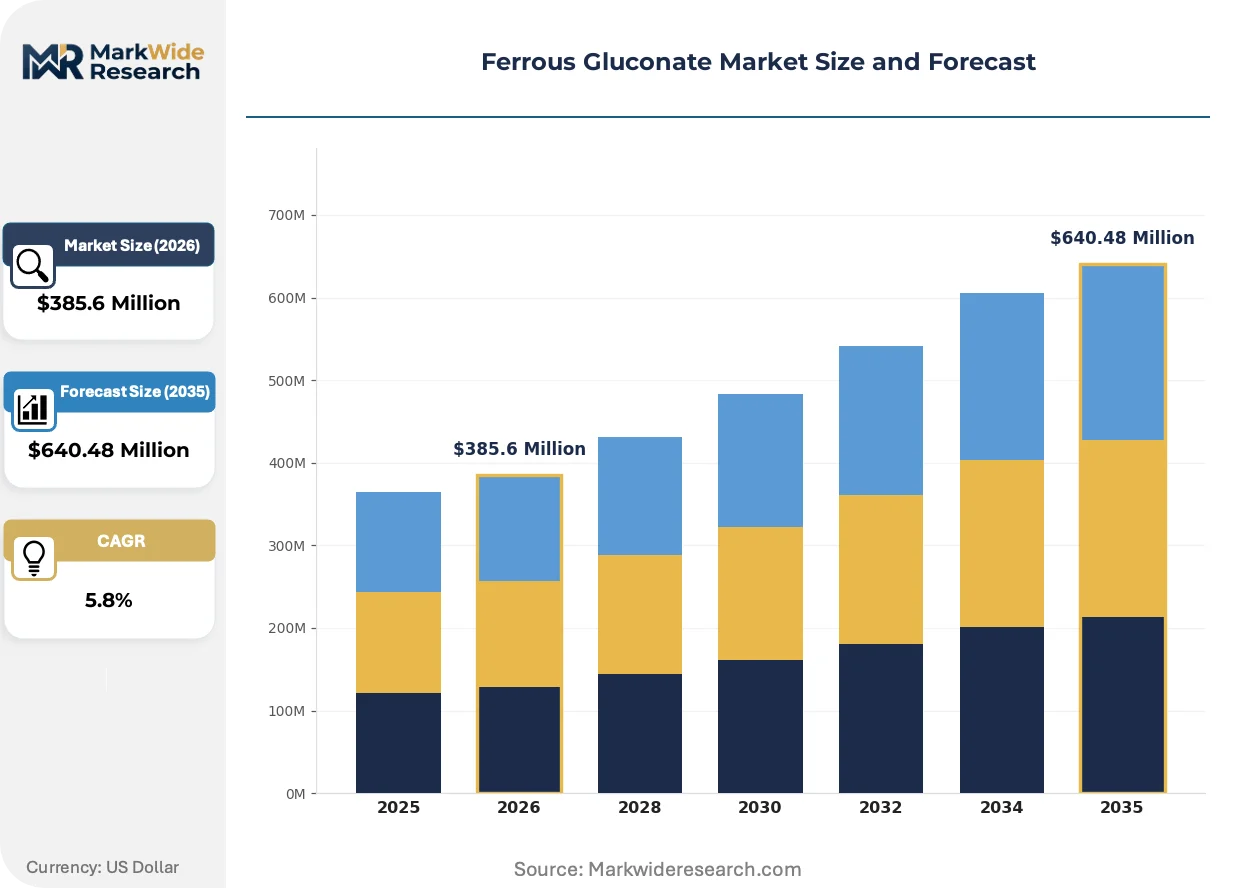
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Powder End User: Pharmacies, Hospitals, Clinics, Online Stores Form: Liquid, Solid, Effervescent, Gummy Packaging Type: Bottle, Blister Pack, Jar, Sachet |
| Companies Covered | Jost Chemical, Aditya Chemicals, Dr. Paul Lohmann, Sudeep Pharma, ShanPar, Global Calcium, Spectrum Chemical, Celtic Chemicals, ISALTIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrous Gluconate Market Shifts & Advancements
Continuous manufacturing and real-time release testing are displacing batch processing in pharmaceutical-grade mineral salt production, compressing lead times from synthesis to finished dosage form.
Process analytical technology is automating crystallization endpoint detection in ferrous gluconate dihydrate production. Jost Chemical and European toll processors are deploying in-line Raman spectroscopy to replace offline HPLC testing. This shift is automating quality assurance and reducing batch cycle times from days to hours.
REACH authorization requirements for process solvents are forcing European API manufacturers to substitute ethanol-water crystallization systems for methanol-based protocols previously standard in Asian production. The reformulation burden falls heaviest on precipitate-grade suppliers serving parenteral applications where residual solvent limits are tightest.
Hospital procurement consortia in China are consolidating iron supplement purchasing through provincial centralized tendering platforms, displacing fragmented distributor networks that previously served individual pharmacy departments. This concentration is visible in Jiangsu and Guangdong provinces where volume commitments now determine supplier qualification.
Ferrous Gluconate Market Segmentation
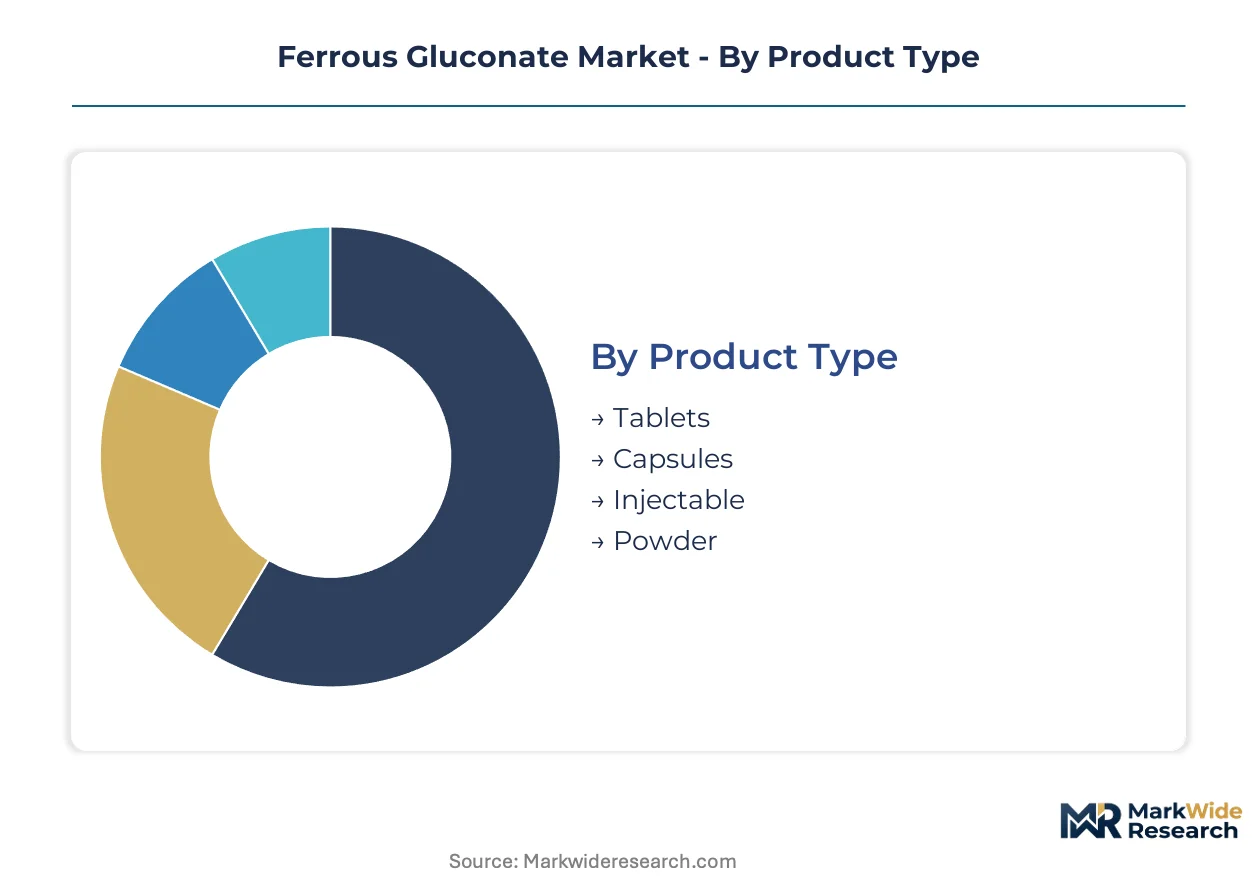
Ferrous gluconate supply chains fragment across four distinct category axes, each commanding different margin profiles and regulatory burdens. Manufacturers must align production certification with the specific channel and formulation requirements of each segment tier.
Product Type:
Supply concentration in pharmaceutical-grade production favors validated tablet and injectable lines over commodity powder operations.
- Tablets:Oral solid dosage forms containing dihydrate ferrous gluconate with standardized 11.6% elemental iron content. India's National Iron Plus Initiative procures bulk volumes through centralized tendering for maternal health programs. FDA bioequivalence tightening is disqualifying uncertified producers from generic tablet supply chains.
- Injectable:Sterile parenteral solutions requiring precipitate-grade purity for hospital malabsorption cases. China's provincial hospital consortia are expanding centralized purchasing platforms in Jiangsu and Guangdong provinces where volume commitments determine supplier qualification.
- Capsules:Gelatin or HPMC shells encapsulating powder for patients with tablet swallowing difficulties.
- Powder:Bulk active pharmaceutical ingredient supplied to contract manufacturers for downstream formulation.
Tablets absorb the bulk of installed capacity; injectable is expanding most quickly.
End User:
Channel economics diverge sharply between institutional procurement and retail pharmacy margins.
- Pharmacies:Community and chain dispensaries serving chronic anemia patients with prescription and over-the-counter replenishment. European pharmacy chains are expanding self-selection aisles for effervescent formats targeting geriatric compliance.
- Hospitals:Acute care facilities managing severe iron deficiency with parenteral protocols when oral therapy fails. China's hospital networks are consolidating iron supplement purchasing through provincial centralized tendering platforms.
- Clinics:Outpatient settings in India's anganwadi nutrition centers where pediatric liquid administration replaces failed tablet compliance.
- Online Stores:Direct-to-consumer channels bypassing traditional distribution for subscription-based replenishment programs.
Hospitals command the steepest pricing premiums; online stores are climbing the fastest as direct distribution models mature.
Form:
Patient compliance engineering drives formulation innovation across age-specific delivery systems.
- Liquid:Aqueous solutions and suspensions with palatability masking for pediatric and geriatric populations. India's government nutrition programs are driving procurement of drops and syrups for anganwadi centers where solid dosage forms fail.
- Solid:Conventional tablets and capsules dominating established oral anemia therapy protocols with proven bioequivalence profiles.
- Effervescent:Rapid-dissolving tablets addressing swallowing difficulties in European geriatric populations through pharmacy self-selection channels.
- Gummy:Confectionery-format supplements targeting adult compliance fatigue in direct-to-consumer markets.
Solid forms retain dominant share; effervescent formats are gaining share fastest through European pharmacy channel expansion.
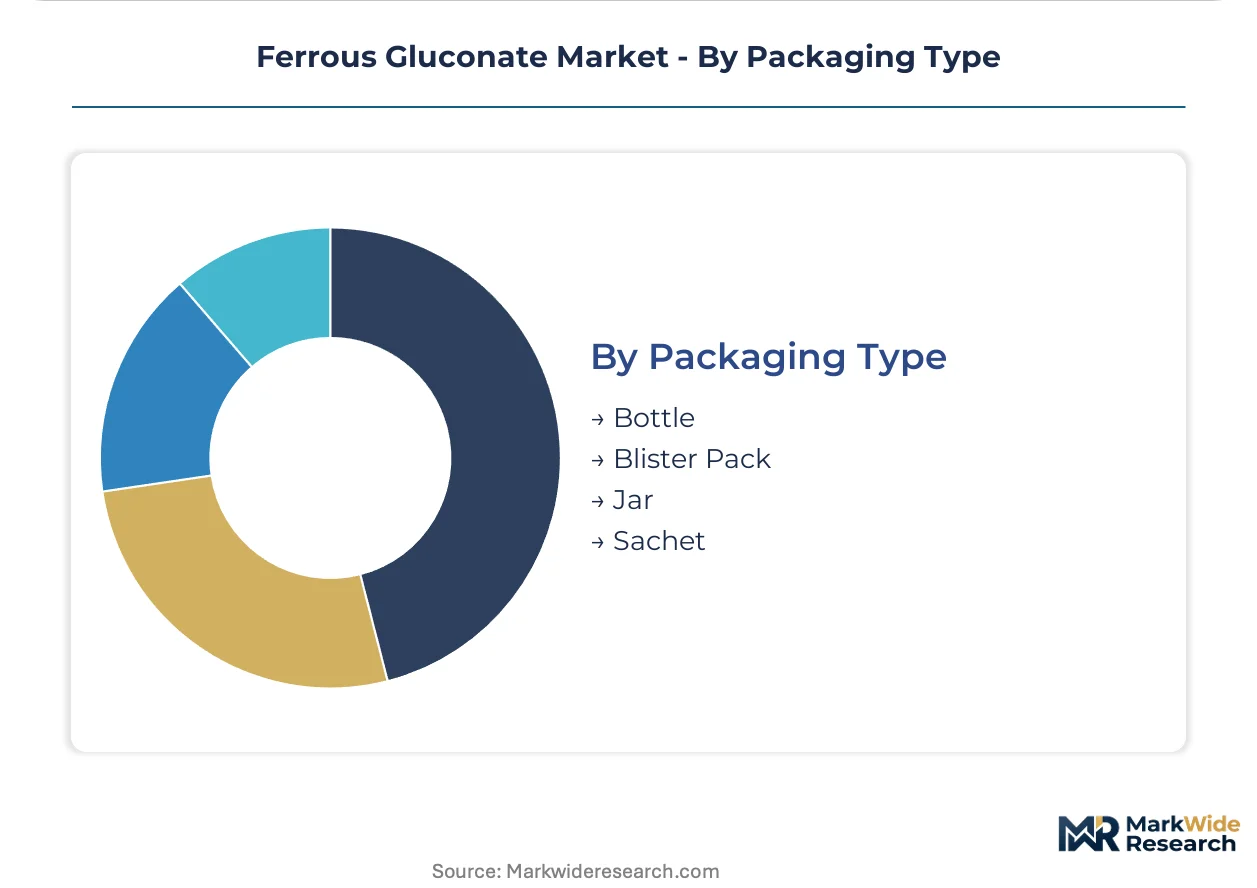
Packaging Type:
Container closure integrity investments separate pharmaceutical-grade suppliers from commodity chemical packagers.
- Bottle:HDPE or amber glass containers with child-resistant closures for liquid formulations and bulk tablet counts. Oxygen-sensitive dihydrate formulations demand nitrogen-flushed packaging investments that generic manufacturers resist.
- Blister Pack:PVC or aluminum-polymer barrier systems for unit-dose tablet protection against moisture and oxidation.
- Jar:Wide-mouth polyethylene containers for powder repackaging by contract manufacturers.
- Sachet:Single-serve foil laminates for effervescent granules and travel-format liquid doses.
Bottles and blister packs together dominate unit volume; sachet formats are expanding most quickly for effervescent and travel segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates bulk chemical production capacity while India and European markets absorb the bulk of pharmaceutical-grade consumption. This geographic split shapes procurement patterns, regulatory compliance burdens, and investment flows across the ferrous gluconate supply chain.
United States
FDA Current Good Manufacturing Practice regulations govern pharmaceutical-grade ferrous gluconate imports, with USP monographs defining assay limits and impurity profiles. Hospital networks and retail pharmacy chains drive demand for oral iron supplements in maternal health and chronic anemia management. The New Jersey-Pennsylvania pharmaceutical corridor hosts formulation manufacturers that source API through validated toll-processing partnerships.
Germany
EMA GMP guidelines and REACH authorization requirements for process solvents shape domestic production economics, forcing substitution of ethanol-water crystallization systems for methanol-based protocols. Precipitate-grade specialization for parenteral applications concentrates in the country's chemical manufacturing belt. The Rhine-Ruhr industrial region maintains API toll-processing capacity serving hospital procurement consortia across the European Union.
India
CDSCO manufacturing licenses under the Drugs and Cosmetics Act govern domestic production, while the National Iron Plus Initiative drives bulk procurement through centralized government tendering for pregnant women and adolescent supplementation programs. Maharashtra and Gujarat host contract manufacturers producing cost-engineered powder for generic tablet makers. Anganwadi nutrition centers in rural districts generate demand for pediatric liquid formulations where tablet compliance fails.
China
NMPA registration of imported API sources through the chemical drug master file system controls market access for foreign suppliers, while provincial hospital consortia in Jiangsu and Guangdong consolidate iron supplement purchasing through centralized tendering platforms. The Yangtze River Delta concentrates spray-drying and crystallization capacity serving both domestic formulation manufacturers and export markets. Hospital networks are expanding injectable iron capacity to address malabsorption cases where oral therapy fails.
United Kingdom
MHRA enforcement of EMA GMP guidelines for active pharmaceutical ingredients determines market access for finished dosage form suppliers. Pharmacy chains are expanding self-selection aisles for effervescent formats targeting geriatric compliance and swallowing difficulties. The Southeast England pharmaceutical cluster maintains formulation capabilities that source ferrous gluconate API through European toll processors.
Ferrous Gluconate Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ferrous gluconate supply chain, with cGMP-certified foundries anchoring pharmaceutical-grade supply while commodity chemical traders serve nutritional supplement markets. The vendor base stratifies across three tiers: validated toll processors commanding premium positioning, regional chemical manufacturers competing on cost-engineered powder production, and bulk commodity traders serving uncertified over-the-counter segments. Dominant competitive moves include capacity expansion in cGMP-certified facilities and strategic partnerships between API suppliers and finished dosage form manufacturers seeking dual-registration efficiency.
Among North American cGMP-certified producers, Jost Chemical occupies a position representing validated pharmaceutical supply chain anchoring, while European precipitate-grade specialization is exemplified by Dr. Paul Lohmann. Cost-engineered powder production for emerging market generic manufacturers is represented by Aditya Chemicals, sitting within the competitive tier serving high-volume, price-sensitive procurement channels.
| Leading Market Players |
|---|
| Jost Chemical |
| Aditya Chemicals |
| Dr. Paul Lohmann |
| Sudeep Pharma |
| ShanPar |
| Global Calcium |
| Spectrum Chemical |
| Celtic Chemicals |
| ISALTIS |
| Others |
Supply & Pricing Matrix
Analytical chemist concentration in India's Maharashtra and Gujarat chemical belts compresses labor-cost differentials between pharmaceutical-grade and commodity-grade production, widening pricing-tier spreads as certified facilities command premiums for complexometric titration expertise that toll processors struggle to staff.
Pricing Analysis
Margin tightening in precipitate-grade injectable supply traces to REACH-mandated solvent substitution costs that European API manufacturers absorb while Asian competitors delay compliance investments. Three-tier pricing structure across cGMP-certified, precipitate-grade, and commodity powder levels separates validated pharmaceutical supply from generic tablet feedstock. Pricing pressure intensifies in oral solid dosage segments as ferrous sulfate substitution erodes ferrous gluconate's accessible market in over-the-counter channels. Government procurement consortia in India and China exhibit highest price sensitivity through centralized tendering, while hospital parenteral purchasers accept premium positioning for malabsorption protocols.
Supply Chain Analysis
Reverse-logistics flows for oxygen-sensitive dihydrate formulations center on nitrogen-flushed repackaging services that recover expired inventory from hospital pharmacy consortia for reprocessing by toll manufacturers. Supply concentrates in China for crystallization and spray-drying capacity, India for cost-engineered powder production, and Germany for precipitate-grade parenteral specialization. Raw material dependencies draw from ferrous sulfate feedstock, sodium gluconate intermediates, and ethanol-water crystallization solvents. Single-source vulnerability in Asian API supply exposes European formulation manufacturers to customs delays and currency volatility. Distribution runs through provincial hospital tendering platforms in China, government procurement channels in India, and validated toll-processing partnerships anchoring North American pharmaceutical supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum in ferrous gluconate supply chains accelerates as API suppliers pursue backward control over crystallization capacity and formulation manufacturers seek captive dihydrate production to secure batch release timelines against toll-processor queue constraints.
For Market Incumbents: Deploy cGMP certification investments to anchor pharmaceutical-grade supply chains as FDA bioequivalence tightening disqualifies uncertified competitors from generic tablet procurement. Expand precipitate-grade capacity in European toll-processing facilities to capture parenteral nutrition expansion in Chinese hospital networks. Fortify against ferrous sulfate substitution threat by emphasizing gastrointestinal tolerability differentiation in maternal health positioning. For New Entrants and Emerging Players: Begin with pediatric liquid formulation development targeting India's anganwadi nutrition centers where tablet compliance failures create procurement white space. Penetrate effervescent tablet channels in European pharmacy self-selection aisles as geriatric swallowing difficulties drive format switching. Pursue toll-processing partnerships with established cGMP facilities rather than greenfield certification investments to compress qualification timelines. For Investors and Strategic Acquirers: Re-rating potential sits with precipitate-grade specialists given parenteral nutrition expansion in Chinese hospital consortia and REACH-compliant solvent substitution capabilities that Asian competitors lack. Long-term viability favors manufacturers with dual USP-EP pharmacopeial registration efficiency as regulatory convergence reduces transatlantic market access costs. Monitor EMA-FDA harmonization progress and provincial tendering platform consolidation in Jiangsu and Guangdong as inflection indicators for contract manufacturing consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystallization Capacity | Captive dihydrate production secures batch release timelines against toll-processor queue constraints. |
| REACH-Compliant Solvent System Transition | Ethanol-water crystallization substitution preserves European market access as methanol-based protocols face authorization barriers. |
| Pediatric Liquid Formulation Development | Palatability-engineered drops address compliance gaps in India's government nutrition programs. |
| Dual Pharmacopeial Registration Investment | Converging USP-EP specifications reduce qualification costs for transatlantic API suppliers. |
| Provincial Hospital Consortium Partnership | Centralized tendering platforms in Jiangsu and Guangdong determine supplier qualification through volume commitments. |
Research Methodology
Multi-period observation of regulatory filing patterns, tender award disclosures, and capacity expansion announcements anchored the trend analysis, supplemented by interviews with pharmaceutical manufacturing executives, CDSCO regulatory affairs leads, hospital procurement managers at Chinese provincial consortia, and toll-processing facility directors. Secondary validation drew from FDA warning letters, EMA GMP inspection reports, USP and EP monograph revision notices, and Indian government tender databases. Bottom-up segment sizing triangulated against top-down market value estimates derived from import-export trade flows.
Segment-weighting across product type, end-user channel, formulation form, and packaging format informed the analytical framework, with regional regulatory clusters and certification-grade tiers as cross-cutting dimensions. CAGRs were derived from fitted growth curves applied to base-period consumption volumes, adjusted for government program procurement schedules and hospital network expansion trajectories. Industry-specific forecast inputs included bioequivalence study completion timelines and pharmacopeial harmonization implementation schedules.
Regulatory enforcement intensity shifts, government nutrition program funding reallocations, and toll-processor capacity utilization swings are the dominant revision risks that could alter trajectory assumptions. Practitioners should monitor FDA bioequivalence guidance updates, India's National Iron Plus Initiative budget allocations, and European REACH authorization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
UK Insect Repellent Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Global Silicone Defoamer Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Fixing Agent Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Cholesteryl Isostearate Market