
 Cloud Emulsions Market | 2026-2036
Cloud Emulsions Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Emulsions Market Outlook
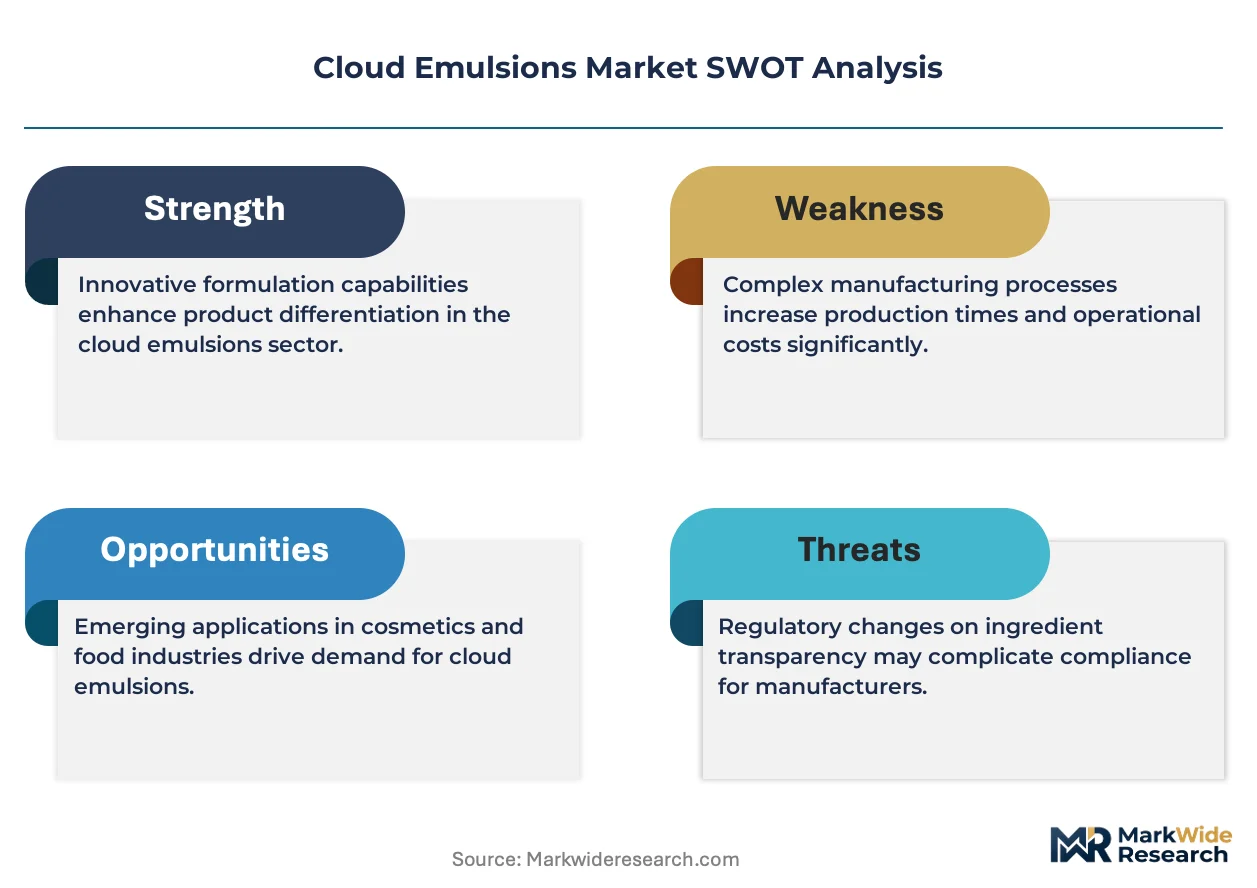
Personal care and cosmetics is restructuring cloud emulsion procurement priorities as brands seek transparent, stable delivery systems for volatile fragrance compounds and hydrophobic actives. Sensient Technologies Corporation leverages its color and flavor technology heritage to anchor cloud emulsion development for premium cosmetic applications. Kerry Group competes through integrated taste and nutrition expertise that extends into emulsion-based encapsulation systems for functional ingredients. Givaudan SA dominates fragrance delivery innovation, positioning cloud emulsions as critical to next-generation perfume architectures.
Cloud emulsions are thermodynamically stable or metastable dispersions of one liquid phase within another, typically oil-in-water or water-in-oil systems with droplet diameters ranging from 100 nanometers to 5 micrometers, engineered to create visually distinctive, turbid or opalescent appearances in finished products. Their primary industrial purpose spans cosmetic aesthetics, controlled-release pharmaceutical matrices, and uniform pigment distribution in waterborne coatings. Nanoemulsions lead technology investment due to superior optical clarity and bioavailability enhancement, while aqueous emulsions anchor volume demand across mass-market personal care. Microemulsions occupy specialized pharmaceutical niches where spontaneous formation and thermodynamic stability justify premium positioning over conventional homogenized systems.
EMA stability guidelines and REACH chemical registration frameworks govern excipient-grade cloud emulsions in European pharmaceutical and cosmetic supply chains, while FDA GRAS and ISO 22716 good manufacturing practice standards shape export-oriented production from US and Asian facilities. These regulatory layers elevate barrier costs for new entrants and reward incumbent suppliers with validated quality management systems. Stakeholders must monitor evolving PFAS restrictions and microplastic labeling requirements that threaten legacy non-aqueous emulsion formulations across European and North American markets.
Market Dynamics
Cloud emulsion formulation is restructuring around bio-based emulsifier substitution as REACH and EU Green Deal mandates eliminate petroleum-derived surfactants from cosmetic and pharmaceutical supply chains. This regulatory compression forces simultaneous reformulation of stability profiles, optical clarity standards, and manufacturing processes across European production facilities.
Growth Catalysts
- Nanoemulsion optical engineering:Droplet size reduction below 200 nanometers enables transparent fragrance architectures in premium skincare, replacing conventional turbid systems in German and French cosmetic lines.
- REACH chemical registration:Compliance deadlines accelerate solvent-free process adoption, creating captive demand for aqueous cloud emulsion platforms that eliminate volatile organic compound exposure.
- Pharmaceutical controlled-release matrices:Hydrophobic active encapsulation requirements in oral and topical drug delivery expand microemulsion procurement across EMA-governed manufacturing networks.
Market Restraints
- Plant-derived surfactant cost volatility:Rapeseed and coconut oil feedstock price swings compress margin structures for bio-based emulsifier producers in Northern European chemical clusters.
- Thermodynamic stability limitations:Kinetically stable nanoemulsions require energy-intensive high-pressure homogenization, constraining scale-up economics for mid-volume pharmaceutical contract manufacturers.
- PFAS restriction cascade:Fluorinated emulsifier bans in Germany, France, and the Netherlands force immediate reformulation of industrial coating applications without drop-in replacements.
Strategic Opportunities
- Microplastic labeling mandates:EU microplastic identification requirements position aqueous cloud emulsions as compliant alternatives to polymer-based encapsulation in rinse-off cosmetics.
- Waterborne coating pigment distribution:Industrial finishes manufacturers in the United Kingdom seek uniform opacity control that oil-in-water emulsion systems deliver without solvent-based viscosity modifiers.
- Pharmaceutical-biotech convergence:mRNA lipid nanoparticle manufacturing expertise transfers directly to cosmetic nanoemulsion engineering, opening cross-sector service contracts for CDMO facilities.
Industry Challenges
- Formulation chemist specialization gaps:Interfacial rheology and colloidal stability expertise scarcity constrains R&D throughput for mid-tier personal care brands accelerating clean-beauty transitions.
- ISO 22716 GMP certification timelines:Eighteen-to-twenty-four-month validation cycles delay market entry for Asian contract manufacturers targeting European cosmetic supply chains.
- Legacy equipment retrofit requirements:High-shear homogenizer and microfluidizer capital investments strain smaller fragrance houses transitioning from conventional mixing technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Emulsions Market |
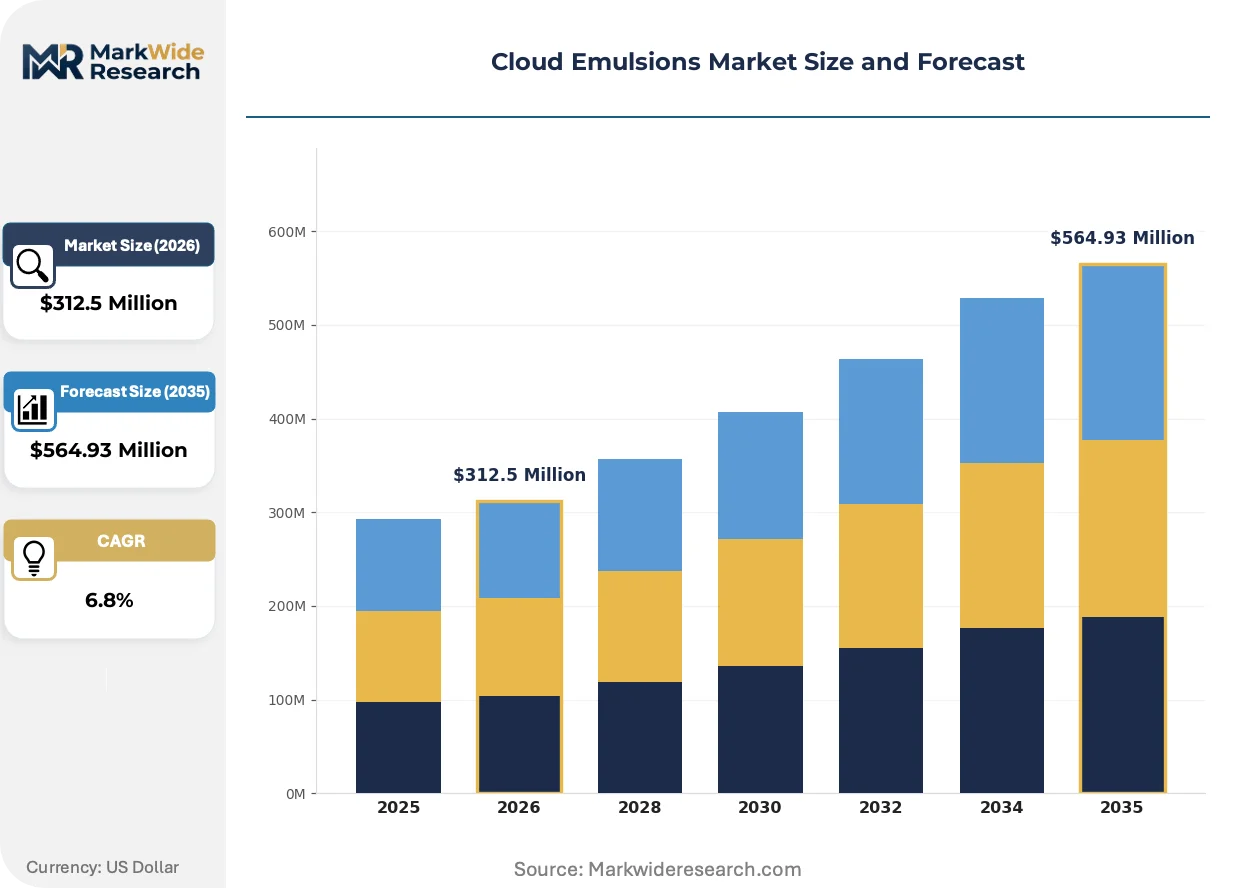
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Emulsions, Non-Aqueous Emulsions, Microemulsions, Nanoemulsions Application: Coatings, Personal Care, Pharmaceuticals, Food Processing End User: Cosmetics Manufacturers, Food Industry, Healthcare Providers, Paint Producers Technology: High-Pressure Homogenization, Ultrasonication, Microfluidization, Static Mixing |
| Companies Covered | Sensient Technologies Corporation, Döhler, Ingredion Incorporated, Kerry Group, Cargill Incorporated, Givaudan SA, International Flavors & Fragrances Inc., ADM, Firmenich SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Emulsions Market Strategic Shifts
Active ingredient delivery architecture is the dominant innovation frontier, with stability engineering and regulatory compliance now inseparable design constraints. Formulation science increasingly borrows from pharmaceutical lipid nanoparticle methodologies.
Microfluidic manufacturing is converging with continuous processing platforms to produce monodisperse nanoemulsions with coefficient of variation below 5%. Premium skincare brands in France and Germany adopt these systems for fragrance encapsulation that withstands temperature cycling. The technology is converging with in-line process analytical technology, collapsing batch release timelines from weeks to hours.
EU Green Deal chemical sustainability requirements now extend to emulsifier biodegradability testing under OECD 301 protocols. Industrial coatings and personal care sectors face synchronized compliance deadlines through 2027. German formulators respond fastest, integrating bio-based alkyl polyglucosides and lecithin derivatives ahead of regulatory enforcement.
Ingredient disclosure transparency now governs supplier selection for mass-market cosmetic brands. Clean-label preferences compress acceptable emulsifier portfolios to naturally derived, minimally processed options. United Kingdom retailers enforce this most stringently, delisting products with synthetic ethoxylated surfactants from premium shelf placements.
Cloud Emulsions Market Segmentation
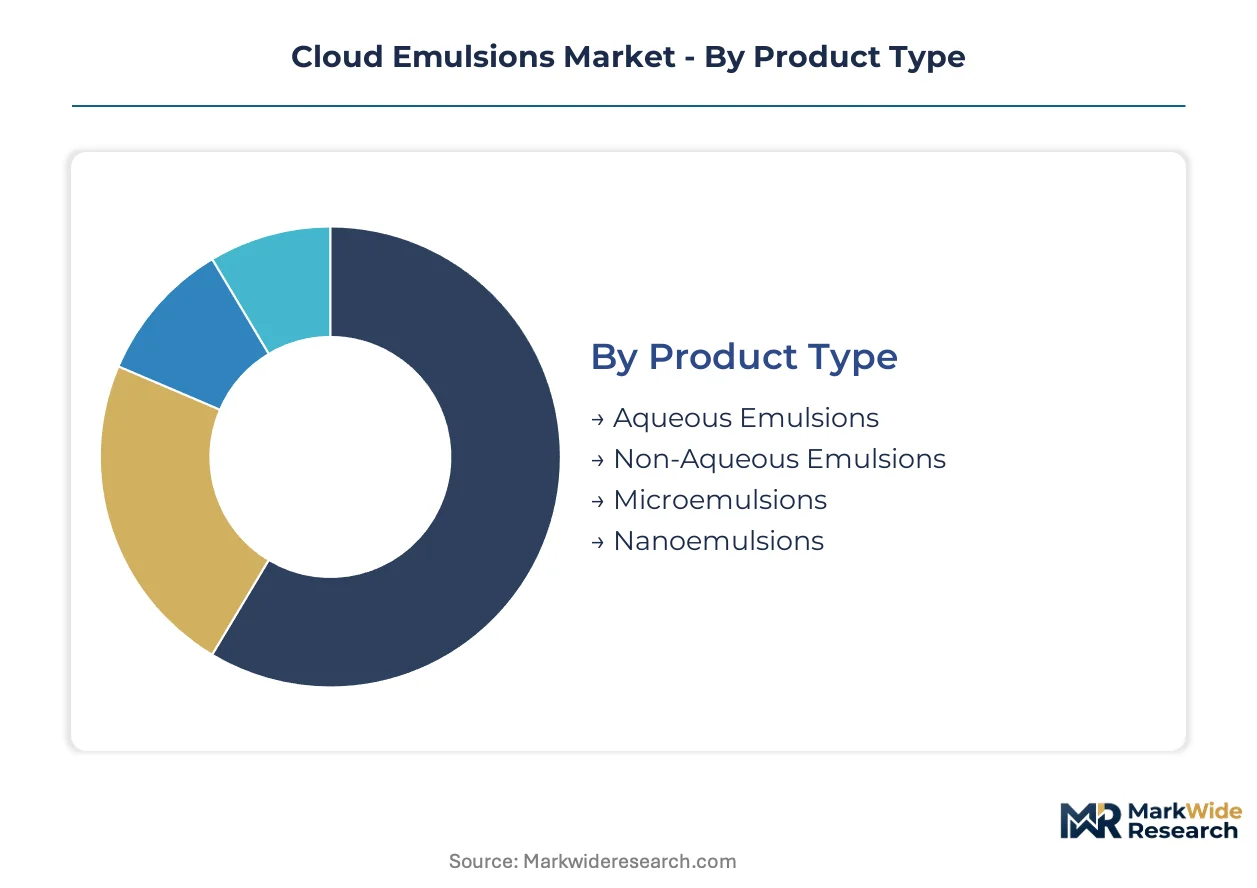
Cloud emulsion procurement decisions diverge sharply across buyer types, with pharmaceutical formulators prioritizing thermodynamic stability while cosmetics manufacturers emphasize optical clarity and label transparency. Technology selection and product architecture determine viable supplier pools for each end-use segment.
Product Type:
Buyers differentiate by droplet size requirements and stability profiles, with premium cosmetic brands demanding sub-200 nanometer clarity and pharmaceutical clients accepting broader size distributions for cost efficiency.
- Aqueous Emulsions:Oil-in-water systems with 1-5 micrometer droplets dominate mass-market personal care due to straightforward manufacturing and compatibility with water-based formulations. German and French cosmetics manufacturers anchor procurement volumes here, though REACH solvent-free mandates are forcing surfactant system redesigns.
- Nanoemulsions:Sub-200 nanometer droplets deliver transparent optical properties essential for premium skincare fragrance architectures. United Kingdom luxury brands concentrate demand for these systems as microplastic labeling requirements displace polymer-based alternatives.
- Non-Aqueous Emulsions:Solvent-based systems persist in industrial coating applications where waterborne alternatives fail on substrate compatibility.
- Microemulsions:Thermodynamically stable systems serve specialized pharmaceutical controlled-release matrices requiring spontaneous formation.
Aqueous emulsions lead volumes today; nanoemulsions are gaining share fastest.
Application:
End-use specifications create incompatible performance thresholds, with pharmaceutical EMA stability guidelines imposing stricter validation than cosmetic ISO 22716 requirements.
- Personal Care:Fragrance encapsulation and hydrophobic active delivery drive formulation complexity. United Kingdom retailers enforce clean-label standards that restrict acceptable emulsifier portfolios to bio-derived surfactants.
- Coatings:Uniform pigment distribution requirements in waterborne industrial finishes favor oil-in-water systems with controlled opacity. British manufacturers seek these platforms to eliminate solvent-based viscosity modifiers ahead of VOC regulations.
- Pharmaceuticals:Oral and topical drug delivery matrices demand validated excipient grades under EMA guidelines.
- Food Processing:Flavor and nutrient encapsulation applications require GRAS-compliant emulsifier systems.
Personal care anchors current demand; coatings applications show the steepest expansion trajectory.
End User:
Customer scale and certification requirements fragment supplier relationships, with multinational cosmetics manufacturers demanding integrated R&D support that smaller fragrance houses cannot match.
- Cosmetics Manufacturers:Premium skincare and color cosmetic brands in France and Germany drive nanoemulsion adoption for transparent fragrance systems. These buyers prioritize suppliers with validated ISO 22716 certification and bio-based emulsifier portfolios.
- Healthcare Providers:Hospital and clinic networks procure pharmaceutical-grade microemulsions for compounding and patient-specific formulations.
- Food Industry:Processors seek GRAS-compliant encapsulation for functional ingredients and flavor stability.
- Paint Producers:Industrial coatings manufacturers in the United Kingdom specify aqueous emulsion systems for uniform opacity control.
Cosmetics manufacturers command the largest procurement volumes; paint producers are expanding purchases most rapidly.
Technology:
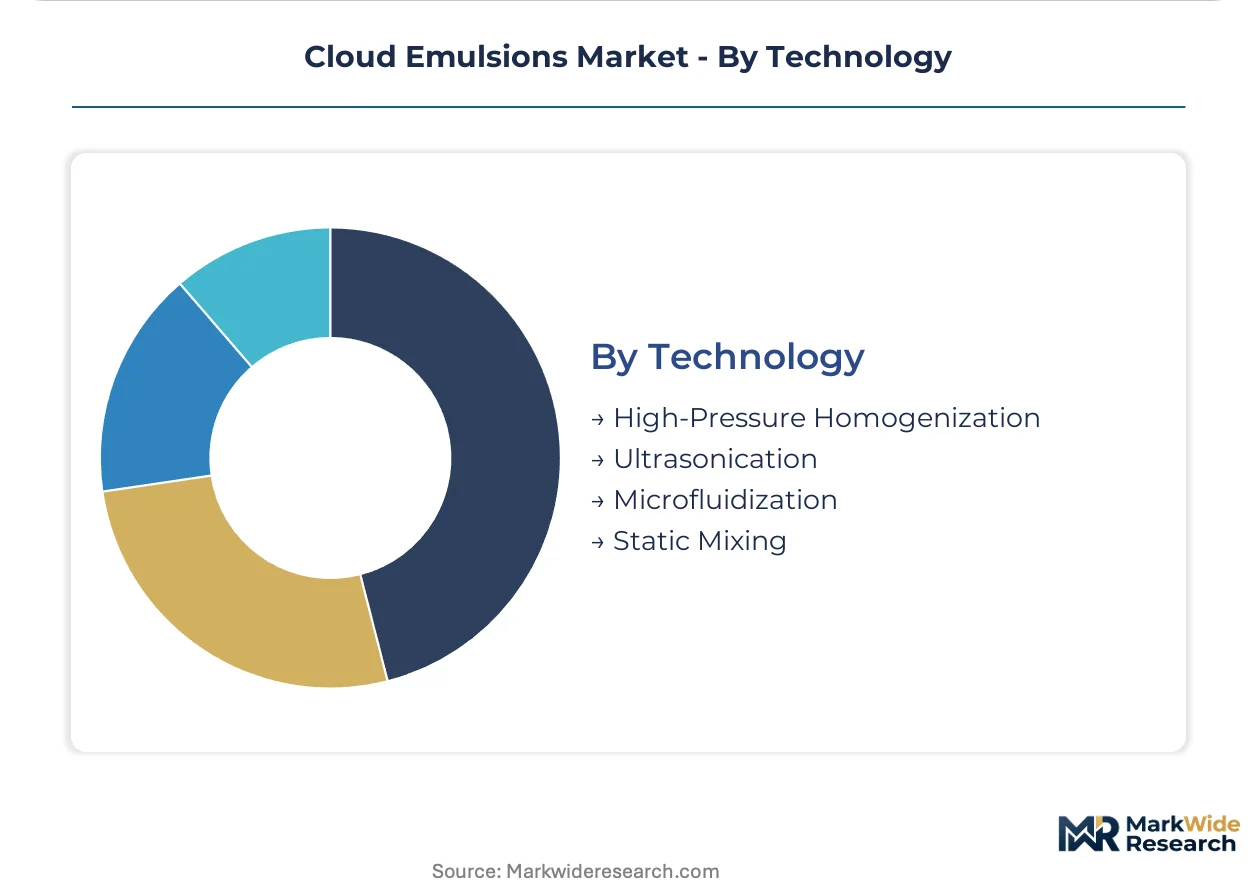
Capital intensity and throughput scalability separate viable production platforms, with continuous processing equipment requiring multi-year payback periods that constrain mid-tier manufacturer adoption.
- High-Pressure Homogenization:Energy-intensive mechanical disruption produces kinetically stable nanoemulsions with narrow droplet distributions. German pharmaceutical contract manufacturers favor this approach for EMA-validated production despite scale-up cost constraints.
- Microfluidization:Precision channel geometries generate monodisperse emulsions with coefficient of variation below 5%. French premium skincare brands adopt these systems for temperature-stable fragrance encapsulation.
- Ultrasonication:Acoustic cavitation suits laboratory-scale formulation development and small-batch cosmetic production.
- Static Mixing:No-moving-parts designs serve high-volume aqueous emulsion manufacturing with lower capital requirements.
High-pressure homogenization dominates installed capacity; microfluidization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as REACH compliance costs in Europe push contract manufacturing toward jurisdictions with lower registration burdens. Manufacturers are relocating aqueous emulsion capacity to exploit these cost-of-compliance gaps while maintaining EMA-grade quality systems for pharmaceutical exports.
Germany
Personal care brands in Cologne and Düsseldorf drive nanoemulsion procurement for transparent fragrance architectures. ECHA enforcement of REACH solvent-free mandates accelerates bio-based surfactant adoption across North Rhine-Westphalia chemical clusters. Bavarian pharmaceutical contract manufacturers invest in high-pressure homogenization capacity to serve EMA-validated microemulsion demand.
France
Luxury skincare houses in Grasse and Paris concentrate demand for sub-200 nanometer droplet systems. ANSM oversight of cosmetic ingredient safety elevates validation requirements for excipient-grade emulsions. The Auvergne-Rhône-Alpes region anchors microfluidic equipment manufacturing that supplies precision emulsion production lines.
United Kingdom
Industrial coatings manufacturers in Manchester and Birmingham seek oil-in-water systems for uniform pigment distribution. Retailer enforcement of clean-label standards restricts acceptable emulsifier portfolios to bio-derived surfactants. The Southeast England corridor hosts fragrance houses transitioning from conventional mixing to high-shear homogenization platforms.
United States
Pharmaceutical formulators in New Jersey and Massachusetts procure GRAS-compliant encapsulation systems for oral drug delivery. FDA oversight of excipient quality elevates barrier costs for European suppliers seeking market access. The Pacific Northwest hosts flavor and fragrance innovators borrowing lipid nanoparticle methodologies from mRNA manufacturing.
India
Cosmetics contract manufacturers in Maharashtra and Gujarat scale aqueous emulsion capacity for export to European personal care brands. CDSCO alignment with ICH guidelines streamlines excipient-grade validation for pharmaceutical applications. The Delhi-NCR corridor concentrates R&D facilities developing cost-optimized bio-based surfactant formulations.
Cloud Emulsions Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbent suppliers extend from core flavor and fragrance competencies into emulsion-based delivery systems. The vendor base stratifies across three tiers: multinational ingredient conglomerates with integrated R&D platforms, mid-scale regional specialists serving pharmaceutical contract manufacturers, and equipment-technology hybrid firms offering turnkey production systems. Strategic archetypes include heritage flavor houses leveraging encapsulation expertise, nutrition ingredient suppliers backward integrating into delivery technology, and precision manufacturing equipment vendors expanding downstream into formulation services. Technology licensing and geographic expansion represent the two dominant competitive moves, with Asian market entry and microfluidic patent acquisitions driving capital allocation.
Within the heritage flavor and fragrance tier, Givaudan SA and Firmenich SA exemplify suppliers whose aroma compound expertise translates directly into cloud emulsion architecture for volatile ingredient stabilization. Sensient Technologies Corporation occupies a position bridging color technology heritage with cosmetic delivery system innovation. Kerry Group represents the nutrition-to-delivery convergence archetype, extending taste and functional ingredient capabilities into encapsulation platforms. These three Swiss and Irish-registered entities anchor the premium-tier supplier landscape for European personal care and pharmaceutical procurement networks.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Döhler |
| Ingredion Incorporated |
| Kerry Group |
| Cargill Incorporated |
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| ADM |
| Firmenich SA |
| Others |
Value Chain & Pricing Dynamics
Colloidal formulation chemist concentration in Germany's North Rhine-Westphalia chemical clusters compresses premium-tier pricing spreads against economy-grade Asian imports, with labor-cost differentials between European high-pressure homogenization specialists and Indian static-mixing operators driving three-tier pricing stratification across personal care and pharmaceutical procurement networks.
Pricing Analysis
Distributor margins for excipient-grade cloud emulsions typically absorb 15-25 percent of manufacturer net pricing before retailer markup or direct-to-OEM volume discounts apply. Pricing stratifies across pharmaceutical-grade EMA-validated tiers, cosmetic ISO 22716-certified mid-tiers, and industrial economy grades, with certification-level and volume-scale differentiation as primary drivers. Cost compression in bio-based surfactant feedstocks is intensifying because rapeseed and coconut oil price volatility squeezes margin structures for European formulators. Small fragrance houses in the United Kingdom exhibit highest price sensitivity due to legacy equipment retrofit capital constraints, while German pharmaceutical contract manufacturers demonstrate lowest sensitivity given EMA validation requirements.
Supply Chain Analysis
Dual-sourcing qualification mandates from REACH-compliant European cosmetics manufacturers require active qualification of at least two bio-based emulsifier suppliers per production line. Geographic supply concentration centers on Germany, France, and India, with German chemical clusters anchoring high-pressure homogenization capacity, French facilities specializing in microfluidic precision systems, and Indian contract manufacturers scaling aqueous emulsion volume production. Raw material dependencies rest on rapeseed-derived alkyl polyglucosides, coconut oil-based surfactants, and pharmaceutical-grade lecithin derivatives. Single-source vulnerability in fluorinated emulsifier alternatives creates structural risk as PFAS restrictions cascade across Northern Europe. Distribution runs through integrated ingredient distributors serving personal care formulators, direct pharmaceutical CDMO relationships, and equipment-technology hybrid firms offering turnkey production platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud emulsions function as a stable compounder anchored by regulatory-mandated reformulation cycles that perpetually refresh demand for compliant delivery systems across European personal care and pharmaceutical supply chains.
For Market Incumbents: Anticipate margin compression from Asian contract manufacturers achieving ISO 22716 certification by securing backward integration into bio-based surfactant production and expanding microfluidic service capacity in Auvergne-Rhône-Alpes. Prioritize EMA-grade validation investments to defend pharmaceutical-grade positioning against emerging Indian CDMO competitors.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium French nanoemulsion systems and economy Indian aqueous emulsions offers white-space targeting for regional European specialists. Focus initial penetration on United Kingdom industrial coatings manufacturers seeking REACH-compliant solvent-free alternatives, leveraging static-mixing equipment partnerships to minimize capital requirements.
For Investors and Strategic Acquirers: Nutrition-ingredient conglomerates are the most active acquirer in this space, consolidating encapsulation technology platforms to extend taste and functional ingredient capabilities into cosmetic delivery systems. Evaluate mid-scale regional specialists with validated bio-based emulsifier portfolios over five-to-ten year holding periods. Monitor ECHA enforcement timelines as the critical inflection signal for accelerated solvent-free process adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Surfactants | Captive supply of rapeseed-derived alkyl polyglucosides insulates margin structures from agricultural commodity volatility. |
| Microfluidic Manufacturing Scale-Up | Precision channel geometries enable monodisperse nanoemulsion production for French premium skincare temperature-stable fragrance encapsulation. |
| EMA Validation Investment | Excipient-grade certification opens pharmaceutical controlled-release matrix procurement across German contract manufacturing networks. |
| REACH Compliance Service Bundling | Integrated solvent-free process consulting captures reformulation demand from personal care brands facing EU Green Deal deadlines. |
| Asian Market Entry Partnership | Joint ventures with Maharashtra and Gujarat contract manufacturers exploit cost-optimized production for European export supply chains. |
Study Parameters
Coverage spans Europe, North America, and Asia-Pacific, with primary inputs from each region combining structured interviews with formulation chemists, procurement leads at cosmetics manufacturers, pharmaceutical contract manufacturing officers, and equipment technology vendors with secondary validation. Secondary sources include ECHA REACH registration databases, FDA GRAS substance inventories, SEC 10-K filings from listed ingredient suppliers, and OECD 301 biodegradability test protocols. Bottom-up volume estimates from individual production facilities triangulate against top-down demand aggregation by end-use segment.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include droplet size tier, application category, end-user scale, and manufacturing technology platform, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derive from weighted least-squares fitting to historical trajectory data, incorporating bio-based emulsifier adoption curves and pharmaceutical lipid nanoparticle methodology transfer rates as industry-specific forecast inputs.
Caveats apply where ECHA enforcement acceleration, PFAS restriction expansion, or feedstock price dislocation could materially shift the outlook. Deviation in REACH solvent-free mandate implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Europe Squalene Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Marula Oil Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Toner Spray Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Silver Sulfate Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
North America Chromatography Resins Market
Specialty Chemicals
Phospholipid Market