
 Undecylenic Acid Market | 2026-2036
Undecylenic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Undecylenic Acid Market Outlook
Contract manufacturing and toll processing is consolidating as the dominant service layer in undecylenic acid commerce, shifting value capture from bulk chemical trading toward specification-controlled partnerships. Arkema Group leverages its European oleochemical infrastructure to sustain high-purity output for pharmaceutical clients. Jayant Agro-Organics Limited anchors Indian supply through backward integration into castor seed crushing and solvent extraction. Merck KGaA differentiates via pharmacopeia-grade certification and controlled-substance handling protocols.
Undecylenic acid is an eleven-carbon unsaturated fatty acid derived primarily from castor oil pyrolysis, functioning as a topical antifungal agent and polymer intermediate due to its terminal double bond and carboxylic acid functionality. The natural product type segment occupies the volume lead where castor oil supply chains remain cost-competitive against petrochemical alternatives. USP grade material commands premium positioning in pharmaceutical applications where compendial compliance determines market access. Personal care applications are recording the fastest expansion as formulators replace synthetic preservatives with naturally derived antimicrobials in skin and nail products.
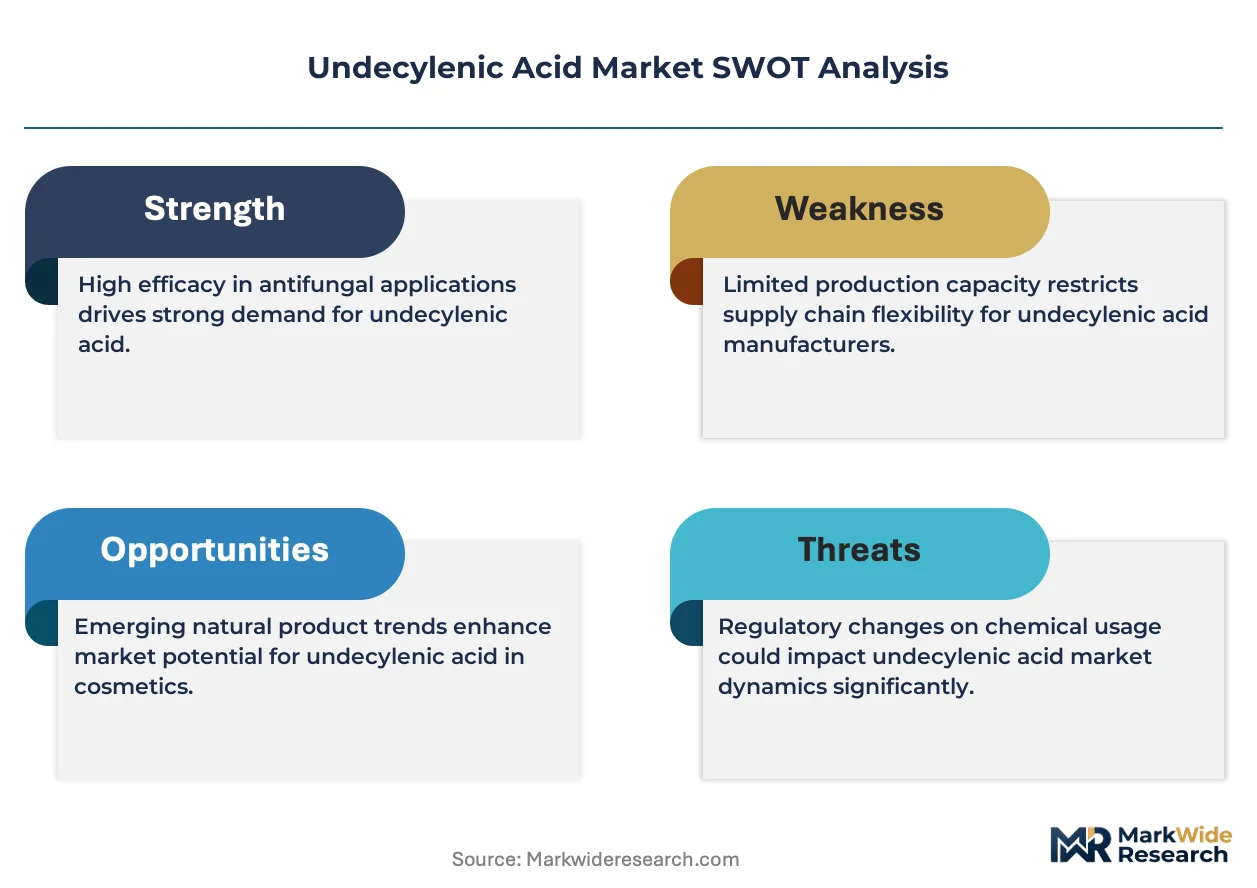
EPA registration requirements govern antifungal claims in the United States, while REACH restricts residual ricinoleic acid impurities in European cosmetic applications. India's CDSCO mandates specific monograph compliance for pharmaceutical-grade imports, creating a three-jurisdiction compliance burden for exporters. Stakeholders must monitor feedstock volatility in castor seed markets and the pace of bio-based certification adoption across personal care supply chains.
Market Dynamics
Castor oil pyrolysis economics and REACH purity mandates are forcing pharmaceutical and cosmetic buyers to consolidate procurement around specification-certified toll processors rather than spot-market traders.
Growth Catalysts
- REACH compliance tightening:European ECHA enforcement of residual ricinoleic acid limits in cosmetic-grade imports is accelerating demand for certified high-purity undecylenic acid from validated supply chains.
- Personal care formulators:Nail care and skin product manufacturers are substituting synthetic preservatives with undecylenic acid-derived natural antimicrobials to meet clean-label positioning requirements.
- Castor seed crushing clusters:Indian Gujarat-based solvent extraction infrastructure provides cost-competitive feedstock access that downstream derivative producers leverage for volume expansion.
Market Restraints
- Castor seed price volatility:Monsoon-dependent Indian agricultural output creates input cost instability that compresses margin predictability for pyrolysis operators.
- Pyrolysis capacity concentration:A limited number of European and Indian facilities control high-purity pharmaceutical-grade production, creating supply bottleneck risk during feedstock disruptions.
- Petrochemical alternative competition:Synthetic C11 unsaturated fatty acid routes from ethylene oligomerization threaten natural-origin positioning in cost-sensitive polymer intermediate applications.
Strategic Opportunities
- Brazilian cosmetic market penetration:ANVISA regulatory alignment with USP monographs creates import pathway expansion potential for certified Indian and European producers.
- Biopolymer intermediate demand:Nylon-11 and polyamide engineering resin manufacturers are sourcing bio-based C11 building blocks to satisfy automotive and textile sustainability mandates.
- Direct-to-formulator digital channels:Specialty chemical platforms are enabling small-batch pharmaceutical and cosmetic compounders to bypass traditional distributor markups.
Industry Challenges
- Pharmacopeia certification timelines:USP and EP monograph compliance testing for new production batches extends lead times by 8-12 weeks, constraining just-in-order fulfillment capabilities.
- Pyrolysis reactor retrofit capex:Upgrading existing castor oil cracking units to meet tightening EPA emission standards for thermal processing requires substantial capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Undecylenic Acid Market |
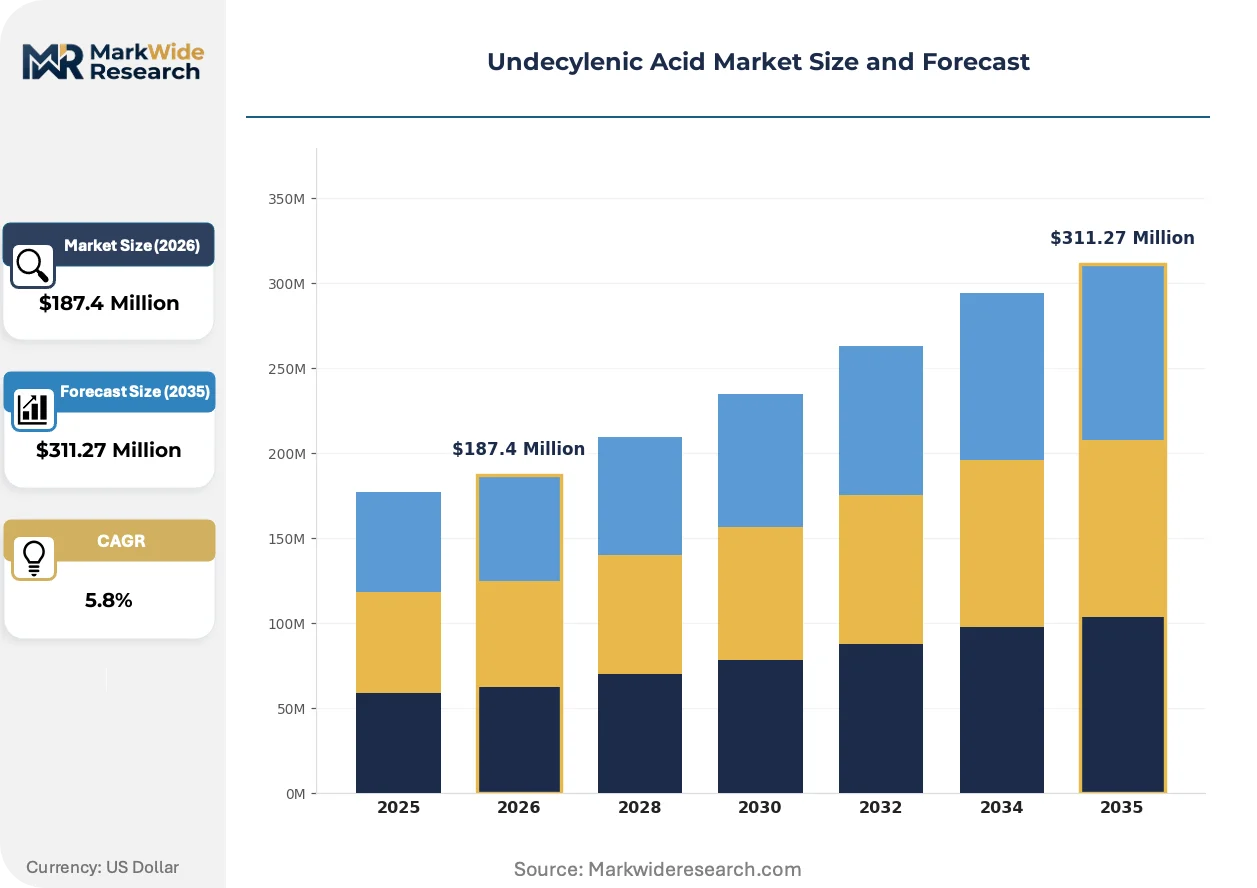
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, USP Grade, Cosmetic Grade Application: Antifungal, Personal Care, Pharmaceutical, Industrial End User: Healthcare Professionals, Manufacturers, Retailers, Consumers Delivery Mode: Topical, Oral, Injectable, Others |
| Companies Covered | TCI Chemicals (India) Pvt. Ltd., Acme Synthetic Chemicals, Arkema Group, Merck KGaA, BASF SE, Jayant Agro-Organics Limited, ITOH Oil Chemicals Co. Ltd., Vigon International, HOKOKU Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Undecylenic Acid Market Strategic Shifts
Process intensification and regulatory digitization are compressing the gap between raw castor oil and specification-certified undecylenic acid, reducing quality variance and enabling real-time chain-of-custody verification.
Continuous-flow pyrolysis reactor designs are unifying thermal cracking and fractional distillation into single-unit operations. European pharmaceutical intermediate producers are retrofitting batch plants with these systems to reduce ricinoleic acid carryover below 0.5%. This technology is unifying quality consistency across production campaigns that previously required extensive batch-to-batch requalification.
REACH Article 33 disclosure requirements and SCIP database obligations are forcing cosmetic ingredient importers to document full substance origin pathways. Formulators serving EU markets are now mandating blockchain-traceable certificates from Indian castor seed crushers. Small and mid-sized personal care brands lacking compliance infrastructure are exiting European distribution channels.
Compounders are consolidating annual undecylenic acid volumes into multi-year toll manufacturing agreements with pyrolysis operators who guarantee pharmacopeia-grade output. Nail care and topical antifungal product manufacturers in North America are prioritizing single-source partnerships over multi-vendor spot purchasing. This concentration is most pronounced among US-based private label skincare houses seeking EPA registration support from their chemical suppliers.
Undecylenic Acid Market Segmentation
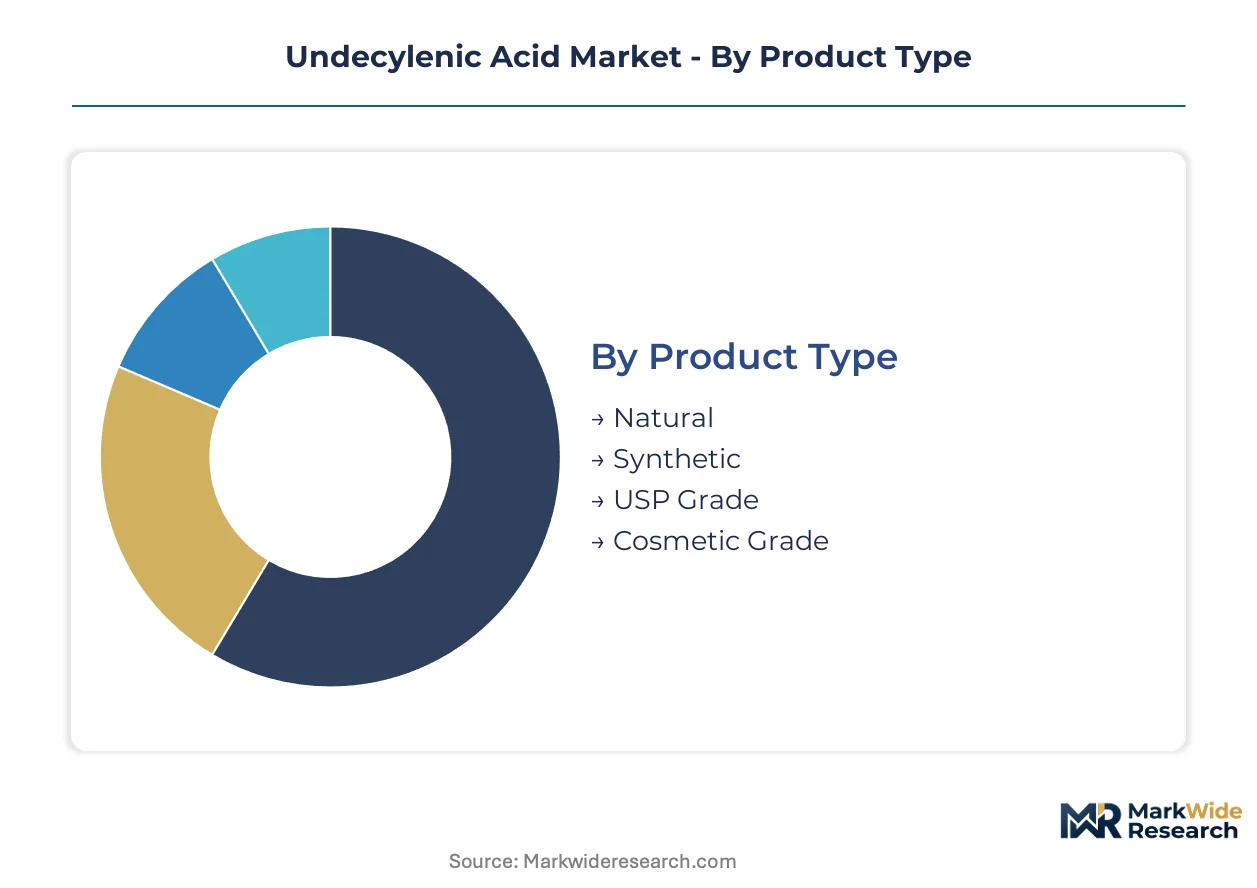
Undecylenic acid's bifurcation between standalone pharmaceutical applications and embedded industrial intermediates determines procurement specifications, certification requirements, and margin structures across each segment tier.
Product Type:
Natural-origin material dominates embedded supply chains where castor oil traceability satisfies bio-based certification requirements, while synthetic alternatives serve standalone applications with less stringent origin mandates.
- Natural:Derived from castor oil pyrolysis with terminal double bond positioning that enables polymerization chemistry. Indian Gujarat crushing clusters supply cost-competitive feedstock to European pharmaceutical toll processors seeking REACH-compliant ricinoleic acid residuals below 0.5%.
- USP Grade:Pharmacopeia-certified material meeting FDA and EP monograph specifications for topical antifungal formulations. CDSCO import requirements in India and EPA registration protocols in the United States restrict market access to validated batch documentation.
- Synthetic:Petrochemical C11 routes from ethylene oligomerization offer cost advantages in polymer intermediate applications where natural-origin positioning carries less premium.
- Cosmetic Grade:Intermediate purity tier serving personal care formulators balancing antimicrobial efficacy with clean-label marketing requirements.
Volume placements concentrate in Natural; the faster expansion belongs to USP Grade.
Application:
Cost-tier stratification separates premium pharmaceutical positioning from commodity industrial sourcing, with personal care occupying a mid-tier value band.
- Antifungal:Topical formulations targeting dermatophyte infections leverage undecylenic acid's fungistatic mechanism at skin-surface pH. EPA-registered products in the United States and pharmacy-channel distribution in Germany sustain demand concentration.
- Personal Care:Nail care and skin product formulators substitute synthetic preservatives with naturally derived antimicrobials to meet ANVISA-aligned clean-label requirements in Brazil and ECHA disclosure obligations in Europe.
- Pharmaceutical:Compounding pharmacies and OTC manufacturers require batch-specific certificates of analysis for each production lot.
- Industrial:Nylon-11 and polyamide resin producers source C11 building blocks for automotive and textile sustainability mandates.
Revenue concentrates in Antifungal; Personal Care is climbing the fastest.
End User:
Customer-type fragmentation creates divergent service requirements from just-in-time pharmaceutical supply to bulk industrial scheduling.
- Healthcare Professionals:Dermatology clinics and podiatry practices prescribe compounded topical formulations with patient-specific concentration adjustments.
- Manufacturers:Toll processors and formulation houses consolidate multi-year procurement agreements with guaranteed pharmacopeia-grade output.
- Retailers:Pharmacy chains and e-commerce platforms stock OTC antifungal products with national regulatory registrations.
- Consumers:Direct purchasers of nail care and skin health products respond to clean-label positioning and natural ingredient claims.
Procurement volume centers on Manufacturers; Healthcare Professionals are expanding most quickly.
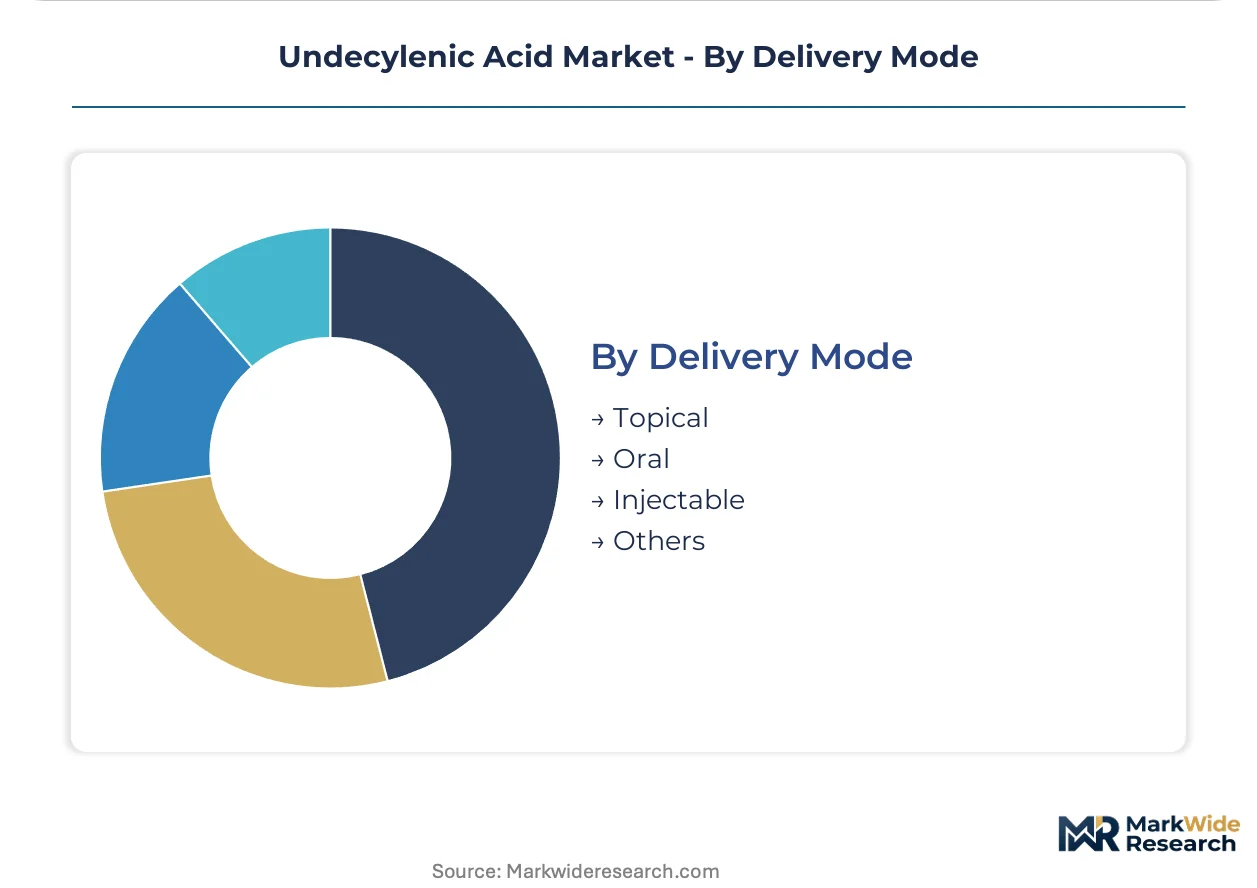
Delivery Mode:
Application-technology alignment restricts certain delivery formats to specific end-use segments based on bioavailability and regulatory clearance.
- Topical:Cream, ointment, and solution formulations dominate dermatological applications with established safety profiles and OTC availability.
- Oral:Limited systemic use due to gastrointestinal irritation potential; restricted to specific compounding protocols.
- Injectable:Negligible commercial presence; no approved parenteral formulations in major regulated markets.
- Others:Vapor-phase and sublingual experimental formats in early development for specialized therapeutic targets.
Volume concentrates in Topical; the steepest expansion trajectory belongs to Others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's castor seed crushing belt anchors global undecylenic acid feedstock supply, with European pharmaceutical toll processors and Brazilian cosmetic formulators drawing from this concentrated pyrolysis corridor.
United States
EPA-registered topical antifungal manufacturers and nail care formulators drive specification-grade procurement. FDA compounding pharmacy regulations enforce batch-specific documentation for dermatological applications. New Jersey and Pennsylvania host toll processing facilities serving OTC brands seeking controlled-substance handling protocols.
Germany
REACH Article 33 disclosure mandates and ECHA residual ricinoleic acid limits filter cosmetic-grade imports toward validated supply chains. EMA pharmacopeia compliance requirements structure pharmaceutical intermediate sourcing. The Rhine-Ruhr industrial corridor concentrates pyrolysis retrofit investments for emission-compliant thermal processing.
India
CDSCO import monographs and domestic castor oil availability position Gujarat as the dominant feedstock and derivative production zone. Solvent extraction clusters in Kutch and Saurashtra supply backward-integrated pyrolysis operators. Maharashtra pharmaceutical formulators consume USP-grade material for topical compounding.
Brazil
ANVISA alignment with USP monographs opens import pathways for certified Indian and European producers. Clean-label positioning in São Paulo and Rio de Janeiro personal care markets accelerates natural antimicrobial substitution. Southeast Brazilian cosmetic manufacturers consolidate procurement around blockchain-traceable certificates.
Japan
METI sustainability mandates and PMDA pharmaceutical standards shape bio-based intermediate demand. Polyamide resin producers in the Nagoya industrial zone source C11 building blocks for automotive textile applications. Osaka-based toll processors mediate between Indian feedstock and domestic formulation houses.
Undecylenic Acid Market Competitive Environment
Capital-heavy pyrolysis operators compete with asset-light specification certifiers across the undecylenic acid value chain. The vendor base stratifies between integrated castor oil crushers with captive cracking capacity and independent toll processors serving pharmaceutical compliance requirements. Three archetypes dominate: backward-integrated Indian feedstock controllers, European pharmacopeia-grade specialists, and diversified oleochemical majors with regional distribution networks. Competitive moves center on pyrolysis reactor retrofits for emission compliance and multi-year toll manufacturing agreements with guaranteed batch certification.
Among European pharmacopeia-grade specialists, Arkema Group and Merck KGaA exemplify specification-controlled positioning through compendial certification infrastructure. Jayant Agro-Organics Limited anchors the backward-integrated archetype with captive castor seed crushing and solvent extraction assets. These three entities represent distinct competitive vectors—European regulatory compliance, Indian feedstock dominance, and diversified chemical platform reach—rather than direct segment overlap.
| Leading Market Players |
|---|
| TCI Chemicals (India) Pvt. Ltd. |
| Acme Synthetic Chemicals |
| Arkema Group |
| Merck KGaA |
| BASF SE |
| Jayant Agro-Organics Limited |
| ITOH Oil Chemicals Co. Ltd. |
| Vigon International |
| HOKOKU Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Castor seed futures on Indian commodity exchanges cascade through pyrolysis economics into three distinct pricing tiers for downstream buyers. Monsoon-dependent harvest volatility in Gujarat creates input cost instability that compresses margin predictability for toll processors serving pharmaceutical and cosmetic formulators.
Pricing Analysis
Margin tightening in USP-grade material reflects REACH-mandated purity investments and extended pharmacopeia certification timelines. Three-tier pricing structure across pharmacopeia-certified, cosmetic-grade, and industrial-grade levels separates specification-controlled pharmaceutical supply from cost-sensitive polymer intermediate sourcing. Cost-down pressure on natural-origin material accelerates because synthetic C11 routes from ethylene oligomerization threaten bio-based positioning in price-driven applications. Industrial nylon-11 producers exhibit highest price sensitivity; compounding pharmacies and OTC manufacturers demonstrate lowest sensitivity due to regulatory switching costs.
Supply Chain Analysis
Spent catalyst recovery and pyrolysis residue reprocessing flows are emerging as circularity requirements under tightening EPA emission standards for thermal processing. Feedstock concentration in India, pharmaceutical toll processing in Germany, and formulation demand in the United States create a triangular supply architecture. Castor oil, ricinoleic acid, and C11 fraction dependencies draw from monsoon-dependent agricultural output in Gujarat's crushing belt. Single-source vulnerability concentrates in high-purity pharmaceutical-grade pyrolysis capacity. Distribution runs through specification-certified toll processors rather than spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into castor seed crushing and captive solvent extraction capacity is becoming the decisive competitive lever as feedstock volatility compresses margin predictability for non-integrated processors.
For Market Incumbents: Extend pharmacopeia-grade certification infrastructure to capture multi-year toll manufacturing agreements from nail care and topical antifungal compounders consolidating procurement. Deepen backward integration into Gujarat-based castor seed crushing assets to defend against monsoon-driven input cost spikes. Arkema Group and Merck KGaA exemplify specification-controlled positioning through compendial certification infrastructure. For New Entrants and Emerging Players: Specialty chemical platforms offer white-space entry points for small-batch pharmaceutical and cosmetic compounders seeking to bypass traditional distributor markups. Brazilian cosmetic manufacturers present the most penetrable geography given ANVISA regulatory alignment with USP monographs and clean-label positioning demand in São Paulo and Rio de Janeiro markets. Direct-to-formulator digital channels provide the lowest-friction go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor Indian pyrolysis operators with captive castor oil supply during periods of feedstock price volatility. Long-term viability over the coming decade hinges on emission-compliant reactor retrofit completion and blockchain-traceable supply chain certification adoption. Monitor ECHA enforcement patterns for residual ricinoleic acid limits as an inflection indicator for high-purity specification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Seed Crushing | Captive Gujarat feedstock supply insulates margin predictability from monsoon volatility. |
| Continuous-Flow Pyrolysis Reactor Retrofit | Single-unit thermal cracking and distillation cuts ricinoleic acid carryover below REACH thresholds. |
| Pharmacopeia-Grade Certification Investment | USP and EP monograph compliance unlocks multi-year toll agreements with OTC manufacturers. |
| Blockchain-Traceable Supply Chain Documentation | SCIP database compliance enables continued EU cosmetic ingredient market access. |
| Direct-to-Formulator Digital Channel Development | Specialty chemical platforms bypass distributor markups for small-batch compounders. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with pyrolysis plant managers, cosmetic formulators, pharmaceutical procurement leads, and castor oil crushers provided operational validation. ECHA enforcement reports, CDSCO import monographs, EPA registration databases, and Indian commodity exchange price series supplied quantitative benchmarks. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Reconciliation of customs export volumes, toll processing capacity utilization, and end-use consumption patterns structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application end-use, and regional regulatory cluster. CAGRs derived from fitted trend extrapolation with scenario-weighted adjustments for feedstock volatility and certification timeline delays. Pyrolysis reactor retrofit capex cycles and bio-based certification adoption curves served as industry-specific forecast inputs.
Caveats apply where monsoon failure patterns, REACH enforcement intensity shifts, or synthetic C11 route cost breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about castor seed yield stability and emission regulation implementation pace. Practitioners should monitor ECHA residual ricinoleic acid limit enforcement and Indian agricultural output reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Taurine Market