
 Isostearyl Alcohol Market | 2026-2036
Isostearyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Isostearyl Alcohol Market Foresight
Specialty chemical distribution is tilting toward direct manufacturer-formulator relationships as cosmetic compounders seek shorter lead times. Croda International Plc leverages its oleochemical heritage to sustain premium positioning in emollient alcohols. Kao Corporation anchors Asian supply through integrated fatty alcohol operations. BASF SE competes on scale, while Evonik Industries AG differentiates through high-purity grades for sensitive-skin applications.
Isostearyl alcohol is a branched-chain C18 fatty alcohol synthesized via hydrogenation of isostearic acid or microbial fermentation routes, valued for its low melting point, oxidative stability, and silky skin-feel in topical formulations. Cosmetic Grade dominates value pools due to stringent purity thresholds and brand-certification requirements, while Pharmaceutical Grade commands the fastest expansion as topical drug delivery systems adopt lipid-based excipients. Liquid form leads volume throughput, though emulsion formats gain share in waterless beauty formulations.
REACH registration governs European market access, while FDA oversight shapes United States pharmaceutical-grade pathways, and China's GB standards dictate import specifications for cosmetic raw materials. Compliance costs favor producers with dedicated regulatory affairs teams and multi-jurisdiction dossier capabilities. Stakeholders must monitor biotechnology scale-up economics and biobased-content certification schemes as these variables reset cost curves and customer qualification protocols.
Market Dynamics
Biotechnology-derived production routes are compressing cost curves for branched-chain fatty alcohols while REACH compliance pressures force reformulation cycles across European personal care supply chains.
Growth Catalysts
- REACH-driven emollient substitution:Formulators across Germany, France, and Italy are replacing restricted linear alcohols with isostearyl grades to maintain product registration. This regulatory pull sustains premium pricing for compliant supply.
- Lipid-based topical drug delivery:Pharmaceutical compounders are adopting high-purity branched alcohols as permeation enhancers in transdermal patches and dermatological creams.
- Microbial fermentation scale-up:Industrial biotechnology platforms in the Netherlands and Denmark are achieving titers that challenge conventional oleochemical hydrogenation economics.
Market Restraints
- Feedstock concentration risk:Isostearic acid precursors derive primarily from castor oil supply chains concentrated in India, exposing processors to monsoon-dependent harvest volatility and export duty fluctuations.
- Specialized hydrogenation asset scarcity:High-pressure catalytic hydrogenation capacity for branched feedstocks is limited to a handful of European and Japanese chemical parks, creating bottleneck risk.
- Glycerol ether competition:Lower-cost alkyl polyglucosides and Guerbet alcohols are capturing share in mass-market rinse-off applications where skin-feel differentiation matters less.
Strategic Opportunities
- Waterless beauty formulation surge:Anhydrous solid shampoo and conditioner bars are proliferating in UK and Scandinavian markets, favoring liquid emollients with low melting points and oxidative stability.
- Biobased certification premiums:USDA BioPreferred and EU Ecolabel compliance pathways are opening price-realization advantages for fermentation-derived grades with verifiable renewable carbon content.
- Sensitive-skin pharmaceutical positioning:High-purity grades meeting USP-NF monographs are penetrating atopic dermatitis and pediatric formulations where irritancy thresholds are stringent.
Industry Challenges
- Multi-jurisdiction dossier management:Maintaining concurrent REACH, FDA Drug Master File, and China NMPA cosmetic raw material registrations demands dedicated regulatory affairs headcount and 18-24 month approval timelines.
- Bioprocess scale-up talent scarcity:Fermentation optimization for C18 branched alcohols requires metabolic engineering expertise concentrated in academic and startup ecosystems, not traditional oleochemical operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isostearyl Alcohol Market |
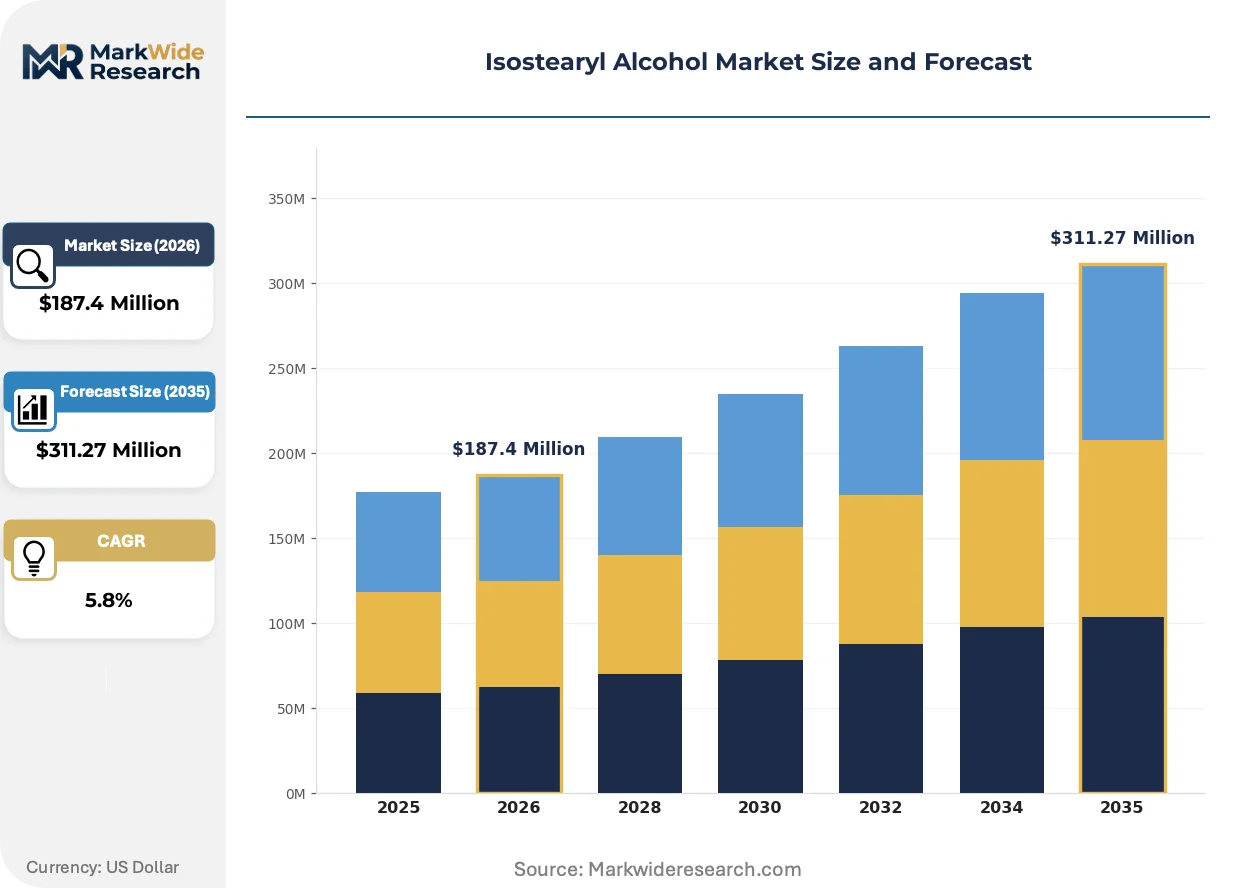
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
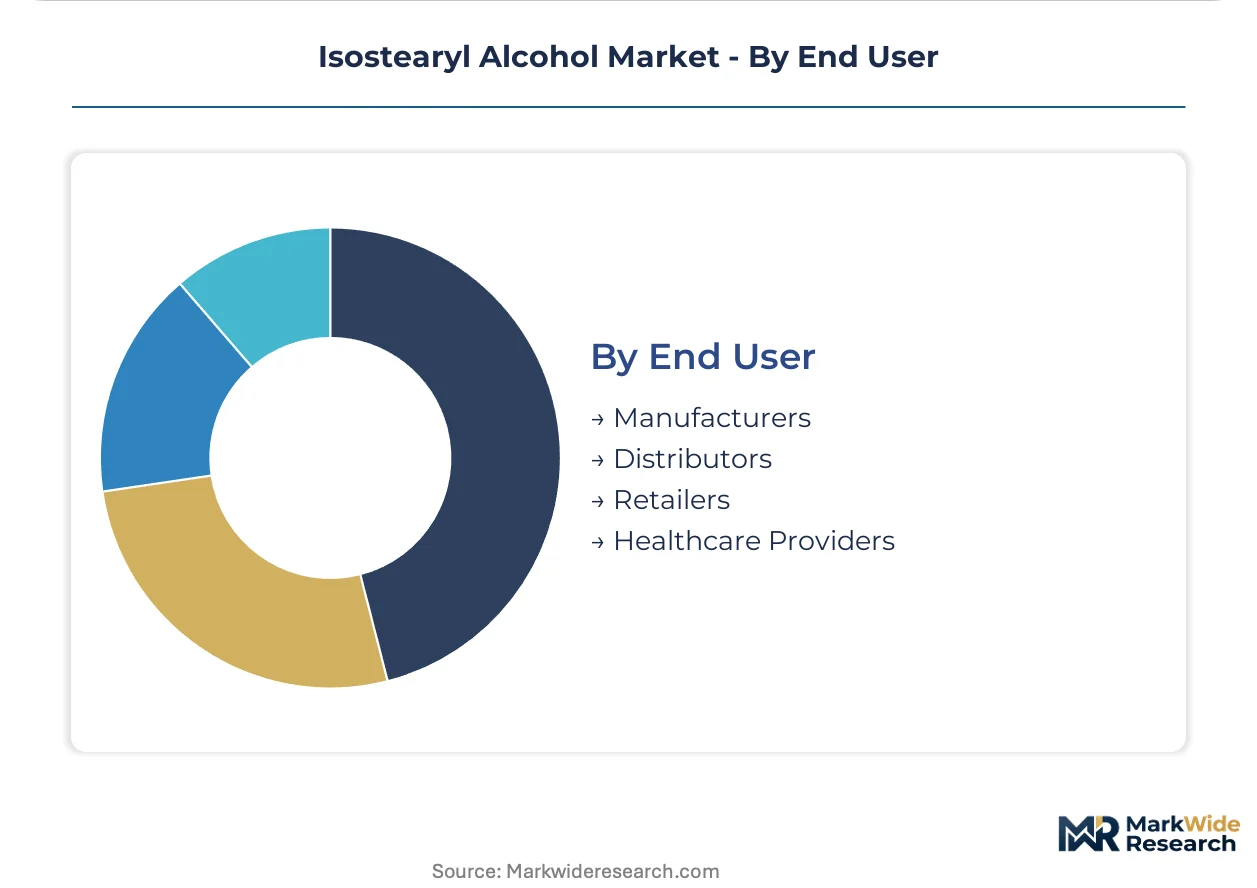
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Pharmaceutical Grade, Food Grade Application: Personal Care, Cosmetics, Pharmaceuticals, Lubricants Form: Liquid, Powder, Emulsion, Gel End User: Manufacturers, Distributors, Retailers, Healthcare Providers |
| Companies Covered | Nissan Chemical America Corporation, Kao Corporation, Croda International Plc, KLK OLEO, Emery Oleochemicals, Oleon NV, BASF SE, Evonik Industries AG, Jarchem Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isostearyl Alcohol Market Shifts & Advancements
Production technology, compliance frameworks, and procurement behavior are converging to reshape competitive positioning in specialty fatty alcohol supply.
Microbial cell factories engineered for branched-chain lipid accumulation are hybridizing conventional oleochemical assets with biotechnology economics. Specialty chemical producers in Northern Europe are retrofitting hydrogenation trains to accept fermentation-derived feedstocks. This technology convergence is collapsing the historical cost gap between petrochemical and biobased routes while preserving performance specifications.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-dependent processing equipment retrofits across German and Dutch chemical parks. Industrial cooling systems for low-temperature crystallization steps face compliance-driven replacement cycles. Cosmetic-grade producers with captive renewable energy contracts are capturing operational cost advantages against grid-dependent competitors.
Direct manufacturer-formulator relationships are displacing layered distribution networks in cosmetic raw materials. Compounders in France and Italy are qualifying single-source supply agreements to compress lead times and secure batch traceability. This channel restructuring is most pronounced in premium skincare verticals where formulation confidentiality and rapid prototyping cycles command priority.
Isostearyl Alcohol Market Segmentation

Isostearyl alcohol's branched-chain structure creates distinct performance profiles across purity tiers and physical forms. Segmentation reflects how formulators match oxidative stability, melting point, and regulatory compliance to specific end-use requirements.
Product Type:
Mature emollient grades anchor current revenue pools while emerging bioprocess certifications reshape premium positioning.
- Cosmetic Grade:Stringent purity thresholds exclude C16 and linear C18 contaminants to ensure silky skin-feel in leave-on formulations. Demand concentrates in German and French skincare compounders reformulating around REACH restrictions on conventional fatty alcohols.
- Pharmaceutical Grade:USP-NF monograph compliance enables use as permeation enhancers in transdermal patches and dermatological creams. Pediatric and atopic dermatitis applications in the United States drive qualification protocols for irritancy-sensitive patient populations.
- Industrial Grade:Standard oxidative stability specifications serve lubricant and metalworking fluid applications where cost efficiency outweighs sensory performance.
- Food Grade:Limited adoption in food-contact coatings and release agents; regulatory dossier requirements restrict supplier entry.
Cosmetic Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Customer procurement patterns split between formulation confidentiality priorities in beauty and technical specification rigor in drug delivery.
- Personal Care:Anhydrous solid shampoo and conditioner bars in UK and Scandinavian markets favor low-melting liquid emollients with oxidative stability for waterless processing.
- Cosmetics:Premium skincare verticals in Italy and France demand batch traceability and single-source supply agreements that compress prototyping cycles.
- Pharmaceuticals:Lipid-based excipient adoption for transdermal systems requires high-purity grades meeting multi-jurisdiction dossier standards.
- Lubricants:Industrial metalworking applications prioritize cost-efficient Industrial Grade supply with standard oxidative stability specifications.
Personal Care commands the largest absolute volume; Pharmaceuticals is expanding most quickly on excipient diversification.
Form:
Processing economics and formulation compatibility determine physical state selection across manufacturing workflows.
- Liquid:Dominant volume format enabling direct incorporation into oil-phase emulsions without melting infrastructure; preferred for continuous processing lines.
- Powder:Spray-dried grades serve powder-to-liquid personal care formats and solid dosage pharmaceutical applications requiring precise dosing.
- Emulsion:Pre-dispersed formats gain share in waterless beauty formulations where cold-process compatibility reduces energy inputs.
- Gel:Structured delivery systems for targeted pharmaceutical applications requiring controlled release kinetics.
Liquid retains volume leadership; Emulsion gains share fastest on cold-process formulation trends.
End User:
Channel restructuring is compressing traditional distribution layers as direct manufacturer relationships displace intermediaries.
- Manufacturers:Specialty chemical producers and finished goods formulators drive specification-setting and batch qualification protocols.
- Distributors:Layered networks face displacement in premium verticals where lead time compression and confidentiality requirements favor direct supply.
- Retailers:Clean beauty positioning and biobased certification visibility influence upstream ingredient selection criteria.
- Healthcare Providers:Hospital and clinic procurement of topical drug products transmits USP-NF compliance requirements through pharmaceutical supply chains.
Manufacturers retain volume leadership; Healthcare Providers show the steepest demand expansion on pharmaceutical-grade adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European buyers absorb 15-20% price premiums over Asian spot markets due to REACH compliance costs and certification requirements. German specialty chemical clusters leverage this pricing power through integrated oleochemical infrastructure. Biotechnology scale-up in Denmark and the Netherlands threatens to erode this margin advantage over the forecast window.
Germany
Personal care formulators in Hamburg and Cologne drive pharmaceutical-grade qualification for atopic dermatitis applications. ECHA enforcement of REACH SVHC candidate list updates accelerates substitution cycles away from linear C18 alcohols. The Marl Chemical Park hosts hydrogenation capacity that processes Indian castor oil derivatives into high-purity branched alcohols for export.
United States
FDA Drug Master File pathways attract transdermal patch manufacturers seeking permeation enhancers with documented safety profiles. The EPA's TSCA Section 5 notification requirements govern new bioprocess introductions. New Jersey and Ohio chemical corridors concentrate cosmetic compounders qualifying single-source supply agreements for premium skincare verticals.
Japan
METI's biomanufacturing roadmap funds microbial fermentation platforms for C18 branched lipids at titers challenging conventional hydrogenation. PMDA consultation procedures shape pharmaceutical-grade monograph development for sensitive-skin applications. Osaka-Kobe industrial zone maintains specialized high-pressure catalytic hydrogenation assets for cosmetic alcohol production.
China
NMPA cosmetic raw material registration drives import specification rigor for European and Japanese suppliers. GB standards for surfactant purity create compliance barriers for lower-grade producers. Yangtze River Delta formulators in Shanghai and Suzhou integrate isostearyl alcohol into waterless beauty formulations for domestic clean beauty brands.
India
Castor oil harvest volatility in Gujarat exposes global supply chains to monsoon-dependent price swings. DGFT export duty fluctuations on oleochemical derivatives reshape processor economics. Mumbai-Pune chemical belt hosts hydrogenation facilities serving both domestic personal care manufacturers and European pharmaceutical compounders.
Isostearyl Alcohol Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in hydrogenation and fermentation technology. The vendor base stratifies between multinational oleochemical conglomerates with integrated fatty alcohol operations and regional processors dependent on merchant isostearic acid supply. Two archetypes dominate: biotechnology platforms pursuing fermentation-derived cost curves, and legacy hydrogenation specialists defending premium positioning through regulatory dossier depth. Competitive moves concentrate on bioprocess licensing partnerships and retrofitting existing hydrogenation trains to accept mixed feedstock slates.
Within the integrated oleochemical tier, Croda International Plc and Kao Corporation exemplify contrasting geographic anchoring strategies. BASF SE occupies a position emphasizing scale economics across multiple fatty alcohol grades. Evonik Industries AG represents the high-purity specialization archetype targeting pharmaceutical and sensitive-skin cosmetic applications. These three companies collectively illustrate how regulatory compliance capabilities and feedstock integration depth determine tier placement.
| Leading Market Players |
|---|
| Nissan Chemical America Corporation |
| Kao Corporation |
| Croda International Plc |
| KLK OLEO |
| Emery Oleochemicals |
| Oleon NV |
| BASF SE |
| Evonik Industries AG |
| Jarchem Industries Inc. |
| Others |
Supply & Pricing Matrix
Indian castor oil harvests in Gujarat feed the isostearic acid precursor stream that European hydrogenation specialists convert into premium branched alcohol grades. This upstream geographic lock concentrates margin capture with processors possessing high-pressure catalytic assets in Germany and Japan, while formulators downstream absorb REACH-driven cost premiums for compliant supply.
Pricing Analysis
Configured-to-order pricing for fermentation-derived grades with USDA BioPreferred certification commands spreads over standard hydrogenation routes. Contract-based long-term offtake dominates volume procurement, with price differentiation driven by purity certification tier and biobased-content verification. Pricing pressure stems from glycerol ether substitutes capturing mass-market rinse-off share. Mass-market compounders exhibit highest price sensitivity; pharmaceutical and premium skincare verticals accept premium positioning for dossier depth and batch traceability.
Supply Chain Analysis
Extended payment terms from European specialty chemical distributors to Indian castor oil processors have become standard working-capital practice. Supply concentrates in India for feedstock, Germany and Japan for hydrogenation, and the Netherlands for emerging fermentation capacity. Raw material dependencies center on castor oil derivatives, high-pressure hydrogenation catalysts, and microbial fermentation feedstocks. Single-source vulnerability runs through specialized hydrogenation asset scarcity. Distribution runs through direct manufacturer-formulator relationships displacing layered intermediaries in premium cosmetic verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory dossier management services attach to every ton of pharmaceutical-grade supply, with compliance-retainer contracts expanding faster than base chemical volumes. This recurring-revenue layer rewards producers investing in multi-jurisdiction registration capabilities.
For Market Incumbents: Build regulatory dossier depth as the primary moat against biotechnology entrants. Deepen backward integration into castor oil processing in India to hedge monsoon volatility. Secure dedicated hydrogenation capacity through long-term offtake agreements with German and Japanese chemical parks before fermentation scale-up erodes asset premiums. For New Entrants and Emerging Players: Build out microbial fermentation platforms targeting pharmaceutical-grade purity thresholds as the most penetrable white space. Denmark and the Netherlands offer established bioprocess infrastructure with METI and Horizon Europe funding access. Lead with biobased certification premiums rather than cost parity to secure qualification with clean beauty formulators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European oleochemical processors holding REACH registration portfolios but limited fermentation expertise. Five-to-ten year viability hinges on successful technology convergence execution. Watch biotechnology titer achievements against conventional hydrogenation economics as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Processing | Captive supply from Gujarat farms mitigates monsoon-driven price volatility for European hydrogenation assets. |
| Fermentation Platform Scale-Up | Danish and Dutch biotech clusters challenge German chemical park economics through microbial C18 branched lipid titers. |
| Multi-Jurisdiction Dossier Investment | Concurrent REACH, FDA Drug Master File, and NMPA registrations open pharmaceutical-grade premium pools. |
| Direct Manufacturer-Formulator Agreements | Single-source supply contracts with French and Italian compounders compress lead times and protect formulation confidentiality. |
| Biobased Certification Program | USDA BioPreferred and EU Ecolabel compliance enable price realization advantages for fermentation-derived grades. |
Research Methodology
Desk research of ECHA registration databases, FDA Drug Master File listings, and specialty chemical trade flow data preceded structured interviews with hydrogenation plant managers, cosmetic procurement leads, pharmaceutical regulatory affairs directors, and biotechnology platform engineers. Primary fieldwork with downstream formulators in Germany, France, and Italy validated secondary estimates of substitution rates away from linear C18 alcohols. Bottom-up volume builds across grade tiers and end-use segments were triangulated against top-down trade data and producer capacity disclosures.
Assumptions held REACH SVHC candidate list expansion schedules and FDA excipient monograph stability fixed, while biotechnology titer improvement rates and castor oil harvest yields were varied across sensitivity scenarios. Segmentation modeling spanned grade tier, end-use industry, physical form, and regional production hub. CAGRs were derived from regression analysis of historical price-volume relationships and projected substitution elasticities. Forecast inputs included hydrogenation capacity utilization rates and fermentation platform commissioning timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by biotechnology platforms or sudden DGFT export duty shifts would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Naphthol AS-IRG Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Asia-Pacific UV Stabilizers Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market