
 Specialty Methacrylate Market | 2026-2036
Specialty Methacrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Methacrylate Market Intelligence
Direct sales channels to large-volume end-users in the automotive and construction sectors are fragmenting as specialized distributors gain share. Arkema differentiates through its portfolio of high-performance polymers for niche applications. Evonik Industries AG leverages its significant manufacturing scale to compete on cost and supply reliability in commodity-grade methacrylates.
Specialty methacrylates are a class of esters derived from methacrylic acid, engineered for specific performance characteristics. These monomers, such as hydroxyethyl methacrylate, feature functional groups that enable cross-linking and enhanced properties like adhesion, durability, and optical clarity in polymers. Within applications, coatings and adhesives represent mature, high-volume segments. Demand for Glycidyl Methacrylate is expanding for use in electronics encapsulation and advanced composites.
The European Union’s REACH regulation and the US EPA's Toxic Substances Control Act (TSCA) impose stringent registration and safety data requirements on methacrylate producers. In parallel, China's GB standards dictate product quality and purity for materials sold into its domestic market. Navigating this complex, multi-jurisdictional regulatory environment is a critical determinant of a supplier's global market access and competitive success.
Market Dynamics
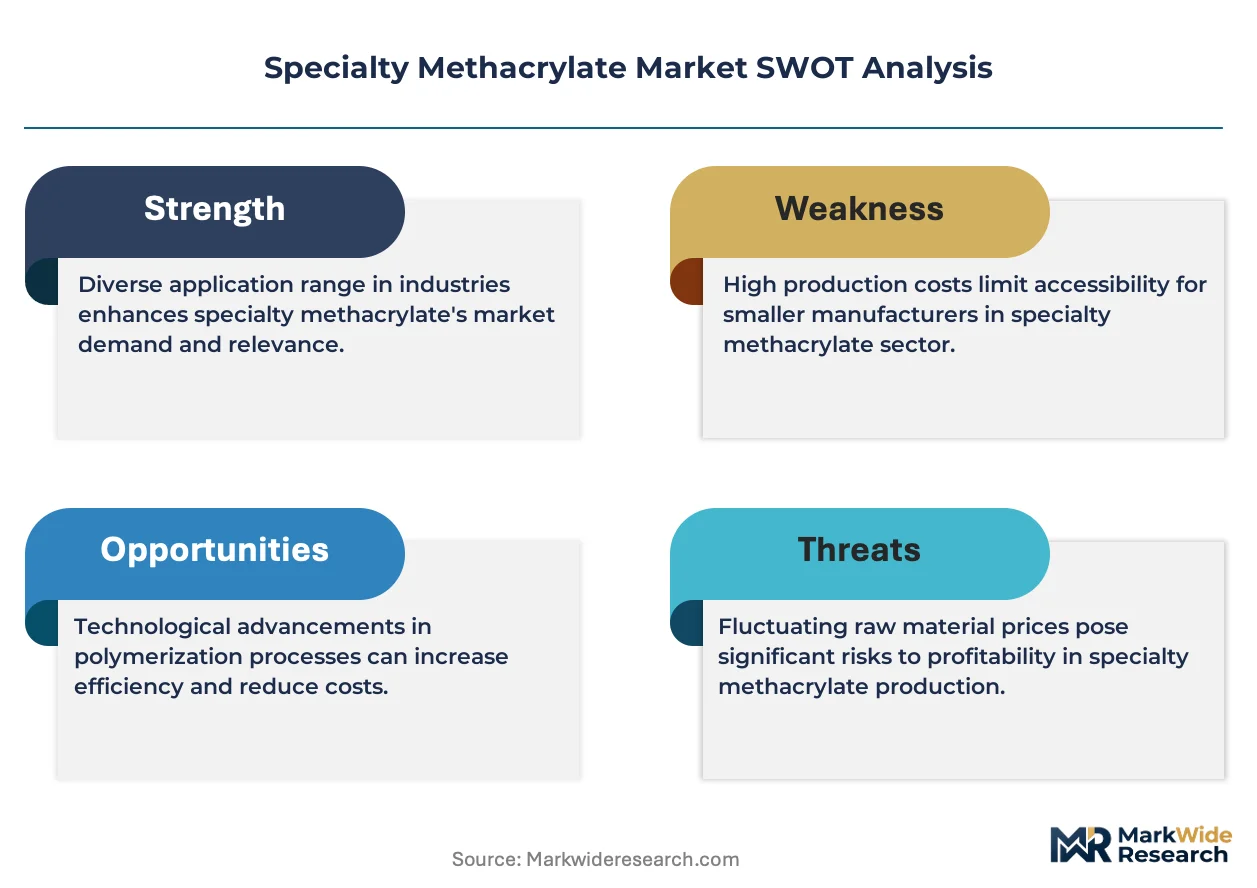
The central force shaping the specialty methacrylate market is the dual pressure from advanced manufacturing and stringent regulation. Demand for high-performance optical and adhesive materials from electronics producers is countered by the complex, multi-jurisdictional compliance burden imposed by chemical safety frameworks.
Growth Catalysts
- Lightweighting in Transportation:Automotive and aerospace demand for lightweight composites drives consumption of functional methacrylates to enhance structural integrity.
- Advanced Optical Materials:The electronics industry requires specialized monomers for optical films and adhesives where clarity and stability are critical performance metrics.
- China's Industrial Policy:National policies create a large domestic market for specialty grades complying with GB standards, supporting high-value manufacturing goals.
Market Restraints
- Feedstock Price Volatility:The cost of precursors like methacrylic acid, tied to crude oil prices, creates margin pressure for producers.
- Complex Regulatory Hurdles:Navigating the separate registration requirements of the EU’s REACH and US EPA’s TSCA creates significant cost and time-to-market barriers.
- Competition from Alternatives:In some coatings applications, methacrylates face substitution threats from epoxy and polyurethane systems based on performance-cost trade-offs.
Strategic Opportunities
- Biomedical and Dental Applications:Developing high-purity, biocompatible methacrylates for use in dental resins and bone cements represents a high-value growth frontier.
- Manufacturing Growth in Southeast Asia:Expanding into Vietnam and Indonesia allows suppliers to serve growing industrial sectors before local specialty chemical production matures.
- Functional Nanocomposites:Integrating methacrylates with nanoparticles enables advanced coatings with properties like self-healing, anti-fouling, or enhanced conductivity.
Industry Challenges
- Supply Chain Reconfiguration:Shifting production to align with manufacturing clusters in Asia requires significant capital investment and introduces new logistical complexities for global suppliers.
- Lengthy Product Registration Cycles:The extensive data requirements and evaluation timelines under frameworks like REACH delay the commercialization of new and innovative specialty monomers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Methacrylate Market |
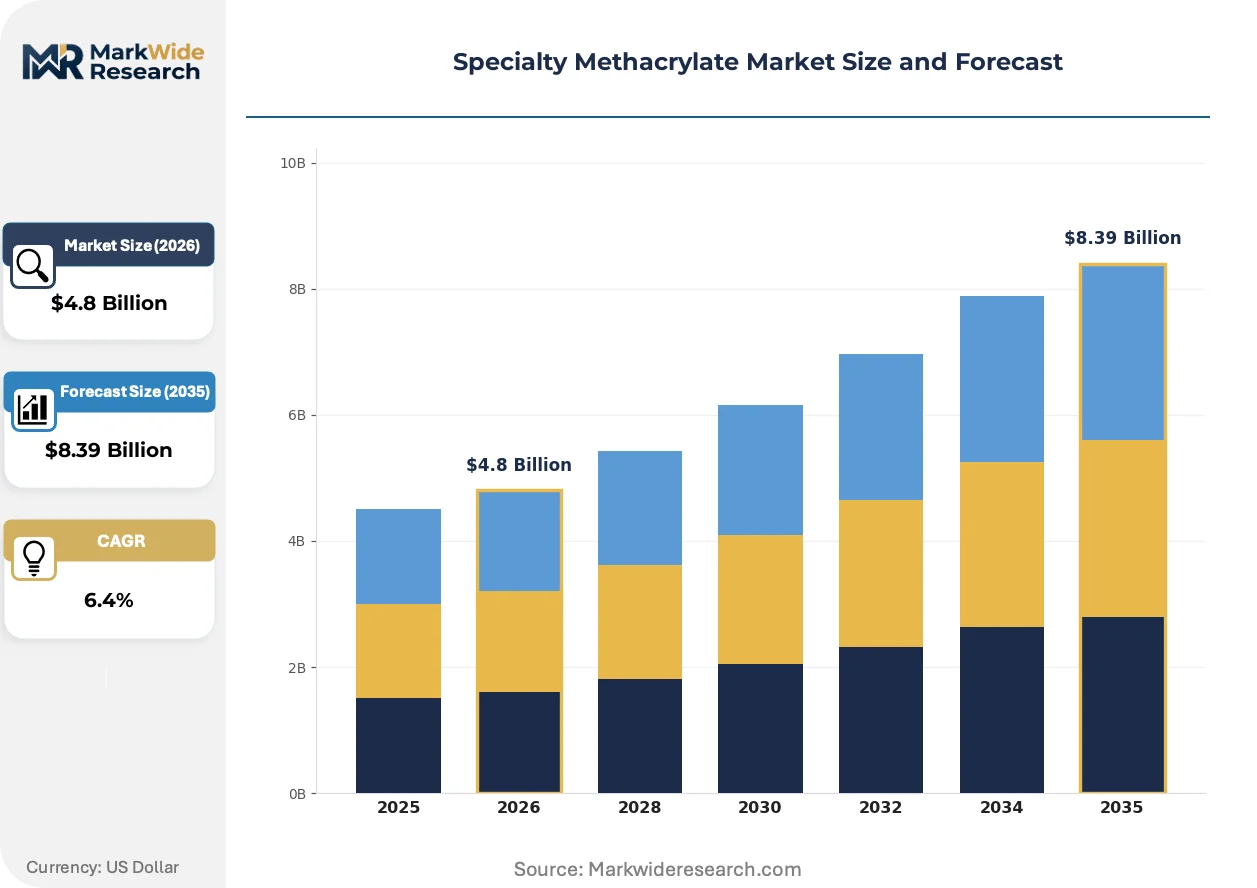
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Methacrylate, Butyl Methacrylate, Hydroxyethyl Methacrylate, Glycidyl Methacrylate, Others Application: Adhesives, Coatings, Automotive Components, Electronics Encapsulation, Optical Materials End User Industry: Construction, Transportation Manufacturing, Consumer Electronics, Packaging, Personal Care Technology: Bulk Polymerization, Emulsion Polymerization, Solution Polymerization, Suspension Polymerization |
| Companies Covered | Evonik Industries AG, Mitsubishi Chemical Holdings Corporation, Dow, Sumitomo Chemical Co., Ltd., LG Chem, Arkema, BASF SE, Nippon Shokubai Co. Ltd., GEO Specialty Chemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Methacrylate Market Strategic Shifts & Innovations
Material science is redefining the role of specialty methacrylates from simple building blocks to functional system enablers. The convergence of green chemistry and electronics miniaturization demands a fundamental rethink of monomer design and polymer performance.
Bio-based methacrylates, derived from renewable feedstocks, offer a lower carbon footprint alternative to traditional petrochemical-based monomers. The automotive and consumer goods sectors are adopting these materials for non-critical components and packaging. This shift toward sustainable sourcing is collapsing the previously distinct boundary between performance chemistry and environmental compliance, forcing suppliers to compete on both.
China’s dual carbon goals and stricter enforcement of its GB standards are pressuring chemical producers. The policies mandate greater energy efficiency and favor materials with lower volatile organic compound (VOC) content. Coatings and adhesives formulators are most affected, accelerating their development of water-borne or high-solids methacrylate systems to maintain market access.
Large end-users in electronics are increasingly bypassing distributors for direct-sourcing relationships with methacrylate manufacturers. This change allows for co-development of custom formulations and greater supply chain transparency, displacing the role of multi-line chemical distributors for specialized grades. The trend is most prominent in South Korea and Taiwan, where electronics conglomerates seek to secure critical optical materials.
Specialty Methacrylate Market Segmentation
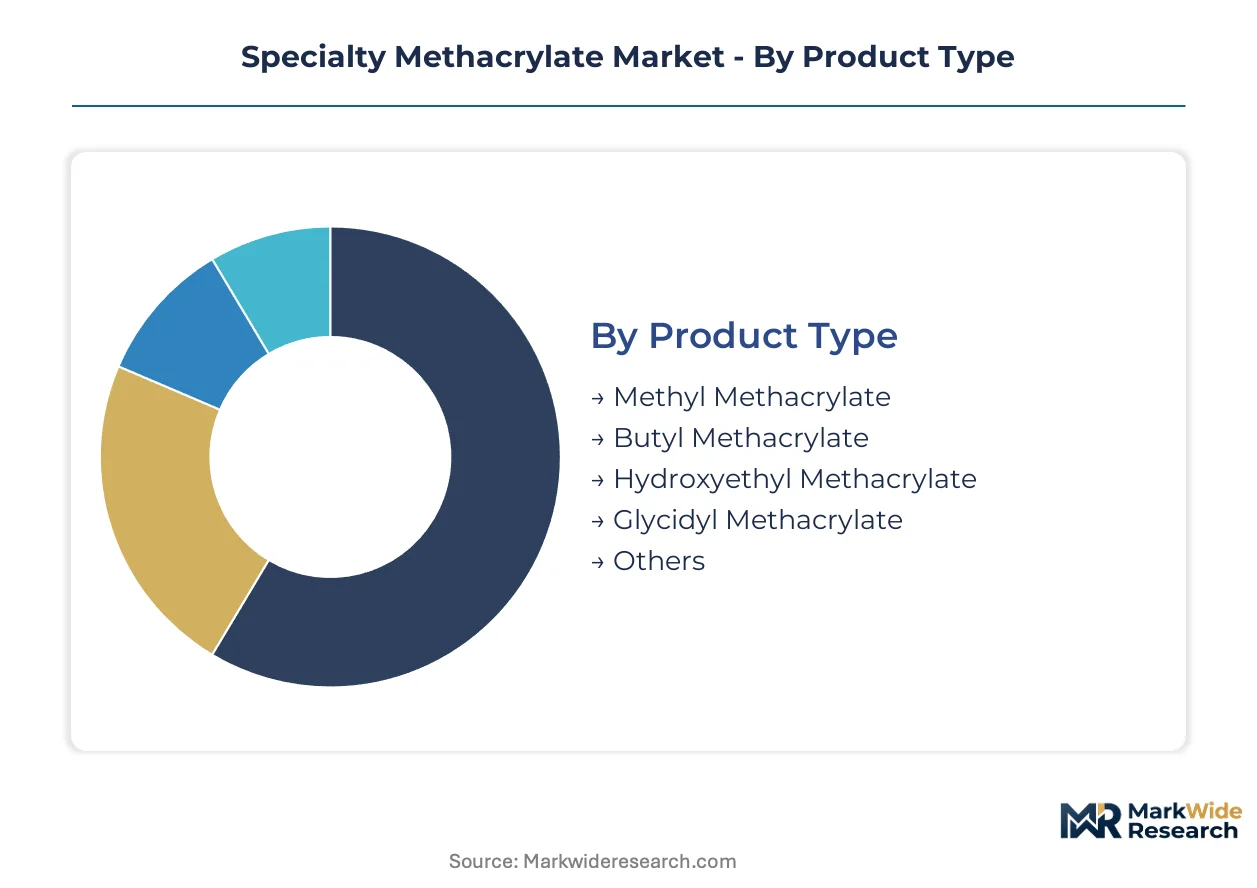
Understanding the segmentation of the specialty methacrylate market is critical for identifying areas of concentrated demand and emerging growth opportunities. Each segment reflects distinct performance requirements, regulatory landscapes, and supply chain dynamics, influencing strategic investment and product development decisions.
Product Type:
Product types in specialty methacrylates exhibit varying production cycle times, influencing supply chain agility and responsiveness to demand shifts.
- Methyl Methacrylate:This monomer serves as a foundational building block for a wide range of polymers, known for its excellent optical clarity and weather resistance in applications like cast sheets and molding compounds. Demand concentrates in the construction sector for glazing and signage.
- Glycidyl Methacrylate:Featuring an epoxy functional group, this methacrylate enables cross-linking and enhanced adhesion, making it valuable for improving the mechanical properties of composites and coatings. Its expanding use in electronics encapsulation and advanced composites drives demand in South Korea and Taiwan.
- Butyl Methacrylate:This ester provides flexibility and hydrophobicity to polymers, finding use in coatings, adhesives, and textile applications where film formation and water resistance are important.
- Hydroxyethyl Methacrylate:Known for its hydrophilic properties, this monomer is crucial in the production of soft contact lenses and certain biomedical devices, offering biocompatibility and water absorption.
- Others:This category encompasses a diverse array of specialty methacrylates, including those with unique functional groups tailored for specific niche applications requiring advanced performance characteristics.
Methyl Methacrylate dominates the installed production base for commodity applications. Glycidyl Methacrylate is where expansion concentrates for specialized uses.
Application:
Application segments are differentiated by their consumption volumes and the specific performance requirements demanded by end-use industries.
- Coatings:Methacrylates provide hardness, gloss, and UV resistance to surface coatings, used extensively in automotive finishes, industrial protective coatings, and architectural paints. This segment requires formulations compliant with VOC regulations like those in the EU and China.
- Adhesives:Specialty methacrylates deliver strong bonding, fast curing times, and durability in various adhesive formulations, including structural adhesives for transportation and dental bonding agents. Demand for high-performance adhesives is strong in Germany and Japan.
- Automotive Components:Methacrylates are incorporated into lightweight composites and clear plastics for vehicle interiors, exteriors, and lighting, contributing to fuel efficiency and aesthetic appeal.
- Electronics Encapsulation:These materials protect sensitive electronic components from moisture, heat, and physical damage, crucial for extending the lifespan and reliability of devices.
- Optical Materials:Specialty methacrylates form the basis for high-clarity optical lenses, films, and displays, essential for consumer electronics and advanced optical instruments.
Coatings and Adhesives command substantial volumes due to their widespread utility. Electronics Encapsulation and Optical Materials demonstrate the steepest expansion trajectory, driven by technological advancements.
End User Industry:
End-user industries for specialty methacrylates present diverse margin profiles, reflecting the value-added nature of the materials within their final products.
- Construction:Methacrylates are used in flooring, sealants, concrete repair, and protective coatings, offering durability, weather resistance, and aesthetic appeal for infrastructure projects. This sector values cost-effectiveness and long-term performance.
- Transportation Manufacturing:This industry employs methacrylates in lightweight composites for aerospace and automotive parts, contributing to structural integrity and fuel efficiency. Demand for advanced materials is high in the US and Germany.
- Consumer Electronics:Specialty methacrylates are critical for optical films, adhesives, and protective coatings in smartphones, tablets, and displays, requiring high clarity and stability. Manufacturers in China and South Korea drive significant demand.
- Packaging:Methacrylates enhance the barrier properties and printability of packaging materials, extending shelf life and improving visual appeal for various consumer goods.
- Personal Care:In cosmetics and toiletries, methacrylates function as film formers, thickeners, and suspending agents, contributing to product texture and performance.
Transportation Manufacturing and Consumer Electronics represent high-value segments for advanced methacrylate formulations. Construction and Packaging maintain consistent demand for established product grades.
Technology:
Polymerization technologies dictate the scale of production and the specific properties achievable, influencing where supply capability concentrates.
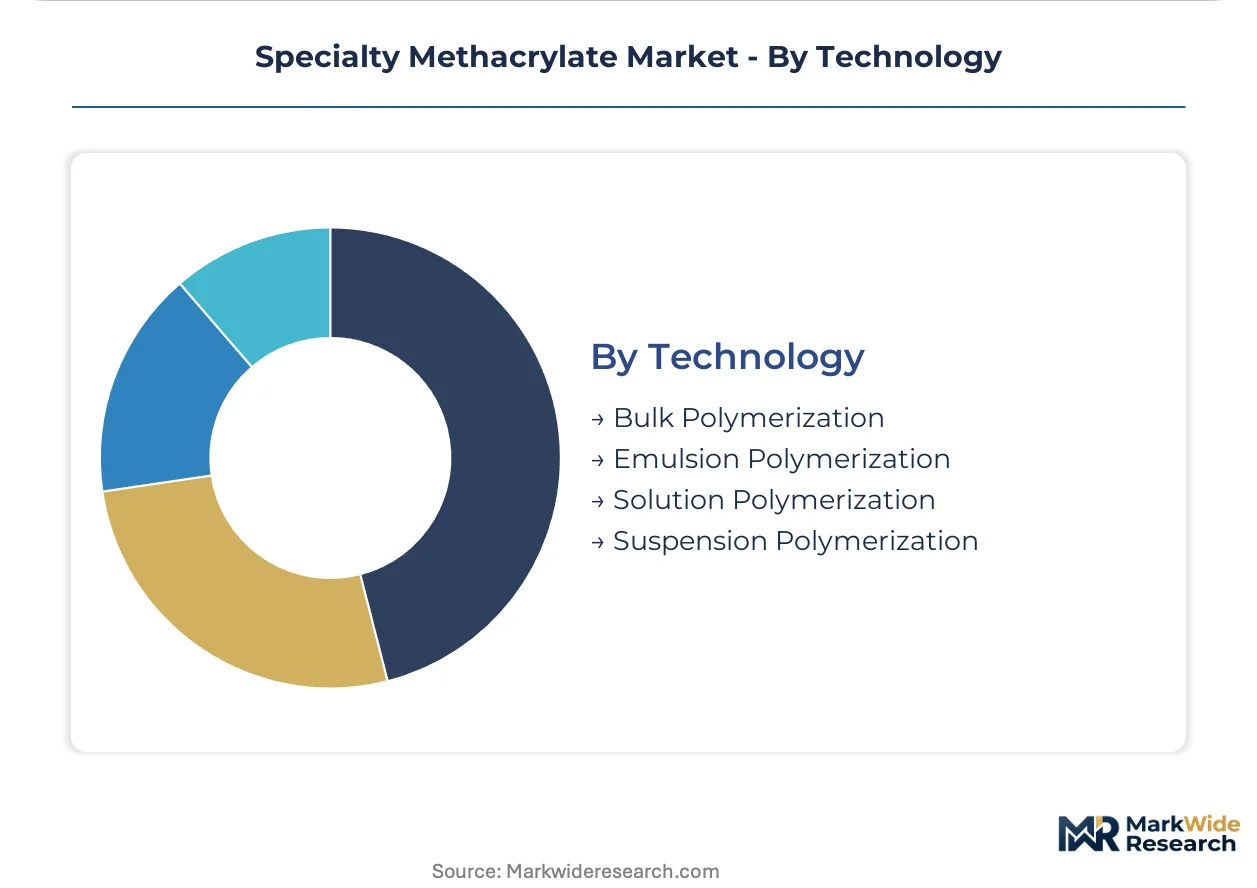
- Bulk Polymerization:This method involves polymerizing monomers without a solvent or diluent, producing high-purity polymers often used for cast sheets and molding compounds. It offers high throughput for large-volume production.
- Emulsion Polymerization:Conducted in an aqueous medium with surfactants, this technique yields polymer latexes suitable for coatings, adhesives, and textile applications, offering precise control over particle size. It is critical for water-borne systems.
- Solution Polymerization:Monomers are dissolved in a solvent, allowing for better heat control and viscosity management, often used for specialty resins and industrial coatings requiring specific molecular weights.
- Suspension Polymerization:This process produces polymer beads or pearls, making it suitable for ion-exchange resins, dental materials, and certain molding applications where granular forms are preferred.
Bulk and Emulsion Polymerization methods underpin the majority of current production. Solution and Suspension Polymerization techniques support niche applications requiring specific molecular weight distributions or particle sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive port infrastructure across major manufacturing hubs underwrites the regional dynamics of the specialty methacrylate market. Demand for high-performance materials in electronics and transportation drives consumption in key economies. Regulatory frameworks significantly influence product formulation and market access in these regions.
China
Demand from consumer electronics and automotive lightweighting fuels significant consumption of specialty methacrylates. China's GB standards dictate product quality and purity for domestic market access. Industrial clusters within the Yangtze River Delta concentrate production and consumption. This region serves its vast manufacturing base.
South Korea
Electronics encapsulation and advanced optical materials drive substantial demand for specialized methacrylate grades. The Ministry of Environment actively monitors chemical substance registration and use. Pyeongtaek's semiconductor fabrication plants require high-purity methacrylate systems for device protection. These materials are essential for display technologies.
United States
Transportation manufacturing, particularly aerospace and automotive, generates significant demand for lightweight composites and structural adhesives. The US EPA's Toxic Substances Control Act (TSCA) imposes rigorous safety data requirements on producers. Chemical production facilities along the Gulf Coast support diverse end-user industries. Biomedical applications also contribute to demand.
Germany
Automotive finishes, high-performance adhesives, and industrial coatings require advanced methacrylate formulations. The European Union's REACH regulation governs chemical substances manufactured or imported into the region. The Rhine-Main area houses numerous chemical companies developing specialized polymers. This region anchors European demand for innovation.
Japan
Optical materials for displays and precision lenses, alongside dental resins, create specific market needs for specialty methacrylates. Japan's Ministry of Economy, Trade and Industry (METI) oversees industrial chemical management and safety standards. Osaka's vibrant electronics industry utilizes methacrylates for precision components. Research efforts focus on functional nanocomposites.
Specialty Methacrylate Market Key Industry Players
On the supply side, the industry is characterized by a blend of large, diversified chemical conglomerates and specialized niche manufacturers. This tiered structure reflects varying production scales and product portfolios, from commodity grades to high-performance specialty chemicals. Archetypes include global commodity suppliers leveraging scale, high-performance specialty chemical producers focusing on innovation, and regional custom formulators. Companies pursue portfolio diversification and strategic partnerships with large-volume end-users to secure market position and drive new product development.
At the scale-driven end, Germany-based Evonik Industries AG exemplifies a large chemical producer leveraging significant manufacturing capacity for commodity-grade methacrylates. France-based Arkema occupies a position among high-performance polymer specialists, differentiating through its portfolio of advanced materials for niche applications. Japan-based Mitsubishi Chemical Holdings Corporation sits within the group of diversified chemical conglomerates, offering a broad range of methacrylate products for various industrial sectors. These companies anchor market supply across different performance tiers and geographic regions.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Mitsubishi Chemical Holdings Corporation |
| Dow |
| Sumitomo Chemical Co., Ltd. |
| LG Chem |
| Arkema |
| BASF SE |
| Nippon Shokubai Co. Ltd. |
| GEO Specialty Chemicals Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in methyl methacrylate production in China creates downward pricing pressure, influencing global supplier behavior and long-term investment strategies for commodity grades.
Pricing Analysis
Volume-based contracts define the dominant pricing structure for commodity-grade methacrylates, reflecting scale efficiencies in production and delivery. Price differentiation stems from product quality grade, particularly for high-purity optical materials, and geographic delivery costs to distant markets like the United States. Margin pressure intensifies due to feedstock price volatility, which is closely tied to crude oil prices. Construction sector buyers are generally most price-sensitive, while consumer electronics manufacturers exhibit lower sensitivity for specialized, high-performance formulations.
Supply Chain Analysis
Feedstock price volatility, tied to crude oil prices, represents a significant structural risk for methacrylate producers, impacting raw material procurement and production costs. Geographic supply concentration for key precursors draws from industrial clusters in China, South Korea, and Germany. The market depends on methacrylic acid and other crude oil derivatives as primary inputs. Distribution runs through a hybrid model, combining direct sales channels to large-volume end-users with specialized distributors serving niche applications across Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty methacrylate market presents a significant service-attach opportunity, with custom formulation and co-development services expanding faster than basic monomer sales.
For Market Incumbents: Harden core market positions by investing in high-purity production capabilities for electronics encapsulation materials. Expand R&D efforts into bio-based methacrylates to preempt regulatory shifts and meet sustainability mandates from the automotive sector. Strategic partnerships with large consumer electronics OEMs in South Korea and Taiwan can mitigate the threat of new entrants leveraging cost advantages. Control over key manufacturing intellectual property serves as a critical lever against commoditization.
For New Entrants and Emerging Players: Underpenetration in Southeast Asian industrial sectors offers a clear entry point for specialized methacrylate suppliers. Target high-value, low-volume niche applications requiring specific functional groups, such as advanced composites for aerospace or high-purity grades for biomedical devices. A strong go-to-market angle involves offering direct technical sales teams supporting custom formulation and rapid prototyping for regional manufacturers in Vietnam and Indonesia. Focus on compliance with local GB standards in China for specialized grades.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across advanced optical materials production, driven by stringent quality requirements and specialized equipment needs. The market demonstrates long-term viability, anchored by persistent demand from electronics miniaturization and healthcare innovation. Target mid-cap specialists with strong R&D in functional nanocomposites or established market access in high-growth regions like South Korea. Increasing patent filings for bio-based or functionalized methacrylates represents a key signal to watch for future inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Build new Glycidyl Methacrylate capacity to serve growing electronics encapsulation demand in Asia. |
| Green Manufacturing Transition | Invest in bio-based methacrylate production to meet automotive and consumer goods sector sustainability mandates. |
| Long-term Supply Agreement | Secure multi-year contracts with consumer electronics giants in South Korea and Japan for critical optical materials. |
| Joint Venture in Southeast Asia | Partner with a local distributor in Vietnam to navigate regional market access and serve emerging industrial sectors. |
| R&D Investment in Nanocomposites | Develop self-healing or anti-fouling methacrylate systems for advanced coatings with enhanced performance properties. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, and plant managers anchored the qualitative base for this analysis. The study integrated insights from primary interviews with extensive secondary validation from chemical industry reports, company SEC filings, and regulatory body publications like ECHA and the US EPA. Bottom-up and top-down triangulation methods were employed to ensure data consistency and accuracy across various market segments.
Scenario-bracketing informed the projection of market expansion across the analysis window, considering both optimistic and conservative growth pathways. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, technology, and regional regulatory compliance. Compound annual growth rates were derived from historical growth trends and projected demand drivers, with crude oil price forecasts and electronics production volumes serving as key industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or manufacturing output would shift the trajectory of specialty methacrylate demand. Forecasts reflect underlying assumptions regarding technological advancements and regulatory stability, acknowledging specific risk factors such as geopolitical tensions impacting supply chains or rapid substitution by alternative materials. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Cholesteryl Isostearate Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Fatliquoring Agents Market