
 Phosphonate Market | 2026-2036
Phosphonate Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphonate Market Analysis
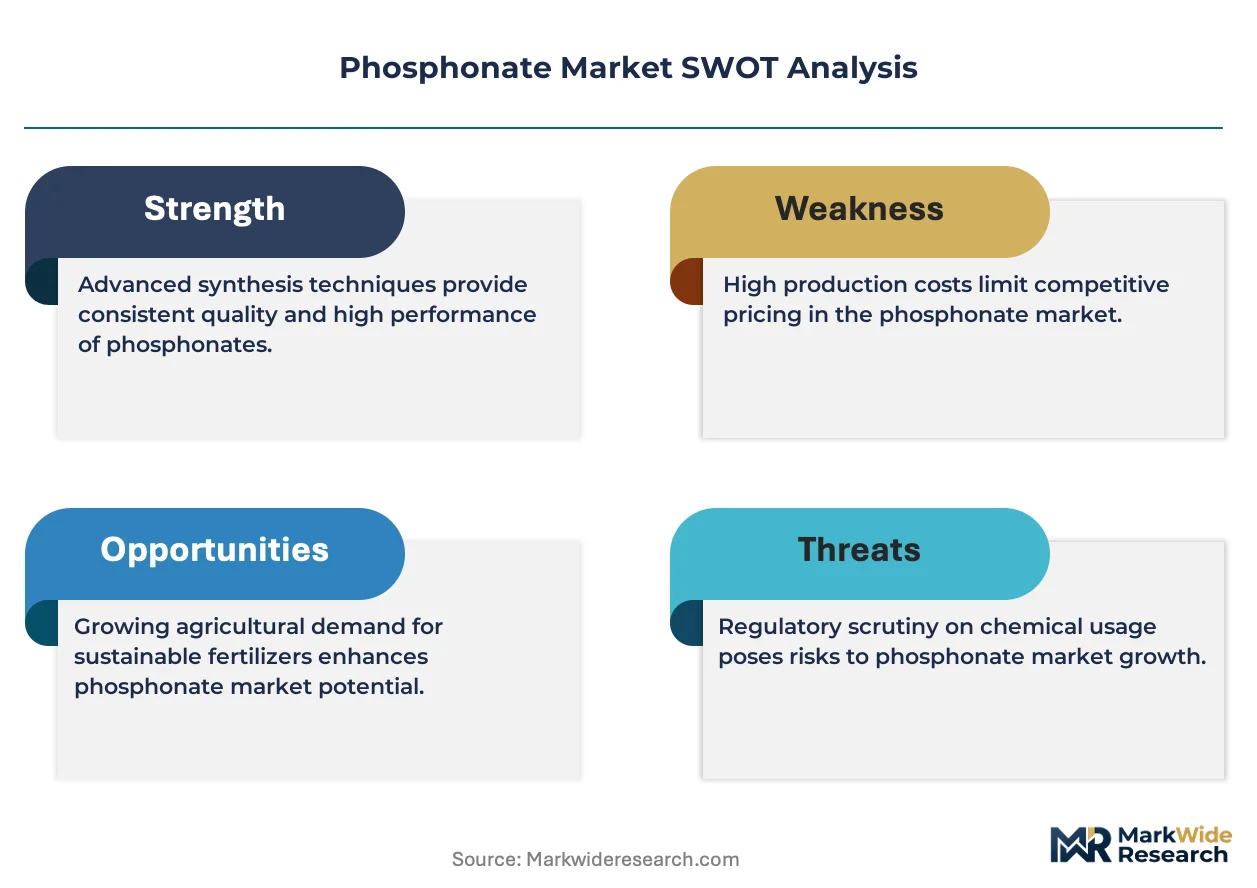
ISO 9001 quality management certification is reorganizing supplier qualification protocols across the phosphonate value chain, elevating documentation and traceability requirements for raw material sourcing. Italmatch Chemicals leverages backward integration into phosphorus chemistry to sustain feedstock security across European industrial water treatment accounts. Shandong Taihe Water Treatment Technologies anchors production scale in China's eastern chemical corridor, while Aquapharm Chemical Pvt. Ltd. competes on specialty-grade phosphonate formulations for pharmaceutical chelation applications.
Phosphonates are organophosphorus compounds containing one or more carbon-phosphorus bonds, typically manufactured through Mannich or Michaelis-Becker reactions, and function primarily as scale inhibitors, chelating agents, and corrosion suppressants in aqueous systems. Organophosphonates dominate volume demand in cooling water and boiler treatment circuits where thermal stability below 250°C is essential. Water treatment applications command the largest margin pools due to long-term service contracts with power generation and petrochemical facilities, while pharmaceutical-grade phosphonates in chelating agent applications attract premium pricing through specialty grade certification requirements.
REACH registration in Europe and China's SAMR oversight of industrial chemical purity are tightening impurity limits on phosphonate active content, forcing reformulation of legacy products. The EPA's framework for phosphonate discharge in cooling tower blowdown shapes regional product selection toward biodegradable analogs in United States industrial zones. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging purity and environmental fate standards.
Market Dynamics
REACH compliance in Europe and China's GB standards are forcing simultaneous reformulation of legacy phosphonate chemistries, compressing product development cycles while elevating purity thresholds across water treatment and pharmaceutical applications.
Growth Catalysts
- Industrial Water Treatment Expansion:Power generation and petrochemical facilities in China's Shandong province are extending long-term service contracts for cooling water scale inhibition, locking in multi-year phosphonate procurement commitments.
- REACH Registration Mandates:ECHA's tightened impurity limits on phosphonate active content are accelerating replacement of first-generation formulations with higher-purity derivatives across European industrial zones.
- Pharmaceutical Chelation Demand:Specialty-grade phosphonate certification for intravenous drug formulations is opening margin pools in pharmaceutical manufacturing corridors.
Market Restraints
- Phosphorus Feedstock Volatility:Yellow phosphorus price swings and export quota restrictions from major producing regions are compressing margin predictability for phosphonate manufacturers.
- Supply-Side Geographic Concentration:Manufacturing clusters in eastern China's chemical corridor dominate global phosphonate output, creating single-source vulnerability for European and North American formulators.
- Biodegradability Substitution Pressure:EPA discharge frameworks for cooling tower blowdown are redirecting specification decisions toward biodegradable scale inhibitors in United States industrial water treatment.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO's alignment with ICH quality guidelines is creating demand for pharmaceutical-grade phosphonate chelating agents in active pharmaceutical ingredient synthesis.
- Green Chemistry Incentives:EU Green Deal funding streams for sustainable chemical processes are subsidizing pilot-scale production of bio-based phosphonate analogs.
- Digital Water Treatment Monitoring:Convergence of IoT sensor networks with automated dosing systems is enabling real-time phosphonate consumption optimization in distributed cooling circuits.
Industry Challenges
- ISO 9001 Documentation Burden:Traceability requirements for phosphorus raw material sourcing are extending supplier qualification timelines by six to twelve months for new market entrants.
- Legacy System Integration:Retrofitting existing cooling water treatment infrastructure with next-generation phosphonate formulations requires simultaneous recalibration of corrosion monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphonate Market |
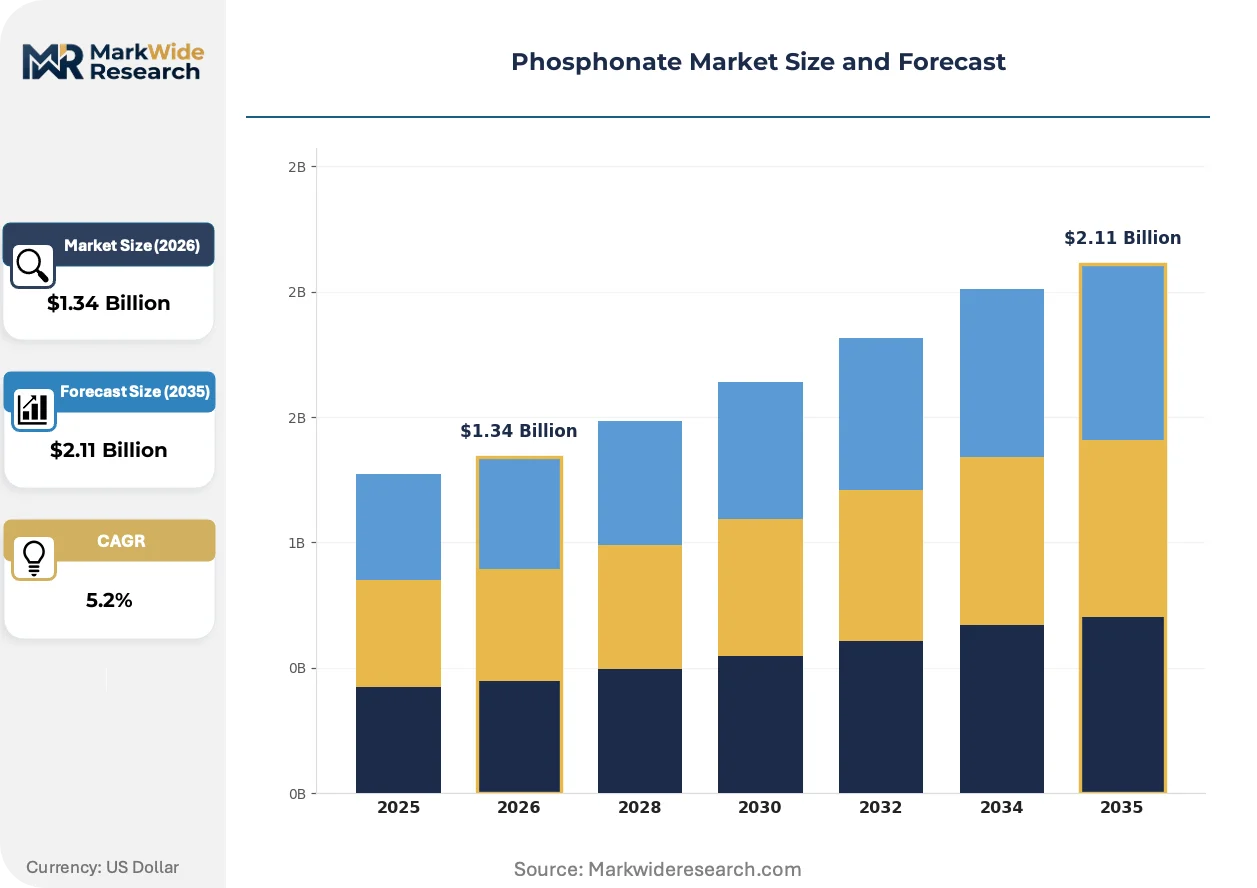
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Phosphonates, Organophosphonates, Phosphonic Acids, Phosphate Esters End Use Industry: Agriculture, Pharmaceuticals, Water Treatment, Personal Care Grade: Technical Grade, Food Grade, Industrial Grade, Specialty Grade Application: Corrosion Inhibition, Chelating Agents, Fertilizers, Additives |
| Companies Covered | Biesterfeld AG, Henan Qingshuiyuan Technology, Italmatch Chemicals, Excel Industries, Changzhou Kewei Fine Chemicals, Shandong Taihe Water Treatment Technologies, Zaozhuang Kerui Chemicals, Zschimmer & Schwarz Chemie GmbH, Aquapharm Chemical Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphonate Market Emerging Trajectories
Phosphonate chemistry is undergoing functional specialization, with formulation science diverging toward application-specific performance tiers rather than universal scale inhibition products.
Polymeric phosphonate hybrids are miniaturizing molecular architecture to enhance calcium carbonate dispersion efficiency at lower active dosages. Cooling water operators in Gulf Coast petrochemical complexes are adopting these condensed-structure formulations to reduce chemical handling volumes. This molecular compression is miniaturizing feedstock requirements per treated volume while maintaining thermal stability thresholds.
China's SAMR oversight of industrial chemical purity is mandating heavy metal impurity testing protocols that exceed legacy GB standard thresholds. Domestic phosphonate producers in Jiangsu province are retrofitting purification trains to meet these elevated specifications. Pharmaceutical-grade applications face the steepest compliance ramps, with active content thresholds now matching European Pharmacopoeia monograph requirements.
Power generation utilities are consolidating vendor relationships around integrated chemical service contracts that bundle phosphonate supply with performance monitoring. This bundling is displacing spot procurement of commodity phosphonate concentrates in favor of outcome-guaranteed treatment programs. The shift is most pronounced in combined-cycle gas turbine facilities where water chemistry optimization directly correlates with heat rate efficiency.
Phosphonate Market Segmentation
Phosphonate procurement channels diverge sharply by application chemistry, with water treatment operators favoring bulk technical-grade contracts while pharmaceutical formulators source specialty-grade materials through qualified distributor networks. Understanding segment-channel alignment reveals where margin pools concentrate and where specification requirements create sourcing friction.
Product Type:
Channel-mix patterns split between commodity bulk shipments for industrial water treatment and drum-quantity specialty distribution for pharmaceutical and personal care applications.
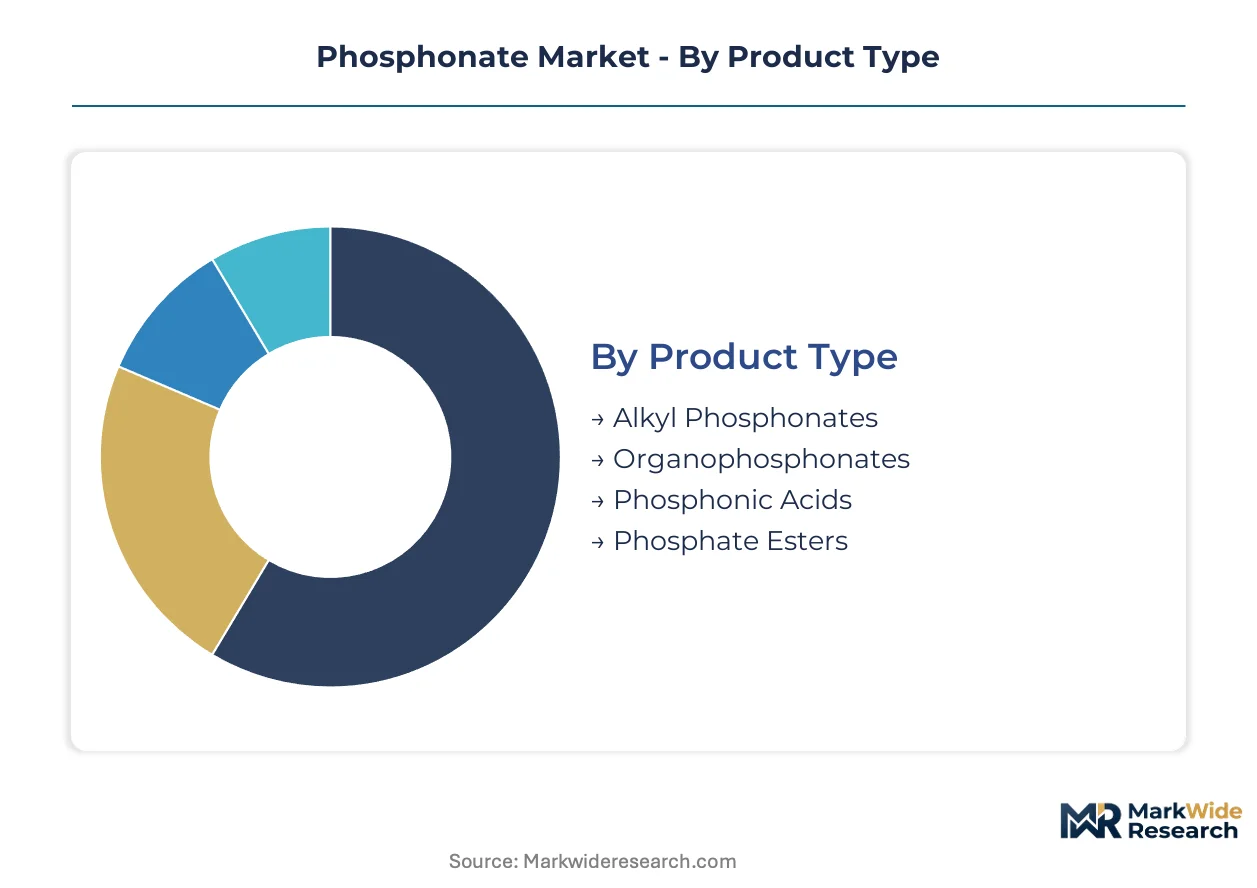
- Organophosphonates:These carbon-phosphorus bonded compounds deliver thermal stability below 250°C in cooling water and boiler treatment circuits. Power generation facilities in China's Shandong province are locking in multi-year procurement commitments for these formulations, though EPA discharge frameworks in United States industrial zones are redirecting specification decisions toward biodegradable alternatives.
- Phosphonic Acids:The acidic form enables precise pH-adjusted chelation in metal ion sequestration applications. REACH registration mandates from ECHA are accelerating replacement of first-generation phosphonic acid formulations with higher-purity derivatives across European industrial water treatment corridors.
- Alkyl Phosphonates:Hydrophobic side chains enhance oilfield scale inhibition performance in Gulf Coast petrochemical complexes.
- Phosphate Esters:Ester linkage chemistry supports flame-retardant and lubricant additive applications in specialty industrial formulations.
By volume, Organophosphonates lead. By growth pace, Phosphonic Acids are expanding most quickly.
End Use Industry:
Cost-tier stratification separates commodity water treatment chemicals from premium pharmaceutical-grade materials requiring active pharmaceutical ingredient certification.
- Water Treatment:Cooling water and boiler treatment circuits command the largest procurement volumes through integrated chemical service contracts that bundle supply with performance monitoring. Long-term service agreements with combined-cycle gas turbine facilities directly correlate water chemistry optimization with heat rate efficiency.
- Pharmaceuticals:Intravenous drug formulations require specialty-grade phosphonate chelating agents meeting European Pharmacopoeia monograph standards. CDSCO's alignment with ICH quality guidelines in India is creating demand for pharmaceutical-grade materials in active pharmaceutical ingredient synthesis corridors.
- Agriculture:Fertilizer additive applications favor technical-grade phosphonates sourced through agricultural chemical distributor networks.
- Personal Care:Cosmetic formulation requirements drive demand for low-impurity phosphonate derivatives in chelating and pH-stabilization roles.
Water Treatment generates the highest absolute volumes. Pharmaceuticals commands the steepest margin expansion trajectory.
Grade:
Application-specific purity thresholds create four distinct specification tiers with divergent certification burdens and pricing structures.
- Technical Grade:Standard purity specifications serve industrial water treatment and agricultural applications where functional performance outweighs trace impurity constraints. China's SAMR oversight of industrial chemical purity is mandating heavy metal impurity testing protocols that exceed legacy GB standard thresholds for this grade.
- Specialty Grade:Elevated active content and documented traceability support pharmaceutical chelation and high-performance industrial applications. ISO 9001 quality management certification is reorganizing supplier qualification protocols, extending documentation timelines by six to twelve months for new market entrants.
- Industrial Grade:Mid-tier specifications balance cost and performance for general manufacturing process applications.
- Food Grade:Regulatory compliance with national food safety authorities enables direct and indirect food contact applications.
Technical Grade dominates shipment volumes. Specialty Grade is gaining share fastest through pharmaceutical manufacturing expansion.
Application:
Functional performance requirements determine whether phosphonates are consumed as continuous-dose treatment chemicals or batch-process additives.
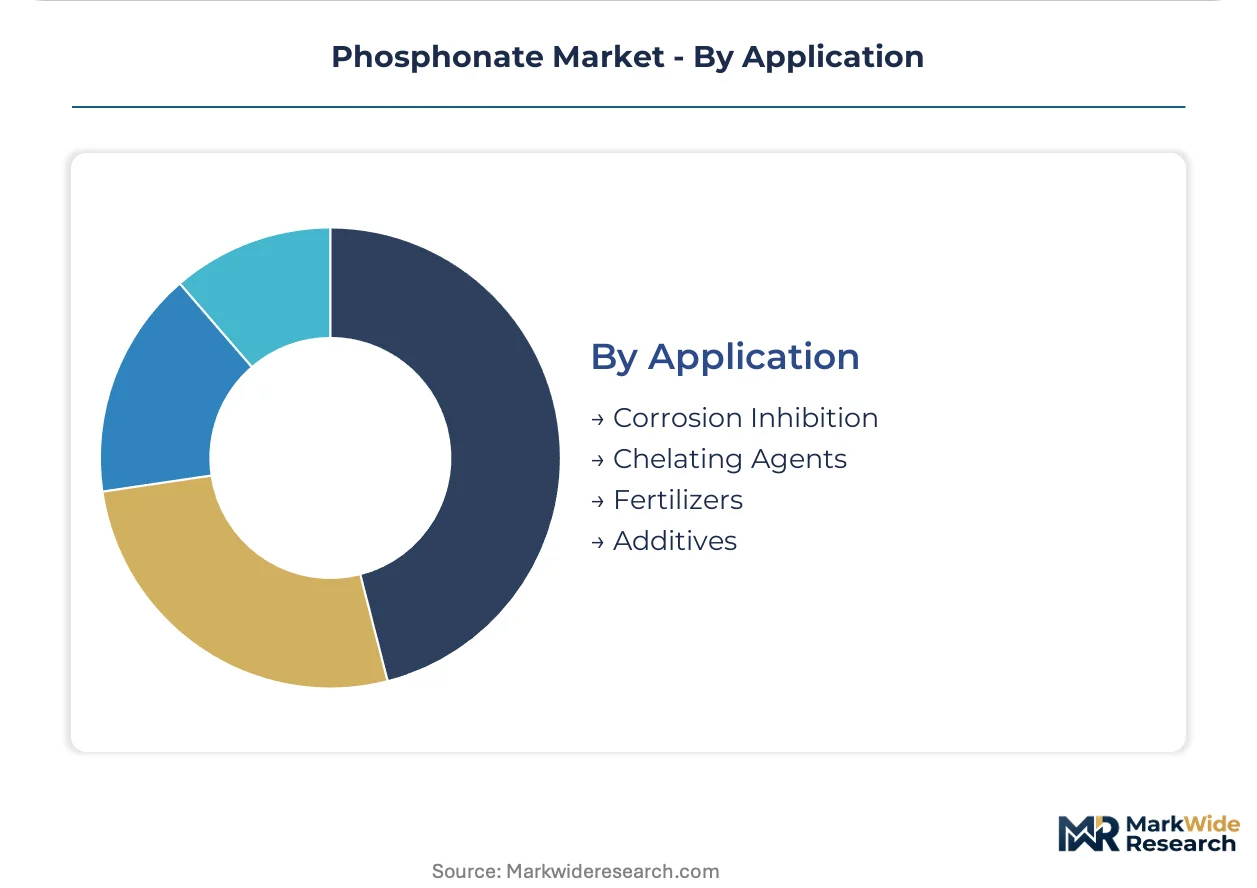
- Chelating Agents:Metal ion sequestration in pharmaceutical manufacturing and industrial water treatment requires precise stoichiometric control. Polymeric phosphonate hybrids are miniaturizing molecular architecture to enhance calcium carbonate dispersion efficiency at lower active dosages.
- Corrosion Inhibition:Surface-active phosphonate films protect carbon steel infrastructure in cooling water systems. Retrofitting existing treatment infrastructure with next-generation formulations requires simultaneous recalibration of corrosion monitoring protocols.
- Additives:Functional modification of lubricants, flame retardants, and personal care formulations utilizes phosphonate chemistry for property enhancement.
- Fertilizers:Nutrient stabilization and metal chelation in agricultural applications leverages phosphonate complexation chemistry.
Chelating Agents anchor volume demand. Corrosion Inhibition shows the steepest expansion trajectory through power generation capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal funding streams subsidize pilot-scale production of bio-based phosphonate analogs while REACH registration mandates from ECHA tighten impurity limits across industrial zones. China's SAMR oversight and GB standards are elevating purity thresholds for phosphonate derivatives in manufacturing corridors. India's CDSCO alignment with ICH quality guidelines creates demand for pharmaceutical-grade materials in active pharmaceutical ingredient synthesis.
China
Power generation and petrochemical facilities in Shandong province extend long-term service contracts for cooling water scale inhibition. SAMR mandates heavy metal impurity testing protocols exceeding legacy GB standard thresholds. Jiangsu province manufacturing clusters retrofit purification trains to meet elevated specifications for both domestic water treatment operators and export markets.
United States
EPA discharge frameworks for cooling tower blowdown redirect specification decisions toward biodegradable scale inhibitors in industrial water treatment zones. Combined-cycle gas turbine facilities consolidate vendor relationships around integrated chemical service contracts bundling phosphonate supply with performance monitoring. Gulf Coast petrochemical complexes adopt condensed-structure polymeric phosphonate hybrids to reduce chemical handling volumes.
Germany
ECHA's tightened impurity limits on phosphonate active content accelerate replacement of first-generation formulations with higher-purity derivatives across European industrial zones. REACH registration reorganizes supplier qualification protocols with elevated documentation requirements. German chemical distributors serve as qualification gateways for technical-grade phosphonate procurement across continental industrial water treatment accounts.
India
CDSCO alignment with ICH quality guidelines generates demand for pharmaceutical-grade phosphonate chelating agents in active pharmaceutical ingredient synthesis corridors. Water treatment utilities in industrial corridors expand phosphonate procurement for scale inhibition and corrosion control. Domestic specialty chemical manufacturers compete on formulation customization for regional pharmaceutical manufacturing clusters.
Phosphonate Market Vendor Landscape
Player mix skews toward integrated phosphorus chemistry specialists and regional water treatment formulators with captive manufacturing assets. The vendor base separates into three strategic tiers: multinational chemical houses with backward integration into phosphorus feedstocks, mid-scale regional producers serving domestic industrial accounts, and specialty-grade formulators targeting pharmaceutical certification requirements. Competitive dynamics center on M&A activity consolidating regional manufacturing clusters and capacity expansion in eastern China's chemical corridor to serve export demand.
Within the integrated phosphorus chemistry tier, Italmatch Chemicals and Zschimmer & Schwarz Chemie GmbH exemplify European-based specialists leveraging captive feedstock security. Shandong Taihe Water Treatment Technologies anchors the scale-driven segment among Chinese producers supplying both domestic water treatment operators and export markets. Aquapharm Chemical Pvt. Ltd. occupies a position within the specialty-grade tier, representing Indian-based competitors targeting pharmaceutical chelation applications requiring elevated certification standards.
| Leading Market Players |
|---|
| Biesterfeld AG |
| Henan Qingshuiyuan Technology |
| Italmatch Chemicals |
| Excel Industries |
| Changzhou Kewei Fine Chemicals |
| Shandong Taihe Water Treatment Technologies |
| Zaozhuang Kerui Chemicals |
| Zschimmer & Schwarz Chemie GmbH |
| Aquapharm Chemical Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
ISO 9001 certification gates both supplier qualification timelines and price differentiation across the phosphonate value chain, extending documentation requirements by six to twelve months while stratifying procurement costs by certification tier. This quality management regime simultaneously elevates barriers for new entrants and enables premium positioning for incumbents with established traceability systems.
Pricing Analysis
Cost-plus contracts with yellow phosphorus indexation dominate long-term procurement agreements between water treatment operators and phosphonate manufacturers. Three-tier pricing structure across pharmaceutical-grade, specialty-grade, and technical-grade materials separates margin pools, with pharmaceutical certification commanding substantial premiums over industrial applications. Cost compression in technical-grade segments is intensifying because of feedstock volatility and export quota restrictions from major producing regions. Municipal water utilities exhibit the highest price sensitivity due to budget constraints, while pharmaceutical formulators prioritize certification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of yellow phosphorus feedstock characterizes procurement behavior among integrated manufacturers, contrasting with just-in-time inventory practices at downstream formulators lacking backward integration. Manufacturing concentration in China, Germany, and India shapes global supply availability, with Jiangsu and Shandong provinces anchoring capacity expansion. The supply chain draws from elemental phosphorus, phosphoric acid, and specialized amine intermediates as core inputs. Single-source vulnerability from China's eastern chemical corridor creates structural risk for European and North American buyers. Distribution runs through integrated chemical service contracts for large water treatment accounts and qualified distributor networks for pharmaceutical-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphonate chemistry disruption is accelerating through regulatory divergence between REACH-mandated purity thresholds and EPA biodegradability frameworks, creating parallel specification tracks that favor agile formulators.
For Market Incumbents: Secure captive phosphorus feedstock through long-term offtake agreements or upstream asset acquisition to insulate margin predictability against yellow phosphorus export quota volatility. Invest in dual-track certification infrastructure enabling simultaneous REACH-registered and EPA-compliant product lines, as regulatory divergence between European and United States jurisdictions threatens portfolio obsolescence for single-standard formulators. For New Entrants and Emerging Players: Pharmaceutical-grade phosphonate certification gaps in India's active pharmaceutical ingredient synthesis corridors offer white-space entry points, as CDSCO alignment with ICH guidelines outpaces domestic specialty-grade production capacity. Target contract manufacturing arrangements with European pharmaceutical houses seeking qualification pathways outside established supplier relationships, leveraging India's emerging regulatory credibility as a go-to-market foundation. For Investors and Strategic Acquirers: REACH registration deadlines reshaping the acquisition landscape toward targets with completed dossier submissions and established ECHA compliance records. Five-to-ten-year viability favors integrated phosphorus chemistry specialists with backward feedstock control over pure-play formulators exposed to raw material volatility. Monitor ECHA substance evaluation timelines as the critical signal; accelerated regulatory scrutiny on phosphonate environmental fate would trigger portfolio restructuring across industrial water treatment exposures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Feedstock | Captive yellow phosphorus supply secures margin stability against export quota volatility from China. |
| Dual-Certification Infrastructure Investment | Parallel REACH and EPA compliance capability enables specification flexibility across diverging regulatory jurisdictions. |
| Pharmaceutical-Grade Purification Expansion | European Pharmacopoeia-aligned production captures premium pricing from intravenous drug formulation demand. |
| Integrated Chemical Service Contracts | Outcome-guaranteed treatment programs bundle phosphonate supply with IoT-enabled dosing optimization. |
| Bio-Based Phosphonate Pilot Development | EU Green Deal funding streams subsidize sustainable chemistry pathways addressing biodegradability substitution pressure. |
Methodological Framework
Operator-level perspectives from water treatment procurement managers, pharmaceutical manufacturing quality directors, and specialty chemical distribution heads anchored the qualitative base for this analysis. Primary field engagement with plant engineers at combined-cycle gas turbine facilities and regulatory affairs specialists at ECHA-registered suppliers combined with secondary validation from customs trade databases, SEC filings of listed chemical distributors, and SAMR industrial chemical purity announcements. Bottom-up demand modeling across cooling water, boiler treatment, and pharmaceutical chelation applications triangulated against top-down phosphorus derivative consumption estimates.
Sensitivity analysis around yellow phosphorus price volatility and REACH registration timeline scenarios informed the forecast framework across the projection horizon. Segmentation dimensions modeled include grade tier (technical, specialty, pharmaceutical), end-use industry (water treatment, pharmaceuticals, agriculture, personal care), and regional production hub configuration. CAGRs were derived from annualized shipment volume trajectories incorporating capacity expansion announcements and long-term service contract visibility. Industry-specific inputs encompassed power generation capacity additions and CDSCO regulatory alignment progress.
Forecasts assume regulatory continuity in REACH, EPA discharge frameworks, and China's GB standards; material policy shifts would require re-modeling active content thresholds or environmental fate restrictions. Specific risks that could revise projections include phosphorus export quota tightening, accelerated biodegradability mandates, or pharmaceutical-grade purity threshold elevation beyond current European Pharmacopoeia standards. Revision becomes warranted when regulatory divergence between major jurisdictions exceeds current dual-track compliance bandwidth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Thermolysin Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Isostearyl Alcohol Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Biodegradable Chelating Agents Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
North America Non-Phthalate Plasticizers Market