
 Barium Sulfate Market | 2026-2036
Barium Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Sulfate Market Insights
Oil and gas drilling is recalibrating its share of barium sulfate consumption as exploration budgets fluctuate and drilling fluid formulations shift toward synthetic alternatives. Solvay leverages its European precipitated barium sulfate capacity to serve pharmaceutical and specialty coating customers with certified high-purity output. Cimbar Performance Minerals anchors North American supply through its barite mining and processing network in Georgia and Nevada. Sakai Chemical Industry specializes in micronized and surface-coated grades for ink and plastics applications across East Asia.
Barium sulfate is a white crystalline inorganic compound with the chemical formula BaSO4, possessing a high specific gravity of approximately 4.5 and near-zero solubility in water, which makes it ideal as a weighting agent, radiopaque contrast medium, and functional filler. Precipitated barium sulfate commands premium positioning in pharmaceutical and imaging applications where particle size distribution and purity thresholds are tightly specified. Natural barite-derived grades dominate oilfield drilling volumes but face margin compression from synthetic alternatives and recycled material streams. The paints and coatings grade segment captures significant value through dispersion performance requirements in automotive and industrial finishes.
FDA purity standards govern barium sulfate used in radiological contrast suspensions, while REACH registration and classification protocols in Europe constrain importer qualification and substance documentation burdens. OSHA permissible exposure limits for respirable crystalline silica intersect with barite mining and milling operations, forcing dust-control investments that reshape cost structures at extraction-stage suppliers. Stakeholders must monitor how dual carbon goals in China and evolving EPA mining waste rules in the United States redirect capital toward cleaner processing routes and alternative weighting materials.
Market Dynamics
REACH crystalline silica exposure limits and OSHA permissible exposure thresholds are forcing barite mining and milling operations to deploy dust-suppression infrastructure, reshaping cost structures at extraction-stage suppliers and compressing margins for natural-grade producers.
Growth Catalysts
- Oilfield weighting agent specifications:High-purity precipitated grades are displacing lower-grade natural barite in deepwater drilling fluid formulations, tightening procurement standards among offshore operators.
- REACH registration protocols:European importers face heightened substance documentation burdens that favor qualified suppliers with certified purity thresholds, consolidating procurement toward integrated chemical processors.
- China's Shandong-Hebei cluster:Integrated barite mining and chemical processing infrastructure supplies domestic coating makers and export markets with scale economies unavailable to fragmented competitors.
Market Restraints
- Input cost volatility:Energy-intensive precipitation processes expose synthetic-grade producers to natural gas and electricity price swings that natural barite miners avoid.
- Supply concentration risk:China's dominance in barite ore extraction creates single-source vulnerability for precipitated-grade manufacturers dependent on consistent feedstock quality.
- Substitution threat:Synthetic hematite and ilmenite weighting materials are capturing share in drilling fluids where density requirements permit formulation flexibility.
Strategic Opportunities
- Pharmaceutical radiopaque applications:FDA-certified micronized grades for contrast suspensions command premium positioning as imaging procedure volumes expand in aging populations.
- Surface-coated specialty grades:Ink and plastics compounders in East Asia are specifying surface-treated particles that improve dispersion performance in high-solids formulations.
- Dual carbon goals:China's MEE enforcement of cleaner processing routes is redirecting capital toward closed-loop precipitation systems that reduce wastewater discharge liabilities.
Industry Challenges
- Certification timeline compression:Pharmaceutical-grade producers face extended FDA validation cycles for particle size distribution and heavy metal contamination thresholds that delay commercialization.
- Legacy equipment retrofit burden:Dust-control investments required by OSHA silica rules demand capital deployment at aging milling facilities with limited depreciation runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Sulfate Market |
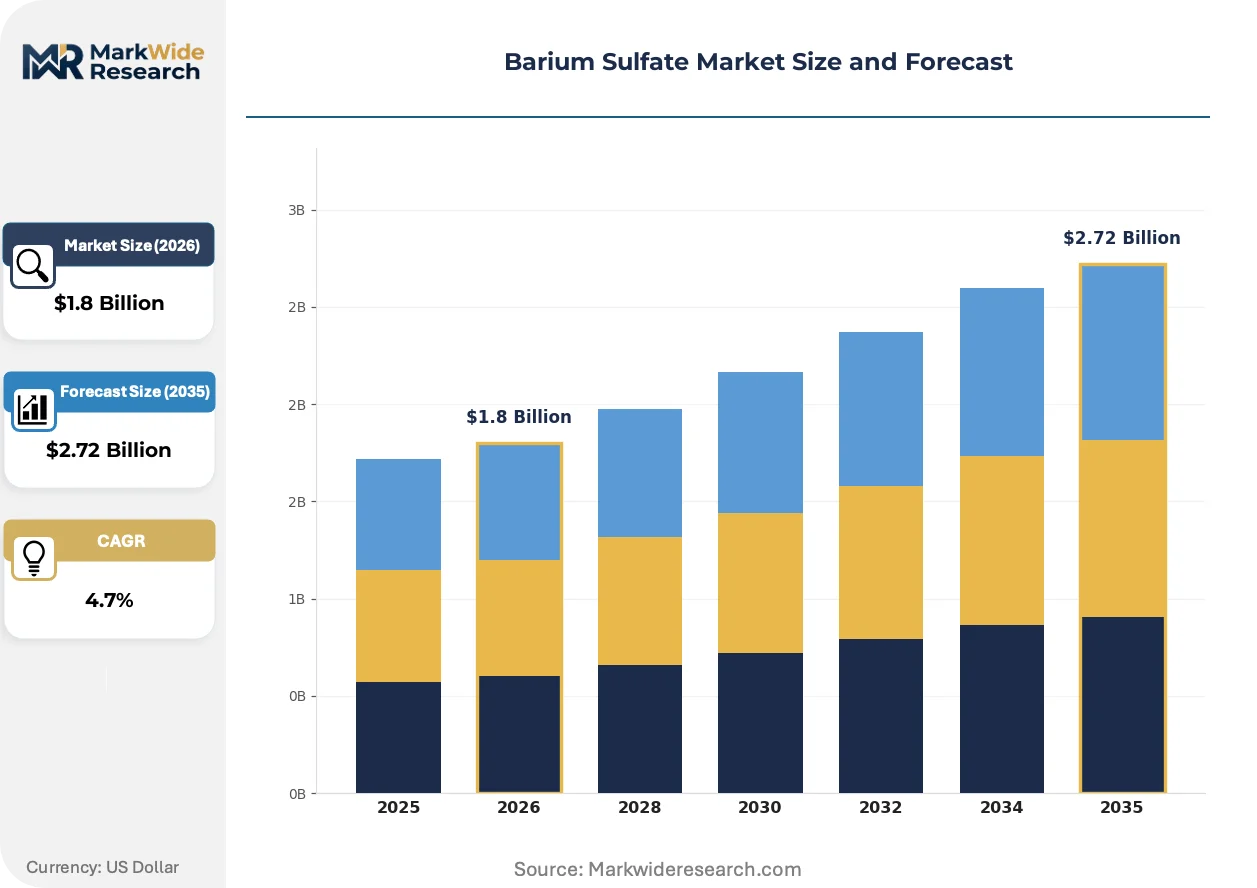
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precipitated, Natural, Synthetic, Micronized, Coated Grade: Pharmaceutical, Industrial, Food, Paints & Coatings, Plastics Application: Oil & Gas Drilling, Paper Industry, Rubber Manufacturing, Cosmetics Production, Radiology End Use Industry: Pulp & Paper, Chemical Processing, Personal Care, Construction Materials, Imaging Centers |
| Companies Covered | Solvay, BASF, Minerals Technologies, Huntsman Corporation, Cimbar Performance Minerals, Sachtleben Chemie, Nippon Chemical Industrial, Sakai Chemical Industry, Shaanxi Fuhua Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Sulfate Market Trends and Innovations
Barium sulfate value chains are restructuring around purity-tier segmentation and regulatory compliance automation, with processing technology and procurement governance undergoing parallel transformation.
Surface modification chemistry is integrating silane coupling agents and polymer encapsulation layers that enhance compatibility with polar resin matrices. Automotive coating formulators in Germany and Japan are specifying these engineered particles to achieve gloss retention and scratch resistance in waterborne basecoat systems. The technology is integrating formerly commoditized filler grades into performance-critical supply tiers with dedicated qualification protocols.
OSHA's crystalline silica permissible exposure limit enforcement is compelling mining operations to install real-time particulate monitoring and automated suppression systems. Milling facilities in Georgia and Nevada are retrofitting enclosed conveyor systems and baghouse filtration to maintain compliance. Natural-grade suppliers serving oilfield markets face the steepest compliance cost inflation, compressing their cost advantage over synthetic alternatives.
Direct-procurement relationships between coating manufacturers and integrated chemical processors are displacing traditional mineral trader intermediaries. Large automotive OEMs in the US and Germany are qualifying precipitated-grade suppliers through multi-year offtake agreements with embedded purity guarantees. This channel consolidation is most visible in industrial finishes, where formulation consistency requirements have tightened specification windows beyond trader-grade material capabilities.
Barium Sulfate Market Segmentation
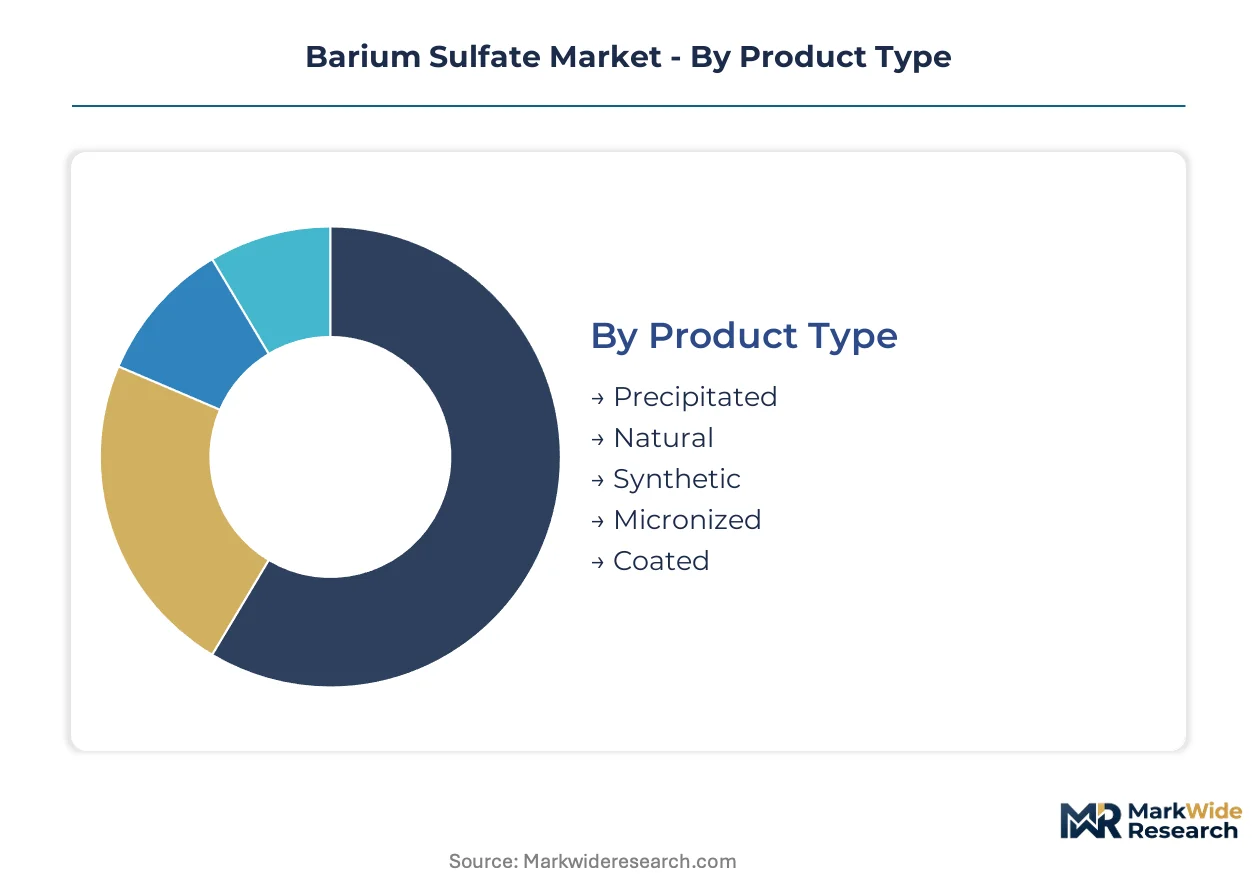
Barium sulfate procurement patterns diverge sharply across purity tiers and end-use specifications. Pharmaceutical and oilfield buyers operate under incompatible qualification protocols, forcing suppliers to maintain parallel production streams with dedicated quality systems.
Product Type:
Specification thresholds separate commodity barite from engineered precipitated grades, with processing intensity determining margin capture and regulatory burden.
- Precipitated:Manufactured through controlled chemical precipitation yielding sub-micron particle sizes and heavy metal content below pharmaceutical-grade thresholds. FDA-certified output serves radiology contrast manufacturers in Germany and Japan where imaging procedure volumes are climbing fastest.
- Natural:Milled barite ore dominates oilfield weighting agent volumes with specific gravity of 4.2-4.3, though OSHA silica exposure rules are compressing extraction-stage margins in Georgia and Nevada mining operations.
- Synthetic:Laboratory-derived grades bypass ore quality variability for electronics and specialty coating applications requiring batch-to-batch consistency.
- Micronized:Jet-milled particles achieve 1-5 micron distributions for high-solids ink formulations across East Asian printing clusters.
- Coated:Surface-modified particles with silane or polymer layers enhance dispersion in polar resin matrices for automotive waterborne coatings.
Natural barite leads on scale; precipitated grades lead on momentum.
Grade:
End-use certification requirements fragment the market into incompatible supply tiers with non-overlapping customer bases.
- Pharmaceutical:Micronized barium sulfate for oral and rectal contrast suspensions faces extended FDA validation cycles for particle size distribution and arsenic content limits.
- Industrial:Standard purity grades serve chemical processing and construction filler applications with minimal regulatory documentation burdens.
- Food:E516 additive-grade material for sugar refining and pigment applications complies with EFSA purity specifications for heavy metal contamination.
- Paints & Coatings:Dispersion-optimized grades command premium positioning in automotive OEM basecoat systems where gloss retention is specification-critical.
- Plastics:Surface-treated particles improve processing throughput in high-density polyethylene masterbatch compounding.
Paints & coatings grade captures the steepest price escalation; pharmaceutical grade faces the longest commercialization timelines.
Application:
Density requirements and formulation chemistry dictate grade selection across industrial and medical use cases.
- Oil & Gas Drilling:Deepwater operators are tightening procurement standards toward high-purity precipitated grades as synthetic hematite alternatives capture share in lower-density fluid formulations.
- Paper Industry:Filler applications in coated fine paper production specify brightness levels above 90% ISO for premium publication grades.
- Rubber Manufacturing:Barium sulfate extends compound density for sound-dampening automotive underbody coatings and industrial conveyor belting.
- Cosmetics Production:Micronized grades serve as opacifying agents in foundation and sunscreen formulations subject to EU cosmetic regulation scrutiny.
- Radiology:Contrast suspension volumes expand with aging demographics in Japan and Germany, though reimbursement pressure constrains price escalation.
Radiology leads on value per kilogram; oilfield drilling leads on absolute tonnage.
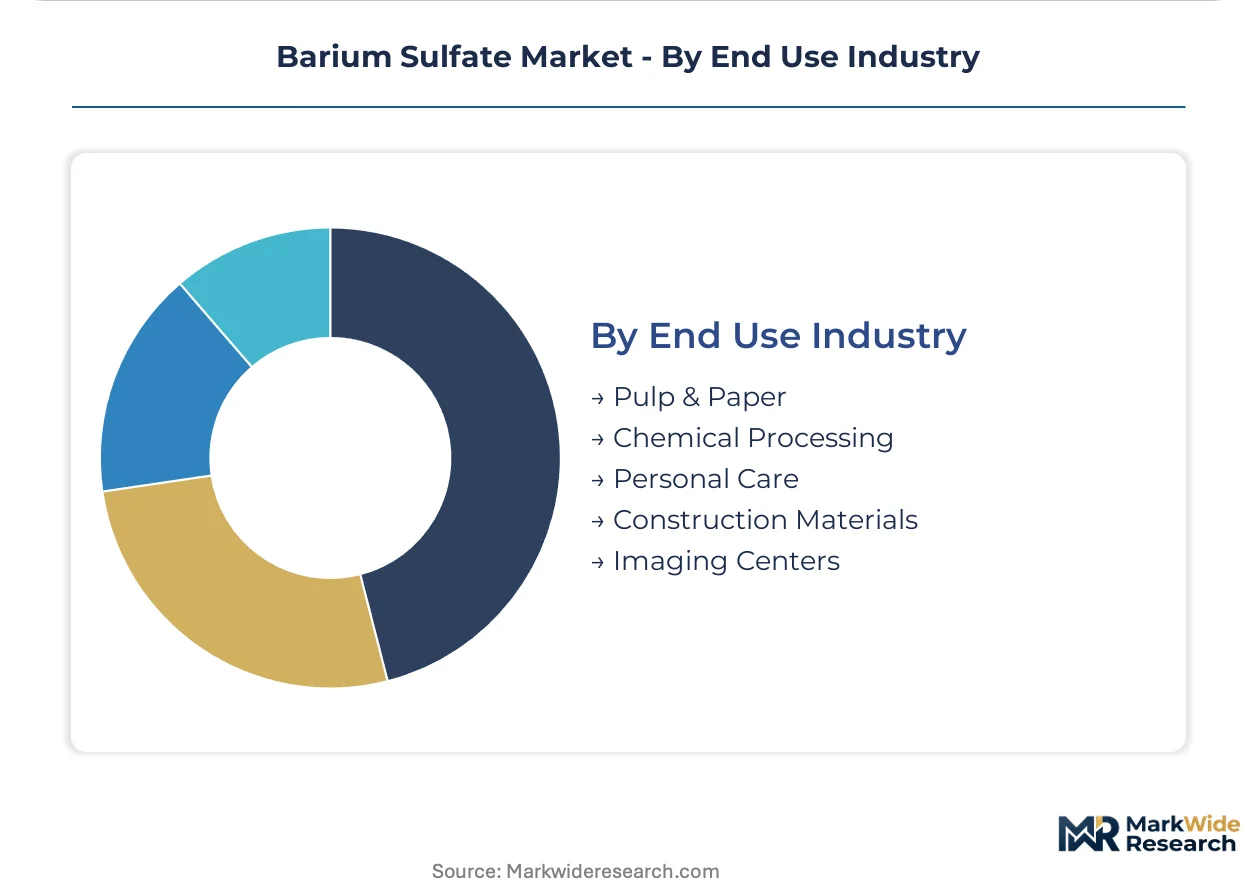
End Use Industry:
Customer concentration and qualification protocols determine supplier relationship structures across fragmented downstream markets.
- Pulp & Paper:Integrated mills in China's Shandong province source brightness-optimized grades through direct procurement relationships bypassing mineral traders.
- Chemical Processing:Catalyst support and reagent applications require consistent sulfate content specifications for downstream reaction efficiency.
- Personal Care:Multinational cosmetics formulators in France and Switzerland audit supply chains for heavy metal documentation under REACH Article 33 obligations.
- Construction Materials:Soundproofing panels and radiation shielding concrete specify high-density filler grades with controlled particle size for mix workability.
- Imaging Centers:Hospital procurement consortia in Germany negotiate multi-year offtake agreements with embedded purity guarantees for contrast media suppliers.
Pulp & paper leads on volume concentration; imaging centers lead on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting precipitated-grade production toward jurisdictions with streamlined chemical registration protocols and lower energy-input costs, while natural barite extraction remains anchored in ore-rich geographies facing tightening dust-exposure enforcement.
China
Shandong and Hebei provinces host integrated barite mining and chemical processing clusters that supply domestic coating manufacturers and export markets with scale economies. MEE enforcement of dual carbon goals is redirecting capital toward closed-loop precipitation systems that reduce wastewater discharge liabilities. Qingdao and Weifang processing hubs are upgrading filtration infrastructure to maintain export qualification under REACH importer protocols.
United States
OSHA permissible exposure limits for respirable crystalline silica are compelling milling facilities in Georgia and Nevada to retrofit enclosed conveyor systems and baghouse filtration. Cimbar Performance Minerals anchors North American supply through its barite mining and processing network. Deepwater drilling operators in the Gulf of Mexico are tightening procurement standards toward high-purity precipitated grades as synthetic alternatives capture formulation share.
Germany
EMA pharmaceutical-grade certification requirements and ECHA REACH registration protocols constrain importer qualification toward integrated chemical processors with certified purity thresholds. Solvay leverages its European precipitated barium sulfate capacity to serve pharmaceutical and specialty coating customers. Ludwigshafen and Leverkusen chemical corridors concentrate formulation expertise for automotive OEM waterborne basecoat systems.
Japan
PMDA oversight of radiopaque contrast media and METI industrial chemical standards shape procurement toward micronized and surface-coated grades. Sakai Chemical Industry specializes in engineered particles for ink and plastics applications across East Asian printing clusters. Osaka and Tokyo metropolitan areas concentrate imaging center demand as aging demographics expand contrast procedure volumes.
India
CDSCO pharmaceutical regulator documentation requirements and BIS industrial standards are elevating qualification barriers for precipitated-grade imports. Construction materials and chemical processing applications drive natural barite consumption for soundproofing panels and catalyst support. Gujarat and Maharashtra industrial corridors are developing downstream processing capacity to reduce feedstock dependence on Chinese ore shipments.
Barium Sulfate Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated chemical processors scale precipitation output to capture pharmaceutical-grade premiums while mining operators defend position through dust-control infrastructure investments. The market structures around three tiers: multinational chemical conglomerates with certified high-purity output, regional mining and milling specialists serving oilfield commodity demand, and Asia-Pacific micronization specialists targeting ink and plastics dispersion applications. Strategic portfolio diversification and backward integration into captive barite ore supply represent the dominant competitive vectors.
Among European chemical conglomerates, Solvay and Sachtleben Chemie occupy positions exemplifying the certified high-purity archetype, with regulatory qualification protocols that constrain market entry. Cimbar Performance Minerals anchors the North American mining and milling tier, representing the integrated extraction-stage model facing margin compression from OSHA compliance costs. Sakai Chemical Industry sits within the East Asian specialty-grade segment, occupying a position aligned with surface-modified particle demand from automotive coating and ink formulators.
| Leading Market Players |
|---|
| Solvay |
| BASF |
| Minerals Technologies |
| Huntsman Corporation |
| Cimbar Performance Minerals |
| Sachtleben Chemie |
| Nippon Chemical Industrial |
| Sakai Chemical Industry |
| Shaanxi Fuhua Chemical |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap mining specialists in Georgia and Nevada anchor North American natural barite supply, their limited depreciation runway forcing pricing discipline that preserves cash flow for OSHA-mandated dust-control retrofits while ceding premium precipitated-grade markets to integrated chemical processors.
Pricing Analysis
Distributor margins on natural barite grades have compressed to single-digit percentages as direct-procurement relationships between automotive OEMs and integrated chemical processors displace mineral trader intermediaries. Three-tier pricing structure across pharmaceutical-certified, industrial-standard, and oilfield-commodity levels reflects FDA validation burdens and REACH documentation intensity. Cost compression in natural-grade extraction is intensifying because OSHA silica compliance demands capital deployment at aging milling facilities. Oilfield drilling contractors exhibit highest price sensitivity, while pharmaceutical contrast manufacturers accept substantial premiums for micronized purity guarantees.
Supply Chain Analysis
Single-source vulnerability sits with China's Shandong-Hebei cluster, which feeds both domestic coating makers and precipitated-grade manufacturers dependent on consistent barite ore quality. The value chain draws from Vietnamese mining operations for brightness-optimized paper grades and Indian Gujarat processing hubs for construction filler applications. Tariff exposure on Chinese ore shipments threatens margin stability for synthetic-grade producers lacking captive feedstock. Distribution runs through direct offtake agreements with automotive OEMs and hospital procurement consortia, bypassing traditional trader networks in specification-critical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA crystalline silica enforcement and REACH registration protocols continuously elevate qualification barriers, consolidating procurement toward integrated processors with certified purity thresholds and documented compliance infrastructure.
For Market Incumbents: Anticipate synthetic hematite substitution in lower-density drilling fluids by deepening backward integration into captive barite ore supply in Nevada and Georgia mining districts. Prioritize FDA certification investment for micronized radiopaque grades as imaging procedure volumes climb in aging Japanese and German demographics, defending margin position against emerging East Asian specialty-grade competitors.
For New Entrants and Emerging Players: Digital-channel direct procurement platforms offer the most penetrable route into mid-tier industrial filler applications currently served by fragmented trader networks. Target surface-coated specialty grades for waterborne automotive coatings in German and Japanese OEM supply chains, leveraging silane coupling agent expertise to bypass capital-intensive precipitation infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional mining operators facing OSHA compliance cost inflation without pharmaceutical-grade certification upside. Five-to-ten-year viability favors integrated processors with dual oilfield and pharmaceutical-grade production streams. Watch for MEE enforcement of dual carbon goals in Shandong as the signal for Chinese supply disruption and Western capacity repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Barite Mining | Secures feedstock quality for precipitated-grade manufacturers facing Chinese ore concentration risk. |
| FDA Pharmaceutical-Grade Certification Investment | Unlocks premium positioning in radiopaque contrast suspensions for aging Japanese and German imaging markets. |
| Closed-Loop Precipitation System Upgrade | Reduces wastewater discharge liabilities under China's MEE dual carbon enforcement. |
| Direct Procurement Platform Development | Displaces mineral trader intermediaries in automotive OEM waterborne coating supply chains. |
| Surface Modification Chemistry Partnership | Integrates silane coupling agents for gloss retention specifications in German automotive basecoat systems. |
Research Methodology
Multiple input streams — executive interviews with barite mining operators and precipitated-grade plant managers, procurement lead discussions at drilling fluid manufacturers and automotive OEMs, and technical director consultations at coating formulators — were reconciled against customs trade data, SEC filings from listed chemical processors, and ECHA REACH registration databases. Bottom-up volume estimates from segmented end-use consumption were triangulated against top-down production capacity assessments across Shandong, Georgia, and Nevada processing hubs.
Historical shipment patterns were cross-referenced against panel input from industry participants to model grade-tier demand evolution across the projection horizon. Segmentation dimensions included purity tier, end-use industry, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized consumption intensity ratios. Forecast inputs incorporated OSHA silica enforcement timelines and MEE wastewater discharge trajectory assumptions.
Feedstock price volatility, regulatory timeline acceleration, and synthetic substitution adoption curves are the dominant revision risks that could reshape trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Alpha Bisabolol Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
North America Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Global Aerosol Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Ricinoleic Acid Market