
 Global Liquid Chromatography Systems Market | 2026-2036
Global Liquid Chromatography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Chromatography Systems Market Intelligence
A historical reliance on highly trained chromatographers with deep method development expertise is unwinding as software automation and pre-validated methods become standard. Agilent Technologies leverages its extensive software suites to simplify instrument control and data analysis for a broader user base. Waters Corporation differentiates through its specialized UPLC systems and column chemistries designed for complex biopharmaceutical applications. Thermo Fisher Scientific sustains its market position through a vast portfolio that spans from sample preparation to mass spectrometry detection.
Liquid chromatography systems are analytical instruments that separate, identify, and quantify components within a liquid mixture. These systems function by passing a sample through a column packed with a stationary phase, using high pressure to force the mobile phase through. While High-Performance Liquid Chromatography (HPLC) remains the workhorse, Ultra-Performance Liquid Chromatography (UPLC) systems represent the fastest-growing product type due to their superior speed and resolution. Pharmaceutical analysis continues to be the dominant application, driven by quality control and drug discovery workflows.
Stringent guidelines from regulatory bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA mandate rigorous analytical testing for drug products. These regulations directly influence instrument validation requirements and data integrity standards, such as 21 CFR Part 11 compliance. The critical decision for laboratory managers now involves balancing the initial capital cost of advanced systems against the long-term benefits of improved throughput and compliance.
Market Dynamics
The central market dynamic is the pressure on laboratory managers to justify high capital investment in advanced UPLC systems, driven by stringent regulatory mandates for data integrity and the productivity demands of biopharmaceutical development.
Growth Catalysts
- Biopharmaceutical Expansion:The rapid growth of monoclonal antibody and vaccine pipelines, particularly within China's biopharmaceutical clusters, directly stimulates instrument procurement for quality control.
- UPLC Technology:The ongoing transition from HPLC to Ultra-Performance Liquid Chromatography systems offers significant gains in analytical speed and resolution for complex sample analysis.
- Regulatory Mandates:Stringent guidelines from the US FDA, EMA, and China's NMPA require rigorous testing, pushing labs to adopt compliant, modern instrumentation.
Market Restraints
- High Capital Cost:The initial purchase price of advanced UPLC and multi-detector systems presents a significant financial barrier for academic institutions and smaller contract laboratories.
- Method Transfer Complexity:Migrating validated analytical methods from legacy HPLC platforms to modern UPLC systems is a time-consuming and resource-intensive process requiring re-validation.
- Substitution Threat:For less demanding, routine quality control tests, lower-cost refurbished HPLC systems or alternative analytical techniques can serve as sufficient, more economical options.
Strategic Opportunities
- Emerging Applications:Instrument capabilities can be adapted for growing analytical needs in food safety, environmental testing for contaminants like PFAS, and clinical diagnostics.
- Software Integration:Developing AI-powered chromatography data systems that automate method development, streamline data review, and predict instrument maintenance can create significant value.
- Geographic Expansion:Targeting publicly funded research institutes and generic pharmaceutical manufacturers in India and Brazil with robust, cost-effective HPLC systems opens new volume opportunities.
Industry Challenges
- Talent Scarcity:A persistent shortage of highly trained chromatographers capable of developing novel separation methods and troubleshooting complex instrument failures constrains laboratory productivity.
- System Integration:Integrating new liquid chromatography instruments and their associated data systems with a laboratory's existing LIMS and enterprise networks often creates technical hurdles.
- Compliance Burden:The continuous evolution of data integrity regulations, such as updates to Europe's Annex 11, necessitates ongoing investment in software upgrades and procedural training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Chromatography Systems Market |
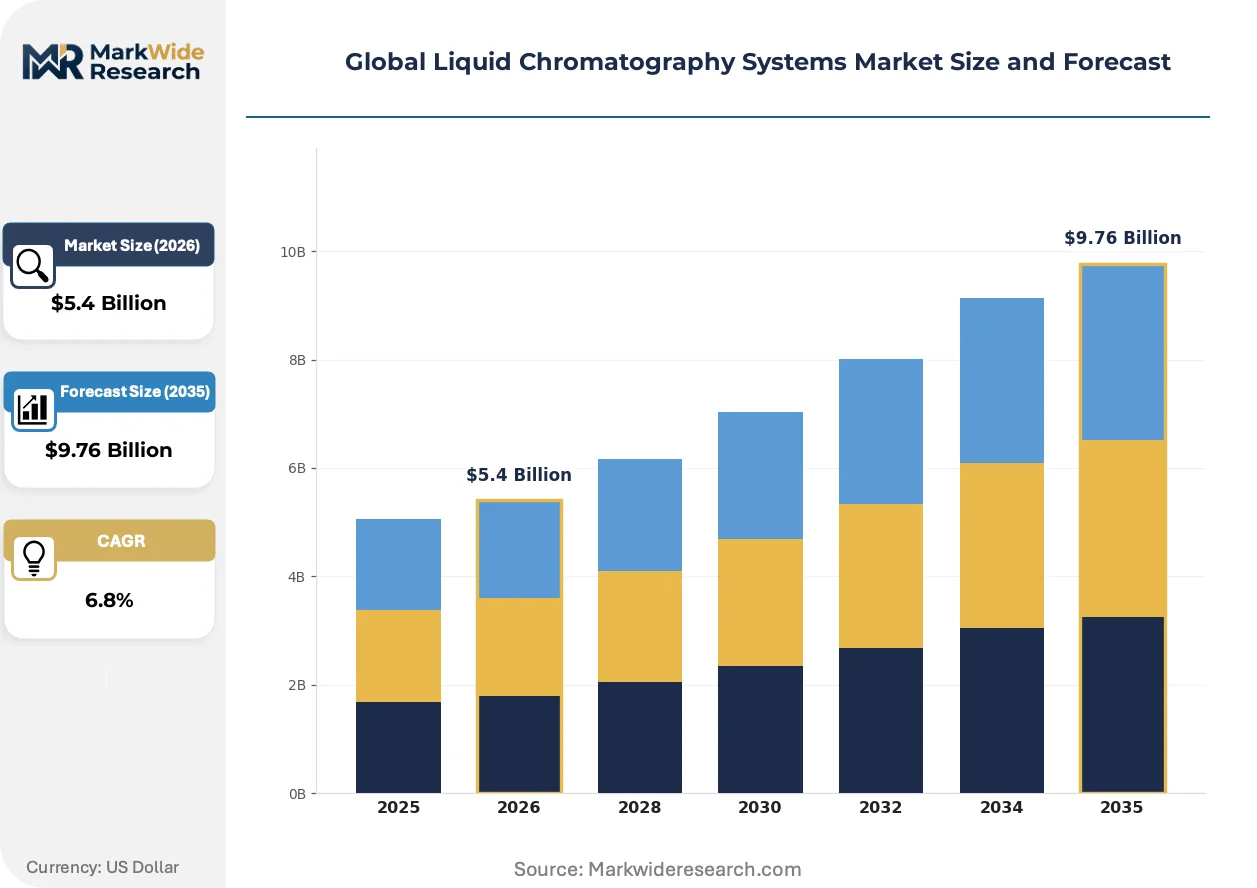
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance Liquid Chromatography, Ultra-Performance Liquid Chromatography, Ion Chromatography, Affinity Chromatography, Size Exclusion Chromatography Technology: Pump Technology, Detector Technology, Column Technology, Autosampler Technology, Software Integration Application: Pharmaceutical Analysis, Food Safety Testing, Environmental Monitoring, Chemical Research, Forensic Investigation End User: Contract Research Organizations, Academic Research Institutes, Biotechnological Firms, Quality Testing Laboratories, Diagnostic Centers |
| Companies Covered | Waters Corporation, Agilent Technologies, Thermo Fisher Scientific, Shimadzu Corporation, PerkinElmer, Bio-Rad Laboratories, Gilson, JASCO Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Chromatography Systems Market Strategic Shifts & Innovations
System intelligence and automation are transforming instrument operation. The focus is shifting from specialist-driven method development to software-guided workflows, making advanced chromatography accessible to a wider range of laboratory personnel.
Ultra-Performance Liquid Chromatography utilizes columns with sub-2 µm particle sizes to deliver superior separation speed and resolution. Biopharmaceutical QC laboratories are the primary adopters for analyzing complex biologics like monoclonal antibodies. This technology is displacing legacy HPLC methods in regulated drug development, where speed and data precision are critical.
Data integrity mandates, including the US FDA's 21 CFR Part 11 and Europe's Annex 11, now have stricter enforcement. This requires chromatography data systems to feature complete, unalterable audit trails and secure electronic records. Instrument manufacturers are most impacted, embedding these compliance-ready features directly into their core software platforms.
A transition toward flexible instrument acquisition models, including leasing and reagent rental agreements, is gaining traction. This model challenges the traditional capital expenditure sales cycle, especially for contract research organizations. The shift is most pronounced in North American and European biopharmaceutical clusters where managing operating expenses is a priority.
Global Liquid Chromatography Systems Market Segmentation
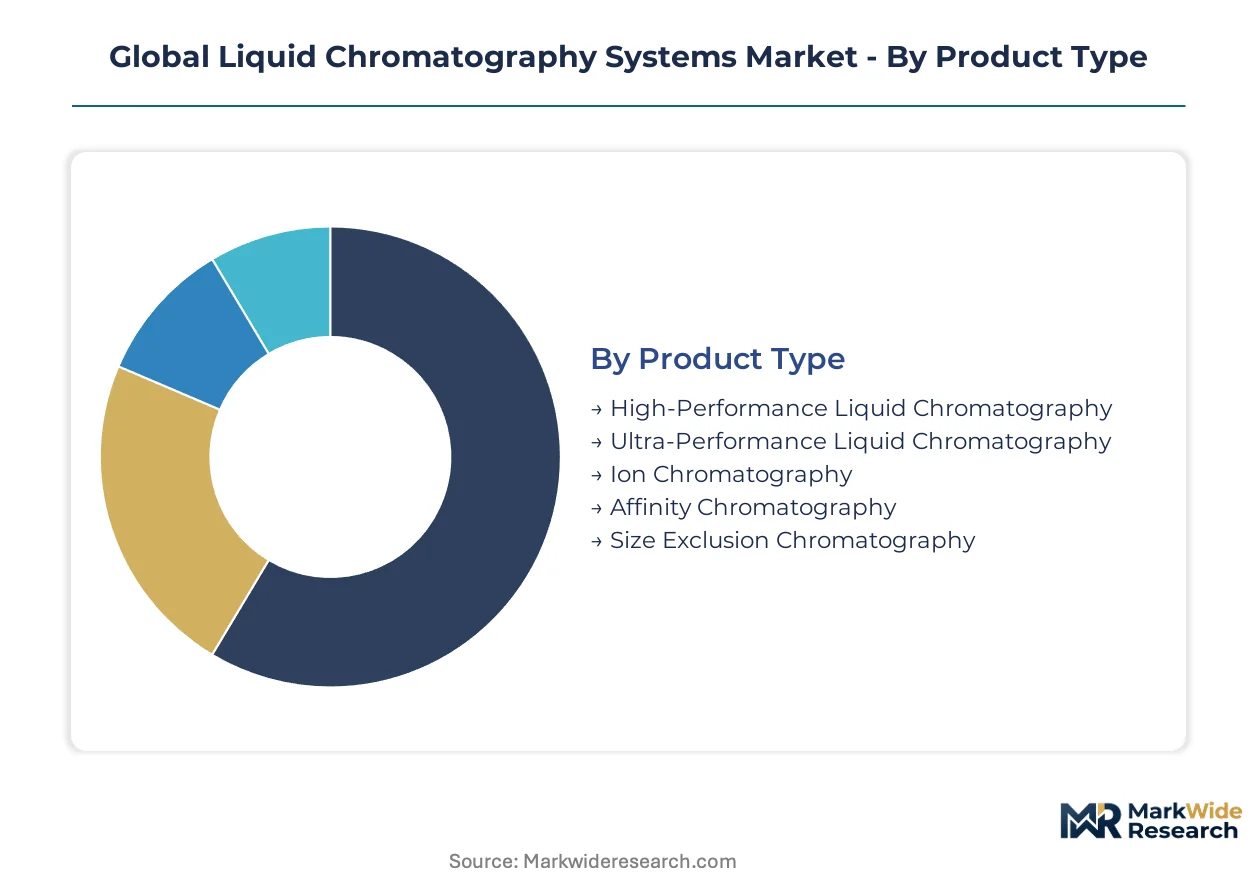
The Global Liquid Chromatography Systems Market is intricately segmented across various dimensions, reflecting the diverse technological needs and application landscapes of end-users. Understanding these segments is crucial for manufacturers to tailor product development and for laboratories to optimize instrument procurement strategies.
Product Type:
Product type segmentation highlights the ongoing pressure from advanced technologies displacing legacy systems, particularly where analytical precision and speed are paramount.
- Ultra-Performance Liquid Chromatography:These systems utilize columns packed with sub-2 µm particles, delivering significantly enhanced speed, resolution, and sensitivity for complex separations. Demand concentrates in biopharmaceutical quality control laboratories and advanced biologics development, particularly across the US and European biopharmaceutical clusters.
- High-Performance Liquid Chromatography:As the traditional workhorse, HPLC systems offer robust, versatile separation capabilities for a wide range of analytical tasks using larger particle columns. Procurement remains strong for routine quality control, academic research institutes, and generic pharmaceutical manufacturers in India and Brazil.
- Ion Chromatography:This technique specializes in the separation and quantification of ions and polar molecules, often used for water analysis and environmental monitoring.
- Affinity Chromatography:Systems leveraging affinity interactions are critical for purifying biomolecules, especially in protein research and biopharmaceutical manufacturing.
- Size Exclusion Chromatography:This method separates molecules based on their hydrodynamic volume, essential for polymer characterization and protein aggregation studies.
High-Performance Liquid Chromatography retains volume leadership; Ultra-Performance Liquid Chromatography holds the steepest expansion curve.
Technology:
Technology segmentation reveals how innovation in specific system components drives both performance enhancements and differentiated pricing structures across the market.
- Detector Technology:This segment includes a range of detection methods such as UV-Vis, Photodiode Array (PDA), Fluorescence, Refractive Index (RI), and Mass Spectrometry (MS) detectors, each offering specific analytical capabilities. Demand for advanced and specialized detectors is concentrating in biopharmaceutical research and development for complex molecule characterization.
- Software Integration:Chromatography Data Systems (CDS) and Laboratory Information Management Systems (LIMS) are foundational for instrument control, data acquisition, processing, and compliance with regulations like 21 CFR Part 11. Regulated pharmaceutical laboratories prioritize robust software solutions for data integrity and streamlined workflows.
- Pump Technology:Pumps are essential for delivering the mobile phase at precise flow rates and pressures, ensuring consistent chromatographic separation.
- Column Technology:This encompasses the diverse range of stationary phases and column dimensions that dictate separation efficiency and selectivity for various analytes.
- Autosampler Technology:Autosamplers automate sample injection, improving throughput and reproducibility in high-volume analytical environments.
Software Integration innovations are central to compliance efforts; Column Technology advancements continuously refine separation capabilities.
Application:
Application segmentation illustrates the diverse analytical needs driving instrument procurement, with core industries dominating overall system utilization.
- Pharmaceutical Analysis:This dominant application includes quality control, research and development, drug discovery, and pharmacokinetics studies for both small molecules and biologics. Demand is consistent across global pharmaceutical companies and contract manufacturing organizations due to stringent regulatory requirements.
- Food Safety Testing:Liquid chromatography systems are vital for detecting contaminants like pesticides, mycotoxins, and additives, as well as for nutritional analysis in food products. Stringent regulations from bodies like the US FDA and European Food Safety Authority drive instrument adoption in food processing and government testing laboratories.
- Environmental Monitoring:These applications focus on analyzing water, soil, and air samples for pollutants, including emerging contaminants like PFAS.
- Chemical Research:Academic and industrial chemical research laboratories utilize LC systems for compound synthesis, purification, and characterization.
- Forensic Investigation:LC systems assist in toxicology screening, drug identification, and analysis of trace evidence in forensic laboratories.
Pharmaceutical Analysis consistently represents the largest application segment; Environmental Monitoring is experiencing notable expansion due to emerging contaminant concerns.
End User:
End user segmentation clarifies the varied operational requirements and purchasing power influencing instrument selection across different laboratory environments.
- Biotechnological Firms:These firms drive demand for advanced UPLC and specialized LC systems for the development, production, and quality control of biopharmaceuticals, gene therapies, and vaccines. Procurement is concentrated in major biopharmaceutical hubs across the United States, Europe, and China.
- Contract Research Organizations:CROs require high-throughput, versatile LC systems to support diverse client projects, ranging from method development to large-scale sample analysis for pharmaceutical and biotech companies. These organizations prioritize scalability and robust data management capabilities.
- Academic Research Institutes:Universities and research institutions use LC systems for fundamental scientific exploration, method development, and student training across various disciplines.
- Quality Testing Laboratories:Independent and in-house quality control labs across industries utilize LC systems for routine product testing and compliance verification.
- Diagnostic Centers:Clinical diagnostic laboratories employ LC systems for biomarker analysis, therapeutic drug monitoring, and disease detection.
Biotechnological Firms drive innovation in high-end system adoption; Academic Research Institutes remain fundamental for foundational research and talent development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's stringent guidelines for pharmaceutical analysis significantly influence the global liquid chromatography systems market. These regulations mandate rigorous analytical testing, driving demand for compliant instrumentation across the biopharmaceutical sector. This regulatory environment fosters innovation and technology adoption within the United States and globally.
United States
The United States market sees strong demand from biopharmaceutical development, particularly for monoclonal antibodies and vaccine production. US FDA regulations, including 21 CFR Part 11, necessitate advanced UPLC systems for data integrity and compliance. Major biopharmaceutical hubs like Boston and San Francisco actively procure high-throughput systems for drug discovery and quality control.
China
Biopharmaceutical expansion in China fuels rapid procurement of liquid chromatography systems. China's NMPA mandates stringent analytical testing for drug products, directly impacting instrument validation requirements. Shanghai's biopharmaceutical clusters concentrate significant investment in UPLC technology for new drug development and manufacturing quality assurance.
Germany
European pharmaceutical analysis drives demand for advanced LC systems in Germany, a key biopharmaceutical hub. The European Medicines Agency (EMA) guidelines push for high-resolution separation techniques and robust data integrity features. Research centers in Munich and Berlin integrate UPLC systems for complex biologics characterization and quality control.
India
Generic pharmaceutical manufacturers in India require cost-effective yet reliable HPLC systems for routine quality control and export compliance. India's CDSCO regulations govern drug product testing, influencing procurement decisions for analytical instruments. Pharmaceutical manufacturing clusters in Hyderabad and Gujarat consistently upgrade their analytical capabilities.
Japan
Advanced biopharmaceutical research and development in Japan generates consistent demand for high-performance liquid chromatography systems. Japan's PMDA ensures rigorous quality standards for drug substances, promoting the adoption of precise analytical methods. The Tokyo and Osaka regions house numerous research institutes and pharmaceutical companies investing in UPLC technology.
Global Liquid Chromatography Systems Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the liquid chromatography systems market. This market structure features a few large, diversified analytical instrument providers alongside numerous niche players focusing on specific technologies or applications. Strategic archetypes include full-portfolio providers, UPLC specialists, and value-segment suppliers catering to different price points. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand application reach.
Full-portfolio providers such as Agilent Technologies and Thermo Fisher Scientific exemplify the integrated leader archetype, offering extensive analytical instrumentation and software solutions. Waters Corporation occupies a position as a UPLC specialist, differentiating through its advanced systems and column chemistries tailored for complex biopharmaceutical applications. These companies anchor the market through continuous innovation in instrument capabilities and software integration, catering to diverse analytical needs across regulated industries. Their offerings span from sample preparation to mass spectrometry detection, addressing the comprehensive requirements of modern laboratories.
| Leading Market Players |
|---|
| Waters Corporation |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| PerkinElmer |
| Bio-Rad Laboratories |
| Gilson |
| JASCO Corporation |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
High capital costs for advanced liquid chromatography systems demand substantial capacity utilization to achieve favorable unit economics, shaping both supply concentration and price floors across the market.
Pricing Analysis
Geographic price differentiation exists, with premium pricing in mature biopharmaceutical markets like the United States and Europe, contrasting with more competitive pricing in emerging economies such as India and Brazil. Value-based pricing dominates for Ultra-Performance Liquid Chromatography systems, reflecting their superior speed and resolution, while High-Performance Liquid Chromatography systems often follow a transactional model. Price differentiation stems from technology sophistication and the level of integrated software support. Pricing pressure stems from competition in the routine HPLC segment, particularly from refurbished systems. Academic institutions and smaller contract research organizations are highly price-sensitive, whereas large biopharmaceutical firms prioritize performance and compliance.
Supply Chain Analysis
Strategic stockpiles for critical detectors and specialized column chemistries often supplement just-in-time inventory for standard components due to their specialized manufacturing processes. Geographic supply concentration for high-precision components centers on Germany, the United States, and Japan. Raw material dependencies include specialized silica media for advanced columns, precision pump components, and sophisticated detector electronics. Single-source vulnerability for highly specialized UPLC column chemistries presents a structural supply chain risk. Distribution runs through direct sales channels for major biopharmaceutical clients, complemented by a network of distributors serving smaller laboratories and academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global liquid chromatography systems market is experiencing a platform-economics inflection, driven by the emergence of integrated software ecosystems and AI-powered data analysis capabilities.
For Market Incumbents:Compound existing software capabilities and extensive customer relationships to solidify market leadership. Expand software integration to offer comprehensive, AI-powered chromatography data systems that automate method development and streamline data review. This strategy mitigates the threat from disruptive analytics platforms and reinforces compliance with evolving data integrity regulations like 21 CFR Part 11. Invest in R&D for advanced column chemistries and novel detector technologies to maintain performance differentiation.
For New Entrants and Emerging Players:Anchor in niche application areas that require robust, cost-effective solutions, such as environmental testing for emerging contaminants like PFAS or specific clinical diagnostics. Target underpenetrated segments like publicly funded research institutes and generic pharmaceutical manufacturers in India and Brazil. A strong go-to-market angle involves offering reliable High-Performance Liquid Chromatography systems with user-friendly software interfaces and simplified method transfer protocols. Focus on localized support and training to build trust in these regions.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors firms with strong software intellectual property and specialized biopharmaceutical application expertise, offering long-term viability over the next five to ten years. Acquisition targets should include companies developing AI-powered chromatography data systems, advanced column chemistries, or specialized detection technologies for complex biologics. The signal to watch is the consolidation of software platforms or new regulatory mandates for AI validation in analytical workflows, indicating a shift in industry standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Software Integration | Automates workflows and enhances data integrity, crucial for regulated biopharmaceutical environments. |
| Invest in AI/ML for Method Development | Reduces reliance on highly trained chromatographers, broadening market access for advanced techniques. |
| Develop Cost-Effective HPLC Systems | Captures volume in price-sensitive emerging markets and academic research institutions. |
| Target Emerging Application Niches | Diversifies revenue streams beyond traditional pharmaceutical analysis into new growth areas. |
| Offer Flexible Acquisition Models | Reduces capital expenditure barriers for contract research organizations and smaller laboratories. |
Research Approach
A spread of perspectives from biopharmaceutical R&D directors, QC managers, lab managers, and instrument engineers converged on the working assumptions for this study. Primary interviews with these industry stakeholders provided qualitative insights, which were then validated against secondary data. Secondary sources included regulatory guidelines from the US FDA, EMA, and China's NMPA, scientific publications, and industry association reports. Bottom-up and top-down triangulation ensured robust data interpretation.
Segmentation dimensions modeled included product type, technology, application, end user, and geographic region across the analysis window. The analytical framework derived compound annual growth rates by assessing historical market performance and projecting future trends based on key drivers and restraints. Industry-specific forecast inputs incorporated biopharmaceutical R&D spending, new drug approvals, and regulatory compliance investment trends. This comprehensive approach ensures a nuanced understanding of market dynamics.
Material uncertainties — including geopolitical trade policies or unforeseen technological breakthroughs — sit outside the modeled envelope, as do significant shifts in global biopharmaceutical funding. Forecasts reflect assumptions documented through extensive primary and secondary research. Revision becomes warranted when major changes in regulatory enforcement or disruptive technological advancements cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Pitting Machines Market
Testing Equipment
Durometers Market
Testing Equipment
Rheometer Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market