
 Chromatography Data Systems Market | 2026-2036
Chromatography Data Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatography Data Systems Market Intelligence
Cloud-based SaaS deployment is rebalancing the economic model for chromatography data systems, displacing traditional on-premise software licenses. Thermo Fisher Scientific leverages its extensive instrument portfolio to bundle integrated software solutions. Waters Corporation differentiates through its specialized software designed for high-performance liquid chromatography and mass spectrometry. Agilent Technologies competes with a focus on open-platform software compatible with multi-vendor laboratory environments.
A chromatography data system is a software application that controls chromatography instruments, acquires data, processes it, and generates final reports. These systems are essential for ensuring data integrity and automating workflows from sample injection to final result calculation. Cloud-based deployment represents the fastest-growing segment, driven by scalability and remote access needs. Within applications, pharmaceutical research and food safety testing command the largest share due to stringent quality control requirements.
Regulations such as the US FDA's 21 CFR Part 11 and Europe's EudraLex Annex 11 set strict standards for electronic records and signatures, directly shaping software design. In China, the NMPA is aligning its data integrity guidelines with these international standards, mandating compliant CDS for drug approvals. Vendor selection will increasingly depend on a system's ability to demonstrate compliance with a harmonizing but multi-jurisdictional regulatory landscape.
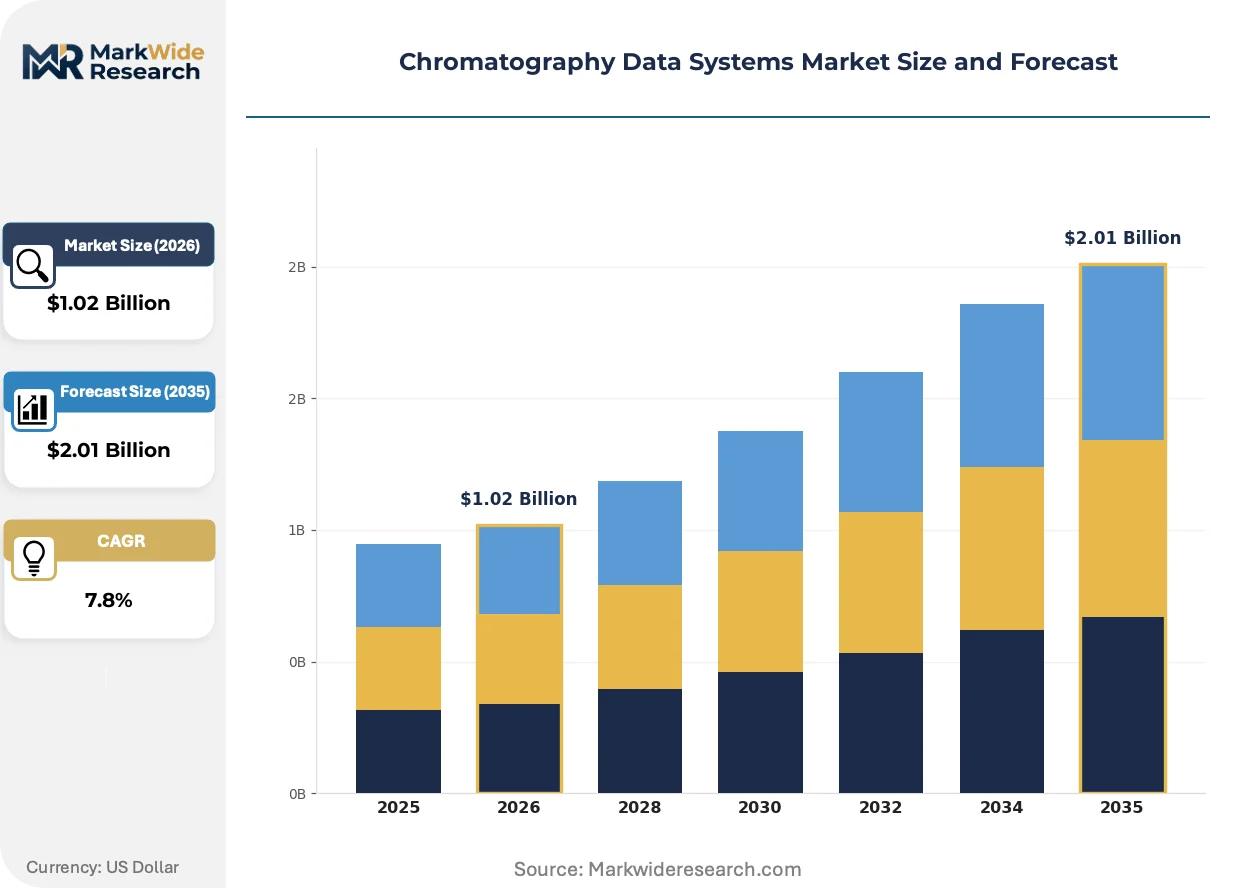
Market Dynamics
The central dynamic shaping the market is the regulatory imperative for data integrity, which is accelerating the transition from legacy on-premise systems to validated, cloud-native chromatography data system platforms.
Growth Catalysts
- Pharmaceutical R&D:Expansion in biopharmaceutical research for biologics and cell therapies necessitates advanced CDS for complex data analysis and reporting.
- Regulatory Mandates:Stricter data integrity rules, including the FDA's 21 CFR Part 11, compel laboratories to upgrade non-compliant software systems.
- Food Safety Testing:Increased testing for contaminants and allergens drives demand for automated CDS workflows to handle high sample throughput with auditable results.
Market Restraints
- High Validation Cost:The expense and time needed to validate a new CDS against GxP standards is a major barrier for smaller laboratories.
- Instrument Interoperability:Lack of universal communication protocols between multi-vendor instruments and a single CDS creates integration challenges and vendor lock-in.
- Legacy System Migration:Migrating historical data from entrenched on-premise systems to new cloud platforms presents a complex operational hurdle for many labs.
Strategic Opportunities
- AI and Machine Learning:Integrating AI/ML algorithms into CDS offers opportunities for predictive maintenance, automated peak integration, and anomaly detection.
- Emerging Geographic Markets:Pharmaceutical growth in India and Brazil creates demand for compliant CDS as local regulators like ANVISA adopt stricter data rules.
- Environmental Monitoring:Expanding regulations for monitoring pollutants like PFAS in water and soil opens a new application vertical for specialized CDS.
Industry Challenges
- Cloud Data Security:Securing sensitive IP and patient data in cloud-based CDS against cyber threats is a primary operational challenge for laboratories.
- Specialized Talent Shortage:A deficit of personnel with hybrid expertise in chromatography, software validation, and IT management hinders effective CDS implementation.
- System Integration Complexity:Integrating a new CDS with existing LIMS and enterprise systems remains a significant and costly technical hurdle for many organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatography Data Systems Market |
| Market Size in 2026 | $1.02 Billion |
| Market Size in 2035 | $2.01 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioinformatics Software, Data Management Systems, Analytical Instruments Software, Reporting Tools, Workflow Automation, Data Visualization Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Enterprise Level Application: Pharmaceutical Research, Environmental Testing, Food Safety, Chemical Analysis, Forensic Examination, Academic Research End User: Pharmaceutical Manufacturers, Research Laboratories, Quality Control Units, Food Testing Labs, Chemical Businesses, Forensic Institutions |
| Companies Covered | Shimadzu Corporation, Bruker Corporation, Waters Corporation, JASCO International, Bio-Rad Laboratories, Agilent Technologies, PerkinElmer Inc., DataApex, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatography Data Systems Market Strategic Shifts & Innovations
The evolution toward platform-based ecosystems is transforming the market. This shift prioritizes interoperability, subscription-based economics, and globally harmonized compliance features over standalone, single-function software.
Cloud-based SaaS platforms provide scalable, remote access to instrument control and data analytics. Biopharmaceutical firms and contract research organizations are rapidly adopting this model to support multi-site collaboration. This evolution is decentralizing data management and analysis capabilities away from a single physical laboratory to a distributed network of users.
A global convergence of data integrity guidelines is underway, with China's NMPA aligning its rules with the US FDA's 21 CFR Part 11. This harmonization requires software vendors to build a single, globally compliant platform. Pharmaceutical and biotech segments are most affected, demanding comprehensive validation documentation for multiple jurisdictions from their CDS suppliers.
Subscription-based procurement models are rapidly displacing traditional perpetual software licenses. This SaaS approach converts large capital expenditures into predictable operational expenses, benefiting budget-conscious academic labs and startups. The shift is most pronounced in North American and European biopharmaceutical research hubs where scalability and financial flexibility are key priorities.
Chromatography Data Systems Market Segmentation
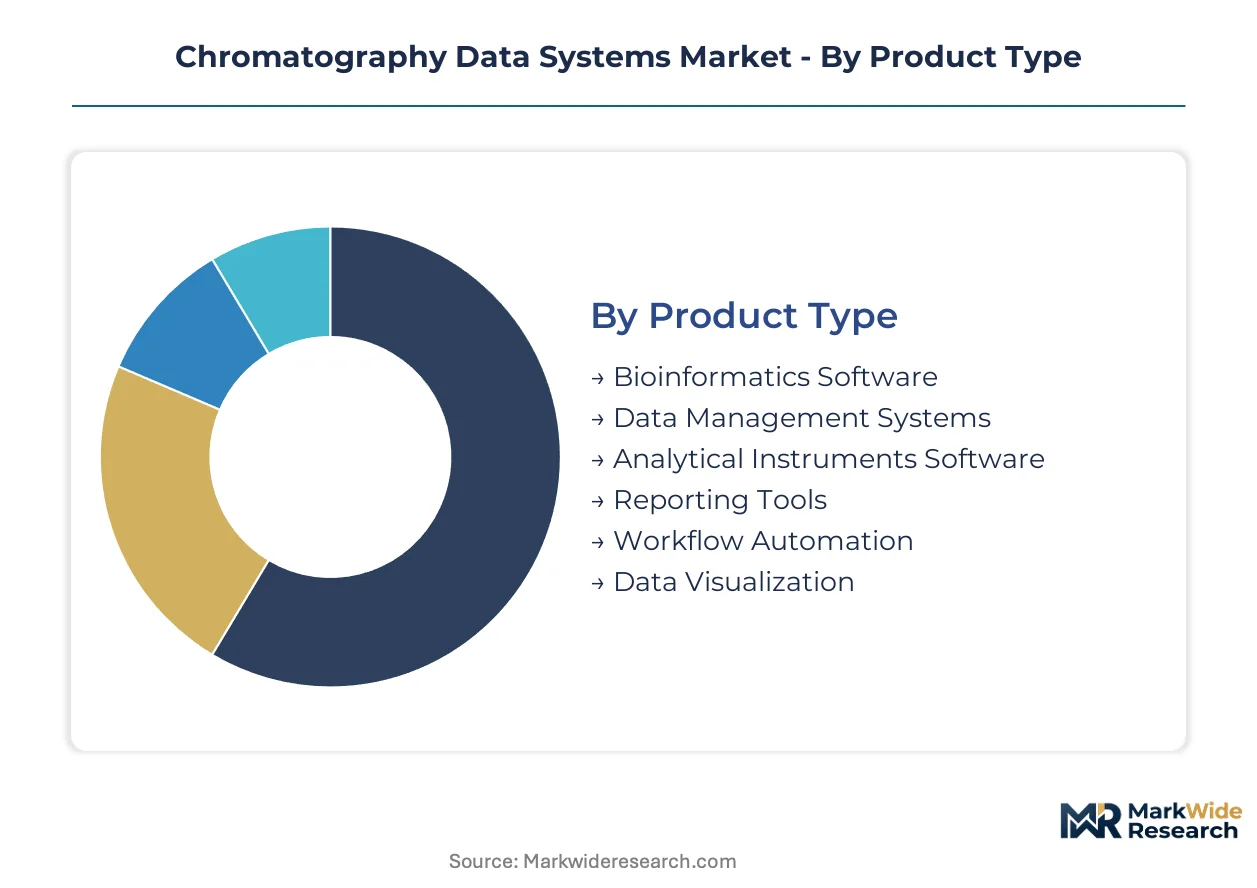
Chromatography data system segmentation reflects the diverse technological requirements and stringent regulatory landscapes across scientific disciplines. Understanding these distinct segments is crucial for vendors to tailor solutions that meet specific industry compliance and operational needs.
Product Type:
The array of chromatography data system products demands rigorous validation, particularly for applications requiring compliance with regulations like the FDA's 21 CFR Part 11 and EMA guidelines.
- Data Management Systems:These core software platforms control instrument operation, acquire raw data, and provide secure storage. Demand concentrates within biopharmaceutical R&D in the United States, driven by the need for auditable data trails.
- Workflow Automation:This software streamlines laboratory processes from sample preparation to final report generation, reducing manual errors. Pharmaceutical manufacturers in Germany prioritize these tools to enhance efficiency and meet GxP standards.
- Bioinformatics Software:Specialized tools for analyzing complex biological data, particularly in biologics and cell therapy research.
- Analytical Instruments Software:Dedicated software interfaces for specific chromatography instruments, ensuring precise control and data acquisition.
- Reporting Tools:Applications designed to generate customizable and compliant reports from processed chromatographic data.
- Data Visualization:Software modules that offer graphical representation and interactive exploration of large analytical datasets.
Leading the category by volume: Data Management Systems. Growing fastest: Workflow Automation.
Deployment:
Deployment models significantly impact initial investment and ongoing operational costs for laboratories, influencing accessibility and scalability.
- Cloud-Based:These platforms offer remote access, scalability, and reduced IT infrastructure overhead, often delivered as Software-as-a-Service. Biopharmaceutical firms in Switzerland are rapidly adopting this model for multi-site collaboration.
- On-Premise:Traditional installations hosted on local servers provide complete data control and customization, favored by organizations with strict internal security policies. Legacy systems in older research institutions often remain on-premise due to migration complexities.
- Hybrid:A combination of on-premise and cloud components, balancing control with remote access flexibility.
- SaaS:Subscription-based software delivery over the internet, providing continuous updates and support without large capital expenditure.
- Enterprise Level:Comprehensive solutions designed for large organizations, integrating with existing LIMS and ERP systems.
Cloud-Based deployment holds the largest share, while Hybrid solutions demonstrate substantial growth.
Application:
Chromatography data systems find diverse utility across industries, driven by specific analytical requirements and regulatory oversight.
- Pharmaceutical Research:Utilized for drug discovery, development, and quality control, supporting complex analysis of biologics and small molecules. This application commands the largest share due to stringent regulatory requirements from the FDA and EMA.
- Food Safety:Essential for detecting contaminants, allergens, and nutritional components in food products, ensuring consumer protection. Increased testing mandates in the US and Europe drive demand for high-throughput, auditable systems.
- Environmental Testing:Measures pollutants like PFAS in water and soil, crucial for compliance with environmental protection agency regulations.
- Chemical Analysis:Supports purity assessments and compositional analysis in various chemical industries.
- Forensic Examination:Used in criminal investigations for substance identification and toxicology analysis.
- Academic Research:Employed in universities and research institutions for fundamental scientific studies and method development.
Pharmaceutical Research generates significant demand, with Environmental Testing expanding most quickly.
End User:
End-user segments reflect distinct operational scales and regulatory environments, influencing CDS feature prioritization.
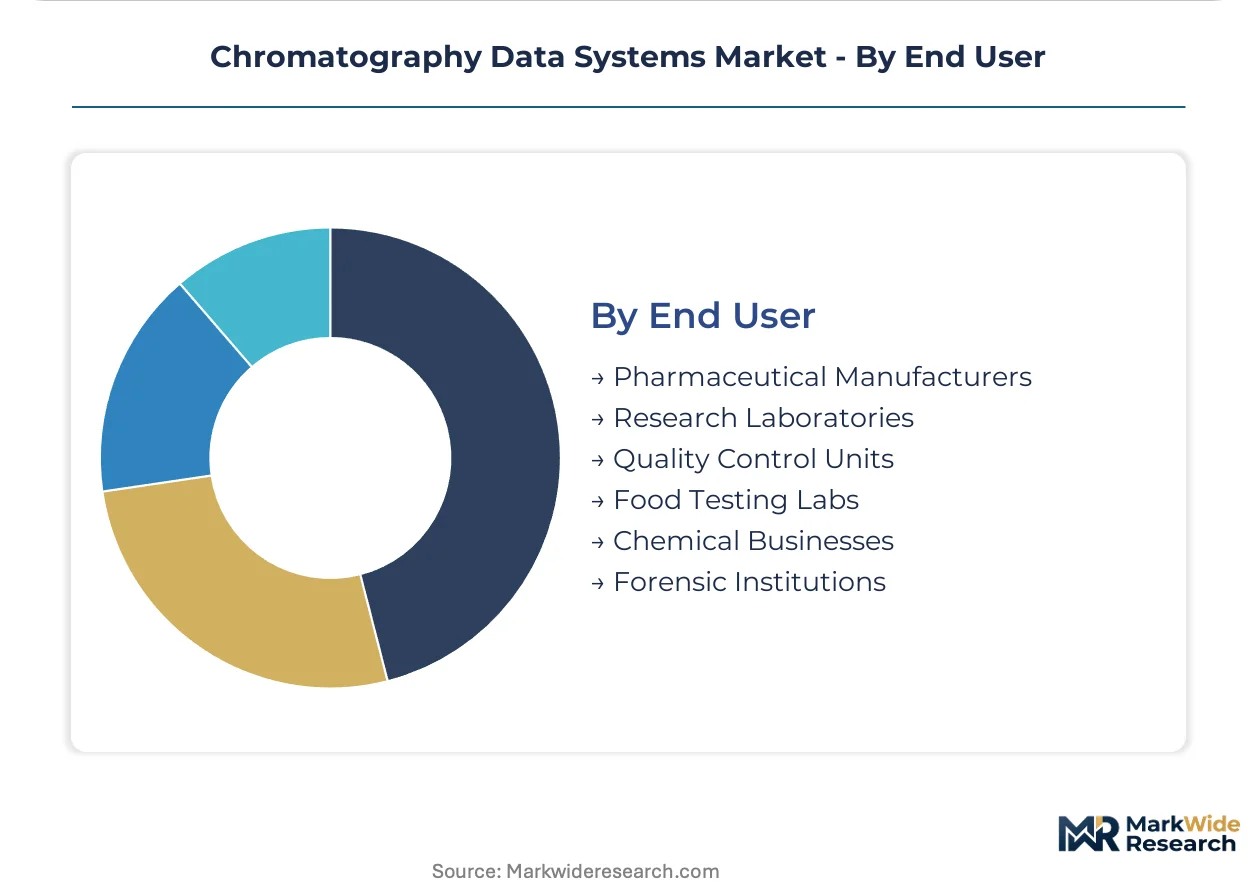
- Pharmaceutical Manufacturers:These organizations require robust, validated CDS for R&D, manufacturing, and quality assurance processes. Their demand is concentrated in major drug-producing regions like the United States and Ireland.
- Research Laboratories:Academic and contract research organizations use CDS for diverse analytical projects, often prioritizing flexibility and multi-vendor instrument compatibility. Laboratories in India and Brazil are increasing their CDS investments.
- Quality Control Units:Departments focused on ensuring product quality and compliance with industry standards.
- Food Testing Labs:Specialized facilities performing chemical analysis on food and beverage samples.
- Chemical Businesses:Companies involved in the production and analysis of various chemical compounds.
- Forensic Institutions:Government and private laboratories conducting forensic analysis for legal purposes.
Pharmaceutical Manufacturers represent the largest user base, and Food Testing Labs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromatography data system demand concentrates heavily within established biopharmaceutical research and development hubs globally. Stricter data integrity mandates under regulations such as the FDA's 21 CFR Part 11 and EMA guidelines compel software upgrades across these regions. This regulatory pressure drives significant investment in compliant CDS platforms.
United States
Demand for advanced CDS solutions stems from extensive pharmaceutical research for biologics and cell therapies. The FDA's 21 CFR Part 11 sets stringent standards for electronic records, necessitating validated software. Major biopharmaceutical clusters in Boston and San Francisco actively upgrade systems to ensure auditability.
Germany
Pharmaceutical manufacturers prioritize workflow automation software to enhance efficiency and meet GxP standards. Europe's EudraLex Annex 11 guidelines shape software design for electronic signatures and data retention. Research institutions in Munich and Berlin are adopting cloud-based platforms for multi-site collaboration.
Switzerland
Biopharmaceutical firms in Switzerland rapidly adopt cloud-based CDS for multi-site collaboration and remote access. Swissmedic regulations require robust data integrity, driving investments in scalable, compliant systems. Basel's pharmaceutical industry leads in implementing advanced analytical instrument software for complex drug development.
China
The expanding pharmaceutical sector in China drives demand for compliant chromatography data systems. The NMPA is aligning its data integrity guidelines with international standards, mandating compliant CDS for drug approvals. Research centers in Shanghai and Beijing are rapidly modernizing their laboratory informatics infrastructure.
India
Pharmaceutical growth in India creates significant demand for compliant CDS as local regulators like the CDSCO adopt stricter data rules. India's CDSCO is enhancing oversight on data integrity, pushing laboratories to upgrade. Major pharmaceutical manufacturing hubs in Hyderabad and Ahmedabad are investing in new validated systems.
Chromatography Data Systems Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the chromatography data systems market. The competitive landscape features a blend of established analytical instrument manufacturers and specialized software providers, each vying for market dominance. Strategic archetypes include integrated solution providers, niche software innovators, and open-platform developers. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and technological capabilities, adapting to evolving regulatory demands.
Integrated solution providers such as Thermo Fisher Scientific exemplify the strategy of leveraging an extensive instrument portfolio to bundle comprehensive software solutions. Waters Corporation occupies a specialized position, differentiating through its specialized software designed specifically for high-performance liquid chromatography and mass spectrometry applications, catering to advanced analytical needs. Agilent Technologies, a prominent player, represents the archetype focused on open-platform software, ensuring compatibility across multi-vendor laboratory environments for broader appeal and flexibility.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Bruker Corporation |
| Waters Corporation |
| JASCO International |
| Bio-Rad Laboratories |
| Agilent Technologies |
| PerkinElmer Inc. |
| DataApex |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Venture capital-backed software firms shape pricing models in chromatography data systems, encouraging flexible subscription offerings and influencing infrastructure procurement strategies.
Pricing Analysis
Volume growth in cloud-based SaaS deployments balances against margin pressures from intense competition among software providers. Subscription-based SaaS models dominate, converting large capital expenditures into predictable operational expenses. Comprehensive validation documentation for multiple jurisdictions and multi-vendor instrument compatibility drive premium pricing. Cloud migration and increasing competition from open-platform providers create pricing softness. Academic labs and startups exhibit higher price sensitivity compared to large pharmaceutical manufacturers.
Supply Chain Analysis
Regulatory mandates for data localization in China and Europe are reshaping the supply chain for cloud-based chromatography data systems. Core development and support functions concentrate in the United States, Germany, and Switzerland. The supply chain relies on robust cloud infrastructure providers and a specialized pool of software development talent. Cloud data security concerns and the shortage of hybrid IT expertise represent significant structural risks. Distribution primarily runs through direct sales channels and bundled offerings with analytical instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chromatography data systems market is in a technology-transition phase, as cloud-native platforms rapidly displace legacy on-premise software solutions.
For Market Incumbents:Anchor existing client bases by leveraging extensive instrument portfolios and deep regulatory compliance expertise. Incumbents should invest in open-platform software development to counter the threat from niche cloud-native providers. Offering comprehensive validation services for FDA 21 CFR Part 11 and EMA guidelines reinforces customer loyalty. Expanding integrated software solutions across diverse instrument lines protects market share against specialized software innovators.
For New Entrants and Emerging Players:Contract research organizations represent a key channel partner type for new entrants seeking market penetration. New entrants should target underserved academic labs and startups with flexible, subscription-based SaaS offerings. Integrating AI and machine learning for automated peak integration provides a differentiated value proposition. Focusing on emerging geographic markets like India, where regulatory standards are evolving, can create early market leadership.
For Investors and Strategic Acquirers:Distressed-cycle entries favor agile software developers in the United States, offering long-term viability within regulated biopharmaceutical markets. The market's long-term viability is strong, driven by continuous regulatory mandates for data integrity. Investors should seek out specialized software providers with deep expertise in AI/ML integration or robust multi-vendor compatibility. A key signal to watch is the increasing alignment of global data integrity guidelines, such as China's NMPA with FDA 21 CFR Part 11.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhances interoperability across diverse laboratory instruments. |
| Geographic Expansion | Captures demand from emerging pharmaceutical markets in Asia. |
| Acquisition of Specialist Firm | Accelerates entry into niche application verticals like bioinformatics. |
| AI/ML Feature Development | Automates data processing and improves analytical accuracy for users. |
| Regulatory Compliance Certification | Reinforces trust and market access in highly regulated sectors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. Primary interviews involved R&D scientists, QA managers, IT procurement specialists, and regulatory affairs officers. Secondary data sources included FDA 21 CFR Part 11 guidance, EMA guidelines, NMPA announcements, and company annual reports. This approach facilitated bottom-up market sizing and top-down validation of segment forecasts.
Data-stream reconciliation across multiple sources informed the analytical framework used to project market trajectories. The quantitative model integrated segmentation dimensions including product type, deployment, application, end-user, and regional regulatory alignment. Compound annual growth rates were derived from historical trends, anticipated technological shifts, and evolving regulatory mandates. Key industry-specific inputs included biopharmaceutical R&D expenditure and enterprise cloud adoption rates over the projection horizon.
Caveats apply where unforeseen regulatory changes or major cybersecurity breaches could materially shift the outlook. Forecasts reflect assumptions regarding the current regulatory landscape and technological development pace. Unforeseen changes in data integrity mandates or significant economic downturns impacting R&D spending represent risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Gold Tester Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
China Material Testing Market
Testing Equipment
Viscometer Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Chromatography Accessories and Consumables Market