
 Medical Propellants Market | 2026-2036
Medical Propellants Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Propellants Market Insights
EU MDR conformity assessment and FDA 505(b)(2) qualification pathways is reorganizing supplier tiers for pharmaceutical-grade propellants. Honeywell International Inc. leverages its fluorochemical R&D infrastructure to sustain leadership in next-generation hydrofluoroalkane development. Arkema Group anchors European supply through backward integration into fluorine chemistry. The Chemours Company competes on manufacturing scale across multiple continents.
Medical propellants are compressed or liquefied gases—primarily hydrofluoroalkanes, carbon dioxide, nitrous oxide, and hydrocarbon blends—formulated to precise purity specifications exceeding 99.9% and packaged under cGMP conditions to deliver consistent particle size distribution in respiratory and injectable drug delivery systems. Hydrofluoroalkanes dominate value pools due to regulatory-mandated transitions away from chlorofluorocarbon and high-GWP alternatives, while compressed gases occupy mature, price-sensitive segments in emergency medicine and surgical anesthesia. Metered dose inhalers capture the fastest application growth as formulation science advances for complex biologic aerosolization, whereas nasal sprays and injection systems serve narrower therapeutic niches with specialized gas purity requirements.
FDA, EMA, and EPA frameworks collectively govern propellant purity, environmental fate, and drug-device combination approvals, with the EU F-Gas Regulation directly constraining hydrofluoroalkane availability and accelerating investment in low-GWP molecular designs. India's CDSCO and China's NMPA impose additional country-specific excipient monographs that fragment qualification requirements for multinational suppliers. Stakeholders must monitor regulatory divergence between environmental phase-down schedules and pharmaceutical safety mandates to avoid supply discontinuities during formulation transitions.
Market Dynamics
The EU F-Gas Regulation's phasedown of high-global-warming-potential hydrofluoroalkanes is compressing supply availability while simultaneously mandating pharmaceutical-grade purity standards, forcing metered dose inhaler manufacturers to dual-qualify alternative propellant chemistries under accelerated timelines.
Growth Catalysts
- EMA MDR conformity pathways:The EU Medical Device Regulation's combination product classification is requiring propellant suppliers to maintain drug-device dossiers, locking in qualified vendors and extending contract durations for compliant hydrofluoroalkane producers.
- Home healthcare channel expansion:Germany, France, and the United States are witnessing patient-administered respiratory therapy migration from hospital settings, expanding addressable volume for portable metered dose inhaler systems.
- Biologic aerosolization advances:Formulation science enabling complex protein delivery through pressurized systems is opening new therapeutic categories previously restricted to nebulized or injectable administration.
Market Restraints
- Fluorochemical feedstock concentration:Three integrated chemical conglomerates control upstream hexafluoropropylene supply, creating single-source vulnerability for hydrofluoroalkane-152a and -134a derivatives.
- CDSCO excipient monograph fragmentation:India's pharmaceutical regulator imposes country-specific purity thresholds that diverge from USP and EP standards, forcing redundant testing campaigns for multinational suppliers.
- Dry powder inhaler substitution:Breath-actuated powder systems eliminate propellant requirements entirely in asthma maintenance therapy, capturing share in price-sensitive chronic disease segments.
Strategic Opportunities
- Low-GWP molecular design investment:The EU F-Gas Regulation's quota allocation mechanism rewards early movers in hydrofluoroolefin and hydrofluoroether development with preferential market access permits.
- Emergency medicine gas expansion:Carbon dioxide and nitrous oxide systems for procedural sedation and resuscitation remain underpenetrated in India's tier-2 and tier-3 hospital networks.
- Japan's PMDA combination product stream:The Pharmaceuticals and Medical Devices Agency's consolidated review pathway for drug-device submissions reduces time-to-market for novel propellant-based delivery platforms.
Industry Challenges
- cGMP facility qualification timelines:Pharmaceutical-grade propellant manufacturing requires 18-24 month FDA pre-approval inspection cycles, constraining capacity expansion responsiveness to demand surges.
- Analytical method transfer complexity:Migrating from chlorofluorocarbon to hydrofluoroalkane formulations necessitates complete redevelopment of impurity profiling protocols, delaying generic substitution approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Propellants Market |
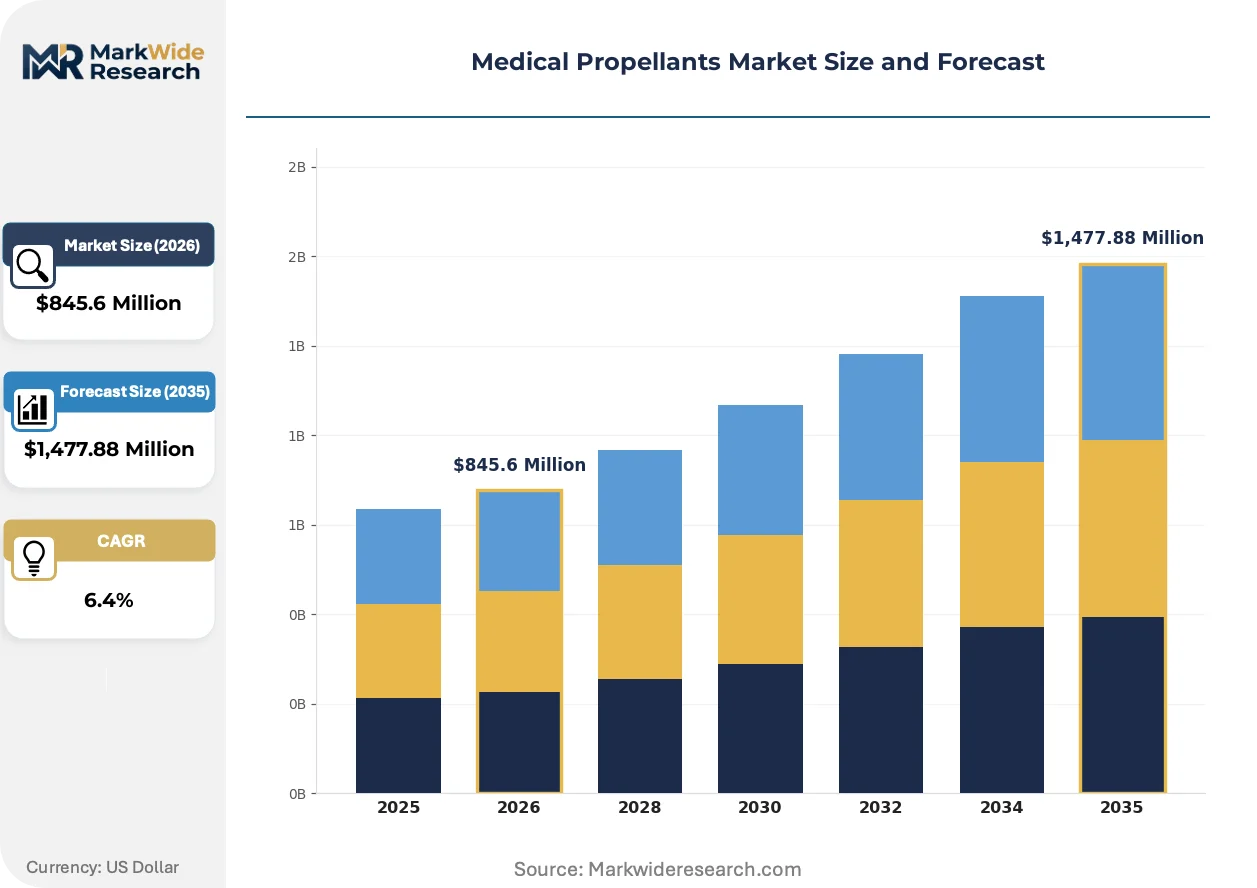
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,477.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrofluoroalkanes, Compressed Gases, Carbon Dioxide, Nitrous Oxide Application: Aerosol Inhalers, Metered Dose Inhalers, Nasal Sprays, Injection Systems End User: Hospitals, Clinics, Home Healthcare, Pharmacies Form: Liquid, Gas, Gel, Powder |
| Companies Covered | Honeywell International Inc., Arkema Group, The Chemours Company, Shell PLC, Nouryon, Aeropres Corporation, BOC Ltd., AkzoNobel NV, Koura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Propellants Market Trends and Innovations
Formulation and device engineering are converging to enable therapeutic categories previously excluded from pressurized delivery, while environmental regulations simultaneously constrain molecular design options and accelerate next-generation chemistry investment.
Next-generation hydrofluoroalkane blends with tailored vapor pressure profiles are fragmenting the traditional single-propellant paradigm for metered dose inhalers. Complex generic manufacturers in India and contract development organizations in Western Europe are adopting these customized formulations to achieve bioequivalence with reference listed drugs containing legacy propellants. This technological diversification is fragmenting supplier relationships as formulators seek co-development partnerships rather than commodity procurement.
REACH authorization requirements for perfluorinated substances are extending to pharmaceutical excipient classifications, compelling propellant manufacturers to submit full substance dossiers for hydrofluoroalkane-227ea and related chemistries. The European Chemicals Agency's scrutiny of persistent organic pollutant characteristics is forcing reformulation investments ahead of clinical necessity. Metered dose inhaler producers with EU manufacturing footprints are responding by accelerating qualification of alternative propellants in parallel portfolios.
Hospital procurement consortia are consolidating pharmaceutical gas purchasing across anesthesia, emergency medicine, and respiratory therapy categories, compressing vendor counts and demanding multi-product supply agreements. Group purchasing organizations in the United States and national tender bodies in France are unbundling propellant sourcing from finished device contracts. This behavioral shift is most visible in Western European markets where hospital network consolidation has created regional monopsony conditions for medical gas suppliers.
Medical Propellants Market Segmentation
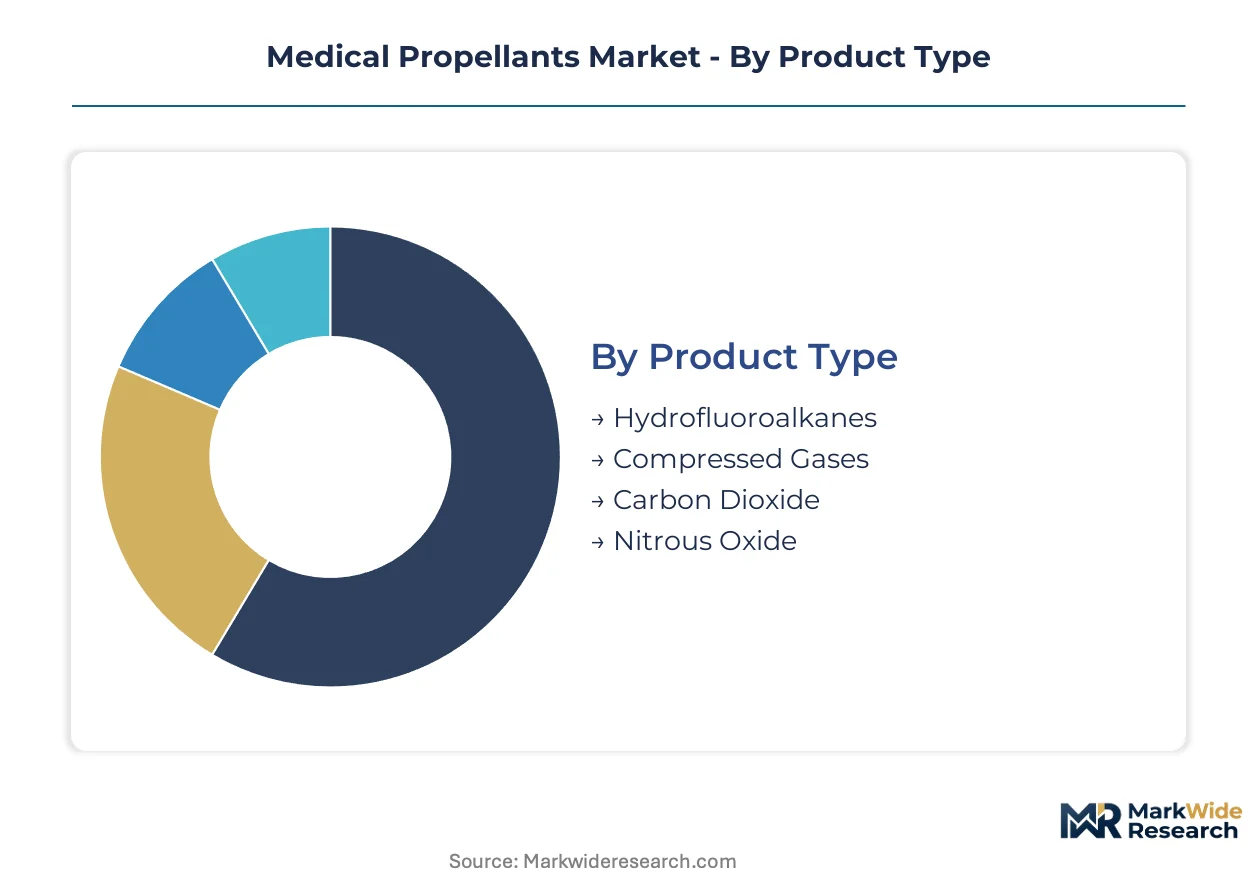
Propellant segmentation dictates procurement strategy, regulatory pathway complexity, and margin capture across respiratory and emergency medicine applications. Formulation scientists and supply chain managers prioritize product type purity grades and application-specific particle size requirements when qualifying vendors.
Product Type:
Margin pools concentrate in hydrofluoroalkane formulations where regulatory-mandated transitions from high-GWP alternatives sustain premium pricing power.
- Hydrofluoroalkanes:Liquefied gas propellants formulated to pharmaceutical-grade specifications exceeding 99.9% purity, with HFA-134a and HFA-227ea dominating metered dose inhaler applications. Demand concentrates in Germany, France, and India where EU F-Gas Regulation phase-downs and CDSCO excipient tightening compress supply availability.
- Compressed Gases:High-pressure stored gases including medical-grade air and oxygen blends for emergency resuscitation and surgical support. Hospital procurement consortia in the United States and France are consolidating purchasing across anesthesia and respiratory categories, squeezing vendor margins.
- Carbon Dioxide:Critical gas for procedural sedation and laparoscopic insufflation with established USP monographs.
- Nitrous Oxide:Analgesic and anesthetic gas with specialized purity requirements for dental and obstetric applications.
The dominant share belongs to hydrofluoroalkanes, while compressed gases are closing the gap fastest through hospital purchasing consolidation.
Application:
Volume concentration tracks respiratory disease prevalence and the shift toward patient-administered therapy in outpatient settings.
- Metered Dose Inhalers:Pressurized systems delivering precise medication doses through breath-actuated or hand-breath coordination mechanisms. Formulation advances enabling complex biologic aerosolization are expanding therapeutic categories in the United States and Western Europe.
- Aerosol Inhalers:Nebulizer-compatible and propellant-driven systems for bronchodilator and corticosteroid delivery. India's tier-2 hospital networks and Germany's home healthcare channels are driving procurement volume as chronic obstructive pulmonary disease management shifts outside acute settings.
- Nasal Sprays:Topical and systemic delivery systems requiring specialized particle size distribution control.
- Injection Systems:Propellant-powered needle-free and auto-injector platforms for emergency medication administration.
Metered dose inhalers command the largest volume position, though aerosol inhalers are expanding most quickly through emerging market hospital procurement.
End User:
Customer-type economics diverge sharply between consolidated institutional purchasers and fragmented retail channels.
- Hospitals:Integrated delivery networks and national health systems with formal tender processes and multi-year supply agreements. Group purchasing organizations in the United States and regional hospital consortia in France are unbundling propellant sourcing from finished device contracts.
- Home Healthcare:Patient-administered therapy settings requiring portable, user-friendly delivery systems. Germany's statutory health insurance reimbursement framework and France's chronic disease management programs are accelerating channel migration from acute care.
- Clinics:Outpatient facilities with intermediate volume requirements and less formalized procurement.
- Pharmacies:Retail dispensing points with high transaction frequency and price-sensitive generic substitution.
Hospitals retain the dominant procurement volume, while home healthcare is gaining share fastest through reimbursement-driven channel shift.
Form:
Physical state determines packaging, stability, and delivery mechanism compatibility across therapeutic applications.
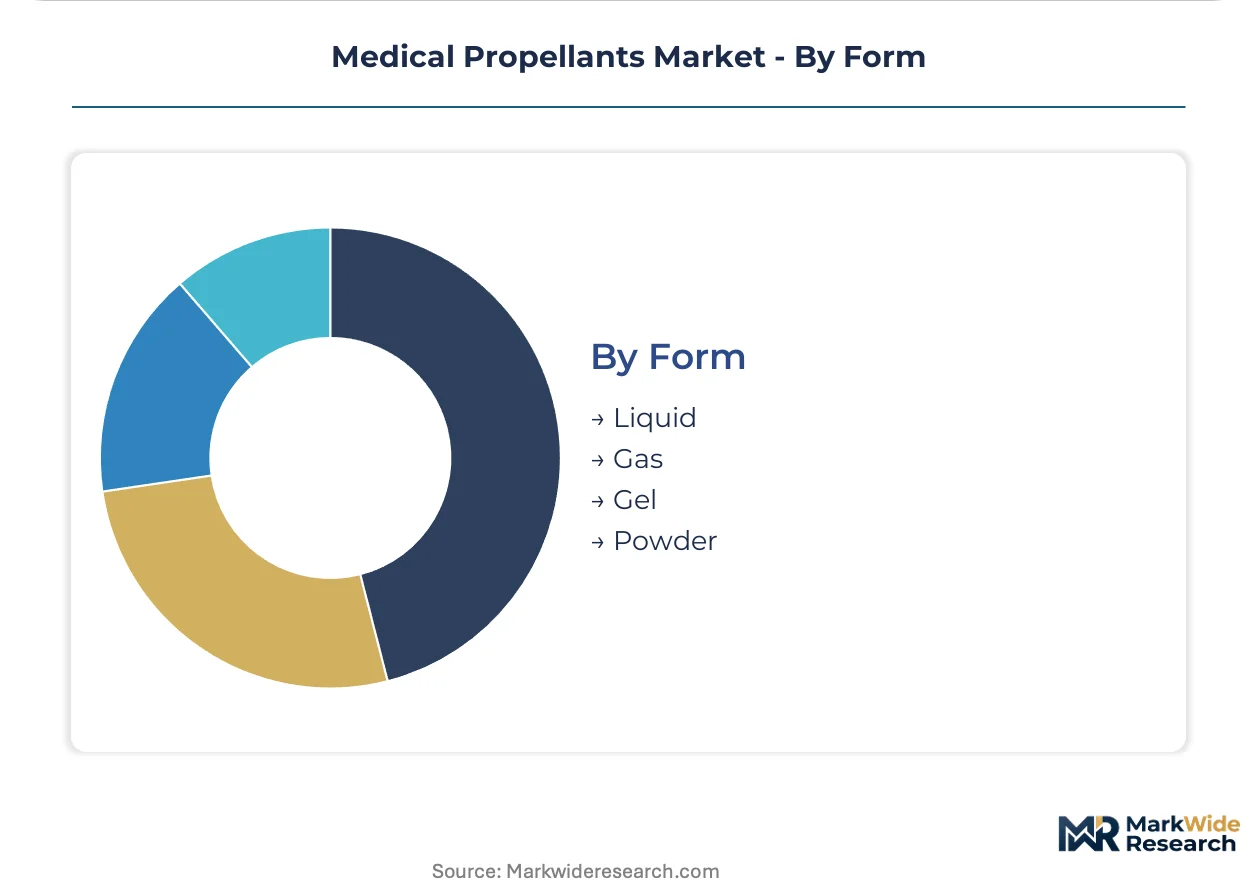
- Liquid:Liquefied gas propellants under pressure enabling consistent vapor pressure and particle size distribution in metered dose systems. Hydrofluoroalkane-134a and -227ea in liquid phase dominate respiratory drug delivery in the United States and European markets.
- Gas:Compressed and cryogenic forms for emergency medicine and surgical anesthesia with established supply infrastructure. Carbon dioxide and nitrous oxide in gaseous state serve procedural sedation in India's expanding hospital network.
- Gel:Thickened propellant formulations for specialized topical and mucosal adhesion applications.
- Powder:Dry propellant carriers and excipient blends for hybrid delivery systems.
Liquid formulations hold the dominant position, while gas forms are climbing the fastest through emergency medicine expansion in underpenetrated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's role in fluorochemical distribution, while the Houston Ship Channel anchors North American feedstock flows for pharmaceutical-grade propellant manufacturing.
United States
The FDA's 505(b)(2) qualification pathways and EPA environmental fate assessments govern hydrofluoroalkane approvals for metered dose inhaler manufacturers. Home healthcare channel expansion in California and Texas accelerates patient-administered respiratory therapy migration from hospital settings. The Houston-Galveston petrochemical corridor concentrates cGMP propellant finishing capacity serving domestic inhaler device producers.
Germany
EMA MDR conformity assessment for combination products locks in qualified propellant vendors under extended contract structures. The EU F-Gas Regulation's phasedown quota system compresses HFA-134a availability for pharmaceutical applications. The Frankfurt-Rhine-Main industrial cluster hosts backward-integrated fluorochemical operations supplying metered dose inhaler formulators across Western Europe.
France
ANSM national health authority oversight intersects with ECHA REACH authorization requirements for perfluorinated pharmaceutical excipients. Hospital procurement consortia in the Île-de-France region unbundle propellant sourcing from finished device contracts. The Lyon-Grenoble chemical corridor concentrates aerosol formulation R&D serving chronic obstructive pulmonary disease management programs.
India
CDSCO excipient monograph tightening imposes country-specific purity thresholds diverging from USP and EP standards. Tier-2 hospital network expansion in Maharashtra and Gujarat drives carbon dioxide and nitrous oxide procurement for procedural sedation. The Mumbai-Pune pharmaceutical belt hosts generic metered dose inhaler manufacturers qualifying alternative propellant chemistries under accelerated timelines.
Japan
PMDA combination product stream consolidation reduces regulatory review duration for novel propellant-based delivery platforms. METI industrial policy supports low-GWP molecular design investment in hydrofluoroolefin development. The Kansai industrial corridor around Osaka anchors pharmaceutical gas packaging operations serving domestic and Asia-Pacific respiratory device markets.
Medical Propellants Market Competitive Landscape
Listed leaders compete with private specialists across cGMP certification tiers, with consolidated upstream fluorochemical supply creating asymmetric bargaining power for integrated conglomerates. Three archetypes dominate: backward-integrated chemical majors controlling hexafluoropropylene feedstock, pharmaceutical-grade gas specialists with FDA-inspected facilities, and regional compressed gas distributors serving hospital procurement consortia. Competitive moves concentrate on dual-qualification of alternative propellants under EU F-Gas Regulation timelines and capacity expansion through 18-24 month FDA pre-approval inspection cycles.
Among integrated chemical conglomerates, Honeywell International Inc. and Arkema Group occupy positions exemplifying fluorochemical R&D infrastructure leveraged for next-generation hydrofluoroalkane development. The Chemours Company sits within the scale-driven archetype, with manufacturing footprints spanning multiple continents. These three entities anchor supplier tier reorganization as EMA MDR conformity pathways and EPA frameworks collectively govern propellant purity and environmental fate standards.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Arkema Group |
| The Chemours Company |
| Shell PLC |
| Nouryon |
| Aeropres Corporation |
| BOC Ltd. |
| AkzoNobel NV |
| Koura |
| Others |
Pricing and Supply Chain Analysis
FDA cGMP certification and EU F-Gas Regulation quota systems simultaneously gate supplier qualification tiers and stratify price levels across pharmaceutical-grade propellant markets. These dual certification and environmental frameworks compress supply availability for compliant producers while enabling premium capture for early movers in low-GWP molecular designs.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade hydrofluoroalkane contracts from commodity industrial gas procurement, with cGMP certification status and EPA environmental fate compliance serving as the primary price differentiation drivers. Hospital procurement consortia in the United States and France extract scaling discounts through multi-year offtake agreements, while generic inhaler manufacturers in India face cost compression from redundant CDSCO purity testing requirements. Price erosion runs through compressed gas segments where breath-actuated dry powder inhalers eliminate propellant requirements entirely.
Supply Chain Analysis
Germany and the United States anchor pharmaceutical-grade hydrofluoroalkane finishing capacity, with the Frankfurt-Rhine-Main and Houston-Galveston corridors hosting cGMP facilities serving metered dose inhaler manufacturers. Upstream hexafluoropropylene feedstock draws from concentrated fluorochemical operations in China and the United States, creating single-source vulnerability for HFA-152a and HFA-134a derivatives. Distribution runs through regional gas packaging hubs qualified under FDA and EMA inspection cycles, with 18-24 month pre-approval timelines constraining capacity responsiveness.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cGMP manufacturing slots for pharmaceutical-grade propellants remain structurally scarce relative to formulation demand from expanding metered dose inhaler portfolios, with environmental regulatory transitions compounding capacity tightness.
For Market Incumbents: Fortify upstream fluorochemical feedstock positions through captive hexafluoropropylene supply or long-term tolling arrangements, while accelerating dual-qualification of hydrofluoroolefin alternatives ahead of EU F-Gas Regulation quota compression. Lock in extended contract structures with hospital procurement consortia before group purchasing organizations complete vendor consolidation. For New Entrants and Emerging Players: Anchor in India's tier-2 hospital network expansion for carbon dioxide and nitrous oxide emergency medicine applications, where CDSCO regulatory divergence has slowed multinational qualification timelines. Pursue partnership-based market entry with domestic generic inhaler manufacturers seeking alternative propellant co-development rather than commodity supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across low-GWP molecular design sub-segments as EU quota allocation mechanisms reward early movers with preferential market access permits. Target acquisition profiles center on FDA-inspected pharmaceutical gas specialists with existing propellant dossiers and EMA MDR combination product experience. The signal to watch is accelerated dry powder inhaler substitution rates in asthma maintenance therapy segments.| Strategic Initiative | Industry Significance |
|---|---|
| Low-GWP Molecular Design Investment | EU F-Gas Regulation quota systems reward early hydrofluoroolefin developers with preferential pharmaceutical market access permits. |
| Backward Integration into Fluorochemical Feedstock | Captive hexafluoropropylene supply secures HFA-152a and HFA-134a derivative availability against upstream concentration risk. |
| cGMP Facility Expansion | FDA pre-approval inspection cycles extending 18-24 months constrain responsive capacity addition for demand surges. |
| Dual-Qualification of Alternative Propellants | Parallel portfolio development mitigates supply discontinuity risk during EU phasedown of high-GWP hydrofluoroalkane formulations. |
| Hospital Procurement Consortium Partnership | Group purchasing organization vendor consolidation in the United States and France compresses supplier counts and extends contract durations. |
Research Methodology
Initial hypotheses were tested against primary input from metered dose inhaler formulation scientists, pharmaceutical procurement managers at hospital systems, fluorochemical plant operations directors, and regulatory affairs specialists at combination product manufacturers, then refined through secondary validation against FDA 505(b)(2) submission databases, EMA MDR conformity assessment records, EU F-Gas Regulation quota allocation filings, and CDSCO excipient monograph updates. Bottom-up propellant volume estimates from individual manufacturing facilities were triangulated against top-down respiratory therapy prescription data and inhaler device production figures.
Variance decomposition across the projection horizon isolates volume drivers by propellant chemistry grade, application delivery mechanism, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from segmented growth rate modeling incorporating patient population epidemiology, reimbursement framework shifts, and environmental regulation phase-down schedules. Industry-specific forecast inputs include dry powder inhaler substitution elasticity and biologic aerosolization formulation advancement timelines.
Material uncertainties — EU F-Gas Regulation quota reallocation, CDSCO excipient standard harmonization decisions, and breath-actuated device technology substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation pacing and pharmaceutical manufacturer qualification timelines. Recalibration cycles align with material shifts in environmental regulation enforcement and combination product approval pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Global Ceramide Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
Global Optical Brighteners Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Global Flash Chromatography Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Global Salicylic Acid Market
Specialty Chemicals
Petroleum Jelly Market