
 L-Ergothioneine Market | 2026-2036
L-Ergothioneine Market Size, Share, and Industry Trends Forecast 2026-2036
L-Ergothioneine Market Analytics
Direct-to-practitioner distribution is rewriting how L-ergothioneine reaches end consumers in the wellness sector. Kaneka Corporation leverages its fermentation expertise to anchor supply for pharmaceutical-grade material. Blue California competes through specialized extraction capabilities that sustain its position in nutraceutical channels. Evonik Industries AG differentiates via biotechnology platforms that extend its reach into clinical formulation partnerships.
L-ergothioneine is a sulfur-containing amino acid derivative synthesized primarily by fungi and certain bacteria, characterized by its exceptional redox stability and selective accumulation in mitochondria and other tissues under oxidative stress. Industrial production employs microbial fermentation or chemical synthesis to yield powder and liquid forms for incorporation into capsules, tablets, and functional food matrices. Raw powder formulations currently dominate manufacturing throughput due to flexibility in downstream processing for multiple end-use categories. The nutraceuticals segment leads commercial volume as consumers prioritize cellular health applications, while cosmetics represents the fastest-growing outlet as topical antioxidant claims gain formulation traction. Dietary supplements occupy the largest margin pool within formulation types, though clinical formulations are expanding as therapeutic research advances.
The FDA oversees dietary supplement labeling and New Dietary Ingredient notifications for L-ergothioneine products entering the United States, while the EMA and EFSA frameworks govern novel food and health claim assessments across European markets. These regulatory structures shape demand by determining permissible health claims, safety documentation requirements, and market access timelines for new suppliers. Stakeholders must monitor evolving GRAS self-affirmation pathways and accumulating clinical trial data that could unlock broader therapeutic positioning.
Market Dynamics
Biosynthesis advances using engineered yeast strains are compressing production costs and expanding supply availability, fundamentally restructuring how L-ergothioneine reaches nutraceutical and cosmetic formulators.
Growth Catalysts
- Engineered Fermentation:Microbial biosynthesis platforms are lowering unit economics for pharmaceutical-grade material, enabling broader incorporation into mitochondrial health supplements.
- FDA GRAS Pathways:Self-affirmation mechanisms for novel dietary ingredients are accelerating market access timelines for L-ergothioneine suppliers targeting United States nutraceutical channels.
- Cosmetic Antioxidant Demand:Topical formulation claims around cellular protection are driving procurement from prestige skincare manufacturers seeking differentiated active ingredients.
Market Restraints
- Fermentation Input Costs:Specialized nitrogen sources and sulfur-containing precursors exhibit price volatility that compresses margins for biosynthesis operators.
- Supplier Concentration:A limited number of fermentation specialists control pharmaceutical-grade capacity, creating bottlenecks for new entrants seeking clinical-grade certification.
- Chemical Synthesis Competition:Synthetic routes from petrochemical feedstocks offer lower purity alternatives that constrain pricing power for biologically derived material.
Strategic Opportunities
- Clinical Therapeutic Positioning:Accumulating mitochondrial protection research could unlock prescription-grade applications beyond current nutraceutical boundaries.
- Direct-to-Practitioner Channels:Functional medicine networks represent underpenetrated distribution infrastructure for practitioner-dispensed longevity formulations.
- EFSA Novel Food Authorization:Successful health claim substantiation under European frameworks would open food fortification applications currently restricted to supplements.
Industry Challenges
- Fermentation Scale-Up Expertise:Shortages of process engineers with commercial microbial production experience delay capacity expansion timelines for emerging suppliers.
- Analytical Method Harmonization:Inconsistent purity standards between ISO reference materials and proprietary in-house assays complicate cross-supplier quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L-Ergothioneine Market |
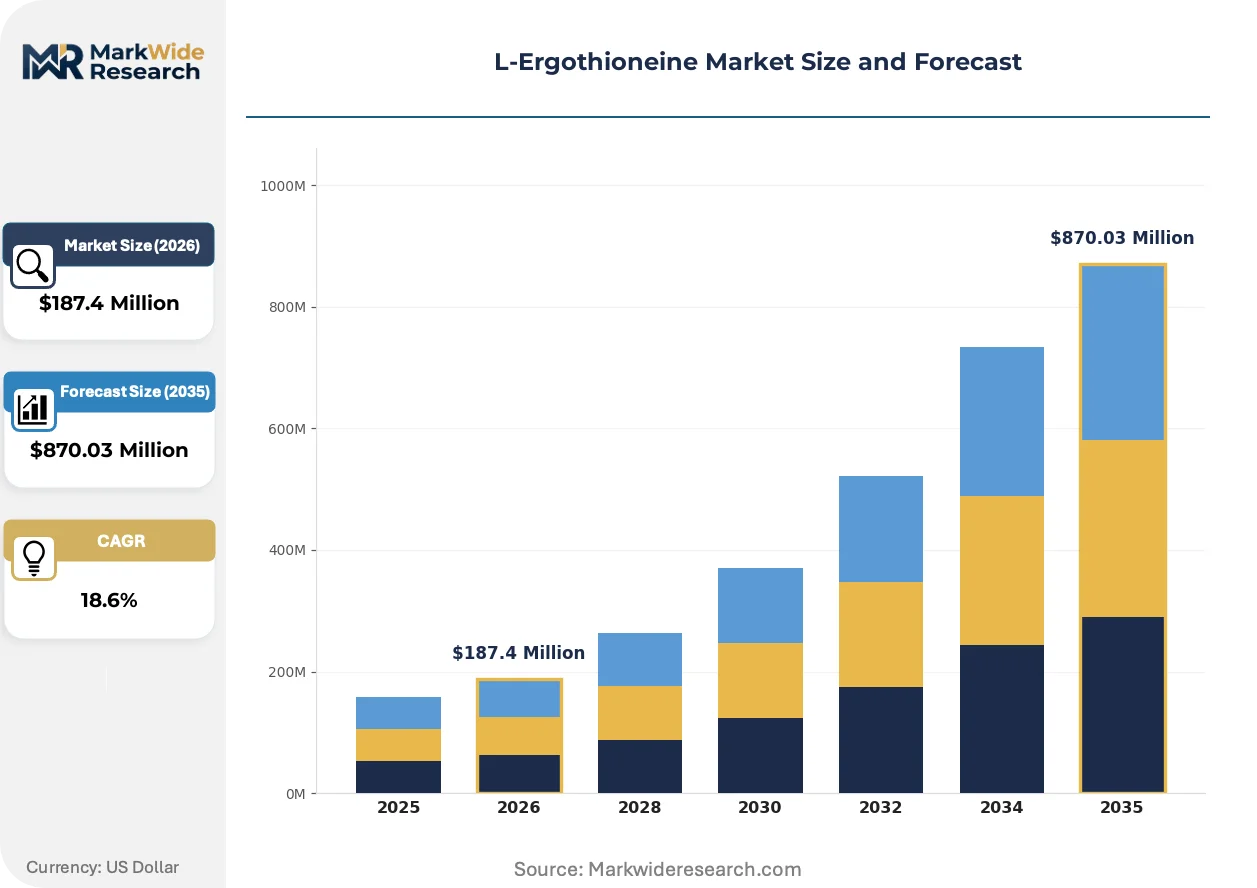
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Powder, Capsules, Tablets, Liquids End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Food Supplements Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Formulation Type: Functional Foods, Dietary Supplements, Clinical Formulations, Personal Care |
| Companies Covered | Mironova Labs, Tetrahedron, Blue California, Kaneka Corporation, Lonza Group AG, AIDP Inc., AnaSpec Inc., Evonik Industries AG, ChromaDex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L-Ergothioneine Market Evolving Landscape
Digital integration across fermentation monitoring and supply chain traceability is compressing quality assurance cycles, while regulatory data accumulation is opening therapeutic positioning beyond antioxidant commodity status.
Continuous bioprocessing technology is virtualizing traditional batch fermentation economics for L-ergothioneine production. Contract manufacturers serving nutraceutical brands are adopting perfusion systems at pilot scale. This virtualization enables real-time titer optimization that reduces downstream purification burden and capital intensity per kilogram output.
REACH registration requirements for novel cosmetic actives are tightening substance documentation obligations across European supply chains. ECHA dossier preparation costs are filtering smaller extraction-based suppliers from topical ingredient markets. Cosmetic formulators are consolidating procurement relationships with fermentation houses possessing existing REACH compliance infrastructure.
Practitioner education programs are displacing traditional retail marketing for cellular health ingredients. Functional medicine clinics in the United States are building direct sourcing relationships with ingredient suppliers, bypassing conventional distributor markups. This channel compression concentrates volume with suppliers capable of clinical trial data packages and medical affairs support.
L-Ergothioneine Market Segmentation
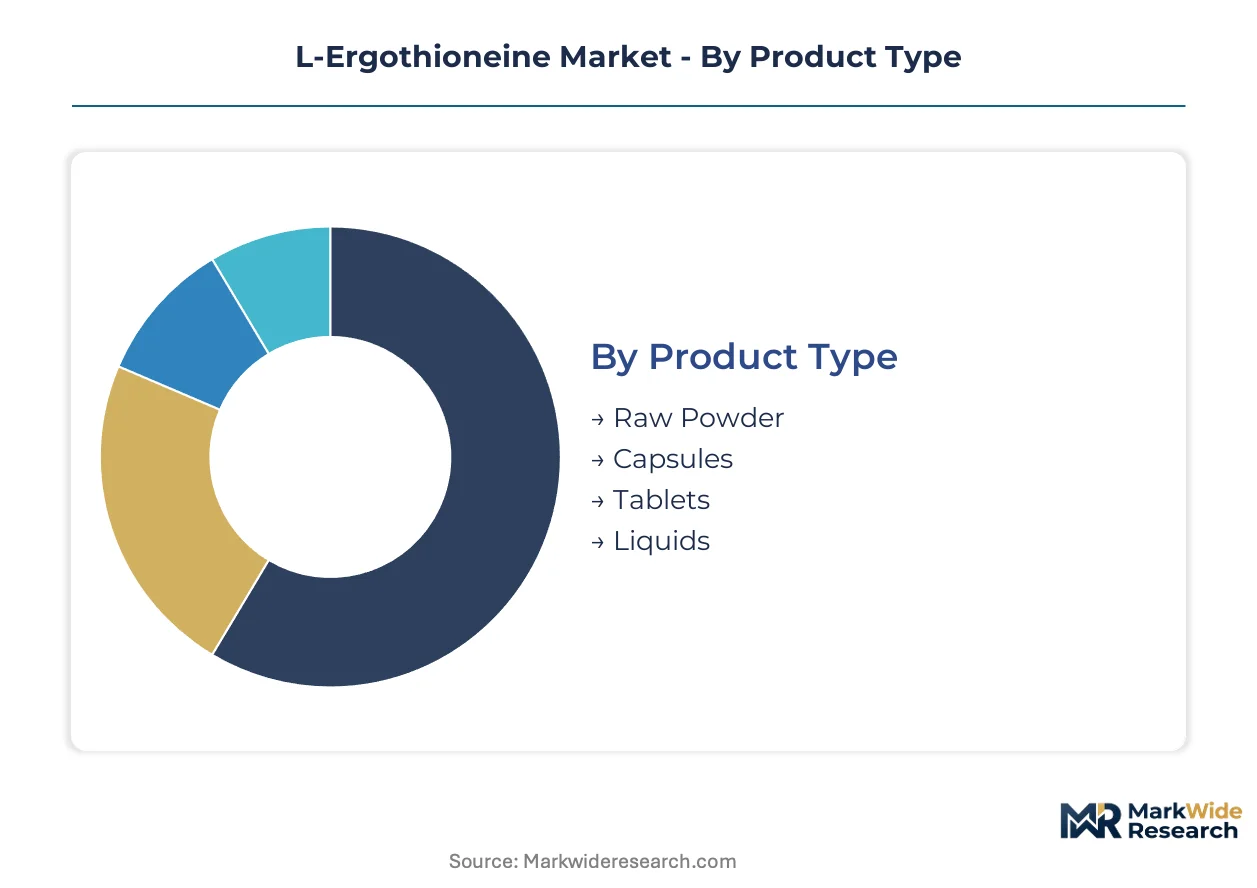
L-ergothioneine's commercial trajectory hinges on how form factors align with distinct buyer workflows and regulatory pathways. Segmentation reveals where production cycles compress and where margin pools concentrate across pharmaceutical, nutraceutical, and cosmetic applications.
Product Type:
Raw powder commands the longest production cycles but delivers maximum downstream flexibility, while finished formats compress time-to-shelf with stricter stability requirements.
- Raw Powder:Unformulated crystalline material with standardized purity grades serves as the foundational input for encapsulation, tableting, and liquid suspension. Nutraceutical contract manufacturers in the United States prioritize this format for mitochondrial health supplement lines, though powder handling protocols extend quality assurance timelines.
- Capsules:Gelatin or vegetable-derived shells containing measured ergothioneine doses target direct-to-consumer longevity brands. Demand concentrates among functional medicine practitioners dispensing personalized cellular health protocols, where capsule count flexibility supports variable dosing regimens.
- Tablets:Compressed formulations with binders and disintegrants suit mass-market dietary supplement positioning. Convenience-driven procurement from retail pharmacy chains favors this stable, shelf-ready format.
- Liquids:Aqueous or oil-based suspensions enable pediatric and geriatric applications where swallowing solid doses presents compliance barriers. Beverage fortification trials in Japan leverage this format for functional drink integration.
Raw powder dominates installed base. Capsules are where expansion concentrates.
End User:
Margin structures diverge sharply between regulated pharmaceutical pathways and faster-moving cosmetic applications, with nutraceuticals occupying the intermediate terrain.
- Pharmaceuticals:Investigational drug applications and prescription-grade formulations require GMP-certified fermentation output with full analytical documentation. Clinical trial sponsors targeting mitochondrial disease indications drive stringent purity specifications.
- Nutraceuticals:Dietary supplement brands leverage GRAS self-affirmation to accelerate market entry for cellular health positioning. This segment absorbs the largest commercial volumes as longevity-focused consumers prioritize evidence-backed antioxidant intake.
- Cosmetics:Topical antioxidant claims in prestige skincare represent the steepest expansion trajectory. Korean and French formulators lead procurement for anti-aging serums citing mitochondrial protection mechanisms.
- Food Supplements:Fortified functional foods and beverages face novel food authorization hurdles in European markets, constraining near-term volume but promising mass-market penetration upon regulatory clearance.
Nutraceuticals anchor current revenue. Cosmetics is climbing the fastest.
Distribution Channel:
Channel selection determines margin retention and customer data access, with digital platforms compressing traditional retail economics.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture subscription-based longevity product buyers. Brands investing in educational content around cellular health mechanisms convert traffic at higher lifetime value metrics.
- Supermarkets:Mass-market placement for fortified beverages and functional foods depends on slotting fee negotiations and consumer packaged goods partnerships. This channel remains underdeveloped pending broader regulatory acceptance.
- Health Stores:Specialty retailers with trained staff support premium positioning for practitioner-grade formulations. United States chains with in-house naturopathic consultants drive higher per-basket ergothioneine sales.
- Pharmacies:Licensed dispensaries provide credibility infrastructure for clinical-grade products and emerging prescription pathways. European pharmacy networks increasingly stock cellular health supplements adjacent to traditional vitamin assortments.
Online retail dominates customer acquisition velocity. Health stores concentrate margin retention.
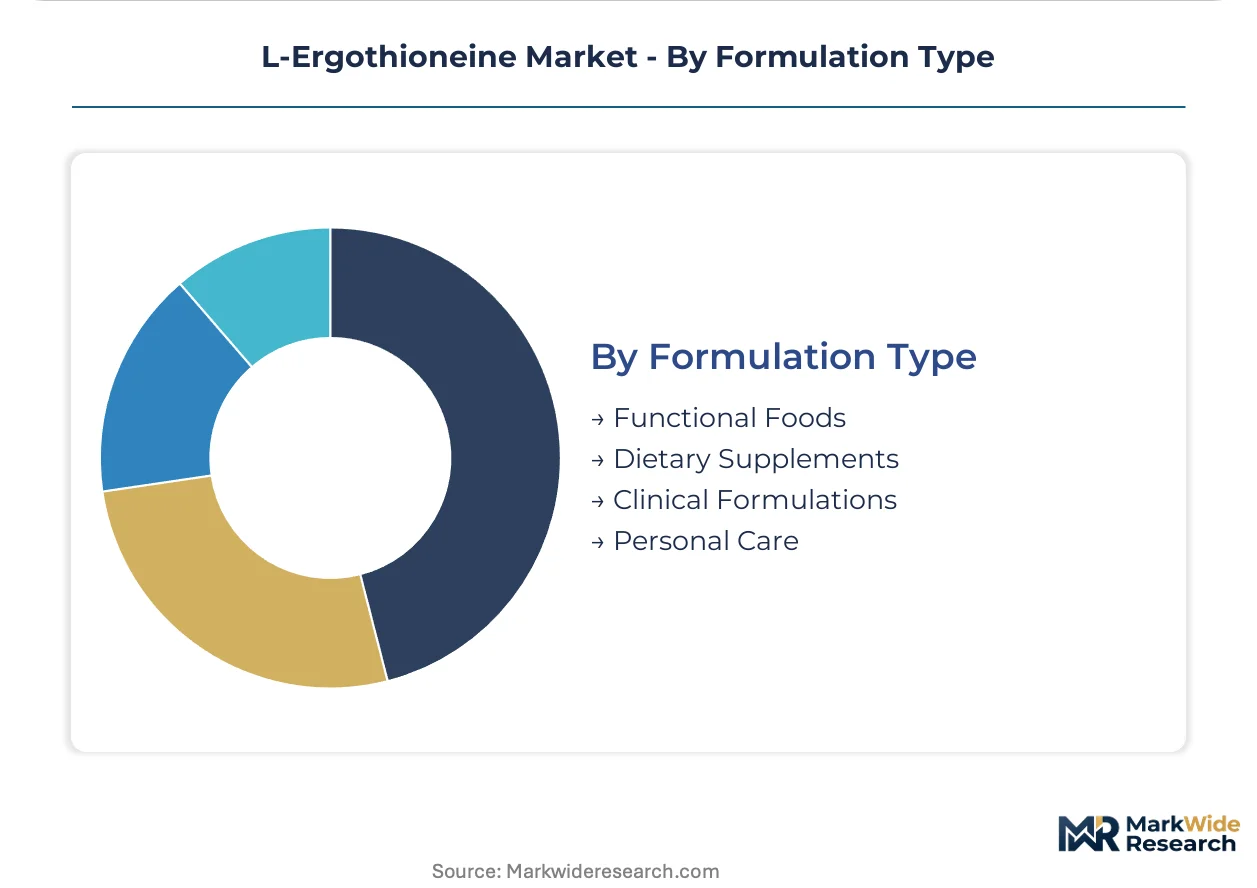
Formulation Type:
Regulatory classification boundaries shape where ergothioneine can be positioned, with food applications facing the steepest substantiation barriers.
- Functional Foods:Fortified matrices including beverages, bars, and dairy alternatives require novel food dossiers under EFSA frameworks. Successful authorization would unlock European grocery channel penetration currently restricted to supplement aisles.
- Dietary Supplements:Capsule, tablet, and powder formats with structure-function claims constitute the primary commercial outlet. FDA notification pathways enable faster United States market access compared to food fortification routes.
- Clinical Formulations:Prescription-grade development for mitochondrial disease, neurodegenerative conditions, and ophthalmology applications demands Phase II trial data. Pharmaceutical partnerships with fermentation specialists concentrate resources on this high-barrier pathway.
- Personal Care:Topical serums, creams, and masks leverage antioxidant stability claims without pharmaceutical regulatory burden. REACH-registered suppliers capture procurement from European cosmetic houses seeking compliant active sourcing.
Dietary supplements dominate installed base. Clinical formulations are where strategic investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical cargo terminals anchor European L-ergothioneine distribution, while the Port of Long Beach handles Pacific Rim fermentation inputs for North American nutraceutical manufacturers.
United States
FDA GRAS self-affirmation pathways accelerate dietary supplement market entry for fermentation-derived L-ergothioneine. Functional medicine clinics in California and New York Metro build direct sourcing relationships with suppliers, bypassing traditional distributor markups. Boston's biotech corridor hosts clinical trial sponsors investigating mitochondrial disease applications.
Japan
PMDA novel food consultations and METI functional food labeling frameworks shape commercialization timelines for beverage fortification trials. Osaka-based formulators lead procurement for anti-aging topical applications. The Kansai region's fermentation heritage supports engineered yeast strain development for pharmaceutical-grade output.
Germany
EMA pharmaceutical-grade GMP certification requirements and EFSA novel food dossier standards govern dual-track market access. Bavaria's biotech clusters concentrate perfusion fermentation R&D for continuous bioprocessing scale-up. Frankfurt's chemical logistics hub manages REACH-registered cosmetic active distribution across European formulators.
Switzerland
Swissmedic's stringent purity documentation requirements filter non-compliant suppliers from clinical-grade procurement channels. Basel's pharmaceutical corridor anchors prescription-grade development partnerships. Zurich's nutraceutical headquarters operations coordinate practitioner-dispensed longevity formulation distribution.
South Korea
MFDS health functional food codes and K-beauty export regulations drive dual-use fermentation capacity investment. Seoul Capital Area cosmetic houses lead prestige skincare antioxidant procurement. Busan-Ulsan's chemical processing infrastructure supports downstream purification for pharmaceutical-grade material.
L-Ergothioneine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between fermentation houses with GMP-certified pharmaceutical capacity and extraction-based suppliers serving cosmetic channels. Three archetypes dominate: integrated biotech platforms, specialized fermentation contractors, and regional extraction specialists. Capacity expansion and clinical trial data partnerships constitute the dominant competitive moves as suppliers seek prescription-grade positioning.
Within the integrated biotech tier, Kaneka Corporation and Evonik Industries AG exemplify platform-scale fermentation capability, while Blue California occupies a position among specialized extraction-focused suppliers. These three entities represent distinct strategic postures: Japanese and German biotech platforms versus California-based botanical extraction heritage. Their collective presence underscores how geographic clustering around regulatory expertise and fermentation infrastructure shapes competitive access to clinical and nutraceutical channels.
| Leading Market Players |
|---|
| Mironova Labs |
| Tetrahedron |
| Blue California |
| Kaneka Corporation |
| Lonza Group AG |
| AIDP Inc. |
| AnaSpec Inc. |
| Evonik Industries AG |
| ChromaDex Corporation |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's chemical cargo terminals anchor European inbound logistics costs, compressing margin pools for fermentation-derived L-ergothioneine as specialized nitrogen sources and sulfur-containing precursors exhibit price volatility that feeds downstream into three-tier pricing stratification across pharmaceutical-grade, nutraceutical-grade, and cosmetic-grade material.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade certifications from nutraceutical-grade GRAS-affirmed material from cosmetic-grade REACH-registered supply, with FDA GMP documentation and EMA purity assays commanding substantial premiums over standard dietary supplement grades. Price differentiation centers on analytical certification depth and geographic delivery costs, with United States functional medicine clinics showing lowest price sensitivity for practitioner-dispensed formulations while mass-market supplement brands drive cost compression in standard-grade procurement. Pricing pressure stems from chemical synthesis competition using petrochemical feedstocks, eroding biologically derived material pricing power in cosmetic applications.
Supply Chain Analysis
Tariff exposure between United States and Chinese fermentation equipment suppliers concentrates risk for emerging biosynthesis operators seeking commercial-scale capacity. Supply concentrates in Japan, Germany, and the United States for pharmaceutical-grade fermentation, with South Korea and France anchoring cosmetic-grade extraction and formulation. Raw material dependencies include engineered yeast strains, sulfur-containing precursors, and specialized nitrogen sources. Distribution runs through direct-to-practitioner channels for clinical-grade material and nutraceutical contract manufacturers for supplement-grade supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
L-ergothioneine supply fragmentation creates niche entry points as direct-to-practitioner channel compression displaces traditional distributor economics, opening margin capture for specialized fermentation houses and regional extraction operators.
For Market Incumbents: Harden analytical certification moats by deepening GMP documentation for pharmaceutical-grade output and securing exclusive practitioner-dispensed distribution partnerships. Incumbents must anchor supply agreements with functional medicine clinic networks before emerging fermentation specialists achieve clinical trial data parity. Capacity addition in Bavaria's biotech clusters and Osaka's Kansai fermentation corridor reinforces geographic supply control against new entrants.
For New Entrants and Emerging Players: Build out white-space positioning in food fortification applications pending EFSA novel food authorization, and in direct-to-practitioner channels where incumbent medical affairs support remains underdeveloped. The most penetrable segment is practitioner-dispensed longevity formulations in United States functional medicine clinics, where educational content partnerships around mitochondrial health mechanisms enable differentiated go-to-market positioning without competing on pharmaceutical-grade certification.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fermentation assets and incomplete downstream purification capabilities. Long-term viability over the next decade hinges on clinical therapeutic positioning beyond nutraceutical commodity status, with prescription-grade mitochondrial disease applications representing the highest-margin outcome. The signal to watch is Phase II trial initiation for neurodegenerative or ophthalmology indications, which would validate pharmaceutical-grade pricing premiums and unlock acquisition premiums for fermentation specialists with existing GMP infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II mitochondrial disease studies validate prescription-grade pricing and therapeutic positioning beyond supplements. |
| Regulatory Approval Pathway | EFSA novel food authorization unlocks European food fortification applications currently restricted to supplement channels. |
| Manufacturing Scale-Up | Continuous bioprocessing adoption at pilot scale reduces capital intensity per kilogram for emerging fermentation operators. |
| Backward Integration | In-house production of engineered yeast strains insulates against specialized precursor price volatility and supply disruption. |
| Strategic Partnership | Direct sourcing relationships with functional medicine clinics bypass distributor markups and concentrate volume with compliant suppliers. |
Research Methodology
Desk research of FDA GRAS notifications, EMA pharmaceutical-grade certification databases, and EFSA novel food dossiers preceded structured interviews with fermentation process engineers, nutraceutical contract manufacturing executives, functional medicine clinic procurement directors, and cosmetic formulator R&D leads. Secondary validation drew from customs trade data for L-ergothioneine precursor imports, SEC filings of publicly traded fermentation specialists, and REACH registration dossiers for cosmetic-grade material. Bottom-up volume estimates from individual production facilities triangulated against top-down demand projections from end-use segment analysis.
Assumptions held constant across the modeling period include regulatory pathway timelines for novel food and health claim authorizations, while fermentation yield improvements and continuous bioprocessing adoption rates were varied in sensitivity scenarios. Segmentation dimensions modeled encompass product type, end user category, distribution channel, and formulation regulatory classification, with regional production hub clustering as an additional industry-specific dimension. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansion announcements and practitioner channel penetration metrics.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by integrated biotech platforms or accelerated clinical trial advancement by pharmaceutical partners would shift volume and pricing outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Isophytol Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
Bio-Ketones Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Releasing Agents Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Epoxidized Soybean Oil Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Diindolylmethane Market