
 Global Baking Soda Substitute Market | 2026-2036
Global Baking Soda Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baking Soda Substitute Market Foresight
Buyer concentration in commercial bakeries and industrial food processors is recalibrating procurement patterns across the supply base. Lesaffre et Cie SA leverages its yeast and fermentation expertise to anchor positions in ammonium bicarbonate for large-scale baking operations. Associated British Foods PLC sustains competitive footing through specialized distribution networks serving European retail and foodservice channels. Corbion N.V differentiates via biotechnology-driven production of potassium bicarbonate with consistent purity grades for sodium-sensitive formulations.
A baking soda substitute comprises chemically distinct alkaline compounds—potassium bicarbonate, ammonium bicarbonate, calcium carbonate, magnesium carbonate, or sodium carbonate—engineered to replicate or exceed the leavening, pH modulation, or gas-release functionality of sodium bicarbonate in food, pharmaceutical, and industrial applications. These substitutes typically exhibit varying decomposition temperatures, neutralization capacities, and residual salt profiles that determine suitability across temperature-sensitive baking processes, effervescent tablet manufacturing, and controlled-release agricultural formulations. Potassium bicarbonate commands the premium tier within product type segmentation due to its direct sodium replacement credentials in cardiac and renal dietary products, while calcium carbonate occupies volume leadership in cleaning and agricultural applications where cost efficiency outweighs reactivity specifications. Ammonium bicarbonate retains dominance in cracker and flat-bread manufacturing across European and Asian industrial bakeries, though its narrow thermal decomposition window limits expansion into artisanal and home-use segments.
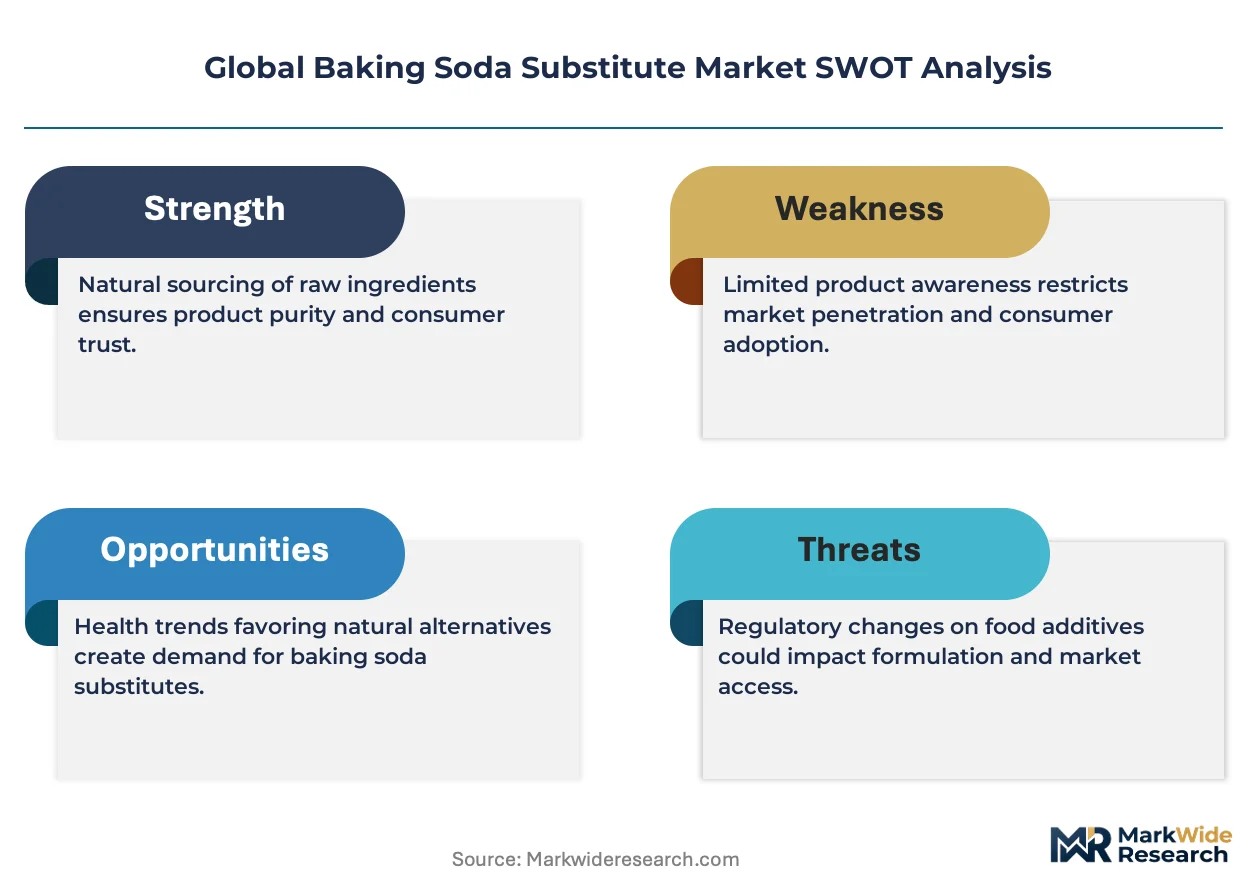
The FDA's sodium reduction guidelines and EFSA's evolving food additive re-evaluation frameworks are tightening compositional disclosure requirements for leavening agents in processed foods. REACH compliance in the European Union and GB standards enforcement through China's SAMR are elevating purity and traceability thresholds for carbonate and bicarbonate imports used in pharmaceutical and personal care end user industries. Stakeholders must monitor regulatory divergence between sodium-focused health mandates and clean-label certification schemes to align R&D pipelines with jurisdiction-specific formulation allowances.
Market Dynamics
Sodium reduction mandates from the FDA and EFSA are forcing wholesale reformulation across processed food manufacturing, redirecting procurement toward potassium bicarbonate and ammonium carbonate alternatives that maintain leavening performance without sodium content.
Growth Catalysts
- EFSA Additive Re-evaluation:The European Food Safety Authority's systematic review of sodium-based additives accelerates industrial migration toward potassium bicarbonate in cardiac-sensitive product lines across German and French bakeries.
- Home Baking Resurgence:Post-pandemic retention of home baking habits in the United States and Japan sustains retail demand for clean-label leavening alternatives with simplified ingredient declarations.
- Controlled-Release Agriculture:Magnesium carbonate formulations for precision nutrient delivery in greenhouse cultivation expand the addressable market beyond traditional food applications into specialty crop production.
Market Restraints
- Potassium Supply Concentration:Global potassium carbonate production clusters in Belarus and Russia, exposing downstream formulators to geopolitical supply interruptions and sanctions-driven price volatility.
- Narrow Thermal Windows:Ammonium bicarbonate's decomposition range of 36-60°C restricts deployment in artisanal baking environments lacking precise temperature control, excluding small-scale producers.
- REACH Compliance Burden:European Union registration requirements for new carbonate entrants impose documentation costs exceeding €100,000 per substance, deterring specialty chemical innovators from market entry.
Strategic Opportunities
- Indian Processed Food Expansion:FSSAI implementation of sodium caps in packaged snacks creates immediate demand for ammonium bicarbonate in cracker manufacturing across Maharashtra and Gujarat industrial corridors.
- Effervescent Pharmaceuticals:Potassium bicarbonate integration into antacid and supplement formulations leverages its dual functionality as pH buffer and sodium-free effervescent base in Japan's aging population market.
- Direct-to-Consumer Channels:E-commerce platforms enable specialty chemical distributors to bypass traditional food ingredient wholesalers, capturing margin from home bakers seeking pharmaceutical-grade alternatives.
Industry Challenges
- Formulation Chemistry Expertise:Industrial bakeries lack in-house technical capacity to recalculate acid-base ratios when substituting sodium bicarbonate, creating dependency on external technical service support.
- Cross-Contamination Controls:Facilities producing both sodium-containing and sodium-free lines must implement segregated processing equipment and validated cleaning protocols to prevent trace contamination in cardiac-designated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baking Soda Substitute Market |
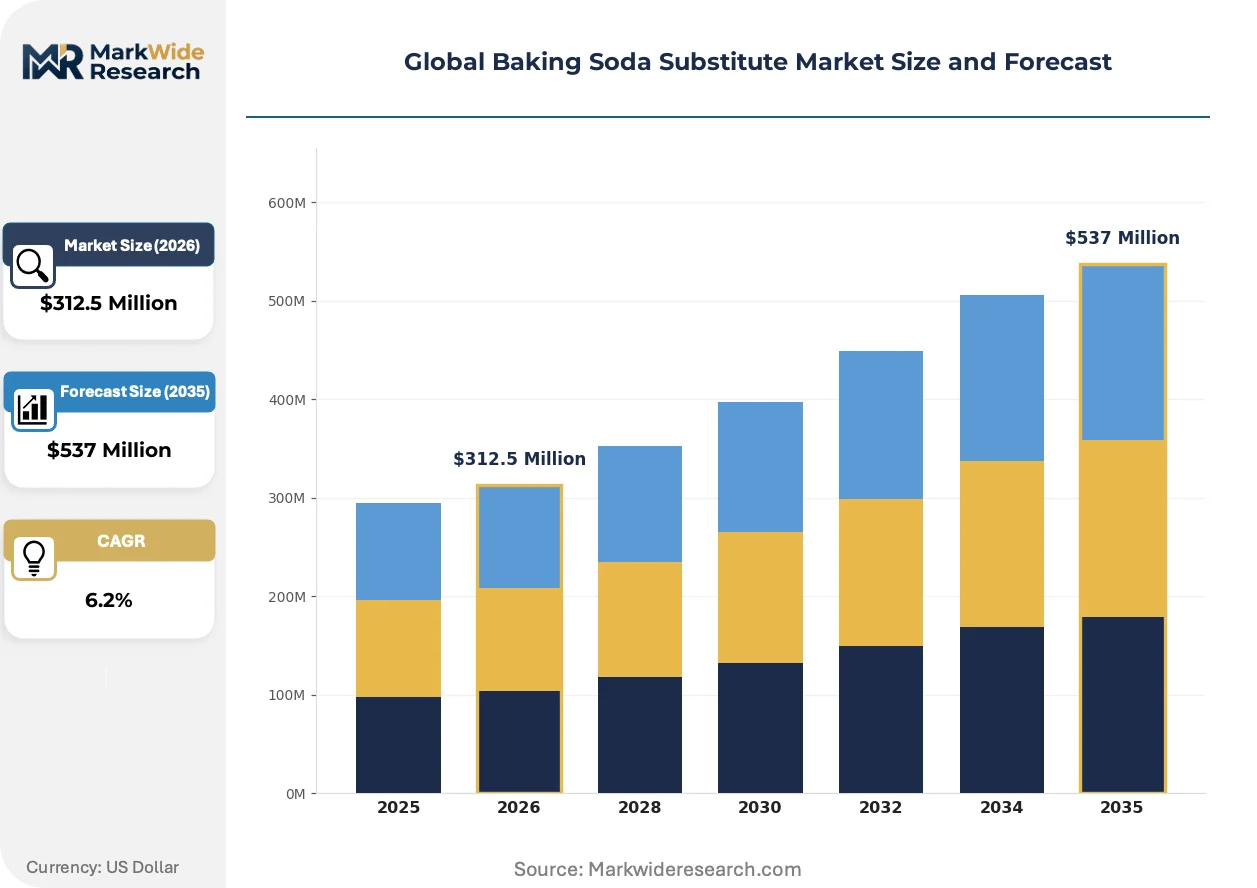
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $537 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Bicarbonate, Ammonium Bicarbonate, Sodium Carbonate, Calcium Carbonate, Magnesium Carbonate Application: Leavening Agent, Cleaning Agent, Deodorizer, Fire Extinguishing, pH Regulator End User Industry: Food Processing, Pharmaceuticals, Personal Care, Agriculture, Chemical Manufacturing Packaging Type: Box, Bag, Drum, Bulk Container, Pouch |
| Companies Covered | Lesaffre et Cie SA, Associated British Foods PLC, Bob's Red Mill Natural Foods, Archer Daniels Midland Co, Cargill, Inc, Corbion N.V, Lallemand Inc., Clabber Girl Corporation, Kothari Fermentation And Biochem Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baking Soda Substitute Market Shifts & Advancements
Biotechnology-enabled production methods and precision fermentation are compressing cost differentials between synthetic and bio-based carbonate sources, while regulatory disclosure requirements reshape competitive positioning around traceability credentials.
Encapsulation technology for controlled-release potassium bicarbonate is integrating into high-moisture batter systems where premature gas evolution degrades product texture. Industrial muffin and cake manufacturers in the United States adopt microencapsulated grades at accelerating rates. This technology is integrating moisture-activated leavening into extended-shelf-life retail products previously incompatible with conventional substitutes.
REACH authorization timelines for legacy carbonate additives are compressing formulation windows for European food processors. The European Chemicals Agency's 2024 substance evaluation roadmap prioritizes ammonium compounds for restriction assessment. German industrial bakeries are accelerating qualification of calcium carbonate blends as contingency formulations ahead of potential regulatory action.
Consolidation among North American commercial bakeries is concentrating purchasing power and standardizing ingredient specifications across multi-plant networks. Large-scale processors now mandate dual-source qualification for all leavening inputs, forcing smaller carbonate suppliers to achieve volume scale or exit the category. This concentration is most visible in the United States, where the top fifteen baking groups control over sixty percent of industrial leavening procurement decisions.
Global Baking Soda Substitute Market Segmentation
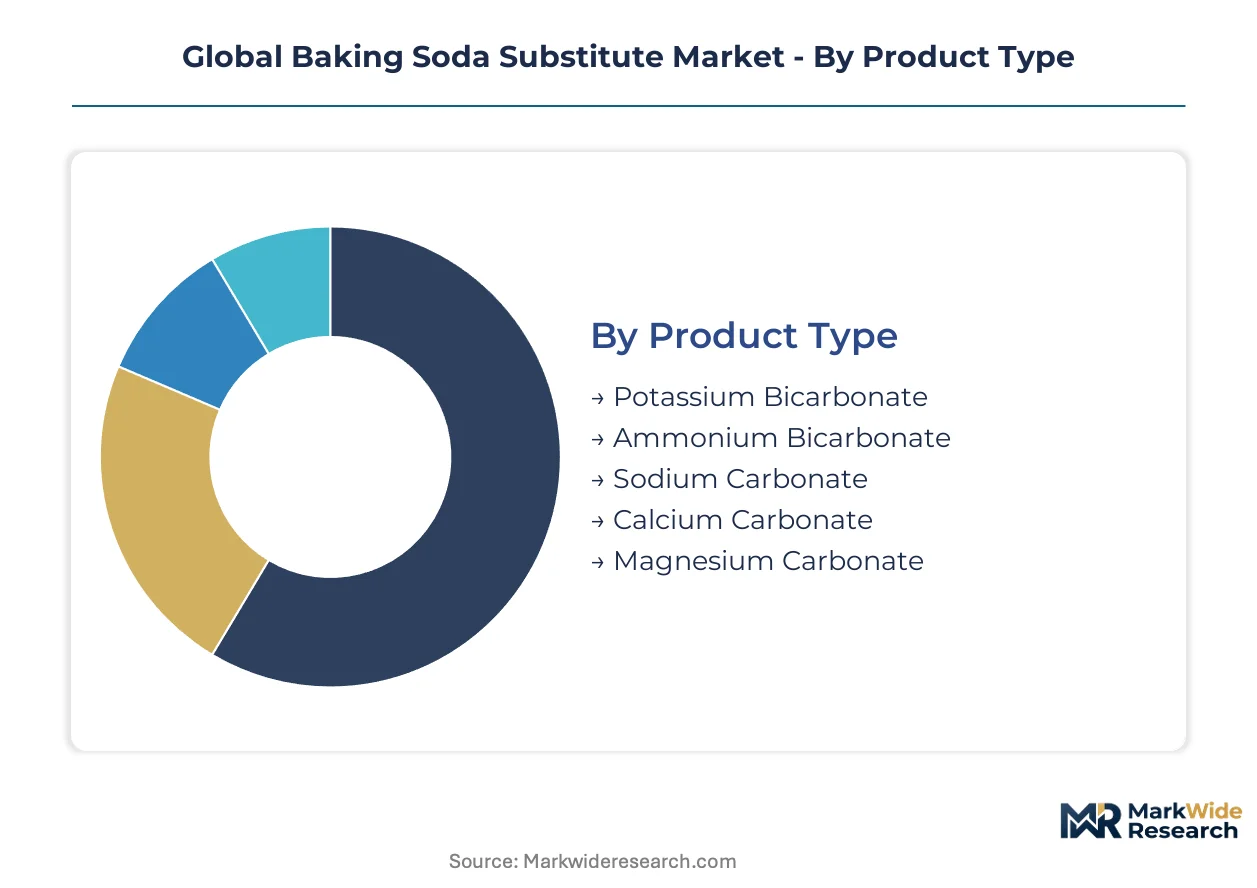
Leavening chemistry and end-use specifications fragment the baking soda substitute market into distinct procurement tiers. Product type determines formulation compatibility, while packaging and application requirements shape distributor relationships and margin structures across food, pharmaceutical, and industrial channels.
Product Type:
Some substitutes function as direct sodium replacements in finished goods; others require acid-base system redesign or thermal process modification.
- Potassium Bicarbonate:Alkaline salt with 39% potassium content delivers equivalent CO₂ release to sodium bicarbonate without sodium load. Cardiac-designated bakery lines in German and French manufacturing plants specify pharmaceutical-grade purity for clean-label positioning under EFSA disclosure frameworks.
- Ammonium Bicarbonate:Volatile leavening agent decomposes completely to gaseous products, leaving no residual salt. European cracker manufacturers in Belgium and the Netherlands rely on narrow thermal windows for thin, dry products where moisture retention is undesirable.
- Sodium Carbonate:Stronger alkali than bicarbonate variants, requiring precise dosage control in pH-sensitive applications. Chemical manufacturing facilities in Japan use reagent grades for laboratory buffer preparation.
- Calcium Carbonate:Inert at baking temperatures, finds utility in agricultural liming and tablet excipients where slow dissolution is preferred. Cost positioning suits volume applications in Chinese greenhouse cultivation.
- Magnesium Carbonate:Light, fluffy powder structure absorbs moisture in personal care formulations. Antiperspirant compounders in the United States specify USP grades for direct skin contact products.
Calcium carbonate leads volumes today; potassium bicarbonate is gaining share fastest.
Application:
Functional requirements span reactive gas generation through passive odor absorption, with each use case imposing distinct purity and particle size specifications.
- Leavening Agent:Gas-release kinetics determine rise quality in baked matrices. US commercial bakeries specify double-acting systems combining potassium bicarbonate with encapsulated acids for extended bench tolerance.
- Cleaning Agent:Mild abrasive action and alkaline pH dissolve grease without surface damage. Japanese household product manufacturers blend calcium carbonate with surfactants for ceramic cooktop formulations.
- Deodorizer:pH neutralization of acidic odor molecules enables refrigerator and footwear applications. Activated magnesium carbonate grades from Chinese producers target consumer goods exporters.
- Fire Extinguishing:Thermal decomposition releases CO₂ while melting to form oxygen barrier. Industrial safety suppliers in Germany stock sodium carbonate-based powders for metal fire classifications.
- pH Regulator:Buffering capacity stabilizes formulation acidity across shelf life. Indian pharmaceutical manufacturers employ potassium bicarbonate in effervescent antacid tablets under CDSCO stability guidelines.
Leavening applications dominate value capture; pH regulation in pharmaceuticals shows steepest expansion trajectory.
End User Industry:
Regulatory frameworks and certification requirements create divergent procurement standards across customer categories.
- Food Processing:Sodium reduction mandates from FDA and EFSA drive reformulation in cracker, cake, and bread manufacturing. German industrial bakeries qualify dual-source potassium bicarbonate supply ahead of potential ammonium compound restrictions.
- Pharmaceuticals:Excipient functionality and sodium-free positioning support cardiac and renal patient formulations. Japan's aging demographic sustains demand for effervescent potassium bicarbonate in antacid and supplement applications.
- Personal Care:Absorbency and mild alkalinity suit deodorant, toothpaste, and bath product matrices. US cosmetic compounders specify USP/FCC grades for clean-label marketing claims.
- Agriculture:Soil pH amendment and controlled-release nutrient delivery extend utility beyond food systems. Chinese greenhouse operators apply magnesium carbonate for precision magnesium supplementation in hydroponic cultivation.
- Chemical Manufacturing:Reagent-grade specifications support analytical and industrial synthesis applications. Japanese laboratory chemical distributors stock sodium carbonate for titration standard preparation.
Food processing anchors procurement volumes; pharmaceutical applications command premium pricing tiers.
Packaging Type:
Moisture sensitivity and handling automation requirements determine container selection across customer scales.
- Box:Corrugated containment with inner moisture barriers suits retail distribution. US specialty baking ingredient brands package potassium bicarbonate in 1-pound boxes for direct-to-consumer e-commerce channels.
- Bag:Multi-wall paper or woven polypropylene enables intermediate bulk handling. Indian commercial bakeries receive 25-kilogram ammonium bicarbonate bags through FSSAI-registered distributors.
- Drum:Steel or fiber construction protects pharmaceutical and personal care grades from contamination. Japanese excipient importers specify sealed drums with nitrogen purge for potassium bicarbonate shipments.
- Bulk Container:Intermediate bulk containers and tank trucks serve high-volume chemical manufacturing and agriculture. Chinese calcium carbonate producers load 1-tonne flexible containers for greenhouse supply contracts.
- Pouch:Flexible laminate structures with reseal features target home baking and small-scale foodservice. German retail chains stock 100-gram pouches of ammonium bicarbonate for traditional springerle cookie preparation.
Bulk containers dominate tonnage movement; pouch formats are expanding most quickly in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial bakeries command premium-grade potassium bicarbonate volumes, while India's cracker manufacturers drive ammonium bicarbonate consumption at markedly different price points and purity specifications.
United States
Commercial bakery consolidation concentrates procurement power among fifteen major baking groups controlling sixty percent of industrial leavening decisions. FDA sodium reduction guidelines force reformulation across cracker, cake, and bread manufacturing lines. Chicago and Minneapolis industrial corridors witness accelerating adoption of microencapsulated potassium bicarbonate for extended-shelf-life retail products.
Germany
Cardiac-designated bakery lines in Baden-Württemberg and Bavaria specify pharmaceutical-grade potassium bicarbonate purity under EFSA disclosure frameworks. REACH authorization timelines compress formulation windows, prompting contingency qualification of calcium carbonate blends. The ECHA's 2024 substance evaluation roadmap prioritizes ammonium compounds for restriction assessment across Rhine-Ruhr industrial bakeries.
Japan
Aging demographics sustain demand for effervescent potassium bicarbonate in antacid and supplement applications through PMDA-regulated channels. METI standards enforcement elevates purity thresholds for pharmaceutical-grade imports. Osaka and Nagoya pharmaceutical clusters integrate sodium-free leavening into cardiac and renal patient formulations.
India
FSSAI implementation of sodium caps in packaged snacks creates immediate demand for ammonium bicarbonate in cracker manufacturing. Maharashtra and Gujarat industrial corridors qualify domestic and imported supply sources ahead of enforcement deadlines. Mumbai-based food processors reformulate legacy recipes to meet clean-label export requirements.
China
GB standards enforcement through SAMR elevates traceability thresholds for carbonate imports in pharmaceutical and personal care applications. Yangtze River Delta greenhouse operators apply magnesium carbonate for precision nutrient delivery in hydroponic cultivation. Shanghai excipient importers specify sealed drums with nitrogen purge for potassium bicarbonate shipments.
Global Baking Soda Substitute Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers defined by volume scale and certification grade. The vendor base separates into three strategic archetypes: fermentation-derived biotech producers, commodity chemical distributors, and specialty ingredient formulators. Consolidation among North American commercial bakeries concentrates purchasing power, forcing smaller suppliers to achieve volume scale or exit. Capacity expansion and dual-source qualification mandates represent dominant competitive moves.
Within the fermentation expertise tier, Lesaffre et Cie SA and Lallemand Inc. occupy positions anchored by yeast and biotechnology capabilities. Associated British Foods PLC exemplifies the diversified conglomerate archetype with European retail and foodservice distribution reach. Corbion N.V represents biotechnology-driven production specialists serving sodium-sensitive formulation requirements.
| Leading Market Players |
|---|
| Lesaffre et Cie SA |
| Associated British Foods PLC |
| Bob's Red Mill Natural Foods |
| Archer Daniels Midland Co |
| Cargill, Inc |
| Corbion N.V |
| Lallemand Inc. |
| Clabber Girl Corporation |
| Kothari Fermentation And Biochem Ltd |
| Others |
Supply & Pricing Matrix
Biotechnology-trained fermentation specialists concentrated in France and the Netherlands command wage premiums that widen spreads between pharmaceutical-grade potassium bicarbonate and commodity ammonium bicarbonate tiers. Labor-cost differentials between these specialized production clusters and standard chemical processing regions in China and India directly feed pricing stratification across certification grades.
Pricing Analysis
Capacity additions in Belarus and Russia are reshaping price floors for potassium carbonate feedstocks, compressing margins for downstream formulators dependent on these geographies. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels separates cardiac-designated bakery lines from industrial cracker manufacturing and agricultural liming applications. Pricing pressure stems from sanctions-driven supply interruptions and energy cost volatility in European production zones. Commercial bakeries in consolidated North American networks exhibit lowest price sensitivity due to dual-source qualification mandates, while small-scale artisanal producers in Japan face acute cost compression.
Supply Chain Analysis
REACH registration and FSSAI import licensing function as primary gating mechanisms for new carbonate entrants, elevating compliance costs above thresholds viable for specialty chemical innovators. Supply concentrates in Belarus, Russia, and Canada for potassium carbonate; China and India for calcium carbonate; and Germany and the Netherlands for ammonium bicarbonate. Raw material dependencies span potash mining outputs, ammonia synthesis feedstock, and limestone quarrying operations. Single-source vulnerability in Belarusian potash exposes downstream formulators to geopolitical disruption. Distribution runs through FSSAI-registered distributors in India, EFSA-aligned wholesalers in Germany, and direct-to-consumer e-commerce platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Baking Soda Substitute Market operates as a regulatory compounder where EFSA's additive re-evaluation framework and FDA sodium reduction mandates generate structural demand for reformulation services. These overlapping compliance requirements create durable procurement pull for certified alternatives.
For Market Incumbents: Hedge against REACH authorization timelines for ammonium compounds by accelerating calcium carbonate blend qualification in German industrial bakeries. Secure backward integration into potassium carbonate supply through long-term offtake agreements with Canadian mining operations. Diversify fermentation capacity across multiple geographies to mitigate sanctions exposure on Belarusian and Russian feedstock sources.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce channels offer the lowest barrier to entry for pharmaceutical-grade potassium bicarbonate targeting home bakers in the United States and Japan. White-space opportunities concentrate in effervescent pharmaceutical applications for aging demographics and precision agriculture formulations for Chinese greenhouse operators. Pursue USP/FCC certification investment as the primary go-to-market angle to bypass established food ingredient wholesaler relationships.
For Investors and Strategic Acquirers: Diversified food ingredient conglomerates are the most active acquirer in this space, seeking sodium-free leavening capabilities for processed food reformulation pipelines. Five-to-ten year viability hinges on regulatory durability of sodium reduction mandates across multiple jurisdictions. Acquisition target archetype: biotechnology-driven carbonate producers with pharmaceutical-grade certification and established technical service capabilities. Monitor ECHA substance evaluation roadmap updates as the critical inflection signal for ammonium compound restriction timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Additional fermentation capacity in France addresses pharmaceutical-grade potassium bicarbonate shortages for cardiac-designated product lines. |
| Backward Integration | Captive potash sourcing from Canadian mining operations insulates formulators from Belarusian supply interruptions. |
| Long-term Supply Agreement | Multi-year offtake contracts with Maharashtra cracker manufacturers secure ammonium bicarbonate volumes ahead of FSSAI enforcement. |
| Green Manufacturing Transition | Biotechnology-enabled production methods compress cost differentials between synthetic and bio-based carbonate sources. |
| Joint Venture | Partnerships with Osaka pharmaceutical clusters accelerate effervescent potassium bicarbonate qualification for aging population markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at European industrial bakeries, procurement leads at North American commercial baking groups, technical R&D directors at fermentation specialists, and regulatory affairs managers at pharmaceutical excipient importers. Secondary validation drew from EFSA additive re-evaluation documentation, FDA sodium reduction guideline releases, REACH registration databases, and FSSAI enforcement circulars. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting approaches assigned differential growth coefficients across product type, application, end user industry, packaging format, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory enforcement timelines and reformulation adoption curves. Forecast inputs incorporated ECHA substance evaluation roadmap priorities, METI pharmaceutical-grade purity thresholds, and SAMR traceability requirement implementations.
Regulatory enforcement delays, feedstock supply interruptions, and reformulation adoption rate variance are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding sodium reduction mandate durability and certification timeline adherence. A model refresh is warranted upon material change in ECHA restriction assessment outcomes for ammonium compounds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Brominated Flame Retardants Market