
 Europe Non-Phthalate Plasticizers Market | 2026-2036
Europe Non-Phthalate Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Phthalate Plasticizers Market Foresight
REACH is decoupling legacy plasticizer economics from viable market entry. BASF SE leverages its Ludwigshafen integrated complex to sustain captive adipate supply chains across Central Europe. Evonik Industries AG anchors specialty trimellitate output for high-temperature cable sheathing. LANXESS competes through backward integration into sebacic acid feedstocks, insulating margin pools from castor oil price volatility.
Europe non-phthalate plasticizers are synthetic or bio-derived compounds—adipates, citrates, sebacates, and trimellitates—that replace ortho-phthalate esters in PVC flexibility modification, typically dosed at 20–60 parts per hundred resin to achieve Shore A hardness targets between 70 and 90. These compounds function by inserting between polymer chains to reduce glass transition temperature without covalent bonding, enabling processing temperatures 15–30°C below phthalate alternatives while maintaining migration resistance under EN 71-3 toy safety protocols. Trimellitates dominate medical device and automotive underhood segments where volatility and fogging constraints are tightest, while adipates occupy high-volume flooring and wall covering applications where cost sensitivity outweighs thermal demands. Citrate esters represent the fastest-expanding category within food-contact films and pediatric toys, driven by EFSA migration limit tightening and brand-led de-risking by consumer goods multinationals.
EMA, ECHA, and the EU Green Deal collectively define product permissibility and carbon intensity thresholds for non-phthalate plasticizers sold into European end-use channels. ECHA's sunset date enforcements under REACH Annex XIV are eliminating di(2-ethylhexyl) phthalate from medical tubing and childcare articles, redirecting procurement specifications toward DEHP-free alternatives with full toxicological dossiers. Stakeholders must monitor the EU AI Act's downstream implications for automated compliance verification in chemical supply chains, as machine-readable safety data sheet requirements will reshape documentation burdens for importers and compounders alike.
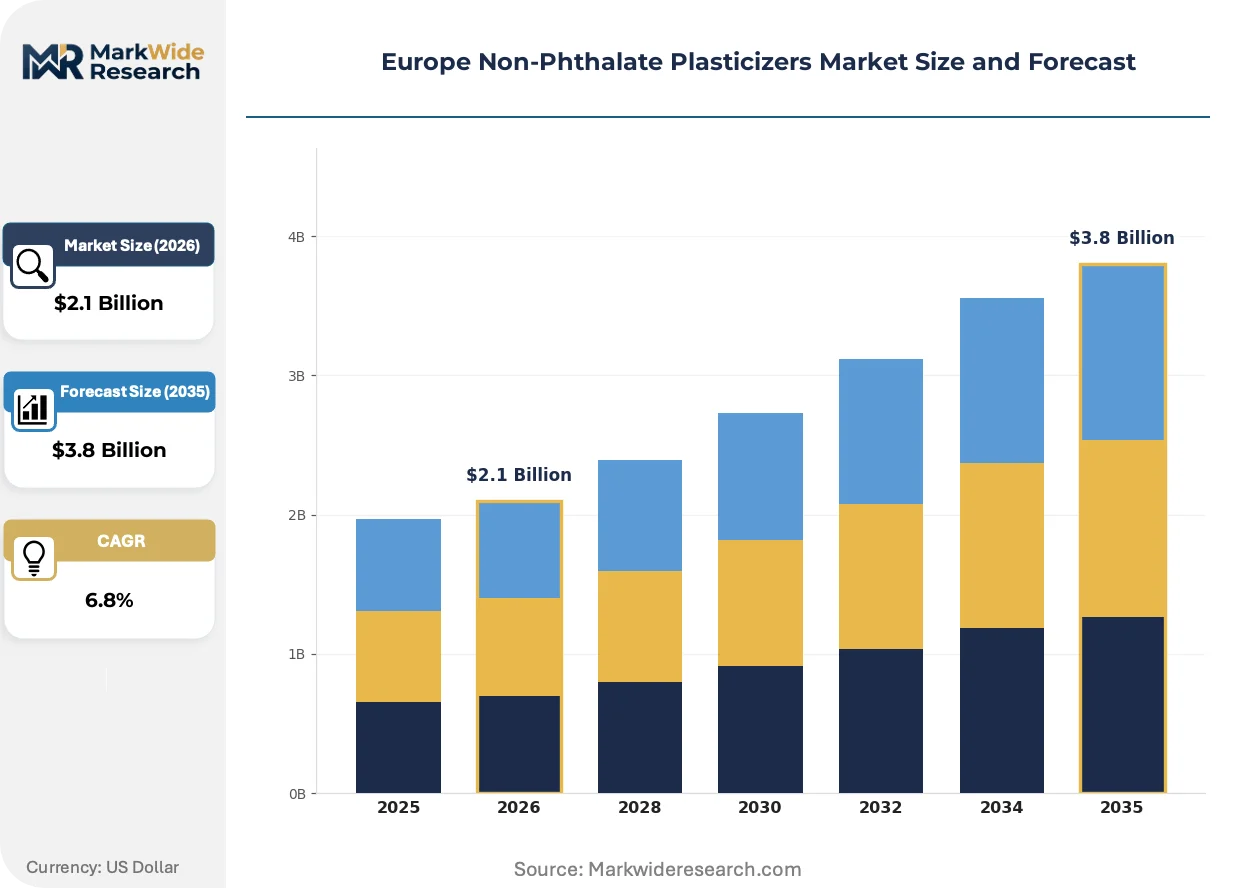
Market Dynamics
REACH Annex XIV sunset dates are systematically eliminating ortho-phthalate plasticizers from European medical tubing and childcare articles, forcing compounders to requalify entire formulation portfolios under compressed timelines. This regulatory compression is redrawing competitive boundaries between integrated adipate producers and specialty trimellitate suppliers.
Growth Catalysts
- ECHA enforcement timelines:REACH restrictions on di(2-ethylhexyl) phthalate in pediatric toys are redirecting procurement specifications toward citrate esters with full toxicological dossiers.
- Automotive underhood thermal demands:German OEMs are specifying trimellitate formulations for cable sheathing operating above 105°C, displacing legacy phthalates in engine bay harnesses.
- Italian flooring clusters:Flexible PVC compounding operations around Milan and Bologna are absorbing adipate volumes for wall covering export markets.
Market Restraints
- Castor oil price volatility:Sebacate producers dependent on ricinoleic acid feedstocks face margin compression when Indian monsoon patterns disrupt harvests.
- Bio-adipate yield gaps:Fermentation-based production routes from glucose feedstocks remain 15-20% below petrochemical adipic acid conversion efficiencies.
- Migration testing bottlenecks:EFSA protocol updates for food-contact films are extending certification timelines by 8-12 months for novel plasticizer chemistries.
Strategic Opportunities
- French medical device requalification:Strasbourg and Lyon tubing manufacturers are seeking DEHP-free alternatives for neonatal intensive care applications.
- EU Green Deal carbon intensity thresholds:Bio-sebacates derived from European rapeseed oil qualify for preferential procurement scoring in public hospital tenders.
- Digital compliance verification:Machine-readable safety data sheet requirements under the EU AI Act are creating first-mover advantages for compounders with integrated documentation systems.
Industry Challenges
- Formulation chemist scarcity:PVC compounding expertise concentrated among aging technical workforces in Germany and Italy is not replenishing at replacement rates.
- Legacy equipment retrofit costs:Adipate and citrate esters require modified screw configurations and cooling profiles versus phthalate-optimized extrusion lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Phthalate Plasticizers Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adipates, Citrates, Sebacates, Trimellitates End Use Industry: Automotive, Consumer Goods, Building & Construction, Electrical Formulation Type: Flexible PVC, Rigid PVC, Coatings, Adhesives Application: Flooring, Medical Devices, Toys, Packaging |
| Companies Covered | Perstorp, Eastman Chemical Company, BASF SE, Avient Corporation, Polynt, Evonik Industries AG, Arkema, Clariant AG, LANXESS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Phthalate Plasticizers Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived building blocks as EFSA migration limits tighten and brand-led de-risking accelerates across consumer goods supply chains. Three converging developments are restructuring competitive positioning.
Enzymatic esterification using immobilized lipase biocatalysts is electrifying sebacate production economics by eliminating high-temperature processing steps and reducing color bodies in final products. Dutch specialty chemical producers are deploying this technology for pharmaceutical-grade citrate esters. The process compression is enabling smaller batch sizes with faster turnaround, disrupting economies-of-scale assumptions that favored centralized phthalate production.
REACH authorization requirements under Annex XIV are forcing downstream users to submit substitution plans for diisononyl phthalate in flooring applications by 2027. German automotive suppliers are pre-emptively qualifying trimellitate alternatives to avoid supply continuity risks. The regulatory friction is accelerating collaborative qualification programs between compounders and OEM specification engineers.
Specification-driven procurement is consolidating purchasing authority among centralized sustainability teams at consumer goods multinationals. These buyers are unbundling traditional distributor relationships to engage directly with plasticizer manufacturers for carbon footprint verification. The channel compression is most visible in Nordic markets where retailer-led chemical transparency initiatives have advanced furthest.
Europe Non-Phthalate Plasticizers Market Segmentation
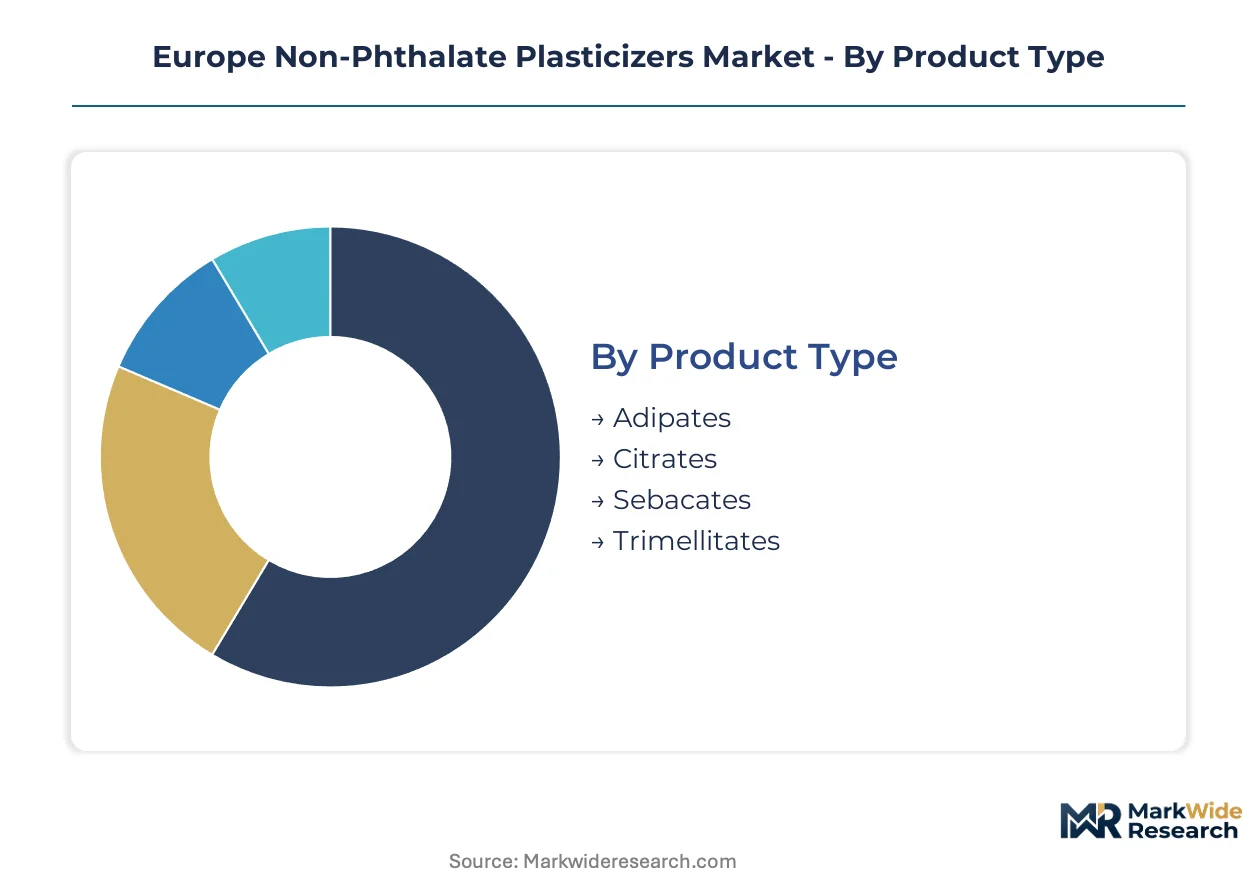
Plasticizer selection in European compounding operations hinges on thermal performance thresholds, migration resistance requirements, and feedstock carbon intensity. Segmentation reveals how formulation chemistry maps onto regulatory compliance tiers and end-use specification bands.
Product Type:
Technical specifications around volatility, fogging resistance, and glass transition depression define competitive positioning across the four primary chemistries.
- Adipates:Linear diesters of adipic acid with C8-C10 alcohols deliver cost-efficient flexibility modulation at 20-40°C below trimellitate processing temperatures. Italian flooring manufacturers around Milan absorb the largest volumes for wall covering export markets where Shore A targets of 75-85 dominate specifications.
- Trimellitates:Branched triesters of trimellitic anhydride provide the lowest volatility profiles and highest thermal stability among non-phthalate alternatives. German automotive cable sheathing operating above 105°C specifies these formulations exclusively, displacing legacy phthalates in engine bay harnesses as OEM thermal durability standards tighten.
- Citrates:Acetyl tributyl citrate and tributyl citrate esters offer the most favorable toxicological profiles for pediatric toy and food-contact film applications. EFSA migration limit tightening is accelerating procurement shifts from compounders serving Nordic retailer transparency initiatives.
- Sebacates:Diesters of sebacic acid derived from castor oil ricinoleic acid deliver superior low-temperature flexibility down to -40°C. Bio-sebacates from European rapeseed oil feedstocks qualify for preferential scoring in French public hospital tenders under EU Green Deal carbon thresholds.
Adipates lead on scale; citrates lead on momentum.
End Use Industry:
Specification authority concentrates differently across sectors, with automotive and medical device buyers exercising the tightest formulation control.
- Automotive:German OEMs specify trimellitate formulations for underhood cable sheathing and interior trim where fogging and volatility constraints are tightest. Thermal durability requirements above 105°C are eliminating legacy phthalate alternatives from engine bay harness qualifications.
- Building & Construction:Italian flexible PVC compounding clusters around Bologna and Milan consume adipate volumes for flooring and wall covering export markets. Cost sensitivity in this segment outweighs thermal performance demands, favoring high-volume adipate economics.
- Consumer Goods:Brand-led de-risking by multinationals is redirecting toy and childcare article formulations toward citrate esters with full REACH toxicological dossiers.
- Electrical:Cable insulation and jacketing applications specify trimellitates for high-temperature conductor protection in industrial and infrastructure deployments.
Building & Construction leads on volume throughput; Automotive leads on specification premium.
Formulation Type:
Processing temperature windows and shear requirements differentiate formulation platform economics for compounders.
- Flexible PVC:The dominant application platform, dosed at 20-60 parts per hundred resin to achieve Shore A hardness between 70 and 90. Flooring and medical tubing represent the largest consumption channels.
- Rigid PVC:Lower plasticizer loadings below 10 phr modify impact resistance without sacrificing structural rigidity for construction profiles and piping.
- Coatings:Solvent-borne and water-borne systems incorporate sebacates and adipates for film flexibility in industrial and protective applications.
- Adhesives:Pressure-sensitive and sealant formulations leverage citrate plasticizers for low-toxicity bonding in consumer-accessible products.
Flexible PVC leads on absolute consumption; Coatings lead on formulation innovation velocity.
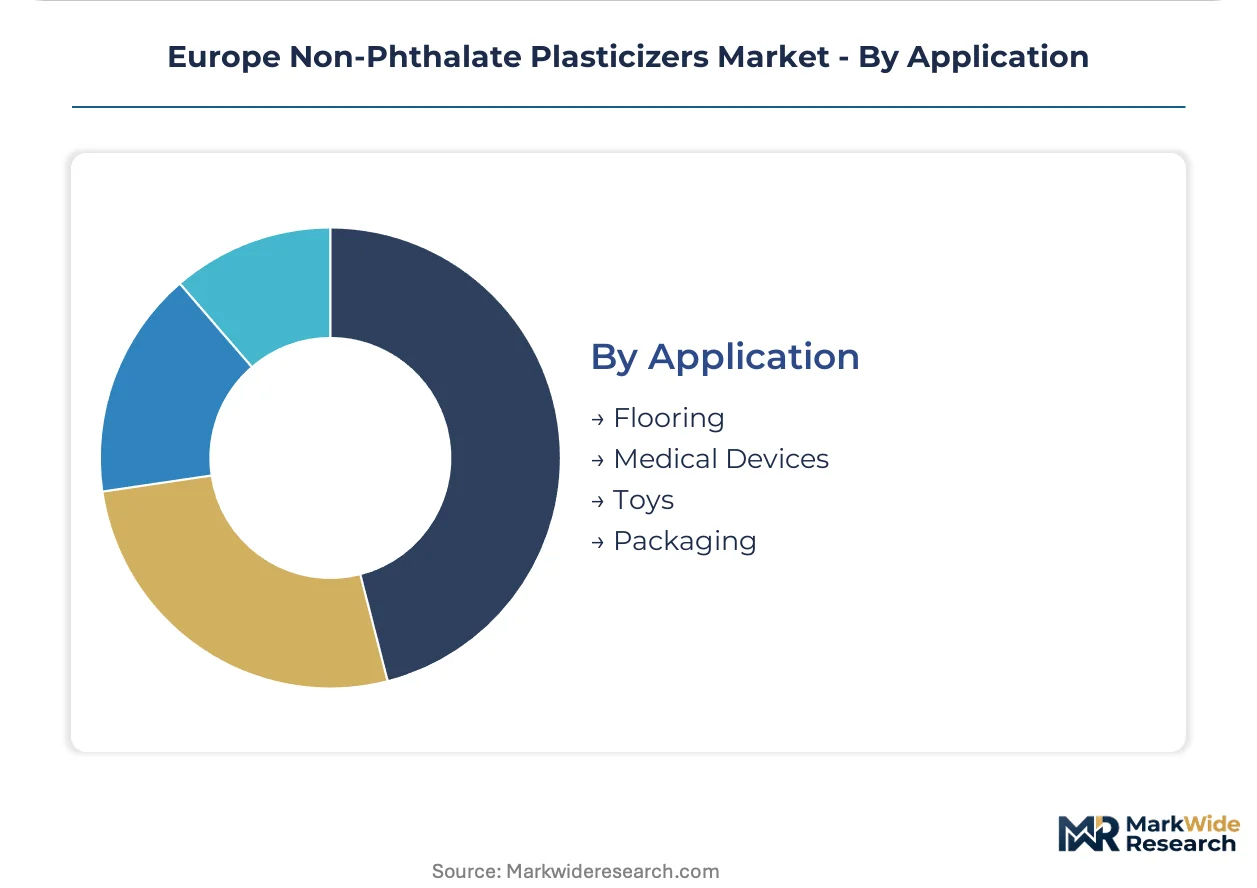
Application:
Regulatory exposure and brand risk profiles segment demand intensity across end-use channels.
- Medical Devices:DEHP elimination from neonatal tubing and intravenous delivery systems under ECHA sunset dates is forcing requalification toward trimellitate and citrate alternatives. Strasbourg and Lyon manufacturers are accelerating procurement of DEHP-free formulations.
- Flooring:Italian compounding operations supply adipate-modified flexible PVC for residential and commercial vinyl tile export markets.
- Toys:REACH restrictions on ortho-phthalates in pediatric articles are redirecting specifications toward citrate esters with established migration safety profiles.
- Packaging:Food-contact films face EFSA protocol updates extending certification timelines, favoring incumbent citrate formulations with existing dossiers.
Flooring leads on manufacturing scale; Medical Devices lead on regulatory-driven substitution intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible PVC compounding operations first achieved industrial scale in Germany's Rhine corridor during the post-war chemical expansion, establishing the technical foundations that now govern non-phthalate formulation standards across the continent.
Germany
Automotive cable sheathing and medical tubing manufacturers in Ludwigshafen and the Ruhr region are absorbing trimellitate volumes for DEHP replacement programs. ECHA sunset date enforcement under REACH Annex XIV is eliminating legacy phthalates from neonatal care applications by 2027. BASF SE's integrated Ludwigshafen complex sustains captive adipate supply chains serving Central European compounders.
Italy
Milan and Bologna flooring clusters consume adipate plasticizers for wall covering export markets where cost sensitivity dominates procurement decisions. The EU Green Deal's carbon intensity thresholds are redirecting formulation investments toward bio-adipates in Emilia-Romagna compounding operations. Italian flexible PVC producers supply residential vinyl tile markets across Southern Europe and North Africa.
France
Strasbourg and Lyon medical device manufacturers are accelerating requalification of DEHP-free formulations for neonatal intensive care tubing systems. EFSA migration limit tightening for food-contact applications is favoring citrate esters with established toxicological dossiers. French public hospital tenders under EU Green Deal frameworks award preferential scoring to bio-sebacates from European rapeseed oil feedstocks.
Netherlands
Dutch specialty chemical producers are deploying enzymatic esterification technology for pharmaceutical-grade citrate esters using immobilized lipase biocatalysts. The process eliminates high-temperature steps and reduces color bodies in final products. Rotterdam-area formulation facilities serve Nordic retailer transparency initiatives with accelerated batch turnaround capabilities.
Belgium
Antwerp chemical processing infrastructure supports sebacate production routes dependent on castor oil ricinoleic acid feedstocks. Indian monsoon volatility disrupts harvests and compresses margins for bio-derived plasticizer producers. Belgian compounders are qualifying rapeseed-based alternatives to insulate supply chains from tropical agricultural risk.
Europe Non-Phthalate Plasticizers Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with backward control over adipic acid and sebacic acid feedstocks. Specialty trimellitate producers occupy narrower premium positions in automotive and medical segments where thermal performance commands specification authority. Three archetypes dominate: integrated chemical majors with captive raw material supply, specialty ester producers focused on high-purity pharmaceutical and food-contact grades, and regional compounders serving construction-sector volume demand. Competitive moves center on fermentation-based bio-adipate yield improvements and enzymatic process licensing for color-critical applications.
Among integrated chemical majors, BASF SE and Evonik Industries AG exemplify divergent strategic positions within the non-phthalate plasticizer value chain. BASF SE anchors adipate supply security through its Ludwigshafen Verbund complex, while Evonik Industries AG occupies the specialty trimellitate segment for high-temperature cable specifications. LANXESS represents the backward-integrated sebacate archetype with upstream control over sebacic acid feedstocks. These three companies illustrate how feedstock positioning and thermal performance specialization segment competitive terrain.
| Leading Market Players |
|---|
| Perstorp |
| Eastman Chemical Company |
| BASF SE |
| Avient Corporation |
| Polynt |
| Evonik Industries AG |
| Arkema |
| Clariant AG |
| LANXESS |
| Others |
Supply & Pricing Matrix
German automotive OEM procurement teams concentrate purchasing authority for trimellitate formulations, anchoring contract-based long-term offtake pricing that insulates premium tiers from spot volatility in adipate feedstocks.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade levels segments the market. Certification under REACH Annex XIV toxicological dossiers and EFSA migration protocols commands substantial premiums over standard technical grades. Cost compression in commodity adipates is intensifying because Italian flooring exporters prioritize volume scale over thermal performance. Building and construction compounders exhibit highest price sensitivity, while medical device manufacturers accept premium positioning for DEHP-free alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Indian castor oil harvests that feed Belgian sebacate production. Manufacturing gravity centers on Germany, Italy, and the Netherlands, with Ludwigshafen and Rotterdam anchoring petrochemical adipate supply. Raw material flows draw from adipic acid, trimellitic anhydride, and ricinoleic acid feedstocks. Tariff exposure on bio-derived sebacic acid imports compresses margin pools during monsoon disruptions. Distribution runs through integrated compounders serving automotive and medical OEMs directly, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as REACH sunset dates force systematic substitution of legacy phthalates across European medical and childcare applications.
For Market Incumbents: To counter margin compression from castor oil price volatility, LANXESS and backward-integrated sebacate producers should deepen upstream control over European rapeseed oil alternatives. BASF SE can extend captive adipate supply advantages by expanding technical service capabilities for Italian flooring compounders facing requalification deadlines. For New Entrants and Emerging Players: Launch via enzymatic esterification licensing to serve Dutch pharmaceutical-grade citrate demand with smaller batch flexibility. White-space opportunity concentrates in French public hospital tenders where EU Green Deal carbon scoring favors bio-sebacates from regional feedstocks. Target direct engagement with centralized sustainability procurement teams at Nordic consumer goods multinationals bypassing legacy distributor relationships. For Investors and Strategic Acquirers: Specialty chemical conglomerates with fermentation bio-adipate platforms are the most active acquirer in this space, seeking yield-gap closure against petrochemical routes. Long-term viability hinges on regulatory permanence of REACH restrictions and EFSA migration tightening. Watch enzymatic process cost curves as the inflection signal for pharmaceutical-grade citrate economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sebacic Acid | LANXESS insulates margins from Indian monsoon volatility through rapeseed oil alternatives. |
| Enzymatic Esterification Licensing | Dutch producers capture pharmaceutical-grade citrate premiums via immobilized lipase biocatalysts. |
| REACH Annex XIV Compliance Investment | Medical tubing manufacturers secure DEHP-free formulation qualifications ahead of sunset deadlines. |
| Carbon Intensity Certification Program | Bio-adipate producers qualify for preferential scoring in French public hospital tenders. |
| Direct OEM Procurement Engagement | Compounders bypass distributors to serve centralized sustainability teams at Nordic retailers. |
Research Methodology
Bottom-up flexible PVC compounding modeling reconciled against top-down plasticizer production tracking forms the analytical core of this study. Primary interviews with plant managers at Italian flooring operations, procurement leads at German automotive Tier 1 suppliers, technical R&D directors at adipate producers, and distribution channel partners across the Benelux region informed demand-side calibration. Secondary validation drew from ECHA REACH registration databases, Cefic chemical industry reports, customs trade data for adipic acid and sebacic acid flows, and SEC filings of listed chemical majors.
Historical trendline analysis of formulation substitution patterns across the analysis window established baseline elasticity assumptions. Segmentation modeling incorporated product chemistry tier, end-use industry vertical, formulation platform type, and regional production hub clustering. CAGRs were derived from slope analysis of annual volume trajectories, with cross-reference to ECHA enforcement timeline impacts and EU Green Deal carbon threshold implementation schedules.
Several conditions sit outside the modeled scope, including potential REACH authorization reversals, breakthrough fermentation yield improvements beyond current technical literature, and geopolitical disruptions to castor oil trade flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Precipitated Barium Sulfate Market
Specialty Chemicals
Bromocyclopentane Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Polyquaternium 6 Market