
 Chromatography Market | 2026-2036
Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatography Market Intelligence
The trend toward modular chromatography systems, which allow laboratories to configure instruments for specific analytical tasks, is restructuring buyer choice. Thermo Fisher Scientific leverages its extensive portfolio to provide comprehensive, bundled solutions. In contrast, Agilent Technologies competes on the performance and reliability of its individual components and systems. Waters Corporation specializes in high-performance liquid chromatography, anchoring its position in the pharmaceutical sector.
Chromatography is an analytical chemistry technique used to separate, identify, and quantify components within a mixture. The process relies on the differential partitioning of analytes between a mobile phase and a stationary phase. Liquid Chromatography, especially High Performance Liquid Chromatography (HPLC) systems, represents the dominant product type due to its wide applicability in pharmaceutical research. The food safety testing application segment is expanding rapidly, driven by consumer and regulatory pressures for stringent quality control.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) are critical demand drivers. These agencies enforce strict standards for drug purity and composition, necessitating advanced analytical validation. Compliance with standards from bodies like Japan's PMDA further solidifies the need for precise instrumentation. System vendors must balance investments between developing highly specialized instruments for niche applications and all-in-one platforms for general laboratory use.
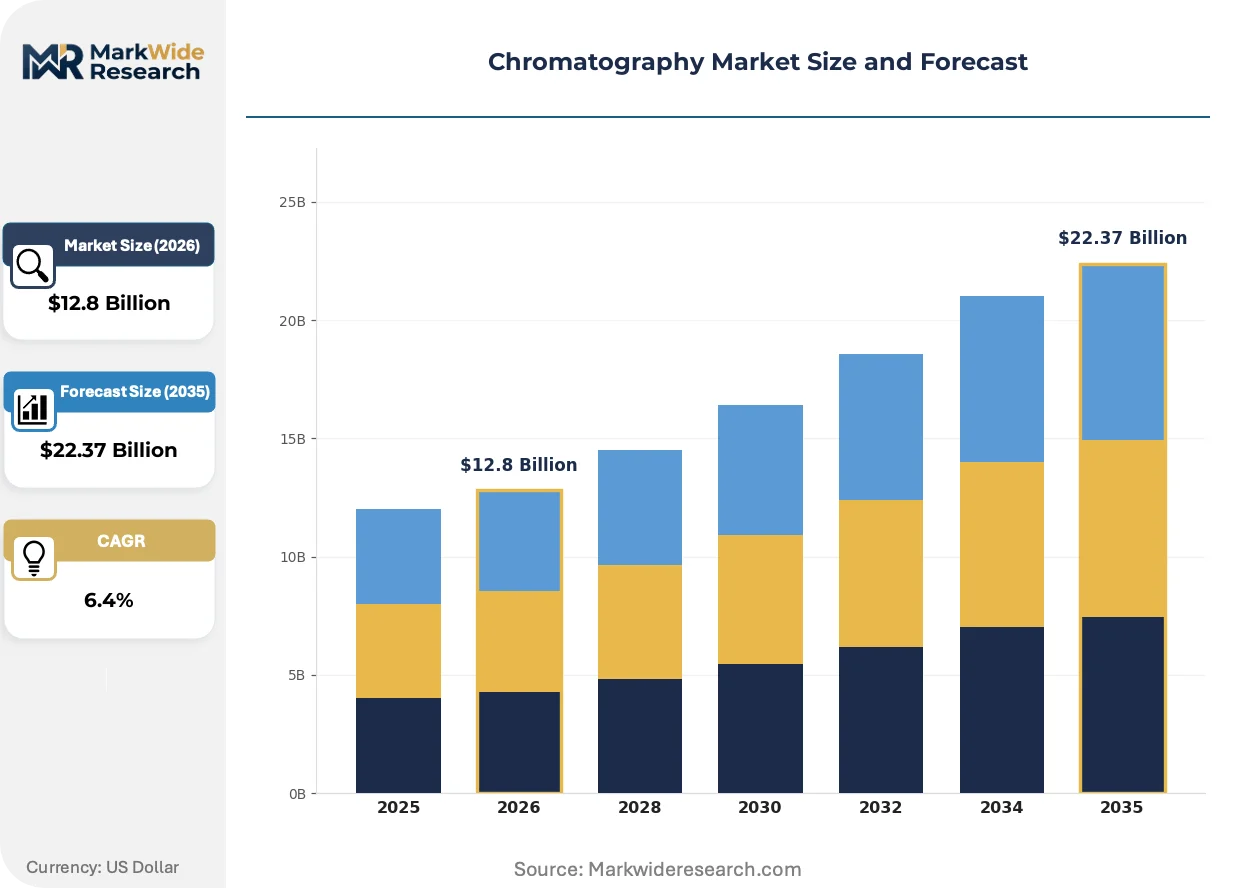
Market Dynamics
The market's central dynamic is the tension between demand for highly specialized, high-performance systems for biopharmaceutical QC and the concurrent need for versatile, modular platforms for general analytical laboratories, influencing vendor product strategies.
Growth Catalysts
- Regulatory Mandates:Stricter purity and validation standards from the US FDA and EMA for biologics, especially monoclonal antibodies, compel the use of advanced chromatography for characterization.
- Food Safety Expansion:The food and beverage industry's adoption of chromatography for detecting contaminants and ensuring quality is accelerating, driven by regulations from bodies like the EFSA.
- Technological Advancement:The adoption of 2D-Liquid Chromatography provides enhanced resolution for complex mixtures, finding significant use in proteomics and metabolomics research.
Market Restraints
- High Capital Cost:The significant initial investment required for advanced systems like UHPLC and mass spectrometry, coupled with high maintenance expenses, limits adoption in smaller labs.
- Technical Complexity:Method development and data interpretation for advanced techniques demand highly skilled personnel, creating a bottleneck due to a shortage of qualified chromatographers.
- Supply Chain Vulnerabilities:The market relies on a concentrated group of suppliers for high-purity solvents and specialized stationary phase materials, creating price and availability risks.
Strategic Opportunities
- Emerging Market Penetration:Instrument vendors can expand into biopharmaceutical R&D hubs in India and Brazil, where local regulators are harmonizing standards with global benchmarks.
- Field-Deployable Systems:Developing portable chromatography instruments creates new applications in environmental monitoring, on-site food testing, and point-of-care diagnostics.
- AI and Automation:Integrating machine learning algorithms offers opportunities to automate method development, streamline data analysis, and enable predictive maintenance for instruments.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of analysts with expertise in multidimensional chromatography and coupled techniques like LC-MS impedes the full utilization of advanced instrumentation.
- System Interoperability:Integrating new modular instruments with legacy laboratory information management systems (LIMS) and equipment from different vendors remains a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatography Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Chromatography, Liquid Chromatography, Ion Exchange Chromatography, Size Exclusion Chromatography Technology: High Performance Liquid, Ultra Performance Liquid, Gas, Affinity, Thin Layer Application: Pharmaceutical Research, Food Safety Testing, Environmental Analysis, Forensic Science, Biotechnology End User: Contract Research Organizations, Academic Institutes, Chemical Manufacturers, Cosmetics Producers, Testing Laboratories |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Waters Corporation, Shimadzu Corporation, Merck KGaA, PerkinElmer, Bio-Rad Laboratories, Danaher Corporation, Sartorius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatography Market Strategic Shifts & Innovations
Automation and miniaturization are the primary forces reshaping laboratory workflows and instrument design. These developments prioritize higher throughput, reduced operational costs, and faster time-to-result, altering how analytical data is generated and managed in modern labs.
Microfluidics technology miniaturizes separation processes onto a single chip, reducing sample and reagent volumes. Biopharmaceutical labs are increasingly adopting this for high-throughput screening applications. This miniaturization technology is converging with mass spectrometry to create fully integrated and automated sample-to-answer platforms, compressing analytical timelines.
Japan's Pharmaceutical and Medical Devices Agency (PMDA) has elevated its data integrity requirements for drug manufacturing, aligning with global cGMP expectations. This mandate compels investment in chromatography data systems (CDS) with secure audit trails and electronic signature functions. The liquid chromatography segment, especially HPLC systems in quality control, feels the most direct impact of this compliance pressure.
A preference for instrument leasing and reagent rental agreements is emerging as an alternative to large capital purchases. This model enables smaller contract research organizations and academic labs to use advanced technology without significant upfront investment. The shift is most visible in the North American and European biopharmaceutical startup ecosystems.
Chromatography Market Segmentation
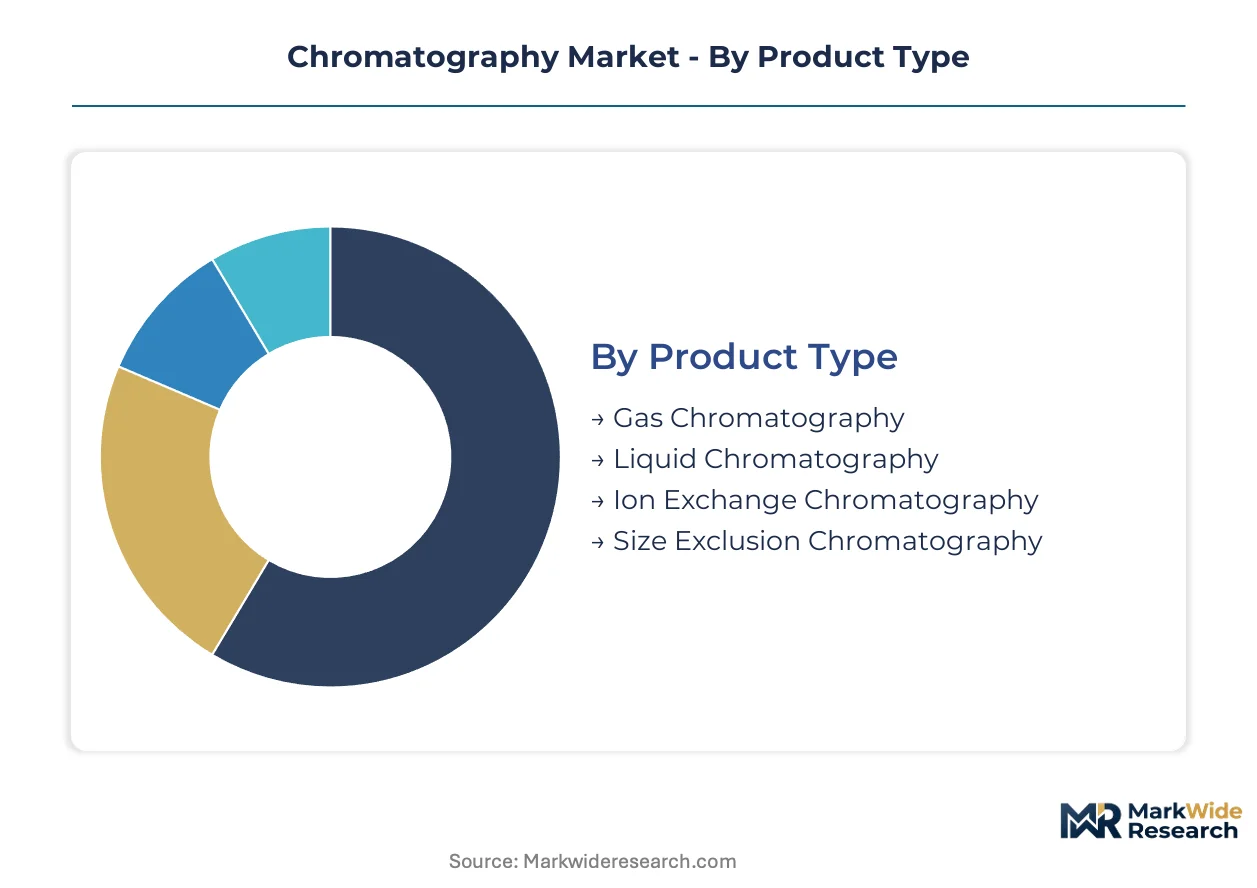
Understanding the distinct segments within the chromatography market is essential for discerning specific demand patterns and technological preferences. Each category reflects varied analytical needs and regulatory compliance requirements across diverse industrial and research settings. This granular view helps in identifying areas of concentrated investment and emerging growth.
Product Type:
The functional differences and separation mechanisms define the various product types within chromatography.
- Liquid Chromatography:Liquid Chromatography separates components based on their differential partitioning between a liquid mobile phase and a solid stationary phase. Demand concentrates in pharmaceutical research due to its wide applicability in drug discovery and quality control.
- Gas Chromatography:Gas Chromatography separates volatile and semi-volatile compounds by partitioning them between a gaseous mobile phase and a liquid or solid stationary phase. Environmental analysis and food safety testing drive its use for detecting trace contaminants in complex matrices.
- Ion Exchange Chromatography:Ion Exchange Chromatography separates ions and polar molecules based on their charge, utilizing a stationary phase with charged functional groups.
- Size Exclusion Chromatography:Size Exclusion Chromatography separates molecules based on their hydrodynamic volume, passing them through a porous stationary phase.
Liquid Chromatography leads on scale; Gas Chromatography shows strong momentum in new application areas.
Technology:
Performance characteristics and operational principles differentiate the core chromatography technologies.
- High Performance Liquid:High Performance Liquid Chromatography (HPLC) utilizes high pressure to force a liquid mobile phase through a column packed with small particles, enabling efficient separations. Pharmaceutical quality control and biopharmaceutical analysis in the United States heavily rely on HPLC for precise compound identification.
- Ultra Performance Liquid:Ultra Performance Liquid Chromatography (UPLC) employs sub-2-micron particles and higher pressures, delivering superior resolution and faster analysis times compared to HPLC. Biopharmaceutical R&D in Germany adopts UPLC for complex mixture analysis and high-throughput screening.
- Gas:Gas chromatography technology separates volatile compounds, finding extensive use in petrochemical and environmental laboratories.
- Affinity:Affinity chromatography isolates specific biomolecules based on highly selective binding interactions, crucial for protein purification.
- Thin Layer:Thin Layer Chromatography offers a simple, cost-effective method for qualitative analysis and sample screening on a stationary phase coated on a flat plate.
The advancements in Ultra Performance Liquid chromatography are driving higher resolution separations while High Performance Liquid chromatography maintains its foundational role.
Application:
Regulatory frameworks and specific industry needs dictate the primary applications of chromatography.
- Pharmaceutical Research:Pharmaceutical research leverages chromatography for drug discovery, development, and quality control, analyzing active pharmaceutical ingredients and impurities. Stricter purity and validation standards from the US FDA and EMA compel its use for biologics characterization.
- Food Safety Testing:Food safety testing employs chromatography to detect contaminants like pesticides, mycotoxins, and allergens, ensuring consumer protection. Regulations from bodies like the EFSA in Europe accelerate the adoption of chromatography for quality assurance.
- Environmental Analysis:Environmental analysis utilizes chromatography to monitor pollutants in air, water, and soil, supporting regulatory compliance and public health.
- Forensic Science:Forensic science applies chromatography for identifying unknown substances in crime scene investigations and toxicology.
- Biotechnology:Biotechnology research uses chromatography for protein purification, nucleic acid separation, and complex biomolecule analysis.
Demand is highest in Pharmaceutical Research due to stringent regulatory requirements, with Food Safety Testing showing significant expansion.
End User:
The operational models and analytical needs of various entities define the end-user landscape for chromatography.
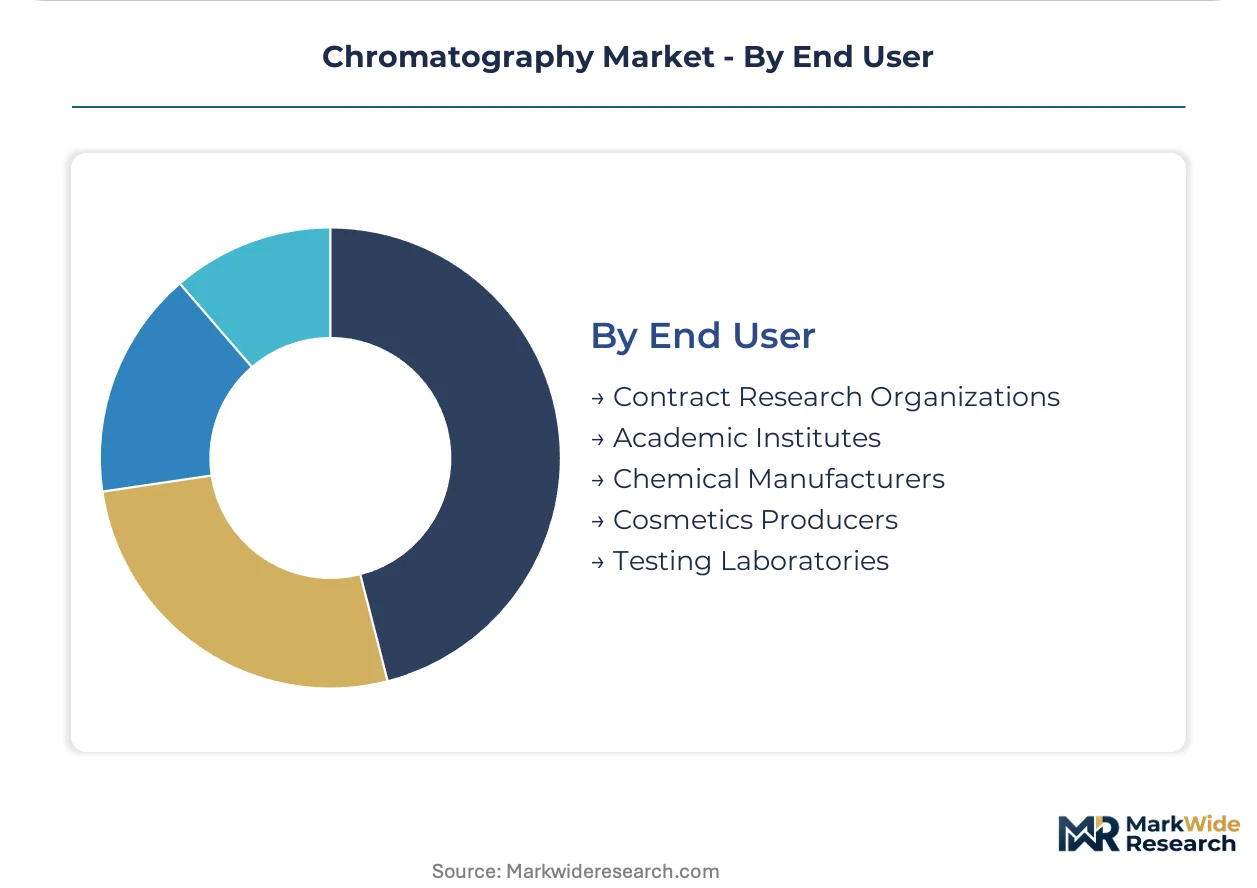
- Contract Research Organizations:Contract Research Organizations (CROs) provide specialized analytical services to pharmaceutical, biotechnology, and chemical industries. They drive demand for advanced, high-throughput systems to support diverse client projects and accelerate drug development timelines.
- Testing Laboratories:Independent testing laboratories offer analytical services across multiple sectors, including environmental, food, and industrial quality control. Strict compliance with national and international standards, such as those from the US FDA, mandates precise chromatography instrumentation.
- Academic Institutes:Academic Institutes utilize chromatography for fundamental research, method development, and training future analytical scientists.
- Chemical Manufacturers:Chemical Manufacturers employ chromatography for raw material inspection, process monitoring, and final product quality assurance.
- Cosmetics Producers:Cosmetics Producers use chromatography to ensure ingredient purity, detect contaminants, and verify product formulation.
The largest volume of instruments goes to Testing Laboratories, while Contract Research Organizations represent a growing segment for outsourced analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chromatography market's historical lineage traces back to European scientific discoveries, yet its significant scaling occurred within the United States, driven by pharmaceutical research. Demand for advanced analytical techniques now extends globally, with key hubs emerging across Asia. This expansion is shaped by evolving regulatory landscapes and increasing biopharmaceutical investments in various regions.
United States
Pharmaceutical research and biopharmaceutical R&D heavily influence chromatography demand in the United States. The US FDA enforces rigorous standards for drug purity and validation, necessitating advanced analytical instrumentation. Major biotech clusters in Boston-Cambridge and the San Francisco Bay Area drive continuous innovation and adoption of high-performance systems.
Germany
Germany's biopharmaceutical R&D sector shows strong demand for Ultra Performance Liquid Chromatography, particularly for complex mixture analysis. The European Medicines Agency (EMA) regulations compel precise analytical validation in drug manufacturing. Research centers in Munich and Frankfurt remain at the forefront of adopting advanced chromatography technologies.
Japan
Japanese drug manufacturing facilities require precise instrumentation for quality control and data integrity. The PMDA's elevated data integrity requirements directly impact investments in chromatography data systems. Major pharmaceutical companies in Tokyo and Osaka consistently upgrade their analytical capabilities to meet these stringent global benchmarks.
China
China's expanding biopharmaceutical R&D hubs and growing food safety testing needs are accelerating chromatography adoption. The NMPA's strengthening regulatory framework for pharmaceuticals drives the demand for compliant analytical solutions. Industrial centers like Shanghai and Beijing are seeing increased investment in both specialized and versatile chromatography platforms.
India
India's emerging biopharmaceutical R&D sector and generic drug manufacturing drive the need for cost-effective, high-performance chromatography systems. Local regulators are progressively harmonizing standards with global benchmarks, increasing the need for advanced analytical validation. Pharmaceutical clusters in Hyderabad and Bengaluru are key areas for market penetration by instrument vendors.
Chromatography Market Key Industry Players
Premium-margin players sit above commodity-margin players across the chromatography instrument and consumables market. The market structure features a mix of vertically integrated providers offering comprehensive solutions and specialized manufacturers focusing on niche components. Strategic archetypes include full-suite technology providers, high-performance component specialists, and application-specific system developers. Competitive activity predominantly involves strategic partnerships and continuous portfolio diversification to address evolving analytical needs.
Within the full-suite technology provider archetype, Thermo Fisher Scientific and Agilent Technologies exemplify broad portfolios spanning instruments, software, and consumables. Waters Corporation occupies a position as a high-performance liquid chromatography specialist, anchoring its presence in the pharmaceutical sector. These companies represent the diverse approaches to market leadership, from extensive product lines to highly focused, high-performance offerings.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Waters Corporation |
| Shimadzu Corporation |
| Merck KGaA |
| PerkinElmer |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Sartorius |
| Others |
Cost & Logistics Intelligence
Miniaturization technologies are reshaping cost economics by reducing reagent and sample volumes, while simultaneously concentrating the supply base for specialized microfluidic components. This shift influences both instrument pricing and raw material availability in the chromatography market.
Pricing Analysis
A tiered pricing structure across premium, standard, and economy levels characterizes the chromatography market. Price differentiation stems from instrument performance, regulatory compliance features for pharmaceutical applications, and bundled after-sales service agreements. Pricing pressure stems from the commoditization of standard HPLC systems and the entry of new manufacturers. Smaller academic labs and contract research organizations exhibit higher price sensitivity compared to large biopharmaceutical enterprises.
Supply Chain Analysis
Logistics and freight costs significantly influence the final pricing of specialized chromatography instruments and high-purity reagents. Supply for advanced systems and critical components concentrates in Germany and Japan, while China provides a growing share of consumables. The market relies on a concentrated group of suppliers for high-purity solvents and specialized stationary phase materials. Single-source vulnerability for key components represents a structural risk, and distribution runs through a mix of direct sales channels and specialized regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chromatography market presents a margin-expansion story driven by the shift towards high-resolution systems and automation, which enables premium pricing and reduces operational costs. This allows vendors to capture greater value from advanced analytical capabilities.
For Market Incumbents: Acquire specialized software firms focused on AI and machine learning to integrate advanced data interpretation and automated method development capabilities. This counters the threat from emerging analytical platforms and addresses the technical complexity bottleneck. Incumbents should also consolidate niche component manufacturers to reduce single-source supply chain vulnerabilities. Invest in R&D for miniaturized, field-deployable systems to expand application areas beyond traditional labs.
For New Entrants and Emerging Players: Price-point gaps exist between premium high-performance systems and basic economy models, creating an opportunity for versatile, modular platforms. New entrants can target academic institutes and smaller contract research organizations with cost-effective, adaptable solutions. Focus on developing field-deployable systems for environmental monitoring or on-site food testing, an underpenetrated application. A flexible instrument leasing and reagent rental model provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component manufacturers and niche software developers focused on chromatography data systems. The market offers long-term viability, underpinned by increasing regulatory mandates for analytical validation in biopharmaceuticals. Target acquisition archetypes include companies with proprietary microfluidics technology or advanced AI capabilities for data processing. A significant signal to watch is the acceleration of regulatory harmonization in emerging biopharmaceutical R&D hubs like India and Brazil.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: 2D-Liquid Chromatography System | This offers enhanced resolution for complex biological mixtures in proteomics research. |
| Strategic Partnership: AI Software Developer | This automates method development and streamlines data analysis for laboratory workflows. |
| Geographic Expansion: India and Brazil | This addresses unmet demand in emerging biopharmaceutical R&D hubs with harmonizing standards. |
| Capacity Expansion: High-Purity Solvents | This mitigates supply chain volatility for critical consumables used in analytical separations. |
| Technology Licensing: Microfluidics Platforms | This enables miniaturization of systems for new field-deployable and point-of-care applications. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. Interviews with R&D scientists, quality control managers, instrument procurement specialists, and regulatory affairs experts provided critical market insights. This primary data was triangulated with secondary sources, including FDA and EMA regulatory filings, industry association reports, and scientific publications. A bottom-up and top-down approach ensured comprehensive market sizing and validation.
Rate-of-change decomposition analyzed market growth by volume, price, and product mix across the analysis window. The market was segmented by product type, technology, application, end-user, and key geographic region. Compound annual growth rates were derived from historical trends and projected based on anticipated industry shifts. Key forecast inputs included biopharmaceutical R&D expenditure and evolving food safety regulatory frameworks.
Caveats apply where major regulatory changes, unforeseen technological breakthroughs, or significant supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions documented at the time of publication. A model refresh is warranted upon material change in biopharmaceutical R&D funding cycles or global trade policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Dynamic Light Scattering (DLS) Measure Instrument Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Hydrometer Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Melting Point Apparatus Market