
 Global Ion Chromatography Market | 2026-2036
Global Ion Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ion Chromatography Market Foresight
Germany's precision instrumentation corridor is rewriting competitive dynamics for ion chromatography supply. Thermo Fisher Scientific leverages its captive detector manufacturing to sustain margin control across conductivity and mass spectrometry configurations. Shimadzu Corporation anchors Asia-Pacific demand through dedicated high-performance ion chromatography R&D facilities in Kyoto. Metrohm AG dominates Swiss-engineered suppressed systems, competing on titration-to-chromatography integration.
Ion chromatography separates ionic and polar species using ion-exchange resins, typically achieving detection limits below parts-per-billion through suppressed conductivity detection. The technique serves regulatory compliance in pharmaceutical counterion analysis and environmental anion monitoring. Suppressed ion chromatography leads instrument value pools due to its sensitivity advantages in trace-level water quality applications. Mass spectrometry detection represents the fastest-expanding technology segment as laboratories seek structural confirmation beyond retention time matching. Environmental monitoring agencies occupy a mature but stable demand channel tied to watershed compliance mandates.
The US EPA enforces Method 300.1 for drinking water disinfection byproduct analysis, directly shaping anion exchange system procurement specifications. EU REACH and the F-Gas Regulation constrain mobile phase chemistry options, forcing manufacturers to reformulate eluent generators. Japan's PMDA and METI coordinate pharmacopeial ion analysis standards that govern export acceptance for active pharmaceutical ingredients. Stakeholders must monitor evolving PFAS detection protocols across EPA and ECHA frameworks, as these emerging contaminant methods will determine next-generation column and suppressor investments.
Market Dynamics
Suppressed conductivity detection is migrating from laboratory benchtops to portable field units, compressing the addressable instrument base while expanding serviceable test locations. Pharmaceutical quality control laboratories now demand simultaneous anion-cation analysis, forcing manufacturers to reconfigure eluent generation architectures. Environmental agencies in Germany, the United States, and Japan are synchronizing PFAS detection protocols, creating specification convergence pressure on column chemistry suppliers.
Growth Catalysts
- EPA Method 300.1:The US EPA's drinking water disinfection byproduct mandate drives anion exchange system replacement cycles in municipal laboratories. Municipal water authorities must upgrade legacy systems to achieve parts-per-billion detection thresholds.
- Pharmaceutical counterion verification:Active pharmaceutical ingredient manufacturers require ionic purity documentation for export acceptance under Japan's PMDA and METI pharmacopeial standards. This creates instrument pull across quality control facilities.
- Swiss precision manufacturing clusters:Suppressed system production concentrates around Basel and Zurich, enabling rapid prototyping of titration-chromatography integrated platforms for European chemical laboratories.
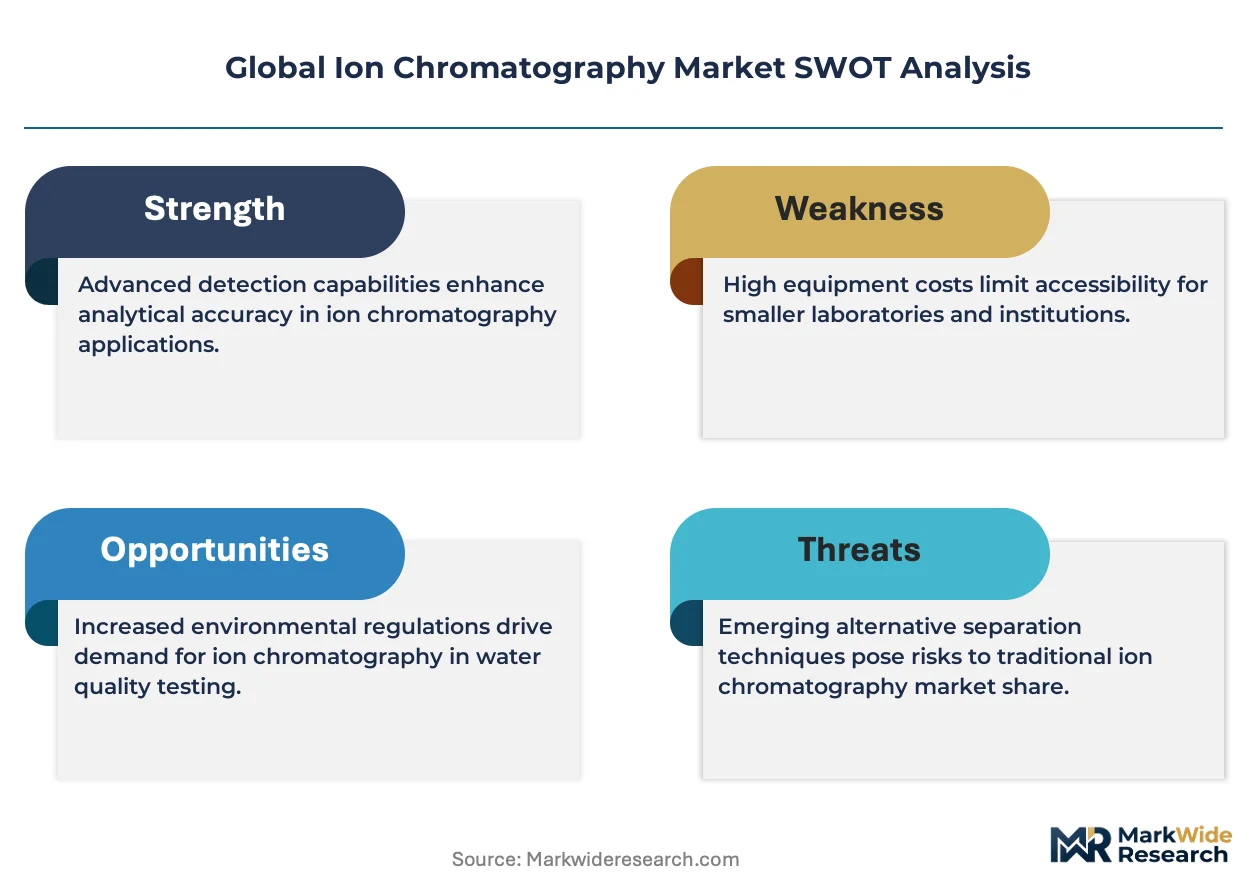
Market Restraints
- Helium supply volatility:Mass spectrometry detection configurations depend on helium carrier gas, with price instability constraining method transfer decisions in contract research organizations.
- Eluent chemistry constraints:EU REACH and the F-Gas Regulation restrict hydrofluorocarbon-based mobile phase formulations, forcing reformulation investments that compress manufacturer margins.
- Capillary ion chromatography substitution:Miniaturized capillary systems achieve equivalent sensitivity with reduced sample volumes, threatening standard-bore instrument replacement demand in academic research settings.
Strategic Opportunities
- India pharmaceutical export corridor:CDSCO and DGFT alignment with ICH Q3D elemental impurity guidelines creates instrument demand in Hyderabad and Mumbai quality control clusters.
- IC-MS convergence:Ion chromatography-mass spectrometry hyphenation enables structural confirmation beyond retention time matching, opening pharmaceutical metabolite identification workflows.
- Service contract unbundling:Preventive maintenance and column subscription models displace traditional capital purchase structures in mid-sized environmental testing laboratories.
Industry Challenges
- Suppressor membrane fabrication expertise:Perfluorinated membrane production requires specialized polymer chemistry knowledge concentrated in limited supplier bases, constraining vertical integration options.
- Multi-instrument data integration:Chromatography data systems must interface with laboratory information management platforms across heterogeneous vendor environments, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ion Chromatography Market |
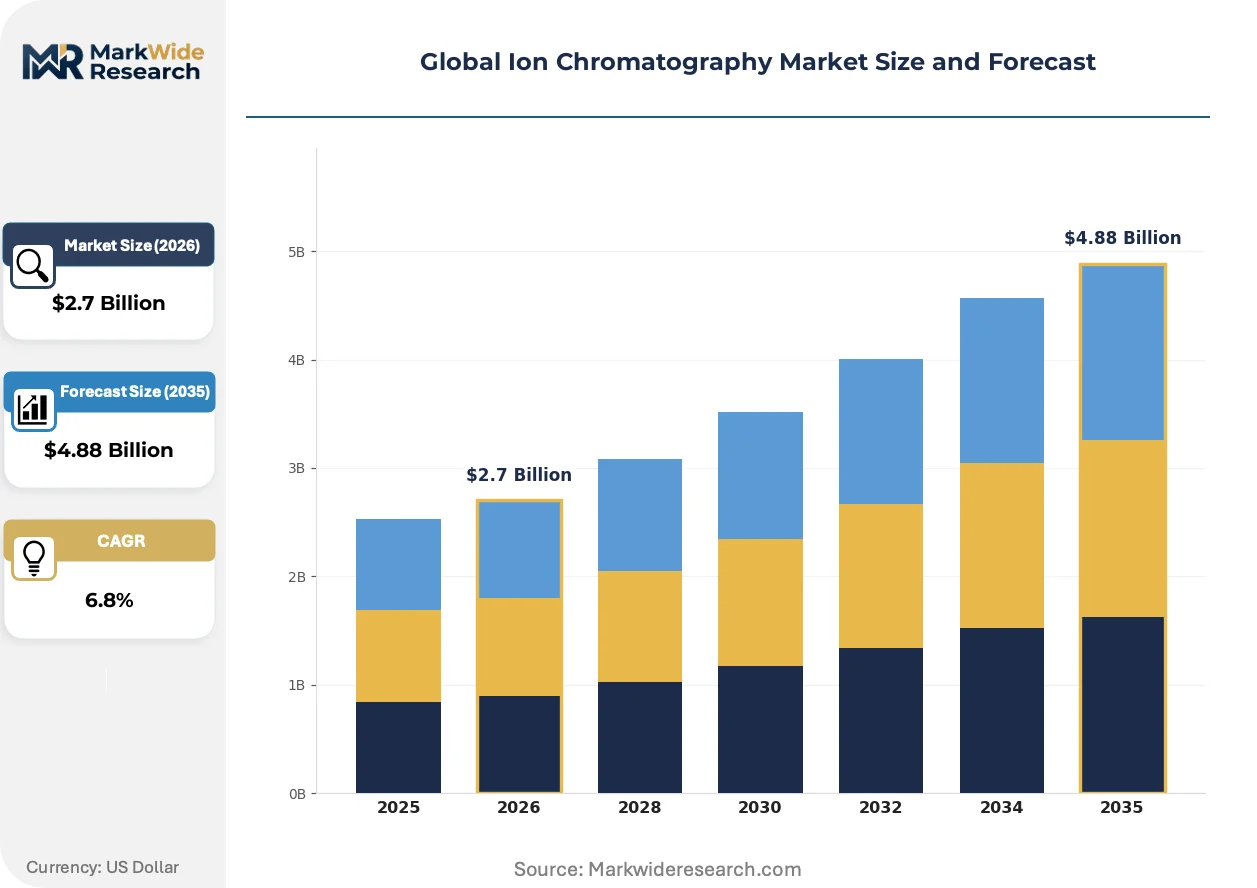
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anion Exchange Chromatography, Cation Exchange Chromatography, Suppressed Ion Chromatography, Non-Suppressed Ion Chromatography, High-Performance Ion Chromatography Technology: Conductivity Detection, Electrochemical Detection, UV-Visible Detection, Mass Spectrometry Detection, Refractive Index Detection Application: Pharmaceutical Analysis, Environmental Testing, Food & Beverage Quality Control, Chemical Analysis, Water Quality Monitoring End User: Research Institutes, Quality Assurance Labs, Chemical Manufacturing Facilities, Food Testing Laboratories, Environmental Monitoring Agencies |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Shimadzu Corporation, Metrohm AG, Waters Corporation, Bio-Rad Laboratories, PerkinElmer, Danaher Corporation, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ion Chromatography Market Shifts & Advancements
Eluent generation technology is eliminating manual preparation protocols, reshaping laboratory staffing models and consumable revenue structures. Three concurrent developments are compressing instrument lifecycles while expanding application breadth.
Reagent-free ion chromatography is migrating from early-adopter pharmaceutical laboratories to routine environmental monitoring stations. Municipal water authorities in California and Bavaria are deploying automated eluent generation systems to reduce operator exposure to concentrated acids and bases. This capability compression enables 24-hour unattended operation while reducing per-sample labor allocation by half.
ECHA's evolving PFAS restriction proposal is forcing column manufacturers to validate new stationary phase chemistries for ultra-short-chain perfluorinated compound separation. Industrial laboratories in the Rhine-Ruhr chemical corridor are pre-qualifying alternative suppressor architectures ahead of anticipated method publication. The environmental testing segment is absorbing the highest compliance burden, with watershed monitoring agencies deferring non-essential capital purchases until protocol finalization.
Service unbundling is fragmenting the traditional capital-equipment-plus-consumables bundle. Contract research organizations in Research Triangle Park and Cambridge are negotiating column subscription arrangements separate from instrument leases. This preference shift is most visible in North American pharmaceutical outsourcing, where procurement functions now benchmark total cost-per-sample rather than capital expenditure metrics.
Global Ion Chromatography Market Segmentation
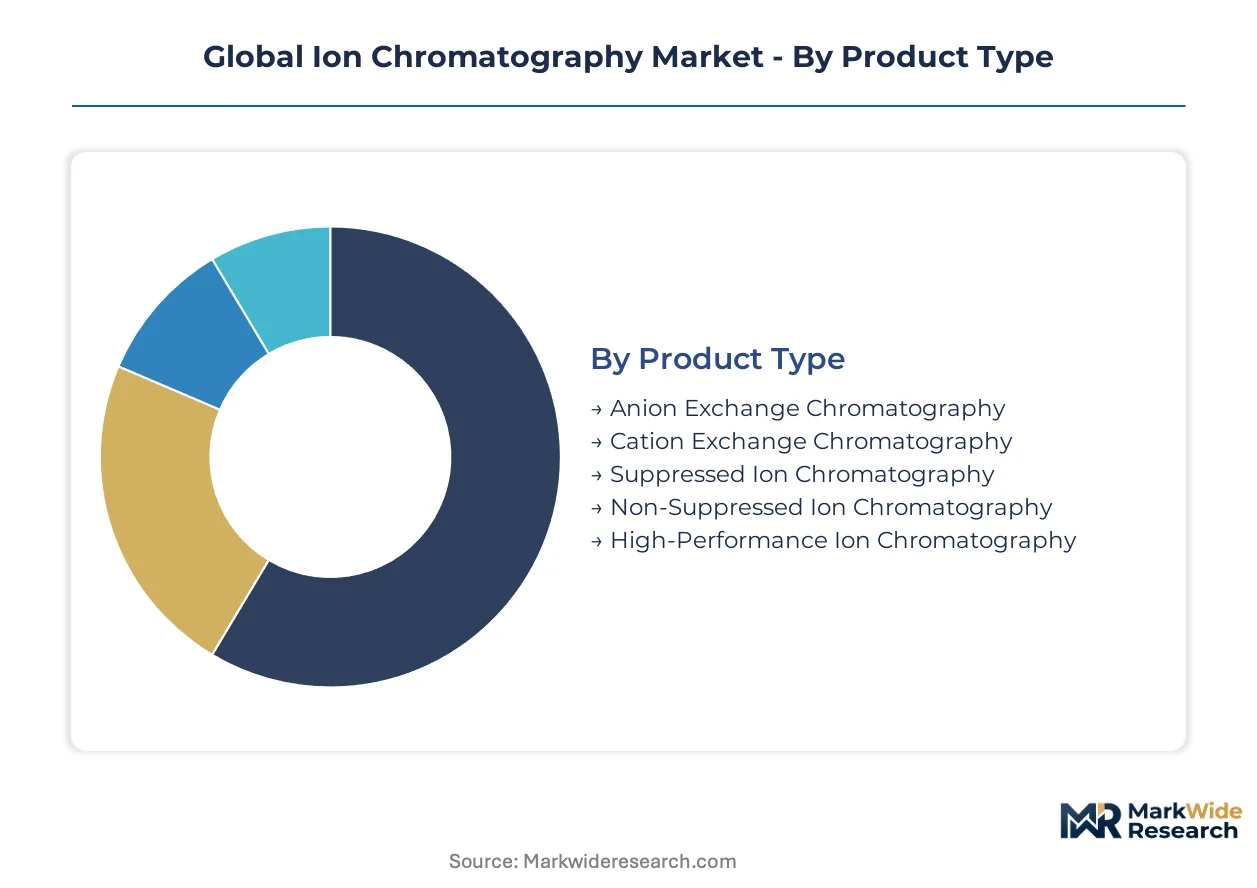
Segmentation in ion chromatography reveals how technical specifications align with regulatory mandates and end-use economics. Product architecture, detection technology, application domain, and user facility type each shape procurement patterns and service contract structures differently.
Product Type:
The use-case spectrum spans routine quality control to trace-level regulatory compliance, with suppression technology determining sensitivity thresholds and capital intensity.
- Suppressed Ion Chromatography:Employs membrane-based or chemical suppressors to reduce background conductivity, achieving parts-per-billion detection limits required by US EPA Method 300.1 for drinking water disinfection byproduct analysis. German municipal water authorities in Bavaria and North Rhine-Westphalia prioritize these systems for watershed compliance monitoring.
- High-Performance Ion Chromatography:Integrates automated eluent generation with high-pressure pumping architectures, enabling simultaneous anion-cation analysis for pharmaceutical counterion verification. Active pharmaceutical ingredient manufacturers in Basel and Hyderabad deploy these configurations for export documentation under Japan's PMDA standards.
- Anion Exchange Chromatography:Separates negatively charged species using quaternary ammonium stationary phases, serving environmental fluoride and nitrate monitoring.
- Cation Exchange Chromatography:Resolves positively charged ions through sulfonate-functionalized resins, supporting lithium and transition metal analysis in battery material qualification.
- Non-Suppressed Ion Chromatography:Operates without conductivity suppression, offering lower capital cost for educational and preliminary screening applications.
Established volume favors suppressed systems; emerging adoption favors high-performance configurations with integrated mass spectrometry interfaces.
Technology:
Detection modality determines capital allocation, with conductivity-based methods anchoring routine compliance and mass spectrometry commanding premium positioning for structural confirmation.
- Mass Spectrometry Detection:Delivers molecular weight and fragmentation data beyond retention time matching, enabling pharmaceutical metabolite identification and emerging contaminant structural elucidation. Contract research organizations in Research Triangle Park and Cambridge are prioritizing IC-MS hyphenation for regulatory submission packages.
- Conductivity Detection:Measures ionic species through electrical conductivity changes, remaining the workhorse for municipal water authority compliance testing due to operational simplicity and established method libraries.
- Electrochemical Detection:Employs amperometric or pulsed techniques for redox-active species including carbohydrates and sulfides.
- UV-Visible Detection:Targets chromophoric ions and post-column derivatization products in pharmaceutical impurity profiling.
- Refractive Index Detection:Provides universal detection for non-ionic polar species in sugar alcohol and organic acid applications.
Conductivity detection retains the largest installed base; mass spectrometry interfaces are climbing the fastest among new instrument procurements.
Application:
Regulatory stringency varies dramatically across sectors, with environmental mandates driving replacement cycles and pharmaceutical requirements forcing sensitivity upgrades.
- Environmental Testing:Encompasses watershed monitoring, air quality analysis, and soil contamination assessment under evolving PFAS detection protocols. ECHA's restriction proposals are forcing Rhine-Ruhr industrial laboratories to pre-validate alternative column chemistries ahead of method finalization.
- Pharmaceutical Analysis:Covers counterion verification, impurity profiling, and dissolution testing governed by ICH Q3D elemental impurity guidelines. CDSCO alignment with these standards is creating instrument demand in Mumbai and Hyderabad quality control clusters.
- Water Quality Monitoring:Serves municipal treatment facilities and bottled water producers requiring continuous compliance documentation.
- Food & Beverage Quality Control:Addresses nitrate, sulfite, and organic acid monitoring for safety and authenticity verification.
- Chemical Analysis:Supports process control and raw material qualification in petrochemical and specialty chemical manufacturing.
Environmental testing commands the most method-driven capital deployment; pharmaceutical analysis offers the steepest expansion trajectory through export compliance requirements.
End User:
Facility type shapes procurement modality, with research institutes favoring capital purchase and quality assurance labs migrating toward subscription-based consumables models.
- Quality Assurance Labs:Operate within pharmaceutical and chemical manufacturing facilities, demanding 24-hour unattended operation and automated eluent generation to reduce operator exposure. California municipal water authorities are deploying reagent-free systems to compress labor allocation per sample.
- Environmental Monitoring Agencies:Execute watershed compliance mandates tied to EPA and ECHA frameworks, deferring non-essential capital purchases until PFAS protocol finalization.
- Research Institutes:Pursue method development and academic publication, often prioritizing instrument flexibility over throughput specifications.
- Chemical Manufacturing Facilities:Integrate chromatography into process analytical technology for real-time release testing.
- Food Testing Laboratories:Balance multi-residue screening capability with rapid turnaround requirements for perishable goods.
Quality assurance labs concentrate replacement demand; environmental agencies are gaining share fastest through regulatory harmonization across Germany, the United States, and Japan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in precision analytical instrumentation, connecting Basel chemical clusters to Bavarian manufacturing centers and enabling just-in-time delivery of suppressed ion chromatography systems.
Germany
Bavarian municipal water authorities and North Rhine-Westphalia industrial laboratories drive suppressed system procurement for watershed compliance monitoring. EPA Method 300.1 alignment through DIN standard harmonization mandates parts-per-billion detection capability upgrades. The Rhine-Ruhr chemical corridor hosts pre-validation testing for PFAS detection protocols ahead of ECHA method finalization.
United States
California municipal water authorities deploy reagent-free eluent generation systems to reduce operator exposure and enable 24-hour unattended operation. The EPA enforces Method 300.1 for drinking water disinfection byproduct analysis, directly shaping anion exchange system replacement cycles. Research Triangle Park contract research organizations negotiate column subscription arrangements separate from instrument leases.
Japan
Active pharmaceutical ingredient manufacturers in the Kansai region require ionic purity documentation for export acceptance under PMDA and METI pharmacopeial standards. Kyoto hosts dedicated high-performance ion chromatography R&D facilities serving Asia-Pacific demand. The Kanto region concentrates quality control laboratory investment for simultaneous anion-cation analysis capability.
India
Hyderabad and Mumbai quality control clusters generate instrument demand as CDSCO and DGFT align with ICH Q3D elemental impurity guidelines. The country's national pharmaceutical regulator mandates counterion verification for export acceptance of active pharmaceutical ingredients. Gujarat chemical manufacturing facilities integrate chromatography into process analytical technology for real-time release testing.
Switzerland
Basel and Zurich precision manufacturing clusters enable rapid prototyping of titration-chromatography integrated platforms for European chemical laboratories. Swissmedic pharmacopeial standards govern ionic impurity thresholds for pharmaceutical products manufactured for global export. The Swiss-engineered suppressed systems segment competes on integration depth rather than standalone instrument specifications.
Global Ion Chromatography Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in suppressor membrane and column chemistry fabrication. The vendor base stratifies across three tiers: multinational conglomerates with captive detector manufacturing, mid-scale regional specialists with titration integration expertise, and niche component suppliers concentrated in perfluorinated membrane production. Two dominant competitive moves define current positioning: backward integration into suppressor membrane fabrication to secure supply continuity, and service contract unbundling to capture recurring revenue from mid-sized environmental laboratories.
Within the platform integrator tier, Thermo Fisher Scientific leverages captive detector manufacturing for margin control across conductivity and mass spectrometry configurations. Shimadzu Corporation anchors Asia-Pacific demand through Kyoto-based R&D infrastructure. Metrohm AG exemplifies the Swiss precision specialist archetype, competing on titration-to-chromatography integration depth rather than standalone instrument scale.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Shimadzu Corporation |
| Metrohm AG |
| Waters Corporation |
| Bio-Rad Laboratories |
| PerkinElmer |
| Danaher Corporation |
| Mitsubishi Chemical Corporation |
| Others |
Supply & Pricing Matrix
The Rhine-Main-Danube waterway corridor's freight cost dynamics amplify supply concentration effects, enabling Swiss and German manufacturers to sustain premium positioning for suppressed conductivity systems while compressing margins on standard-bore configurations shipped to distant markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IC-MS hyphenated platforms from suppressed conductivity workhorses and non-suppressed educational units. Price differentiation hinges on detection modality certification and after-sales service bundling, with mass spectrometry interfaces commanding substantial premia over conductivity-only configurations. Pricing pressure stems from capillary ion chromatography substitution in academic settings, where miniaturized systems achieve equivalent sensitivity. Municipal water authorities exhibit highest price sensitivity due to budget cycles tied to EPA compliance mandates, while pharmaceutical quality control laboratories prioritize throughput over capital cost.
Supply Chain Analysis
Export control regimes restricting perfluorinated membrane technology limit suppressor component flows from Swiss and Japanese suppliers to emerging market instrument assemblers. Manufacturing concentrates in Germany, Switzerland, and Japan, with perfluorinated membrane production and high-pressure pump fabrication serving as critical inputs. Supply chain risk centers on single-source vulnerability for specialized polymer chemistry knowledge in membrane fabrication. Distribution runs through direct sales teams for pharmaceutical and environmental agency accounts, with channel partners serving academic and smaller contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as municipal water authorities deferred capital purchases during PFAS protocol uncertainty now release pent-up replacement demand for Method 300.1 compliant systems.
For Market Incumbents: Harden suppressor membrane supply continuity through backward integration or captive supply agreements with perfluorinated polymer specialists, as single-source vulnerability threatens production schedules. Deepen service contract unbundling to capture recurring revenue from mid-sized environmental testing laboratories facing compressed capital budgets. Prioritize eluent generator reliability investments to reduce field service dispatch frequency and protect margin structure. For New Entrants and Emerging Players: Portable field-deployable suppressed conductivity units for watershed monitoring agencies in Germany and California represent the most penetrable entry point, as regulatory harmonization creates specification convergence that reduces validation burden. Column chemistry subscription models for North American contract research organizations offer alternative revenue architecture without competing head-to-head on instrument platform development. Target service contract unbundling as primary go-to-market mechanism. For Investors and Strategic Acquirers: ECHA's evolving PFAS restriction proposal reshapes the acquisition landscape by elevating column chemistry validation capabilities above standalone instrument manufacturing scale. Long-term viability favors targets with integrated titration-chromatography platforms and established regulatory submission support infrastructure. Watch for EPA method finalization timing as inflection indicator for environmental testing segment capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Suppressor Membrane Backward Integration | Captive supply of perfluorinated components secures production continuity against single-source polymer chemistry constraints. |
| Eluent Generation Automation | Reagent-free systems reduce operator exposure and enable 24-hour unattended operation for California municipal water authorities. |
| IC-MS Hyphenation Platform Development | Mass spectrometry detection interfaces open pharmaceutical metabolite identification workflows beyond retention time matching. |
| Column Subscription Service Model | Consumables-as-a-service arrangements displace capital purchase structures in Research Triangle Park contract research organizations. |
| PFAS Column Chemistry Pre-Validation | Alternative stationary phase development ahead of ECHA method finalization positions Rhine-Ruhr laboratories for compliance surge. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical quality control directors, municipal water authority laboratory managers, environmental testing procurement leads, and chromatography data systems engineers and refined through secondary validation against EPA Method 300.1 documentation, ECHA restriction proposal drafts, FDA warning letter databases, and ICH Q3D implementation guidance. Bottom-up instrument shipment estimates triangulated with top-down capital expenditure surveys across German, United States, and Japanese end-user facilities.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by product architecture, detection technology, application domain, and end-user facility type plus regulatory compliance tier as industry-specific dimension. CAGRs were derived from replacement cycle analysis and export compliance requirement expansion. Forecast inputs incorporated eluent generator adoption curves and PFAS method development timelines without assuming specific publication dates.
Practitioners should monitor EPA PFAS method finalization, ECHA restriction proposal adoption, and helium supply contract renegotiations for early signals of forecast revision necessity. Forecasts reflect documented assumptions regarding regulatory harmonization pace and instrument lifecycle compression rates. Material shifts in suppressor membrane supply continuity or eluent chemistry regulatory constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Laboratory Accessories Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Pitting Machines Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Global Analytical Standards Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
HPLC Market