
 Magnesium Gluconate Market | 2026-2036
Magnesium Gluconate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Gluconate Market Foresight
The divergence between pharmaceutical-grade and food-grade magnesium gluconate is hardening around purity thresholds and documentation depth. Jost Chemical Co. leverages its USP-grade certification infrastructure to anchor premium contract positions with injectable nutrition suppliers. Global Calcium Pvt. Ltd. competes on bulk powder scale across South Asian dietary supplement channels. Anhui Xingzhou Medicine Food Co., Ltd. differentiates through dual-purpose manufacturing lines that serve both pharmaceutical and food fortification buyers.
Magnesium gluconate is a magnesium salt of gluconic acid, typically containing 5.4% elemental magnesium by weight, synthesized through neutralization of gluconic acid with magnesium oxide or hydroxide. The compound functions primarily as a bioavailable mineral supplement in parenteral solutions, oral dosage forms, and processed food matrices where gastrointestinal tolerance exceeds that of oxide or chloride alternatives. Bulk powder and tablet product types dominate current revenue, though sachet formats are gaining traction in sports nutrition channels where single-serve portability commands shelf space. Pharmaceutical end users sustain the highest margin pools due to stringent compendial compliance costs that filter out commodity producers.
The US FDA enforces Current Good Manufacturing Practice regulations for dietary supplements under 21 CFR Part 111, while China's NMPA administers pharmaceutical-grade mineral salt licensing through drug master file protocols. The European Pharmacopoeia's monograph on magnesium gluconate sets assay and impurity benchmarks that determine CE-marked medical product access. Stakeholders must monitor evolving elemental magnesium labeling rules across multiple jurisdictions, as regulatory divergence between nutritional and pharmaceutical classifications reshapes formulation strategies and certificate-of-analysis requirements.
Market Dynamics
The magnesium gluconate market is bifurcating around purity-grade stratification, with pharmaceutical compendial requirements compressing supplier margins while food-grade commoditization accelerates volume competition. This structural tension is reshaping capital allocation across manufacturing footprints and certification investments.
Growth Catalysts
- Parenteral nutrition expansion:Hospital formulary adoption of magnesium gluconate in total parenteral nutrition bags is accelerating across North American and European acute care networks, driven by superior vein tolerance versus chloride salts.
- 21 CFR Part 111 enforcement:The US FDA's intensified dietary supplement cGMP audits are disqualifying uncertified mineral salt suppliers, consolidating demand toward documented USP-grade producers with established drug master files.
- Shandong province cluster effects:China's concentrated bulk chemical infrastructure in Shandong is capturing economies of scale in gluconic acid precursor supply, lowering conversion costs for regional magnesium gluconate output.
Market Restraints
- Magnesium oxide feedstock volatility:Refinery-grade magnesium oxide pricing fluctuates with Chinese environmental inspection cycles, transmitting cost instability downstream to gluconate manufacturers without long-term offtake contracts.
- European Pharmacopoeia compliance burden:The EP monograph's heavy metal and assay specifications require dedicated analytical equipment investments that exclude smaller chemical traders from CE-marked medical product supply.
- Chelated magnesium substitution:Magnesium glycinate and bisglycinate formats are capturing premium oral supplement shelf space through superior bioavailability marketing, pressuring gluconate's position in direct-to-consumer channels.
Strategic Opportunities
- Sports nutrition sachet formats:Single-serve powder sticks are commanding expanded retail space in US specialty nutrition channels, creating white space for magnesium gluconate formulations targeting cramp prevention and recovery positioning.
- India's PLI scheme for APIs:The Indian government's production-linked incentive framework for active pharmaceutical ingredients offers capital subsidy pathways for domestic magnesium gluconate manufacturing to replace Chinese import dependency.
- Clean label mineral fortification:Processed food manufacturers are reformulating away from magnesium oxide toward gluconate for improved taste masking in plant-based dairy alternatives and functional beverages.
Industry Challenges
- Analytical chemist scarcity:Compendial-grade assay validation and impurity profiling require specialized chromatography expertise that commands premium salaries in competitive pharmaceutical labor markets.
- Dual-use facility validation:Manufacturers operating both pharmaceutical and food-grade lines face extended changeover protocols and segregated storage requirements that compress asset utilization rates.
- Certificate of analysis standardization:Divergent elemental magnesium reporting conventions between USP, EP, and FCC specifications create documentation friction for multi-jurisdictional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Gluconate Market |
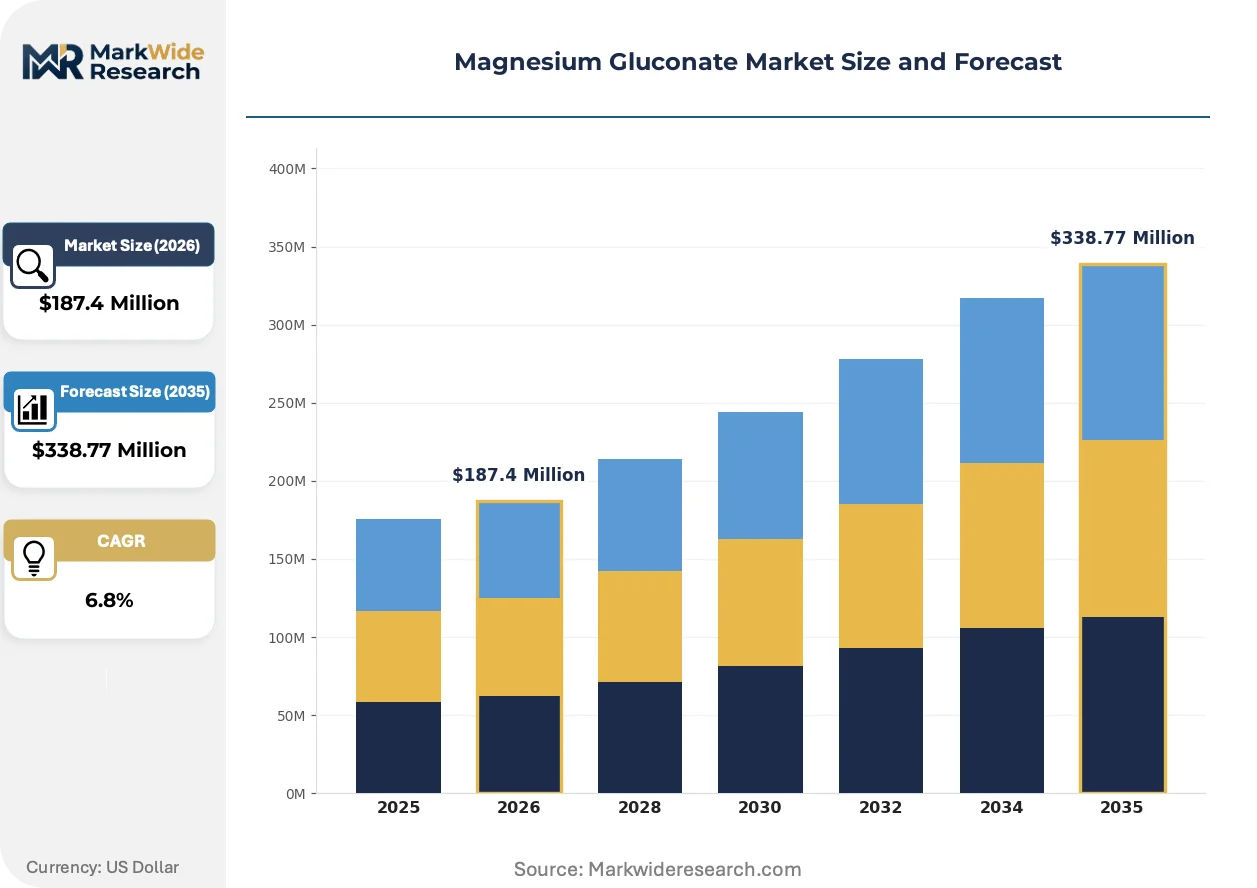
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Powder, Capsules, Tablets, Sachets End User: Pharmaceuticals, Dietary Supplements, Food Industry, Animal Feed Application: Health Supplements, Sports Nutrition, Nutritional Fortification, Medical Use Form: Liquid, Solid, Granule, Crystalline |
| Companies Covered | Jost Chemical Co., Global Calcium Pvt. Ltd., Anhui Xingzhou Medicine Food Co., Ltd., Shandong Xinhong Pharmaceutical Co. Ltd., Liaoyang Fuqiang Food Chemical Co. Ltd., Santa Cruz Biotechnology, Inc., Nantong Feiyu Fine Chemical Co. Ltd., Reephos Chemical Co., Ltd., Anhui Xingzhou Pharmaceutical-Food Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Gluconate Market Shifts & Advancements
Continuous manufacturing technologies and real-time release testing are reshaping how magnesium gluconate producers balance compendial compliance against unit economics. These shifts are compressing traditional batch-cycle timelines while elevating quality system investments.
Direct compression-grade magnesium gluconate granules are absorbing tableting line demand from conventional powder blends. Contract manufacturers serving generic pharmaceutical clients are adopting these pre-processed formats to eliminate in-house granulation steps. The technology is absorbing capital that previously flowed toward conventional fluid bed processing equipment, consolidating supplier relationships around integrated excipient-mineral compounders.
REACH registration requirements for gluconic acid derivatives are tightening substance volume tracking across European supply chains. The regulation is forcing importers to establish orlonly representative structures for tonnage band compliance. Pharmaceutical-grade magnesium gluconate destined for EU medical device and drug applications is most affected, with distributors restructuring logistics to segregate REACH-registered from non-registered inventory streams.
Hospital procurement consortia are consolidating mineral salt purchasing through centralized formulary committees. Group purchasing organizations are displacing direct manufacturer relationships for parenteral nutrition components, compressing supplier margins in exchange for multi-year volume commitments. This concentration is most visible in US integrated delivery networks, where standardized magnesium gluconate specifications are reducing SKU proliferation across member facilities.
Magnesium Gluconate Market Segmentation
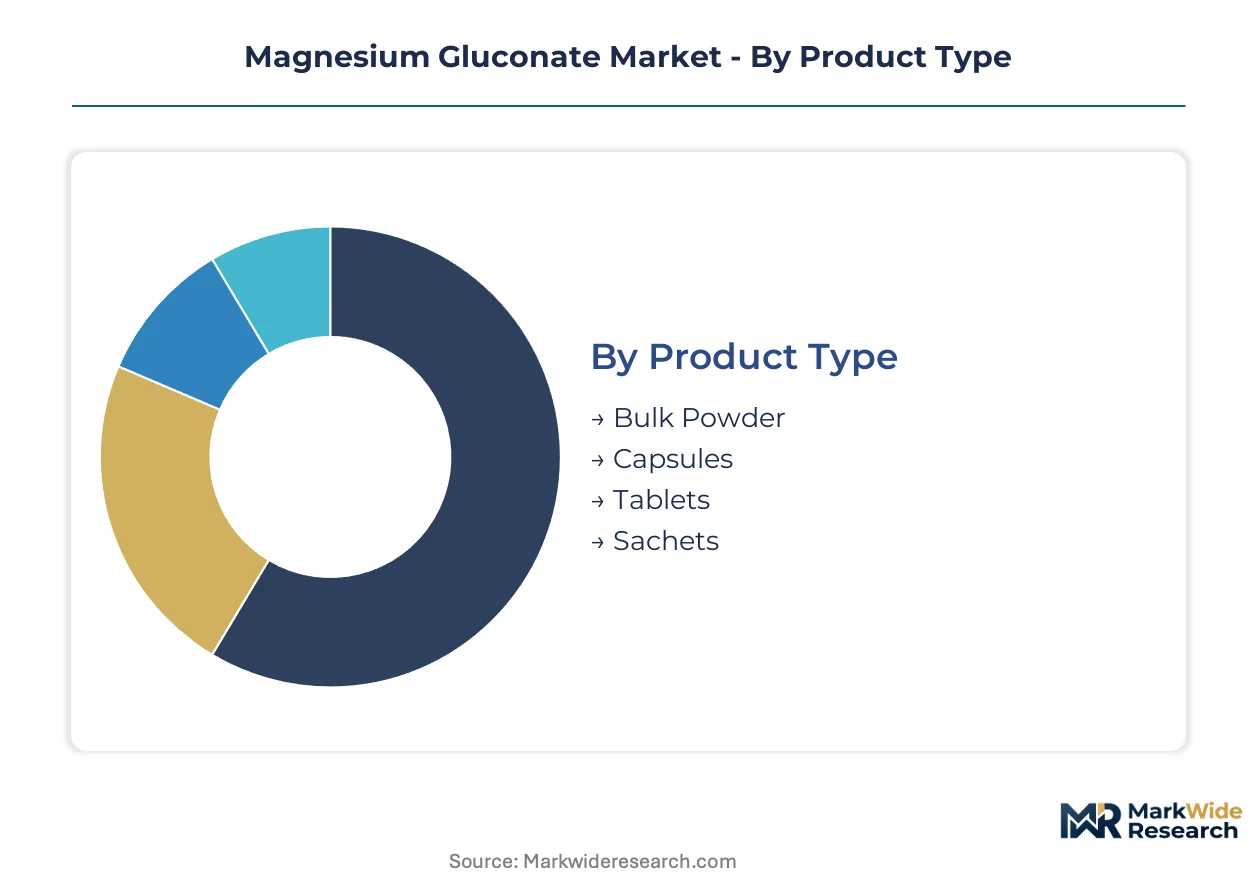
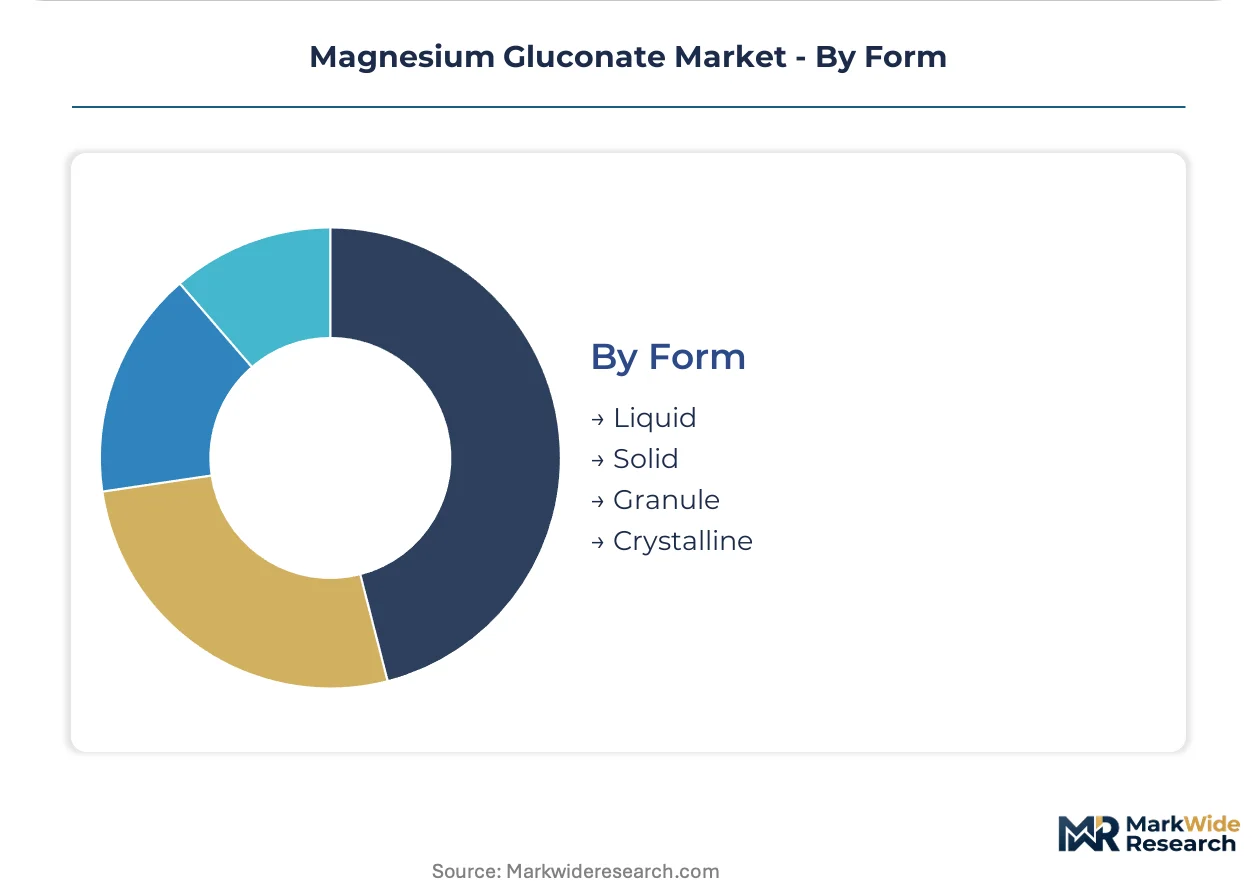
Magnesium gluconate segmentation reflects divergent purity requirements and integration depths across pharmaceutical compendial systems versus standalone consumer formats. Suppliers configure production lines around either embedded parenteral nutrition supply or direct-to-patient oral delivery, with minimal overlap in equipment and certification.
Product Type:
Bulk powder serves as the foundational feedstock for downstream formulation, while tablets and sachets represent progressively deeper integration into finished dosage forms.
- Bulk Powder:Unprocessed magnesium gluconate with standard particle size distribution serves contract manufacturers and compound pharmacies. Demand concentrates in Shandong province chemical clusters where gluconic acid precursor supply lowers conversion costs for regional output.
- Tablets:Direct-compression formats incorporating binders and disintegrants target oral supplement channels. US specialty nutrition retailers are consolidating shelf space around immediate-release coated tablets for magnesium deficiency positioning.
- Capsules:Powder-filled gelatin or HPMC shells accommodate taste-sensitive consumers seeking precise dosing flexibility.
- Sachets:Single-serve powder sticks command premium placement in sports nutrition retail.
Bulk powder leads volumes today; sachets are gaining share fastest.
End User:
Customer type determines margin structure, with pharmaceutical buyers demanding certificate-of-analysis depth that commodity channels reject.
- Pharmaceuticals:Injectable-grade magnesium gluconate for total parenteral nutrition requires USP monograph compliance and drug master file documentation. Hospital procurement consortia in the US are consolidating purchasing through group purchasing organizations, compressing supplier margins for multi-year volume commitments.
- Dietary Supplements:Oral dosage forms operate under 21 CFR Part 111 with lighter analytical burdens than pharmaceutical grades. Amazon and direct-to-consumer brands are absorbing volume through private-label contract manufacturing arrangements.
- Food Industry:FCC-grade material fortifies plant-based dairy alternatives and functional beverages where taste masking exceeds oxide salt performance.
- Animal Feed:Technical-grade supply supports livestock mineral supplementation with reduced documentation requirements.
Pharmaceuticals command highest unit margins; dietary supplements drive absolute volume expansion.
Application:
Use-case positioning determines formulation complexity and regulatory pathway, from disease-state medical claims to general wellness marketing.
- Medical Use:Parenteral nutrition bags and prescription oral solutions require compendial-grade material with validated stability data. European hospital networks are standardizing magnesium gluconate specifications across integrated delivery systems to reduce formulary proliferation.
- Sports Nutrition:Cramp prevention and recovery positioning targets endurance athletes through electrolyte replacement formulations. Specialty retailers in Germany and the US are expanding single-serve format shelf space for gym and event distribution.
- Health Supplements:General wellness positioning for magnesium deficiency correction competes with glycinate and citrate alternatives.
- Nutritional Fortification:Processed food integration requires heat-stable, low-hygroscopic grades for UHT beverage and baked good applications.
Medical use anchors premium pricing; sports nutrition shows steepest expansion trajectory.
Form:
Physical state dictates packaging, stability, and handling requirements across the value chain.
- Solid:Powder and compressed formats dominate tablet and capsule manufacturing with standard excipient compatibility.
- Liquid:Aqueous solutions for parenteral and pediatric oral applications require sterile processing and amber glass or blow-fill-seal packaging.
- Granule:Intermediate particle size enables direct compression without in-house granulation steps.
- Crystalline:High-purity recrystallized grades satisfy EP monograph heavy metal specifications for CE-marked medical devices.
Solid forms maintain volume leadership; liquid formats are climbing fastest on parenteral nutrition demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists and compendial validation technicians cluster in pharmaceutical manufacturing hubs across China, the United States, Germany, India, and Japan. These workforce concentrations anchor regional production capabilities for magnesium gluconate.
China
Shandong province's bulk chemical infrastructure supplies gluconic acid precursors at conversion cost advantages. The NMPA administers pharmaceutical-grade mineral salt licensing through drug master file protocols that filter out commodity producers. Weifang and Jinan host integrated fermentation-to-salt manufacturing complexes serving both domestic injectable nutrition formulators and export markets.
United States
Hospital procurement consortia and group purchasing organizations consolidate mineral salt purchasing for parenteral nutrition through centralized formulary committees. The FDA enforces 21 CFR Part 111 cGMP regulations that disqualify uncertified dietary supplement suppliers. Missouri and New Jersey house USP-grade certification infrastructure anchoring premium contract positions with injectable nutrition suppliers.
Germany
Specialty sports nutrition retailers expand single-serve sachet shelf space for electrolyte replacement formulations targeting endurance athletes. The European Pharmacopoeia monograph sets assay and heavy metal benchmarks determining CE-marked medical product access. Frankfurt and Hamburg distribution hubs structure REACH-registered inventory streams for pharmaceutical-grade imports.
India
The government's production-linked incentive scheme for active pharmaceutical ingredients offers capital subsidy pathways for domestic manufacturing to reduce Chinese import dependency. The CDSCO regulates pharmaceutical-grade mineral salts through drug master file submissions. Gujarat and Maharashtra chemical corridors attract backward integration investments from dietary supplement contract manufacturers.
Japan
Aging demographics drive hospital formulary adoption of vein-tolerant magnesium salts in total parenteral nutrition bags. The PMDA enforces pharmaceutical-grade mineral salt standards aligned with international compendia. Osaka and Tokyo pharmaceutical clusters maintain dedicated analytical equipment investments for EP-compliant heavy metal specifications.
Magnesium Gluconate Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated market structure. The supplier base stratifies around compendial certification depth versus bulk powder scale. Three archetypes dominate: USP-grade certified specialists with drug master file infrastructure, fermentation-integrated Chinese bulk chemical producers, and dual-purpose manufacturers serving both pharmaceutical and food fortification channels. Competitive moves concentrate on capacity expansion in Shandong province and strategic partnerships with hospital procurement consortia.
Within the certification-specialist tier, Jost Chemical Co. exemplifies premium positioning through USP-grade infrastructure investment. Among Asia-Pacific fermentation-integrated producers, Global Calcium Pvt. Ltd. and Anhui Xingzhou Medicine Food Co., Ltd. occupy positions spanning pharmaceutical and dietary supplement supply. These three entities represent the structural tension between documentation-intensive hospital formulary supply and volume-driven consumer channel competition.
| Leading Market Players |
|---|
| Jost Chemical Co. |
| Global Calcium Pvt. Ltd. |
| Anhui Xingzhou Medicine Food Co., Ltd. |
| Shandong Xinhong Pharmaceutical Co. Ltd. |
| Liaoyang Fuqiang Food Chemical Co. Ltd. |
| Santa Cruz Biotechnology, Inc. |
| Nantong Feiyu Fine Chemical Co. Ltd. |
| Reephos Chemical Co., Ltd. |
| Anhui Xingzhou Pharmaceutical-Food Co., Ltd. |
| Others |
Supply & Pricing Matrix
REACH registration requirements for gluconic acid derivatives gate qualified supply and premium-tier pricing access for pharmaceutical-grade magnesium gluconate destined for EU medical markets. Importers lacking orlonly representative structures face tonnage band compliance barriers that filter out commodity traders and consolidate pricing power among registered specialists.
Pricing Analysis
Bundled certificate-of-analysis documentation and drug master file support command 15-25% premiums over unbundled bulk powder transactions. Three-tier pricing structure across USP-grade, FCC-grade, and technical-grade levels separates hospital formulary suppliers from dietary supplement contract manufacturers and animal feed compounders. Cost compression in food-grade channels is intensifying because Shandong province fermentation capacity expansion outpaces branded ingredient demand. Dietary supplement private-label buyers exhibit highest price sensitivity; parenteral nutrition GPOs prioritize multi-year supply security over unit cost negotiation.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle compendial-grade volume, while chemical distributors manage food-grade and technical-grade flows. China's Shandong province, India's Gujarat corridor, and the US Midwest anchor global magnesium gluconate production, drawing from gluconic acid fermentation, refinery-grade magnesium oxide, and analytical validation equipment inputs. Single-source vulnerability concentrates in Chinese environmental inspection cycles that disrupt magnesium oxide feedstock availability without warning. Distribution runs through hospital procurement consortia for pharmaceutical grades and Amazon-enabled direct-to-consumer brands for supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's concentrated fermentation infrastructure and India's PLI-subsidized API manufacturing incentives, exploiting a 12-18% effective cost differential on capital-intensive compendial compliance.
For Market Incumbents: Anticipate chelated magnesium substitution pressure in oral supplement channels by deepening analytical chemist retention programs and securing exclusive multi-year parenteral nutrition GPO contracts. Prioritize backward integration into gluconic acid fermentation capacity within Shandong province to capture precursor cost advantages and buffer magnesium oxide feedstock volatility.
For New Entrants and Emerging Players: Continuous manufacturing technology with real-time release testing offers a defensible wedge against batch-process incumbents burdened by legacy quality systems. Target India's PLI scheme beneficiaries seeking domestic magnesium gluconate sources to displace Chinese import dependency, leveraging CDSCO drug master file pathways as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Roll-up economics work for USP-grade certification specialists because hospital procurement consolidation is compressing supplier counts and elevating documentation-intensive players. Acquire targets with established European Pharmacopoeia compliance and REACH-registered inventory streams; monitor FDA 21 CFR Part 111 enforcement intensity as the signal for further supplier disqualification and margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gluconic Acid Fermentation | Captures Shandong province precursor cost advantages and insulates against magnesium oxide price volatility. |
| Drug Master File Investment for USP Certification | Qualifies suppliers for hospital GPO contracts that filter out uncertified competitors under FDA enforcement. |
| Continuous Manufacturing Technology Adoption | Compresses batch-cycle timelines and elevates quality system investments against legacy batch competitors. |
| REACH-Only Representative Structure Establishment | Enables EU market access for pharmaceutical-grade tonnage bands that exclude non-registered importers. |
| Sports Nutrition Sachet Format Development | Commands premium retail placement in German and US specialty channels targeting endurance athlete recovery. |
Research Methodology
Bottom-up parenteral nutrition and dietary supplement demand modeling reconciled against top-down gluconic acid fermentation capacity tracking forms the analytical core of this study. Primary interviews with hospital formulary directors, pharmaceutical procurement managers at GPOs, contract manufacturing executives, and regulatory affairs specialists combined with secondary validation from FDA 21 CFR Part 111 enforcement records, NMPA drug master file registries, European Pharmacopoeia monograph revisions, and Shandong province chemical industry customs data. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped magnesium oxide feedstock availability, fermentation-to-salt conversion yields, and compendial certification rates across the projection horizon. Segmentation dimensions modeled include pharmaceutical versus food-grade purity tiers, parenteral versus oral versus fortification applications, and regional regulatory cluster divergence between FDA, EMA, NMPA, and CDSCO jurisdictions. CAGRs derived from fitted growth curves applied to hospital admission trends, sports nutrition retail scan data, and processed food reformulation announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese environmental inspection cycle intensity, chelated magnesium substitution rates in consumer channels, and PLI scheme disbursement timing in India. Forecasts reflect documented assumptions around regulatory enforcement continuity and raw material price band stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Acetum Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Silicone Acrylate Market