
 Octofluoropropane Market | 2026-2036
Octofluoropropane Market Size, Share, and Industry Trends Forecast 2026-2036
Octofluoropropane Market Analytics
Specialty gas distribution networks serving semiconductor and medical buyers is rewriting procurement geography across the octofluoropropane value chain. Linde plc leverages its captive hexafluoropropene precursor supply to control cost positions in high-purity grades. Air Liquide S.A. anchors European medical imaging demand through long-term hospital contracts. Showa Denko K.K. competes aggressively in East Asian electronics etching applications with localized blending capabilities.
Octofluoropropane is a perfluorinated compound with the chemical formula C3F8, manufactured primarily through electrochemical fluorination of hydrocarbon precursors or direct fluorination pathways, yielding a colorless, odorless gas with exceptional chemical stability and a boiling point of minus 36.7 degrees Celsius that serves as a plasma etchant in semiconductor fabrication, a propellant in metered-dose inhalers, and a contrast agent in diagnostic ultrasound. Refrigerants and medical imaging applications dominate current volume flows, with refrigerant demand maturing in mature markets while medical imaging grows fastest on aging demographics and cardiac procedure expansion. Blowing agents retain niche status but carry above-average margins in rigid foam insulation for cold-chain infrastructure.
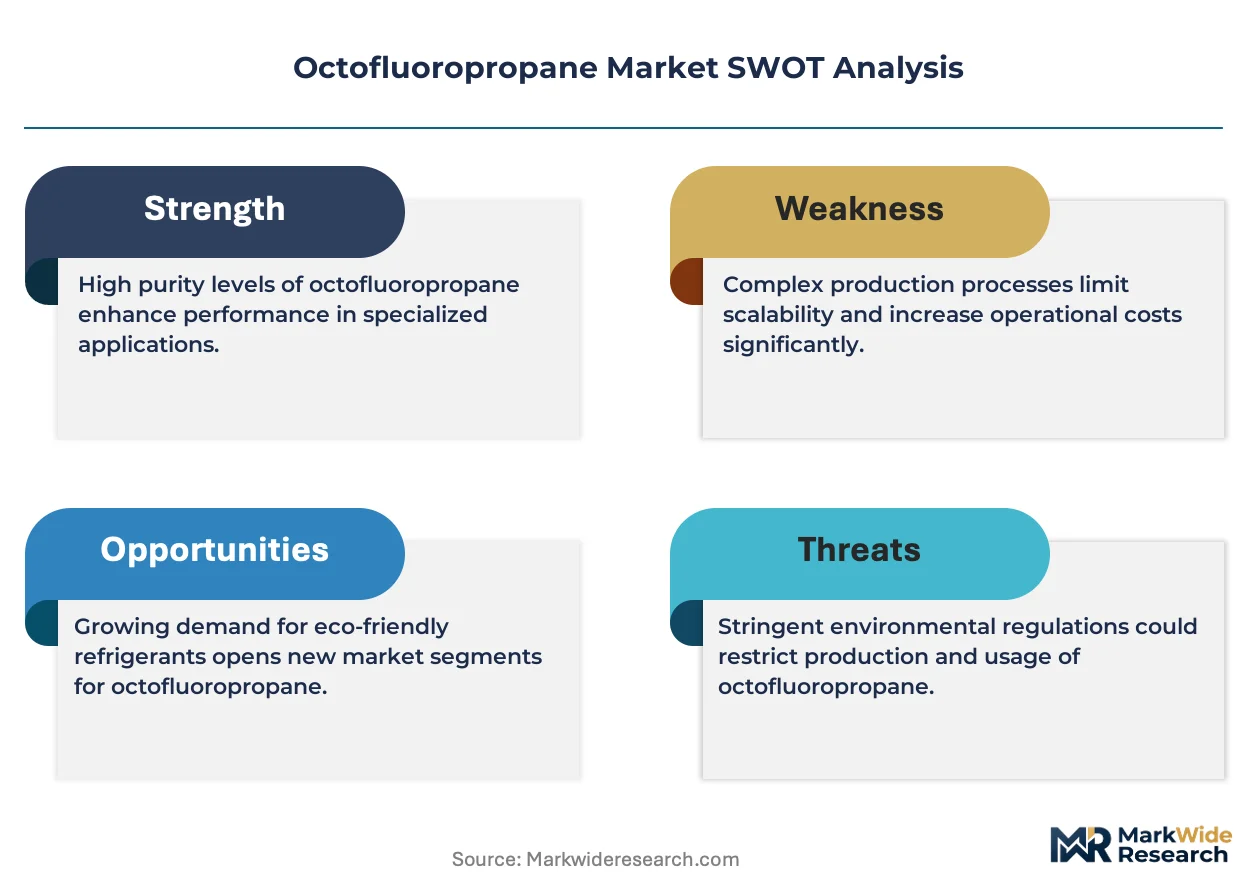
The EPA Significant New Alternatives Policy program restricts octofluoropropane venting in the United States, while the EU F-Gas Regulation mandates phasedown quotas that tighten virgin supply and elevate reclaimed product premiums. Japan's METI enforces parallel reporting requirements under its fluorocarbon lifecycle management framework, creating a triad of compliance architectures that favor suppliers with closed-loop recovery infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where certificate trading, reclamation mandates, or outright bans will reshape product availability and pricing power.
Market Dynamics
The EU F-Gas Regulation phase-down is compressing virgin octofluoropropane availability while semiconductor etching demand concentrates in East Asian manufacturing clusters, forcing buyers toward reclaimed supply chains and captive precursor networks.
Growth Catalysts
- Semiconductor node shrinkage:Advanced logic and memory fabrication below 7nm requires high-purity C3F8 plasma etchants for atomic-layer precision in South Korean and Taiwanese fabs.
- EU F-Gas Regulation reclaimed quotas:Mandatory phase-down of virgin production creates premium pricing for certified-reclaimed product, rewarding closed-loop recovery infrastructure.
- Cardiac ultrasound expansion:Aging demographics in Germany and Japan drive diagnostic procedure volume, expanding microbubble contrast agent consumption in hospital networks.
Market Restraints
- Hexafluoropropene feedstock concentration:Electrochemical fluorination precursors depend on concentrated fluorochemical supply chains in China, exposing cost volatility to export licensing shifts.
- Refrigerant substitution pressure:Hydrofluoroolefins and natural refrigerants displace C3F8 in cold-chain applications, capping volume growth in mature markets.
- EPA venting prohibitions:Significant New Alternatives Policy restrictions on atmospheric release impose recovery infrastructure costs that burden small-scale medical distributors.
Strategic Opportunities
- Indian semiconductor manufacturing:PLI scheme incentives for domestic fab construction create virgin demand for etchant gases as the country builds 28nm and 65nm capacity.
- Closed-loop hospital contracts:Long-term service agreements bundling contrast agent supply with recovery and reclamation lock in recurring revenue streams.
- Dual-use medical-industrial blending:Multi-grade purification infrastructure serves both diagnostic imaging and electronics etching from shared production assets.
Industry Challenges
- Fluorochemical process engineering talent:Electrochemical fluorination expertise concentrates at legacy facilities, constraining capacity expansion at new market entrants.
- Reclamation certification timelines:EU F-Gas Regulation reclaimed product verification requires 12-18 month qualification cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octofluoropropane Market |
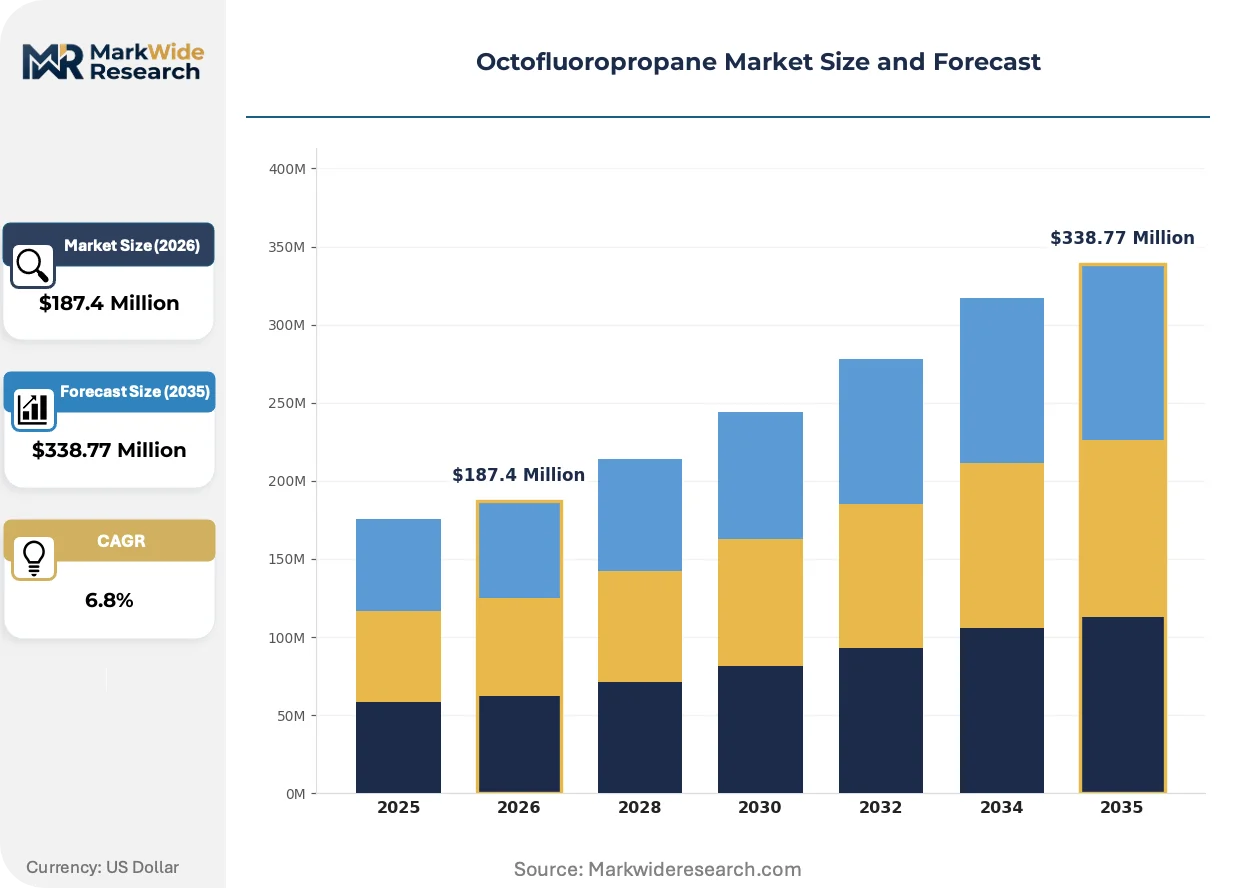
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerants, Aerosols, Solvents, Blowing Agents Application: Refrigeration, HVAC, Medical Imaging, Food Processing End User: Manufacturers, Hospitals, Laboratories, Food & Beverage Distribution Channel: Direct Sales, Online, Wholesale, Retail |
| Companies Covered | Linde plc, Air Liquide S.A., Praxair Technology Inc., Air Products Inc., Showa Denko K.K., Messer Group, Kanto Denka Kogyo Co., Ltd., F2 Chemicals Ltd, Guangdong Huate Gas Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octofluoropropane Market Evolving Landscape
Process intensification and regulatory compliance architectures are reshaping how octofluoropropane is produced, certified, and consumed across medical and electronics value chains.
Plasma etchant purification technology is migrating from batch distillation to continuous membrane separation systems. Semiconductor fabs in South Korea and Taiwan now specify sub-ppb metallic impurity grades that only advanced filtration achieves. This migration from conventional separation is compressing qualification timelines and locking in supplier relationships with integrated purification capabilities.
The EU F-Gas Regulation reclaimed quota system tightens virgin supply access for non-integrated distributors. Industrial gas majors now finance captive recovery networks to secure certified-reclaimed volumes. Medical imaging buyers in Germany and France face extended lead times unless they contract for closed-loop service models.
Hospital procurement departments now bundle contrast agent supply with waste recovery obligations in total-cost contracts. This displaces spot purchasing through independent distributors in cardiac centers across Japan and Germany. The shift concentrates purchasing power with vertically integrated gas suppliers capable of cradle-to-cradle logistics.
Octofluoropropane Market Segmentation
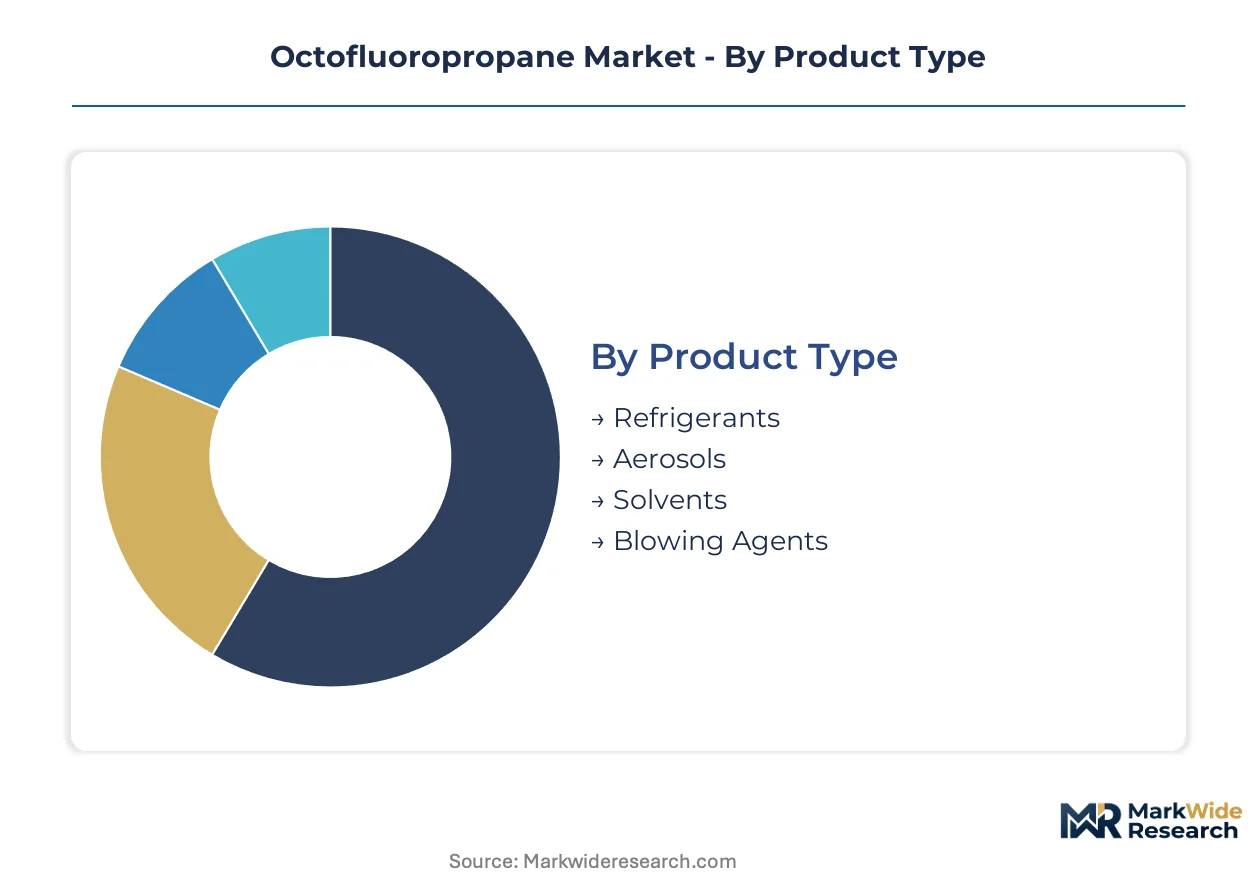
Octofluoropropane procurement patterns diverge sharply across product grades and end-use specifications. Semiconductor fabs demand sub-ppb purity levels that command premium positioning, while medical buyers prioritize certified-reclaimed supply chains under EU F-Gas compliance mandates.
Product Type:
Cost tier differentiation separates commodity refrigerant grades from specialty electronics and medical specifications with tenfold purity premiums.
- Refrigerants:Standard-grade C3F8 serves cold-chain infrastructure and commercial HVAC systems where thermal stability outweighs purity requirements. Mature markets in Germany and Japan face substitution pressure from hydrofluoroolefins as natural refrigerant alternatives gain regulatory preference.
- Aerosols:Propellant-grade octofluoropropane powers metered-dose inhalers for respiratory therapeutics, with FDA and EMA quality certifications mandatory for pharmaceutical applications. Demand concentrates with contract manufacturing organizations serving North American and European drug developers.
- Solvents:Precision cleaning formulations leverage C3F8 chemical inertness for semiconductor component degreasing.
- Blowing Agents:Rigid foam insulation for cold-chain logistics employs octofluoropropane where thermal performance justifies above-average margins.
Refrigerants command the established base. The steepest expansion runs through aerosol propellants.
Application:
End-use functional requirements reshape purification investments and distribution infrastructure across thermal management, diagnostic, and processing workflows.
- Medical Imaging:Microbubble contrast agents for cardiac ultrasound procedures require pharmaceutical-grade C3F8 with batch-level traceability. Aging demographics in Japan and Germany drive hospital procurement volume, with closed-loop recovery contracts displacing spot purchasing.
- Refrigeration:Commercial and industrial cooling systems utilize standard-purity octofluoropropane where regulatory phase-downs under EU F-Gas Regulation tighten virgin supply access.
- HVAC:Building climate control applications face refrigerant substitution as hydrofluoroolefins and natural alternatives capture retrofit demand.
- Food Processing:Cryogenic freezing applications for protein and prepared foods employ C3F8 in blast chilling operations.
Medical imaging commands the established base. The steepest expansion runs through semiconductor etching applications embedded within electronics manufacturing supply chains.
End User:
Customer type determines procurement scale, certification burden, and service model complexity across industrial, clinical, and research environments.
- Manufacturers:Semiconductor fabs in South Korea and Taiwan specify sub-ppb metallic impurity grades for plasma etching at advanced nodes below 7nm. Long-term supply agreements with integrated gas majors lock in volume commitments and captive recovery infrastructure.
- Hospitals:Cardiac centers in Germany, France, and Japan bundle contrast agent procurement with waste recovery obligations under total-cost contracts.
- Laboratories:Research institutions consume small-batch high-purity C3F8 for analytical instrumentation and process development.
- Food & Beverage:Cold-chain operators and protein processors utilize standard grades for cryogenic freezing applications.
Manufacturers command the established base. The steepest expansion runs through hospital networks.
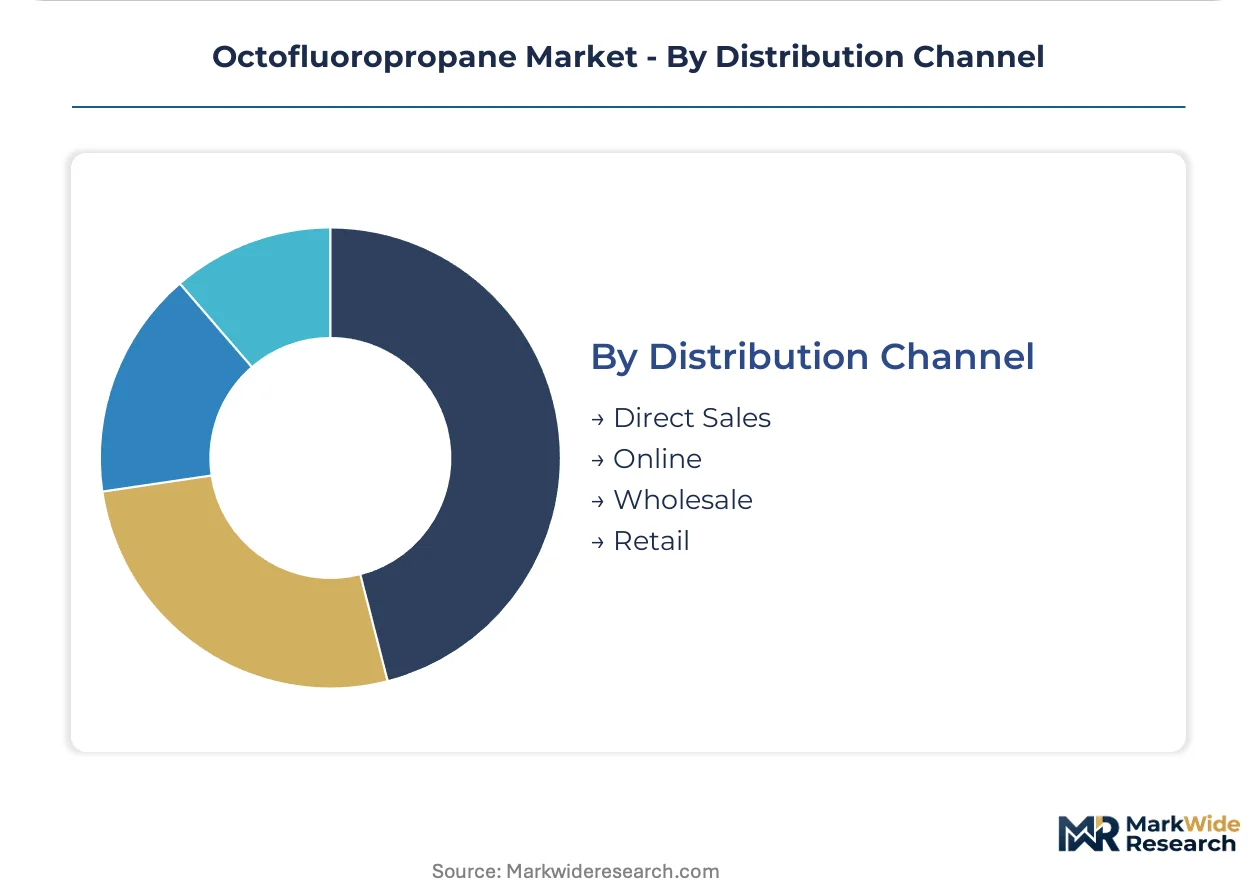
Distribution Channel:
Channel structure reflects buyer scale, geographic concentration, and regulatory compliance requirements for certified-reclaimed product verification.
- Direct Sales:Integrated industrial gas majors serve semiconductor fabs and hospital networks through dedicated account teams managing cradle-to-cradle logistics. Linde plc and Air Liquide S.A. leverage direct relationships to bundle purification, delivery, and recovery services.
- Wholesale:Regional distributors aggregate demand from smaller medical practices and food processing facilities, facing margin compression as EU F-Gas Regulation reclaimed quotas favor vertically integrated suppliers with captive recovery assets.
- Online:E-procurement platforms capture spot demand for standard-grade refrigerants and laboratory quantities.
- Retail:Limited to small-volume aerosol propellant and specialty gas canister sales.
Direct sales command the established base. The steepest expansion runs through wholesale channels consolidating fragmented medical and food processing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical tanker infrastructure anchors European fluorochemical distribution, while East Asian semiconductor clusters depend on specialized gas pipeline networks serving advanced fabrication facilities.
United States
EPA Significant New Alternatives Policy restrictions drive recovery infrastructure investment at semiconductor fabs in Arizona and Texas. The agency's venting prohibitions elevate compliance costs for medical distributors serving cardiac centers. Houston's petrochemical corridor hosts electrochemical fluorination capacity serving domestic refrigerant and electronics etchant demand.
Germany
EU F-Gas Regulation reclaimed quotas compress virgin supply access for hospital networks in Bavaria and Baden-Württemberg. EMA pharmaceutical-grade certification requirements extend lead times for contrast agent procurement. The Rhine-Main industrial cluster concentrates blending and purification infrastructure for medical imaging applications.
China
MIIT dual carbon goals and MEE fluorocarbon lifecycle reporting reshape production economics in the Yangtze River Delta. NMPA pharmaceutical-grade certification enables domestic microbubble contrast agent manufacturing expansion. Zhejiang and Jiangsu provinces concentrate hexafluoropropene precursor capacity serving both refrigerant and electronics supply chains.
Japan
METI fluorocarbon reporting mandates under the Act on Rational Use and Proper Management of Fluorocarbons drive closed-loop recovery adoption at Tokyo and Osaka cardiac centers. PMDA batch-level traceability requirements elevate purification standards for diagnostic applications. The Chubu region's Nagoya industrial corridor anchors high-purity etchant gas production for domestic semiconductor tooling.
South Korea
MFDS pharmaceutical-grade certification enables local contrast agent formulation for aging demographic demand in Seoul and Busan. Government semiconductor industry incentives under the K-Semiconductor Belt initiative expand plasma etchant consumption at Pyeongtaek and Yongin fabrication complexes. The country's fluorochemical import dependency creates strategic stockpiling behavior among integrated gas purchasers.
Octofluoropropane Market Competitive Landscape
On the supply side, the industry is consolidating around integrated industrial gas majors with captive precursor networks and closed-loop recovery infrastructure. Three strategic archetypes dominate: vertically integrated chemical conglomerates controlling hexafluoropropene feedstock, regional specialists with localized blending capabilities, and pharmaceutical-grade purifiers serving diagnostic imaging contracts. Competitive moves center on M&A to secure reclamation assets and capacity expansion in East Asian semiconductor corridors.
Among diversified industrial gas majors, Linde plc and Air Liquide S.A. exemplify the integrated archetype with upstream precursor control and downstream purification infrastructure. Showa Denko K.K. occupies a position representing East Asian specialists competing on localized service models for electronics etching applications. These three anchors illustrate how geographic footprint and feedstock access determine competitive positioning under tightening regulatory phase-downs.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide S.A. |
| Praxair Technology Inc. |
| Air Products Inc. |
| Showa Denko K.K. |
| Messer Group |
| Kanto Denka Kogyo Co., Ltd. |
| F2 Chemicals Ltd |
| Guangdong Huate Gas Co., Ltd |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's chemical tanker infrastructure channels octofluoropropane from Zhejiang precursor facilities to European semiconductor fabs and German hospital networks, with freight cost volatility amplifying price spreads between virgin and reclaimed product tiers as EU F-Gas Regulation quotas tighten supply access.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade microbubble contrast agents from standard refrigerant grades, with sub-ppb semiconductor etchant specifications commanding the widest premiums. Certification under EU F-Gas reclaimed quotas and FDA pharmaceutical-grade standards drives price differentiation alongside purity metrics and captive recovery service bundling. Cost compression in refrigerant tiers is intensifying because hydrofluoroolefins displace C3F8 in cold-chain retrofits. Hospital procurement committees show least price sensitivity due to closed-loop contract structures, while independent medical distributors face acute margin pressure.
Supply Chain Analysis
Export-control regimes on fluorochemical precursors restrict hexafluoropropene flows from Chinese production zones to European and East Asian purification facilities. Supply concentrates in China for electrochemical fluorination feedstock, South Korea for semiconductor-grade blending, and Germany for pharmaceutical certification. Raw material dependencies encompass hexafluoropropene monomer, hydrofluoric acid, and specialized membrane filtration media. Single-source vulnerability runs through concentrated precursor capacity in the Yangtze River Delta. Distribution runs through direct sales networks serving fabs and hospital systems, with wholesale channels consolidating fragmented food processing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, EU F-Gas, and METI compliance architectures fragments procurement patterns into certifiable niches, creating entry points for specialists with reclaimed-product infrastructure or regional purification capabilities.
For Market Incumbents: Insulate core positions by securing captive hexafluoropropene precursor supply through backward integration into Chinese fluorochemical production zones, and by expanding closed-loop recovery infrastructure at South Korean semiconductor corridors to preempt reclaimed-product competition. Hydrofluoroolefin substitution pressure in mature refrigerant markets threatens volume-based margins without service-model differentiation. For New Entrants and Emerging Players: Build out reclamation certification capabilities targeting German hospital networks facing extended lead times under EU F-Gas reclaimed quotas, and establish localized blending operations in India to capture PLI-scheme semiconductor fab demand. The most penetrable white space sits in certified-reclaimed pharmaceutical-grade supply for cardiac ultrasound applications, with go-to-market traction through GPO contracts at Bavarian and Baden-Württemberg hospital systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial gas conglomerates with underutilized fluorochemical purification assets and stranded hospital service contracts. Long-term viability hinges on regulatory phase-down durability rather than virgin capacity expansion. Watch for EU F-Gas Regulation quota tightening velocity as the inflection signal determining reclaimed-product premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive hexafluoropropene access insulates margin positions against Chinese export licensing volatility. |
| Reclamation Asset Acquisition | Closed-loop recovery infrastructure secures EU F-Gas reclaimed quota certification for hospital network contracts. |
| Regional Blending Expansion | Localized South Korean and Indian facilities reduce logistics costs for semiconductor etchant specifications. |
| Long-term Hospital Service Agreements | Bundled contrast agent supply with waste recovery locks in recurring revenue at German cardiac centers. |
| Joint Venture with Fluorochemical Specialist | Partnerships with Zhejiang precursor producers secure feedstock priority during supply disruptions. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor fab gas procurement managers, pharmaceutical contract manufacturing executives, hospital purchasing committee directors, and fluorochemical plant operations leads, and refined through secondary validation against customs trade data, EPA Significant New Alternatives Policy filings, EU F-Gas Regulation quota registries, and SEC disclosures from industrial gas majors. Bottom-up volume triangulation across product grades and end-use segments was cross-checked against top-down market sizing from precursor consumption flows.
Demand-supply-balance modeling across the analysis window incorporated semiconductor node shrinkage trajectories, cardiac ultrasound procedure expansion rates, and refrigerant substitution elasticities. Segmentation dimensions spanned purity grade tiers, end-use applications from medical imaging to electronics etching, packaging formats from bulk tanker to cylinder, and regional regulatory clusters. CAGRs were derived from fitted growth curves calibrated to historical consumption patterns and projected capacity additions. Industry-specific forecast inputs included EU F-Gas phase-down quota schedules and South Korean K-Semiconductor Belt incentive disbursement timelines.
Stress conditions across hexafluoropropene feedstock export restrictions, reclaimed-product certification delays, and hydrofluoroolefin substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology transition rates. Material shifts in EU F-Gas Regulation quota allocation methodology or EPA venting prohibition scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Copovidone Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Phosphatidylcholine Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Sialic Acid Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
Global Molecular Weight Marker Market
Specialty Chemicals
Cellulose Acetate Phthalate Market