
 Europe Chromatography Resins Market | 2026-2036
Europe Chromatography Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chromatography Resins Market Analysis
Biopharmaceutical buyer concentration is consolidating as large contract manufacturers internalize downstream purification operations and reduce vendor counts. Merck KGaA leverages its integrated life sciences platform to supply resin and filtration systems under single procurement contracts. Thermo Fisher Scientific anchors its position through direct service agreements with European CDMOs. Bio-Rad Laboratories competes on specialty affinity chemistries for gene therapy vectors.
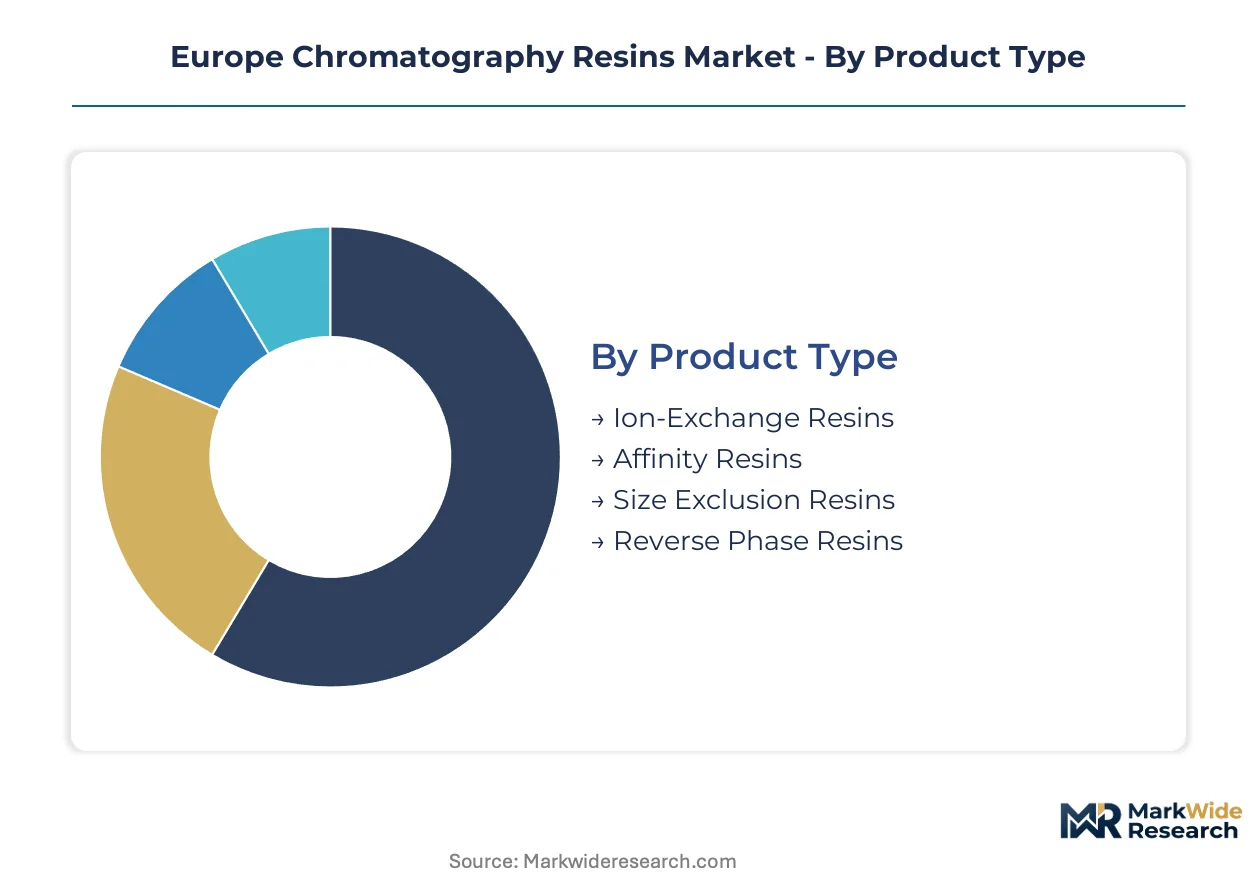
Chromatography resins are porous polymer or silica-based media with controlled pore sizes and surface chemistries, engineered for selective separation of biomolecules based on charge, size, or hydrophobicity. Affinity resins lead European value capture due to protein A ligand premiums in monoclonal antibody purification. Ion-exchange resins represent the highest-volume category as biosimilar manufacturers optimize cost per gram. Size exclusion resins occupy a mature niche in aggregate analysis and final polishing steps.
EMA guidelines on biosimilar comparability and REACH substance restrictions shape resin qualification timelines and chemical composition standards. The EU Green Deal pushes manufacturers toward aqueous-compatible, solvent-reduced production methods. Stakeholders must monitor evolving EMA guidance on continuous bioprocessing and its implications for resin cycling validation requirements.
Market Dynamics
Contract development and manufacturing organizations across Germany, France, and Switzerland are internalizing downstream purification capacity, compressing vendor counts and reshaping resin procurement from spot purchasing toward multi-year framework agreements with integrated suppliers.
Growth Catalysts
- EU Green Deal solvent-reduction mandates:REACH compliance deadlines are accelerating adoption of aqueous-compatible resin chemistries among European biopharmaceutical manufacturers.
- Monoclonal antibody pipeline expansion:Biosimilar developers in Germany's Rhine-Main corridor are scaling protein A affinity resin consumption for commercial purification campaigns.
- Continuous bioprocessing validation:EMA guidance evolution is driving resin cycling qualification programs that extend media lifetime and reduce cost per batch.
Market Restraints
- Protein A ligand supply concentration:Critical ligand production clusters in Denmark and Sweden create single-source vulnerability for European affinity resin manufacturers.
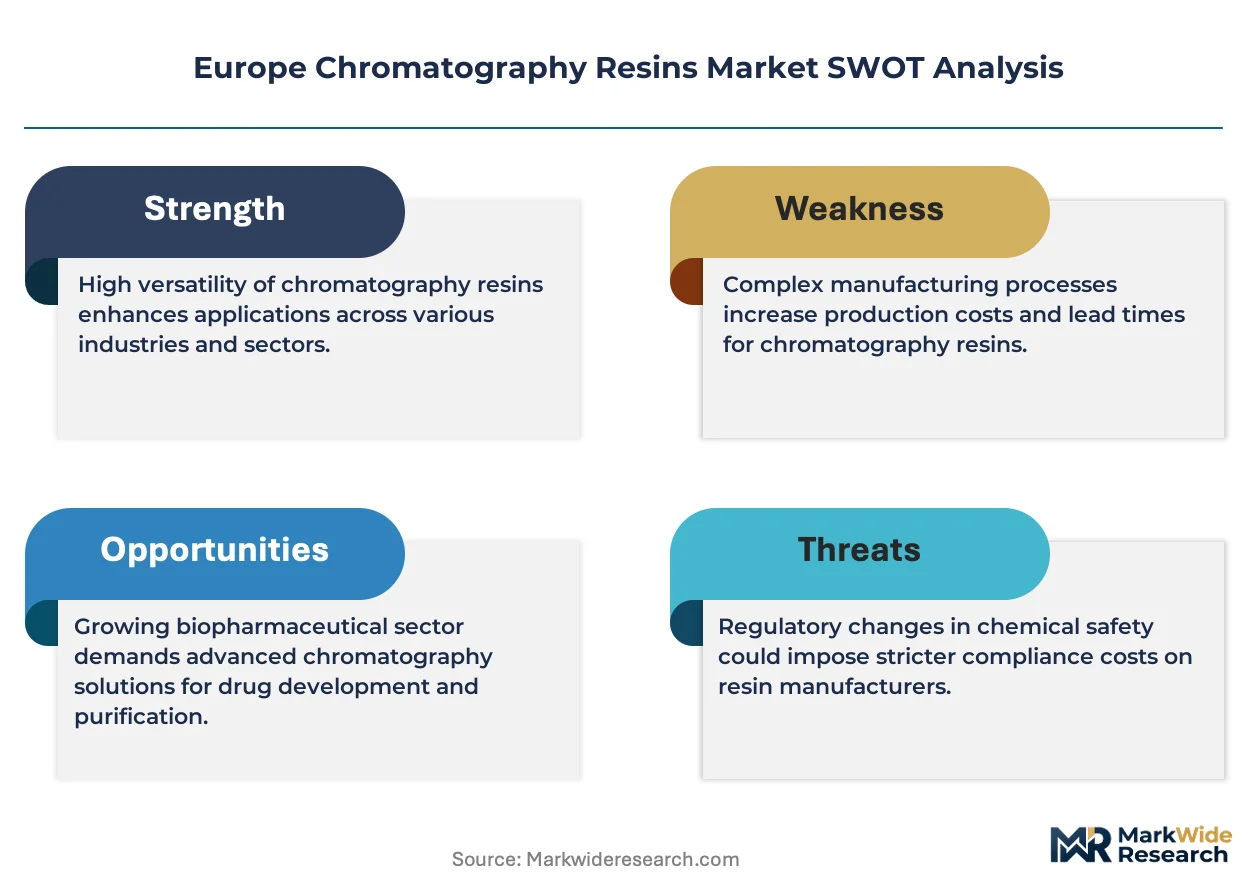
- REACH substance authorization costs:ECHA registration fees and toxicology data requirements impose six-figure barriers on novel resin chemistry commercialization.
- Silica matrix price volatility:Energy-intensive fused silica processing faces input cost pressure from natural gas price fluctuations across German industrial zones.
Strategic Opportunities
- Gene therapy vector purification:Viral vector manufacturers in France and Belgium are establishing dedicated affinity resin specifications for AAV and lentivirus downstream processing.
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive requirements are creating procurement preference for bio-based resin alternatives with verified carbon footprints.
- Single-use chromatography integration:Pre-packed column formats are converging with disposable flow path technologies to reduce cleaning validation burden in multi-product facilities.
Industry Challenges
- Resin lifetime validation under continuous processing:EMA cycling study requirements demand extensive documentation of ligand leaching and binding capacity decay that extends qualification timelines.
- Cross-contamination risk management:Multi-product biologics facilities face complex changeover protocols between monoclonal antibody and gene therapy campaigns using shared purification skids.
- Specialized purification engineering talent:European contract manufacturers report scarcity of process development scientists with expertise in resin selection for novel modality biologics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chromatography Resins Market |
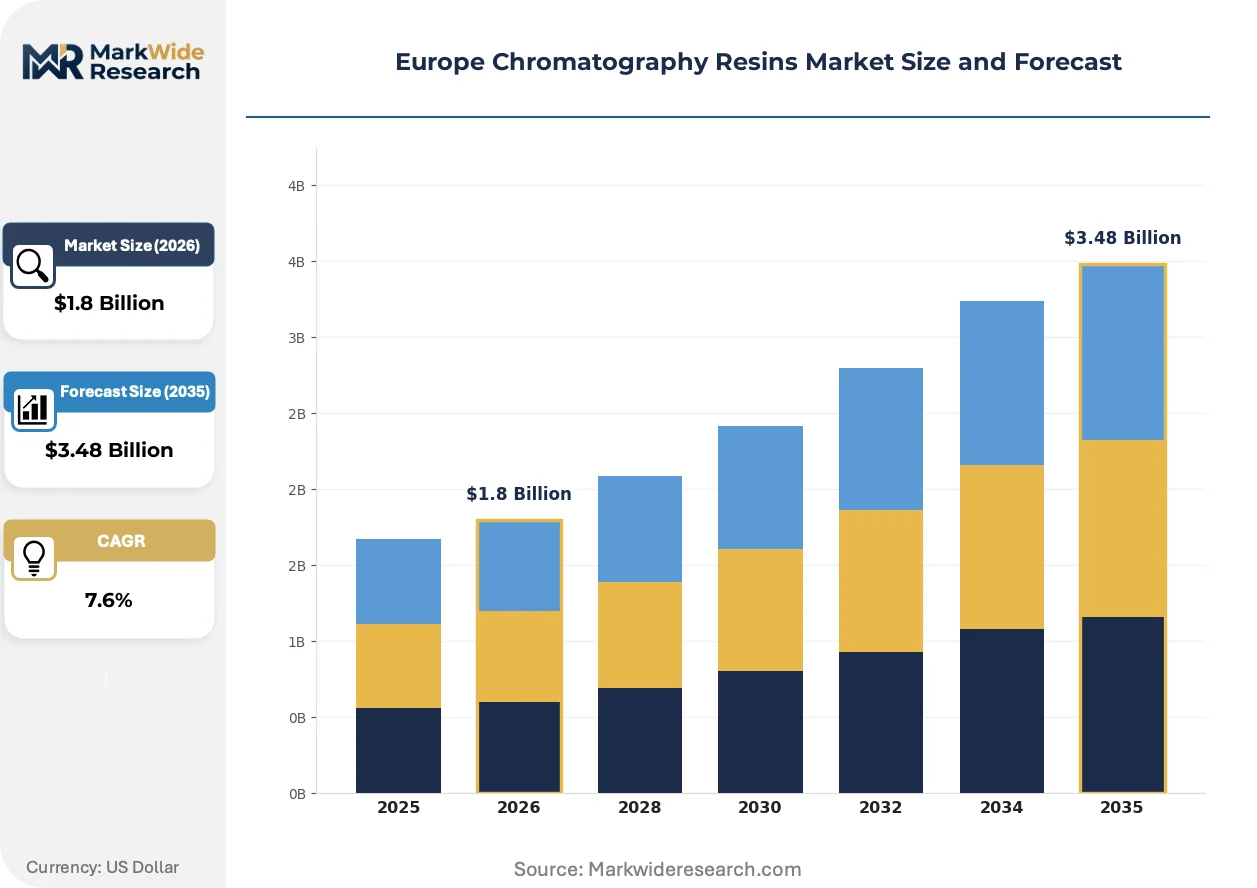
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion-Exchange Resins, Affinity Resins, Size Exclusion Resins, Reverse Phase Resins Application: Biotechnology, Pharmaceutical, Food & Beverage, Environmental Testing End User: Research Laboratories, Contract Research Organizations, Pharmaceutical Companies, Academic Institutions Sales Channel: Online Sales, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, Bio-Rad Laboratories, GE Healthcare, Mitsubishi Chemical Corporation, Dupont, Tosoh Corporation, Purolite Corporation, Avantor, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chromatography Resins Market Emerging Trajectories
Chromatography resin technology is pivoting toward platform standardization and sustainability verification as biopharmaceutical manufacturers consolidate supplier relationships and face Scope 3 emissions accounting requirements.
Multimodal resin chemistries are integrating charge, hydrophobic, and hydrogen-binding functionalities into single ligand architectures. CDMOs in the Netherlands and Belgium are adopting these media for impurity clearance in complex bispecific antibody formats. This convergence is integrating multiple purification steps into single-column operations that compress facility footprint and buffer consumption.
REACH authorization timelines are tightening restrictions on solvent-based resin production methods. ECHA substance evaluation programs are phasing out chlorinated hydrocarbon use in polymer cross-linking reactions. German resin suppliers are responding with aqueous-phase synthesis routes that maintain pore structure control while eliminating volatile organic compound emissions.
Consolidated procurement frameworks are displacing transactional resin purchasing across European biopharmaceutical manufacturing. Large CDMOs in Switzerland and Germany are negotiating multi-year resin supply agreements bundled with technical service and regulatory support. This concentration is most visible in the Rhine-Main biotechnology corridor, where three contract manufacturers now account for a substantial share of regional protein A resin offtake.
Europe Chromatography Resins Market Segmentation
Chromatography resin purchasing decisions in Europe diverge sharply by end-use sophistication, with pharmaceutical manufacturers prioritizing regulatory documentation while research laboratories optimize for catalog breadth and delivery speed. Understanding these segment-specific buying criteria enables suppliers to align product portfolios with distinct qualification requirements and procurement workflows.
Product Type:
Buyers select resin chemistries based on purification complexity and molecule class, with protein A premiums driving affinity category economics and ion-exchange volumes scaling with biosimilar manufacturing expansion.
- Affinity Resins:Protein A ligand-immobilized agarose matrices deliver monoclonal antibody capture with >95% purity in single-step purification. Rhine-Main corridor CDMOs account for concentrated European demand as biosimilar developers scale commercial campaigns under EMA comparability guidelines.
- Ion-Exchange Resins:Positively or negatively charged functional groups separate biomolecules by surface charge distribution at varying pH conditions. German and Swiss biosimilar manufacturers drive the highest European volumes, optimizing cost per gram through resin cycling validation programs.
- Size Exclusion Resins:Porous matrices fractionate molecules by hydrodynamic radius for aggregate analysis and final polishing steps.
- Reverse Phase Resins:Hydrophobic ligands separate compounds based on polarity, serving analytical and preparative peptide purification.
Affinity resins lead on scale; ion-exchange resins lead on momentum.
Application:
Application selection correlates with regulatory burden intensity, with pharmaceutical manufacturing requiring extensive resin qualification documentation versus environmental testing's emphasis on throughput economics.
- Pharmaceutical:Downstream purification of small molecules and biologics demands resin batches with validated extractables profiles and stability data packages. EMA guidelines on biosimilar comparability extend qualification timelines, favoring suppliers with established regulatory support capabilities.
- Biotechnology:Recombinant protein and gene therapy vector production requires specialized affinity chemistries with low ligand leaching. French and Belgian viral vector manufacturers are establishing dedicated resin specifications for AAV downstream processing.
- Food & Beverage:Carbohydrate and vitamin purification employs food-grade ion-exchange matrices with compliance to EU food contact regulations.
- Environmental Testing:Water and soil contaminant analysis utilizes reverse phase and ion-exchange resins for sample preparation and analyte concentration.
Pharmaceutical commands the largest revenue pool; biotechnology exhibits the steepest expansion trajectory.
End User:
End-user type determines procurement channel preference and technical service intensity, with pharmaceutical companies negotiating multi-year framework agreements while academic institutions rely on distributor catalogs.
- Pharmaceutical Companies:In-house biologics manufacturing operations require resin supply security, technical support, and regulatory filing assistance. Large European manufacturers are consolidating vendor counts and internalizing purification capacity, compressing supplier relationships toward integrated platform providers.
- Contract Research Organizations:Method development and early-phase purification services demand rapid resin sampling and flexible batch sizes. CROs across Germany and the Netherlands prioritize suppliers with broad chemistry portfolios and fast delivery logistics.
- Research Laboratories:Discovery-stage protein purification utilizes small-pack affinity and ion-exchange resins with emphasis on catalog availability.
- Academic Institutions:Grant-funded research programs select resins based on price sensitivity and educational discount programs.
Pharmaceutical companies dominate procurement value; contract research organizations are gaining share fastest.
Sales Channel:
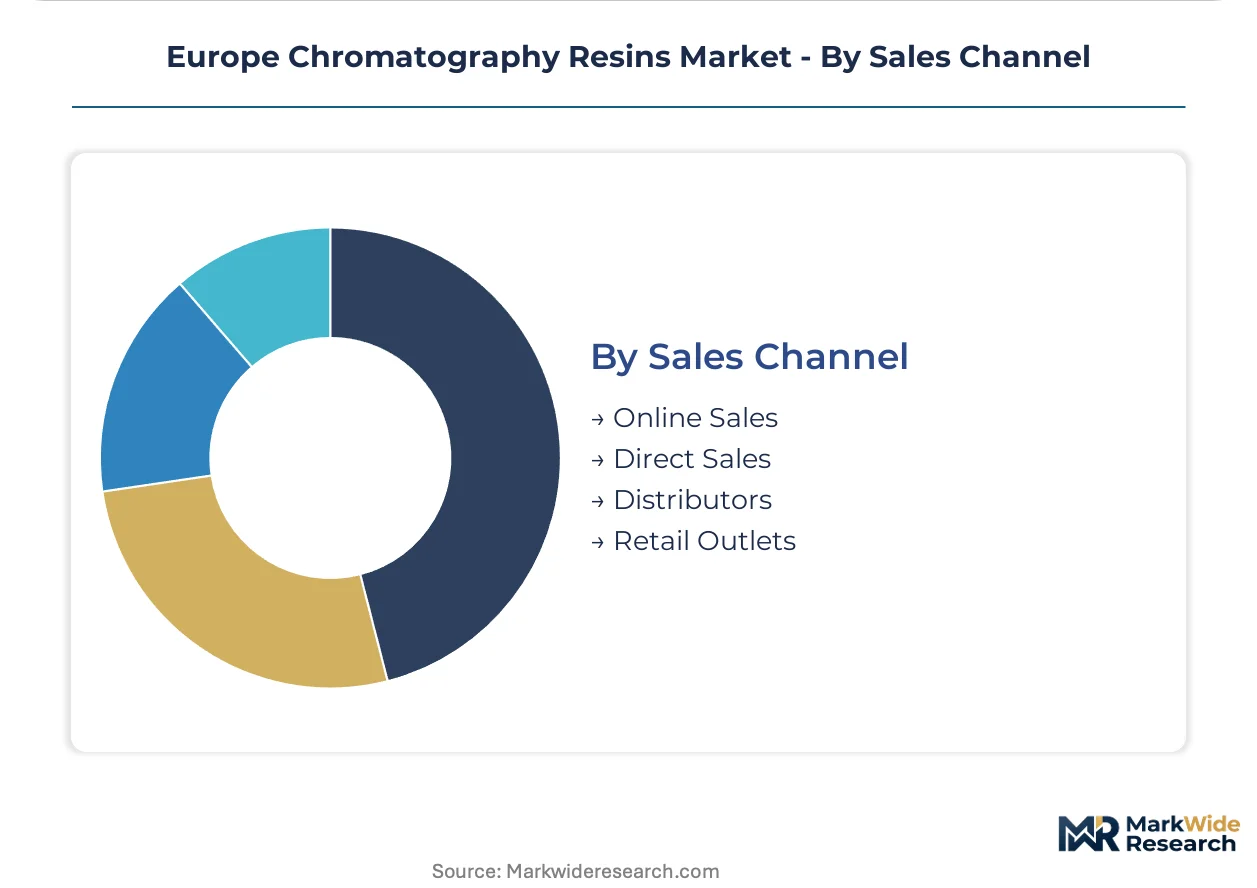
Channel strategy reflects customer scale and relationship complexity, with direct sales capturing pharmaceutical framework agreements and online platforms serving fragmented research demand.
- Direct Sales:Dedicated account teams negotiate multi-year resin supply contracts with technical service bundles and regulatory support. Large CDMOs in Switzerland and Germany favor this channel for protein A resin procurement with guaranteed volume allocations.
- Distributors:Regional warehousing and local technical support serve mid-sized biotechnology companies and research institutions across dispersed European geographies.
- Online Sales:E-commerce platforms with credit card purchasing and rapid delivery serve urgent research laboratory needs and small-volume orders.
- Retail Outlets:Limited presence for chromatography resins due to specialized storage and handling requirements.
Direct sales capture the highest contract value; online sales demonstrate the most rapid channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed base of biopharmaceutical manufacturing capacity, while Switzerland concentrates the highest density of contract development organizations per capita. France and Belgium are emerging as viral vector production hubs. The Netherlands anchors analytical method development expertise.
Germany
Protein A resin consumption dominates as biosimilar developers in the Rhine-Main biotechnology corridor scale commercial purification campaigns. REACH compliance deadlines are accelerating aqueous-compatible chemistry adoption among Frankfurt-area manufacturers. Munich's biotech cluster is internalizing downstream operations that previously outsourced resin procurement.
Switzerland
Contract manufacturers in Basel and Zurich are negotiating multi-year framework agreements with integrated resin suppliers. Swissmedic guidance on continuous bioprocessing is driving resin cycling validation investments. The Basel life sciences corridor accounts for concentrated demand for multimodal purification media.
France
Viral vector manufacturers in Lyon and Paris-Saclay are establishing dedicated affinity resin specifications for AAV downstream processing. ANSM regulations on gene therapy comparability are extending resin qualification timelines. The Lyon biopole is attracting CDMO investment in dedicated gene therapy purification capacity.
Belgium
Lentivirus and AAV producers in Flanders are specifying low-leaching affinity chemistries for clinical-grade vector production. EMA guidelines on advanced therapy medicinal products are shaping resin extractables documentation requirements. The Flanders biotech corridor is consolidating purification vendor relationships toward single-source agreements.
Netherlands
Analytical method development laboratories in Amsterdam and Rotterdam are driving size exclusion resin demand for aggregate analysis. Dutch CDMOs are adopting multimodal resins for bispecific antibody impurity clearance. The Leiden bioscience cluster is pioneering single-use chromatography integration with disposable flow path technologies.
Europe Chromatography Resins Market Vendor Landscape
German producers anchor one tier; Japanese specialists hold established positions in ion-exchange and size exclusion matrices. The vendor base organizes around three strategic archetypes: integrated life sciences conglomerates supplying resin-filtration bundles, mid-sized chemical companies with polymer synthesis expertise, and boutique affinity chemistry specialists. Competitive moves concentrate on multi-year service contracts with European CDMOs and aqueous-phase manufacturing process conversions to meet REACH solvent-reduction mandates.
Among Germany-based suppliers, Merck KGaA exemplifies the integrated platform archetype through its combined resin and filtration system offerings. Thermo Fisher Scientific occupies a position as a North American-headquartered service-intensive supplier with direct agreements across European contract manufacturers. Bio-Rad Laboratories represents the specialty affinity tier, particularly for gene therapy vector applications where ligand specificity commands premium positioning.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| GE Healthcare |
| Mitsubishi Chemical Corporation |
| Dupont |
| Tosoh Corporation |
| Purolite Corporation |
| Avantor |
| Others |
Supply Flow & Price Mechanics
Aqueous-phase synthesis adoption across German resin suppliers is compressing production costs while simultaneously concentrating supply relationships toward integrated platform providers with capital-intensive manufacturing conversions. REACH solvent-reduction mandates are eliminating smaller competitors unable to fund aqueous-compatible chemistry transitions, reshaping procurement toward multi-year framework agreements with guaranteed volume allocations.
Pricing Analysis
Capacity additions in Germany and Switzerland are reshaping price floors for ion-exchange resins as biosimilar manufacturers negotiate three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on regulatory documentation depth and protein A ligand sourcing origin, with EMA-validated batches commanding substantial premiums over research-grade alternatives. Cost compression in standard-tier ion-exchange media is intensifying because biosimilar developers optimize cost per gram through aggressive resin cycling programs. Contract research organizations exhibit highest price sensitivity due to grant-funded budgets, while Swiss CDMOs prioritize supply security over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from EMA and Swissmedic mandate that European biopharmaceutical manufacturers qualify at least two resin suppliers for critical purification steps, yet actual supply concentrates in Germany, Denmark, and Sweden. Protein A ligand production draws from Danish and Swedish fermentation facilities, while agarose matrix supply rests on Spanish and Portuguese seaweed harvesting operations. Single-source vulnerability persists for specialized affinity chemistries despite regulatory dual-sourcing mandates. Distribution runs through integrated life sciences distributors with regional warehousing in Frankfurt, Basel, and Amsterdam serving just-in-time delivery requirements for multi-product biologics facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in this market stem from aqueous manufacturing cost-down curves and the premium-tier shift toward gene therapy vector purification specifications. Suppliers capturing CSRD-compliant bio-based chemistry positions will extract pricing power from sustainability-driven procurement mandates.
For Market Incumbents: Deepen backward integration into protein A ligand production to neutralize Danish-Swedish supply concentration risk. Secure multi-year framework agreements with Rhine-Main corridor CDMOs before aqueous-phase conversion investments by mid-tier competitors mature. Prioritize EMA cycling validation documentation investments that extend contract renewal barriers against emerging aqueous-chemistry specialists. For New Entrants and Emerging Players: The price-point gap between premium protein A resins and economy-tier ion-exchange media creates entry space for mid-tier multimodal chemistries targeting bispecific antibody purification. French and Belgian viral vector manufacturers represent the most penetrable segment given dedicated AAV resin specification windows. Pursue direct technical service agreements with gene therapy CDMOs rather than distributor channel dependence. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized polymer synthesis houses with REACH-compliant aqueous production capabilities but underdeveloped biopharmaceutical sales channels. Long-term viability centers on captive ligand production and EMA regulatory support infrastructure rather than commodity resin volumes. Watch EMA guidance on continuous bioprocessing resin cycling requirements as the inflection signal for qualification-intensive supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous-Phase Manufacturing Conversion | Eliminates solvent-based production to meet REACH mandates while reducing volatile organic compound emissions. |
| Protein A Ligand Backward Integration | Captures critical input supply currently concentrated in Danish and Swedish fermentation facilities. |
| Gene Therapy Vector Specification Development | Establishes dedicated affinity chemistries for AAV and lentivirus purification in Lyon and Flanders. |
| CSRD-Compliant Bio-Based Chemistry Launch | Positions resin portfolios for Corporate Sustainability Reporting Directive procurement preferences. |
| Multi-Year CDMO Framework Agreement | Locks in Rhine-Main corridor volume through bundled resin, filtration, and regulatory support contracts. |
Methodological Framework
Direct dialogue with biopharmaceutical process development scientists, CDMO procurement executives, EMA regulatory affairs specialists, and resin manufacturing plant managers grounded this analysis in operational reality. Secondary validation drew from EMA biosimilar guidance documents, ECHA REACH substance registration databases, EU Green Deal implementation reports, and SEC filings from listed life sciences suppliers. Bottom-up resin volume estimates from individual CDMO capacity expansions were triangulated against top-down biopharmaceutical manufacturing spend projections.
Segmentation outputs across product type, application, end user, and sales channel dimensions were modeled over the projection horizon with country-level granularity for Germany, Switzerland, France, Belgium, and the Netherlands. CAGRs were derived from regression analysis of historical resin consumption patterns against monoclonal antibody and gene therapy pipeline advancement rates. Industry-specific forecast inputs included EMA continuous bioprocessing guidance evolution timelines and REACH authorization cost trajectories for novel chemistries.
Caveats apply where EMA cycling study requirement revisions or REACH substance restriction expansions could materially shift the outlook for resin qualification timelines and chemistry commercialization economics. Deviation in natural gas pricing for fused silica processing or protein A ligand fermentation capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Polyaryletherketone (PAEK) Market