
 Global Ceramide Market | 2026-2036
Global Ceramide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramide Market Foresight
Pharmaceutical-grade ceramide specifications is unwinding new value pools across the supply chain. Croda International Plc leverages captive botanical extraction to sustain high-purity output for regulated drug applications. Evonik Industries AG anchors synthetic ceramide capacity in Europe with dedicated fermentation infrastructure. SK Bioland Co., Ltd. dominates plant-derived ceramide supply to Seoul-based cosmetic formulators through backward integration into rice bran sourcing.
Ceramides constitute a lipid class comprising sphingosine-bound fatty acids that reinforce epidermal barrier function through lamellar bilayer formation in stratum corneum tissue. Industrial production employs either solvent-based extraction from wheat germ or rice bran, yeast fermentation biosynthesis, or chemical condensation routes yielding defined carbon-chain lengths for targeted dermal penetration rates. Plant-derived ceramides command premium positioning in clean-label skincare, while synthetic variants from fermentation gain share in pharmaceutical-grade applications where batch consistency overrides origin claims. Multilipid ceramide blends concentrate margin pools in dermatology clinic channels that demand clinically validated barrier-repair protocols.
FDA oversight of ceramide-containing drug-device combinations shapes clinical trial pathways for barrier-repair therapeutics, while REACH registration requirements in Europe constrain animal-derived feedstock availability and redirect investment toward biosynthetic platforms. EMA quality guidelines for topical lipids further tighten impurity thresholds, compelling manufacturers to validate carbon-chain specificity through chromatographic certification. Stakeholders must monitor regulatory divergence between pharmaceutical and cosmetic classification thresholds as ceramide formulations migrate across channel boundaries.
Market Dynamics
Pharmaceutical-grade certification requirements are bifurcating the ceramide supply base, separating fermentation-derived synthetic producers from plant-extraction specialists as EMA impurity thresholds tighten and FDA drug-device oversight expands.
Growth Catalysts
- REACH-Compliant Biosynthesis:European chemical registration mandates are redirecting investment toward yeast-fermentation platforms that eliminate animal-derived feedstock dependencies.
- Dermatology Clinic Channel Expansion:Multilipid barrier-repair protocols in South Korea's medical-aesthetic sector are absorbing premium-grade ceramide volumes at accelerated procurement cycles.
- Clean-Label Skew in North American Retail:Rice bran and wheat germ extraction methods are capturing shelf-space preference as retailers enforce botanical-origin disclosure standards.
Market Restraints
- Feedstock Concentration Risk:Rice bran supply chains cluster in East Asian agricultural processing zones, exposing price volatility to regional harvest fluctuations.
- Carbon-Chain Precision Limits:Solvent extraction yields variable fatty acid chain distributions that fail EMA chromatographic certification thresholds for pharmaceutical applications.
- Fermentation Capex Barriers:Dedicated bioreactor infrastructure requires capital deployment that excludes mid-scale entrants from synthetic ceramide production.
Strategic Opportunities
- Indian Pharmaceutical Formulation:CDSCO regulatory pathways for topical lipids remain underdeveloped, creating first-mover positioning for certified suppliers.
- Device-Drug Combination Approvals:FDA's expanding oversight of barrier-repair therapeutics opens contract-manufacturing demand for validated ceramide suppliers.
- Brazilian Clean-Label Cosmetics:ANVISA's evolving ingredient transparency mandates are displacing petroleum-derived emollients in São Paulo-based formulator procurement.
Industry Challenges
- Chromatographic Certification Backlogs:EMA-mandated carbon-chain specificity testing is extending batch-release timelines for European pharmaceutical shipments.
- Cross-Functional Talent Scarcity:Lipid biochemistry expertise intersects with regulatory affairs capability in hiring markets where both skill sets rarely coexist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramide Market |
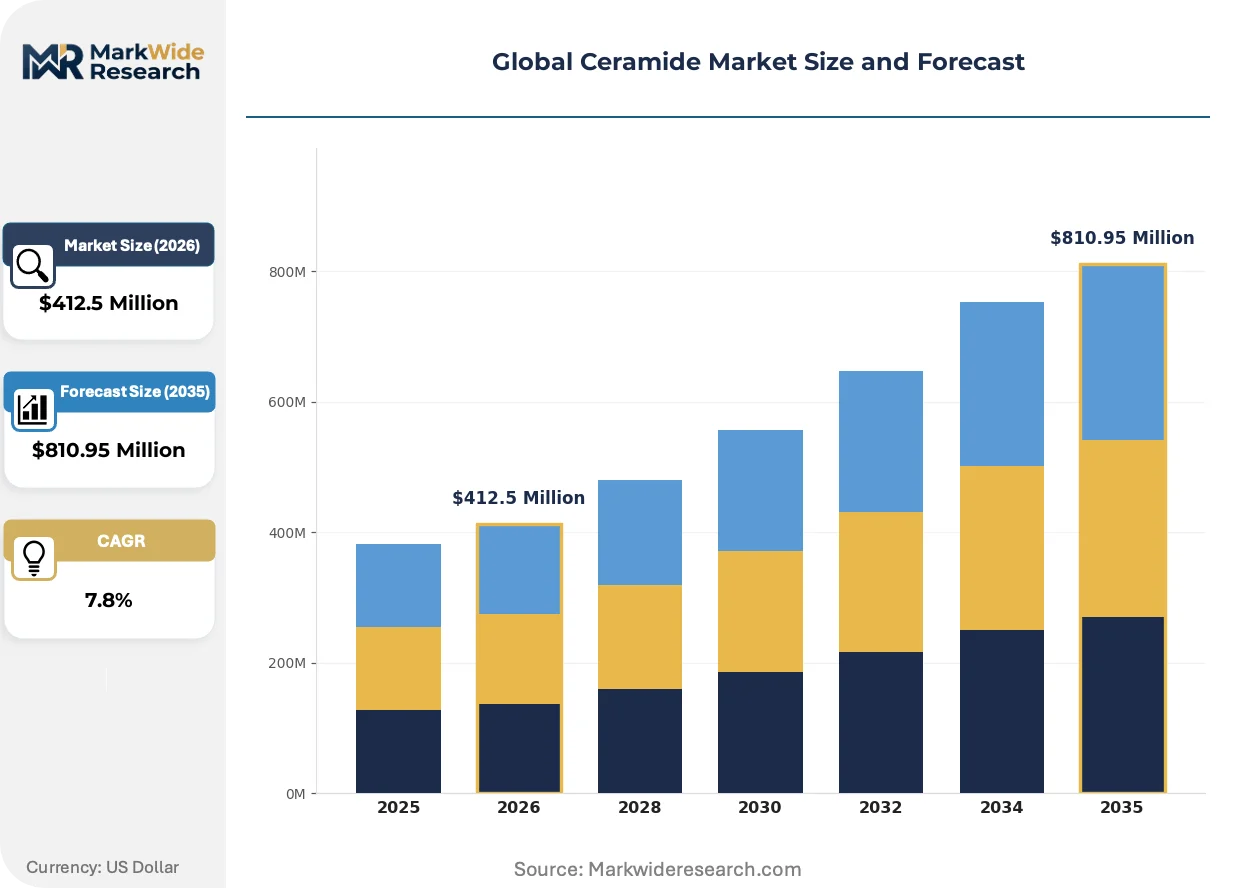
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Derived Ceramides, Synthetic Ceramides, Animal-Derived Ceramides, Multilipid Ceramides Application: Skincare Products, Hair Care Products, Pharmaceutical Products, Personal Care Products End User: Dermatology Clinics, Cosmetic Manufacturers, Pharmaceutical Companies, Spa & Wellness Centers Form: Powder, Liquid, Emulsion, Gel |
| Companies Covered | Croda International Plc, Evonik Industries AG, Doosan Corporation, SK Bioland Co., Ltd., Vantage Specialty Ingredients, Ashland Global Holdings Inc., Kao Corporation, TOYOBO CO., LTD., Shiseido Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramide Market Shifts & Advancements
Fermentation-based synthetic production is rewriting purity benchmarks while regulatory divergence between pharmaceutical and cosmetic classifications forces dual-track compliance investments.
Precision fermentation of defined carbon-chain ceramides is supplanting solvent-extracted plant variants in pharmaceutical applications where batch-to-batch consistency overrides origin claims. Contract manufacturers serving FDA-regulated drug-device combinations are specifying synthetic grades exclusively. This technology compression is collapsing premium pricing spreads that previously separated botanical from biosynthetic supply tiers.
EMA quality guidelines for topical lipids are tightening impurity thresholds beyond REACH baseline requirements, compelling manufacturers to validate carbon-chain specificity through expanded chromatographic certification. European producers are retrofitting quality systems to accommodate both cosmetic and pharmaceutical classification audits simultaneously. The regulatory burden falls heaviest on mid-scale extraction specialists lacking in-house analytical capabilities.
Direct procurement from certified manufacturers is displacing distributor-mediated supply in Seoul's cosmetic formulator base. Large-scale buyers are consolidating vendor panels to reduce qualification overhead while securing volume commitments. This channel consolidation is most pronounced among medical-aesthetic clinic chains demanding clinically validated barrier-repair protocols with documented batch traceability.
Global Ceramide Market Segmentation
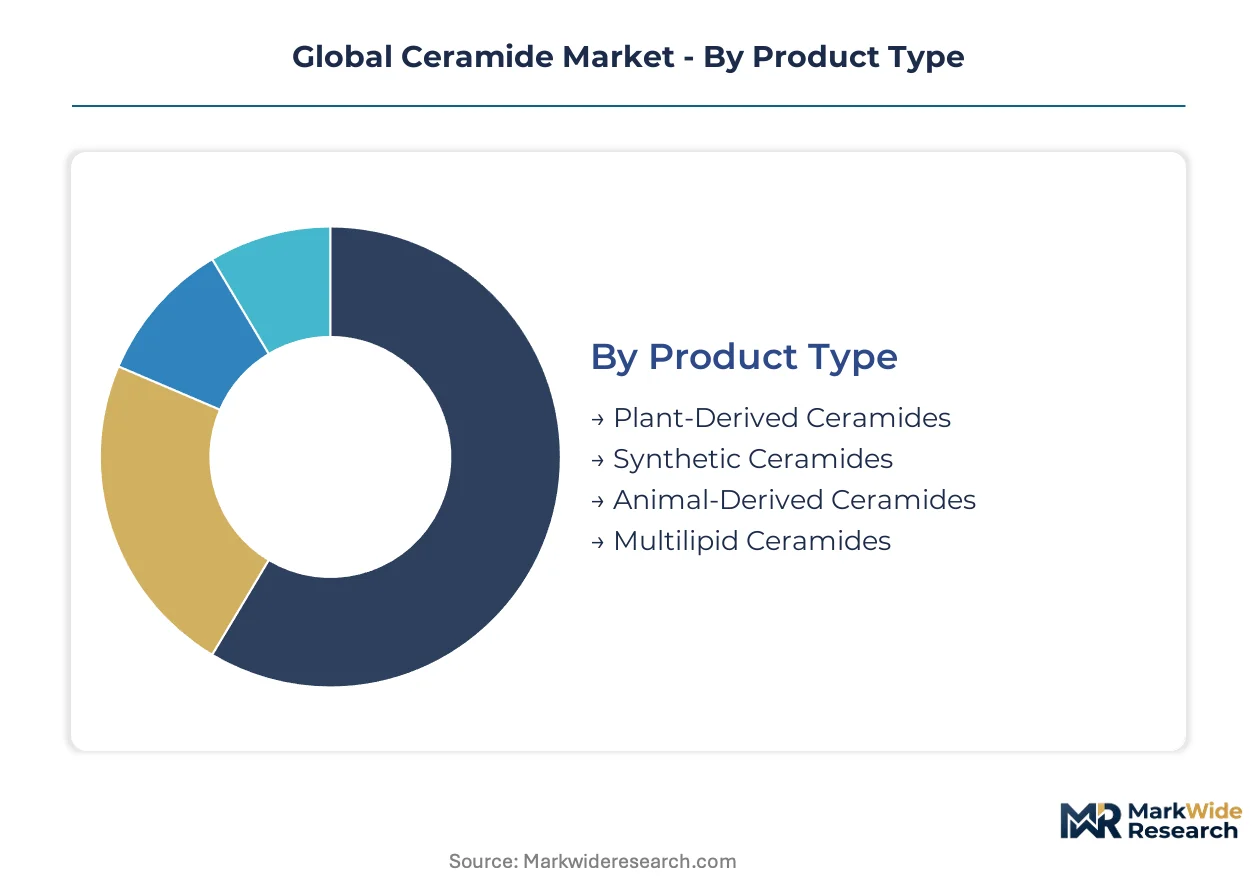
Ceramide segmentation separates margin capture between origin-certified botanicals and consistency-optimized synthetics. Pharmaceutical-grade specifications are compressing pricing spreads across product tiers while channel-specific formulations concentrate demand in distinct end-user bases.
Product Type:
Margin pools concentrate in synthetic ceramides where fermentation platforms command pharmaceutical premiums, while plant-derived variants retain clean-label positioning in cosmetic channels.
- Plant-Derived Ceramides:Solvent extraction from rice bran and wheat germ yields sphingolipid fractions with C16-C24 fatty acid distributions. Seoul-based cosmetic formulators absorb premium volumes as South Korean retailers enforce botanical-origin disclosure standards.
- Synthetic Ceramides:Yeast fermentation biosynthesis produces defined carbon-chain lengths with batch-to-batch chromatographic consistency. FDA-regulated drug-device combination manufacturers specify synthetic grades exclusively for barrier-repair therapeutic submissions.
- Animal-Derived Ceramides:Bovine and porcine tissue extraction yields ceramide-cholesterol mixtures with established dermal compatibility profiles.
- Multilipid Ceramides:Pre-formulated blends combining ceramides, cholesterol, and free fatty acids in physiologic ratios for stratum corneum mimicry.
Synthetic ceramides hold installed capacity. Plant-derived ceramides are rotating up the share rankings in North American clean-label retail.
Application:
Volume concentration sits with skincare formulations, though pharmaceutical applications are climbing fastest on regulatory validation requirements.
- Skincare Products:Facial moisturizers and barrier-repair creams incorporate ceramides at 1-5% concentrations for lamellar bilayer reinforcement. South Korea's medical-aesthetic sector drives premium absorption through clinically validated protocol adoption.
- Pharmaceutical Products:Topical drug formulations leverage ceramide-based drug-device combinations for atopic dermatitis and psoriasis management. EMA impurity thresholds and FDA oversight are bifurcating supply qualification pathways.
- Hair Care Products:Shampoos and conditioners utilize ceramides for cuticle sealing and moisture retention in damaged hair shafts.
- Personal Care Products:Body lotions and hand creams incorporate ceramides for generalized barrier maintenance in mass-market positioning.
Skincare applications hold installed capacity. Pharmaceutical products are gaining share fastest on regulatory tailwinds.
End User:
Procurement patterns separate between direct manufacturer relationships and distributor-mediated supply, with channel consolidation favoring large-scale buyers.
- Dermatology Clinics:Medical-aesthetic chains in Seoul demand documented batch traceability and clinically validated barrier-repair protocols. Direct procurement from certified manufacturers is displacing traditional distribution channels.
- Cosmetic Manufacturers:Large-scale formulators consolidate vendor panels to reduce qualification overhead while securing volume commitments for clean-label product lines.
- Pharmaceutical Companies:Drug-device combination developers require REACH-compliant and FDA-validated ceramide supply with expanded chromatographic certification.
- Spa & Wellness Centers:Service-oriented channels absorb smaller volumes of premium-grade ceramides for treatment-room applications.
Cosmetic manufacturers hold installed capacity. Dermatology clinics are rotating up the share rankings.
Form:
Supply concentration favors powder and liquid formats, with emulsion and gel forms capturing formulation-specific premiums.
- Powder:Spray-dried ceramide concentrates enable stable storage and flexible reconstitution for diverse formulation bases.
- Liquid:Solubilized ceramide dispersions facilitate direct incorporation into aqueous and emulsion systems without micronization steps.
- Emulsion:Pre-dispersed lipid droplets with surfactant stabilization accelerate manufacturing throughput for cream and lotion producers.
- Gel:Thixotropic ceramide matrices target targeted delivery applications and medical-device compatible formulations.
Powder and liquid forms hold installed capacity. Emulsion formats are rotating up the share rankings on manufacturing efficiency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean ceramide exports flow primarily to cosmetic formulators in Japan and the United States, establishing Seoul as the dominant trade-flow hub for premium-grade botanical variants.
United States
FDA oversight of ceramide-containing drug-device combinations accelerates demand for synthetic grades with batch-to-batch chromatographic consistency. The agency's expanding therapeutic classification requirements redirect pharmaceutical procurement toward fermentation-derived supply. New Jersey-based formulators absorb growing volumes for atopic dermatitis protocol development.
Germany
EMA quality guidelines for topical lipids tighten impurity thresholds beyond REACH baseline requirements, compelling manufacturers to retrofit dual-track compliance systems. Evonik Industries AG anchors synthetic ceramide capacity with dedicated fermentation infrastructure serving pharmaceutical clients. Frankfurt-area chemical clusters concentrate quality certification capacity for cross-border European supply.
South Korea
Seoul-based cosmetic manufacturers anchor premium ceramide consumption through direct procurement relationships displacing distributor channels. MFDS cosmetic safety standards enforce botanical-origin disclosure that rice bran-derived variants satisfy. Busan-Ulsan industrial zones host backward-integrated extraction facilities processing domestic agricultural feedstock.
Japan
PMDA regulatory pathways for barrier-repair therapeutics create demand for pharmaceutical-grade ceramide specifications with documented carbon-chain specificity. Shiseido and Kao Corporation procurement concentrates volumes for clinical validation requirements. Tokyo-Osaka cosmetic innovation corridors absorb multilipid blends for medical-aesthetic protocol adoption.
Brazil
ANVISA's evolving ingredient transparency mandates displace petroleum-derived emollients in São Paulo-based formulator procurement. Clean-label skincare retailers enforce botanical-origin standards that rice bran and wheat germ extraction methods satisfy. Southeastern industrial zones concentrate cosmetic manufacturing capacity absorbing premium-grade ceramide imports.
Global Ceramide Market Competitive Landscape
Listed leaders compete with private specialists across certification-grade tiers, producing a bifurcated structure where fermentation-derived synthetic producers separate from plant-extraction specialists. Publicly traded chemical conglomerates anchor pharmaceutical-grade supply chains with dedicated bioreactor infrastructure, while private botanical processors retain clean-label positioning in cosmetic channels. Three archetypes dominate: captive-integrated agricultural processors, synthetic fermentation specialists, and multilipid blend formulators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct procurement relationships displacing traditional distribution channels.
Within the synthetic fermentation tier, Evonik Industries AG exemplifies European capacity concentration, while SK Bioland Co., Ltd. represents East Asian botanical integration. Croda International Plc occupies a position bridging pharmaceutical and cosmetic grade supply, reflecting the regulatory divergence between FDA drug-device oversight and clean-label retail standards.
| Leading Market Players |
|---|
| Croda International Plc |
| Evonik Industries AG |
| Doosan Corporation |
| SK Bioland Co., Ltd. |
| Vantage Specialty Ingredients |
| Ashland Global Holdings Inc. |
| Kao Corporation |
| TOYOBO CO., LTD. |
| Shiseido Company, Limited |
| Others |
Supply & Pricing Matrix
Synthetic fermentation platforms displacing solvent-extracted plant variants are redrawing supply geography toward East Asian bioreactor clusters while collapsing historical premium spreads between botanical and biosynthetic grades. This substitution dynamic concentrates pricing power with fermentation specialists possessing validated chromatographic certification capacity, leaving extraction-dependent processors exposed to feedstock volatility and regulatory rejection risk.
Pricing Analysis
Three-generation pricing stratification separates next-gen precision fermentation outputs from incumbent solvent-extraction methods and legacy animal-derived grades. Pharmaceutical-grade synthetic ceramides command premium positioning through FDA-validated batch consistency, while plant-derived variants compete on clean-label positioning in cosmetic channels where EMA impurity thresholds exert less pressure. Cost compression in mid-tier extraction grades is intensifying as rice bran feedstock volatility and chromatographic certification backlogs squeeze margins. Mass-market cosmetic manufacturers exhibit highest price sensitivity, whereas drug-device combination developers prioritize supply security over unit economics.
Supply Chain Analysis
Extended batch-release timelines for EMA-mandated carbon-chain specificity testing are stretching inventory cycles and forcing safety-stock accumulation among European pharmaceutical clients. Supply concentrates in South Korea, Germany, and Japan, with backward-integrated rice bran processors in Busan-Ulsan zones feeding Seoul cosmetic formulators. Fermentation infrastructure draws from dedicated yeast strain repositories and pharmaceutical-grade bioreactor networks. Single-source vulnerability sits with East Asian agricultural feedstock clusters exposed to regional harvest fluctuations. Distribution runs through direct manufacturer relationships displacing traditional distributor channels among large-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation disruption is accelerating market bifurcation as regulatory validation requirements harden entry barriers and compress pricing spreads across traditional grade tiers.
For Market Incumbents: Shield pharmaceutical-grade positioning through captive fermentation capacity expansion and dual-track EMA/FDA certification systems that preempt regulatory divergence. Deepen backward integration into yeast strain development to secure biosynthetic supply chain control against emerging platform competitors. For New Entrants and Emerging Players: Anchor in Brazilian clean-label cosmetics where ANVISA transparency mandates displace petroleum-derived alternatives and rice bran extraction methods satisfy botanical-origin standards. Target São Paulo-based formulators with certified plant-derived supply as the most penetrable entry corridor, leveraging direct procurement relationships to bypass established distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private botanical processors possessing clean-label positioning but lacking pharmaceutical-grade certification infrastructure. Five-to-ten year viability hinges on regulatory divergence between cosmetic and therapeutic classification thresholds. Watch for CDSCO pathway development in India as inflection signal for emerging market pharmaceutical formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yeast Strain Development | Captive biosynthetic capacity secures batch consistency for FDA drug-device submissions. |
| Dual-Track EMA/FDA Certification Investment | Simultaneous quality system retrofit captures pharmaceutical and cosmetic grade demand. |
| Direct Procurement Relationship Expansion | Channel consolidation among Seoul medical-aesthetic chains reduces distributor dependency. |
| Chromatographic Certification Capacity Addition | In-house analytical capabilities preempt EMA-mandated batch-release backlogs. |
| Indian Pharmaceutical Market Entry | First-mover positioning in CDSCO topical lipid pathways captures formulation growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with cosmetic formulators, pharmaceutical procurement managers, fermentation plant engineers, regulatory affairs specialists, and dermatology clinic chain buyers. Secondary validation drew from EMA quality guidelines, FDA drug-device combination filings, REACH registration databases, MFDS cosmetic safety standards, and customs trade flow records. Bottom-up volume estimates from production facility disclosures were triangulated against top-down demand aggregation from end-user procurement patterns.
Across the projection horizon, the analytical framework modeled ceramide segmentation by origin type, application channel, end-user procurement pattern, and geographic regulatory cluster. CAGRs were derived from supply-side capacity expansion schedules cross-referenced against demand-pull indicators from pharmaceutical pipeline development and cosmetic retail shelf-space evolution. Forecast inputs incorporated fermentation yield improvement curves and EMA impurity threshold enforcement trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory divergence between pharmaceutical and cosmetic classifications; material deviation would warrant model refresh. Specific risks include abrupt REACH feedstock restrictions, FDA therapeutic reclassification rulings, and East Asian agricultural supply shocks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Anti-Static Control Products Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market