
 Precision Farming Software Market | 2026-2036
Precision Farming Software Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Farming Software Market Intelligence
The integration of generative AI into data analytics platforms is reshaping how precision farming software delivers actionable insights from disparate data sources. This shift moves software from a passive data repository to an active decision-support partner for farmers. Trimble Inc. leverages its deep expertise in GPS and positioning technology to offer highly accurate field management solutions. Meanwhile, Deere & Company sustains a dominant market position through its tightly integrated ecosystem of machinery and proprietary software, creating a significant barrier to entry.
Precision farming software comprises a suite of digital tools designed to collect, process, and analyze geospatial and agronomic data from multiple sources. These platforms often incorporate Variable Rate Technology (VRT) algorithms to automate the application of inputs like fertilizers and seeds. Their primary purpose is to enhance farm operational efficiency, optimize crop yields, and ensure sustainable resource management. Cloud-based deployment models exhibit the fastest growth due to their scalability and ease of data sharing among farmers, agronomists, and consultants. Within product categories, crop management and analytics platforms command the largest share.
Regulatory frameworks directly influence software design and adoption. The US EPA's rules on pesticide application records and the EU's Common Agricultural Policy (CAP) with its eco-schemes create compliance-driven demand for documentation and reporting features. Similarly, Brazil's ABC Plan incentivizes low-carbon agricultural practices, supported by precision software. The central strategic decision for vendors now revolves around choosing between open, interoperable platform architectures and closed, proprietary ecosystems.
Market Dynamics
The central strategic tension in the precision farming software market is the conflict between open, interoperable data platforms and closed, proprietary ecosystems. This choice dictates vendor strategy, influencing everything from hardware compatibility and data sharing to long-term customer lock-in.
Growth Catalysts
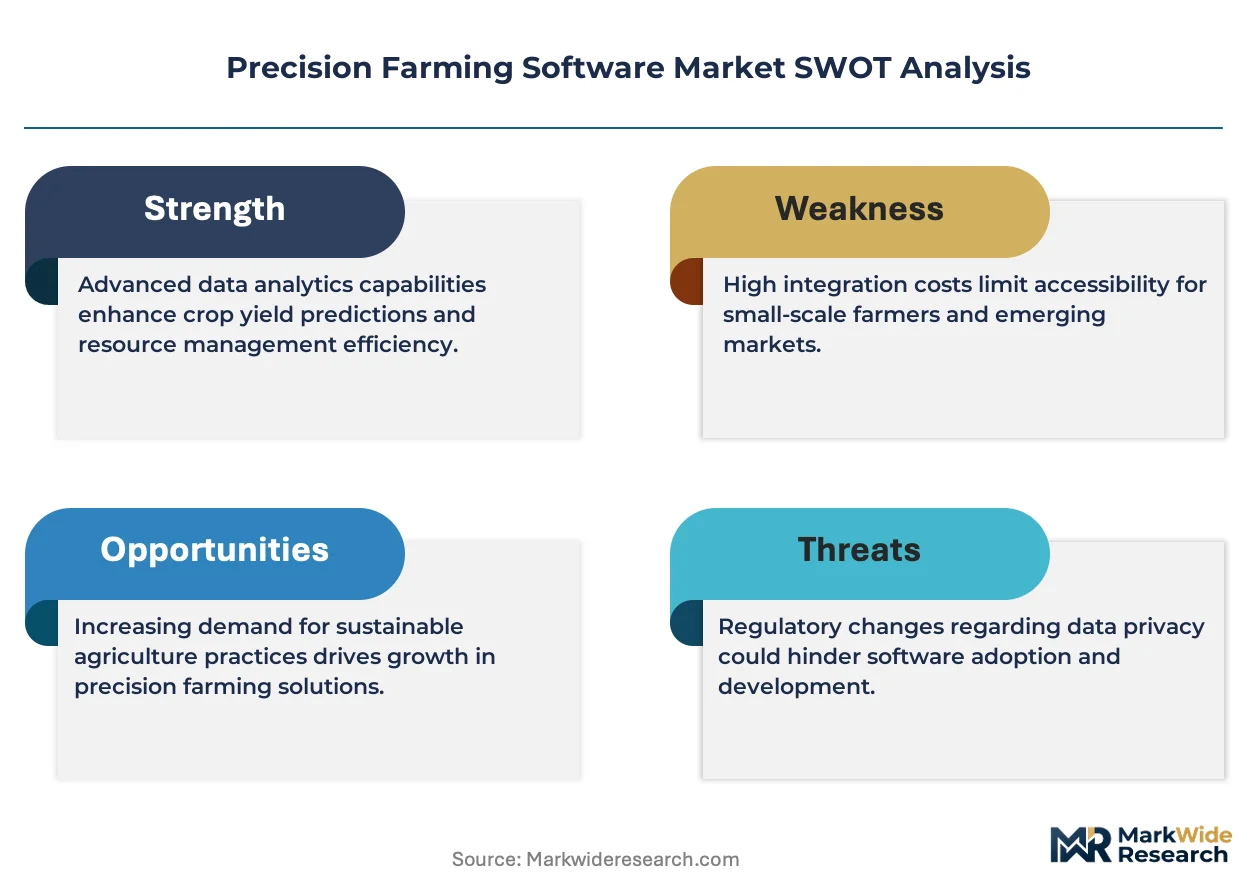
- Regulatory Mandates:The EU's Farm to Fork Strategy, which requires significant reductions in chemical pesticide and fertilizer use, compels farmers to adopt software for precise, documented application and compliance.
- AI Integration:The incorporation of generative AI into analytics platforms transforms raw data from sensors and machinery into predictive agronomic advice, increasing the software's value proposition for large-scale grain and oilseed operations.
- Sustainability Incentives:Brazil's ABC Plan provides financial incentives for low-carbon agricultural practices, spurring demand for software that can monitor, verify, and report on metrics like soil carbon sequestration and reduced emissions.
Market Restraints
- High Initial Costs:The substantial upfront investment required for compatible hardware, such as VRT-enabled controllers and GPS receivers, alongside software subscription fees, remains a significant barrier for small to medium-sized farms.
- Data Interoperability:A lack of universal data standards across different equipment manufacturers creates data silos, preventing seamless information flow between a farmer's tractor, combine, and software platform from competing brands.
- Rural Connectivity Gaps:Inadequate or unreliable broadband and cellular service in many primary agricultural regions limits the functionality of cloud-based platforms and hinders real-time data synchronization from field to office.
Strategic Opportunities
- Carbon Farming Platforms:Developing specialized software modules to help farmers quantify, document, and monetize soil carbon credits presents a new revenue stream tied directly to corporate and governmental sustainability goals.
- Technology Convergence:Integrating drone-based hyperspectral imagery with data from in-field IoT sensors enables the creation of highly granular field management zones, optimizing inputs at an unprecedented level of precision.
- Emerging Market Penetration:Expanding into agricultural economies in Eastern Europe and Southeast Asia, where large farms are rapidly modernizing but software adoption is low, offers significant growth potential for vendors.
Industry Challenges
- Agronomic Talent Scarcity:A shortage of agronomists and farm managers with the data science and analytics skills needed to interpret software outputs and implement complex variable-rate prescriptions limits effective technology utilization.
- Data Privacy and Security:Ensuring the security of sensitive farm operational data against cyberattacks and defining clear data ownership policies are critical challenges for cloud-based software providers to maintain farmer trust.
- Legacy System Integration:The difficulty of integrating modern, cloud-based software with older, on-premise farm accounting systems and incompatible machinery hardware creates significant implementation friction and delays adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Farming Software Market |
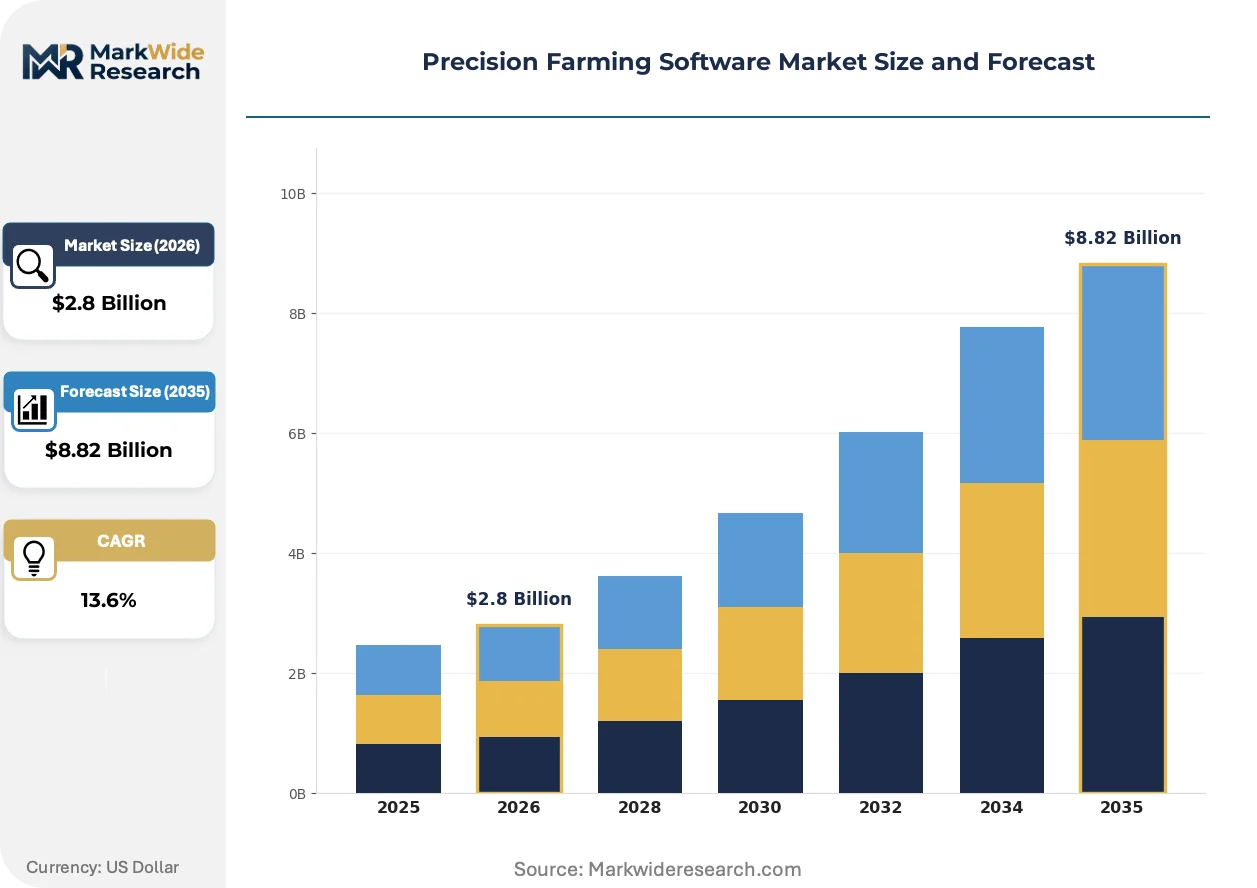
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Management, Soil Monitoring, Livestock Management, Analytics Platform Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Application Technology: Satellite Imaging, IoT Sensors, Drones, Data Analytics End User: Farmers, Agronomists, Agricultural Consultants, Cooperatives |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Topcon Corporation, Kubota Corporation, Corteva Agriscience, Bayer AG, Farmers Edge Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Farming Software Market Strategic Shifts & Innovations
The evolution of precision farming software is defined by a move from passive data aggregation to active, automated decision support. This transition is powered by machine learning algorithms and enhanced sensor fusion, making the software an indispensable partner in daily farm management.
Digital twin technology for agriculture creates a dynamic, virtual representation of a physical field or an entire farm operation. Large agribusinesses and advanced research institutions are the earliest adopters, using these models for complex simulations. This technology is virtualizing crop growth cycles and the effects of different input strategies, enabling risk-free scenario analysis before committing physical resources.
The United States EPA's rules governing pesticide application require meticulous record-keeping for restricted-use products. This regulation creates a compliance-driven need for software that can automatically log application date, time, location, and weather conditions directly from sprayer equipment. The grain and oilseed segment, which uses large volumes of inputs, is most affected, driving its adoption of platforms with robust reporting features.
A definitive shift is underway from one-time perpetual software licenses to recurring subscription-based models. This SaaS approach significantly lowers the entry cost for farmers, converting a large capital expenditure into a manageable operational expense. The trend is most advanced in North America and Western Europe, where vendors increasingly bundle software access with continuous data storage, support, and feature updates.
Precision Farming Software Market Segmentation
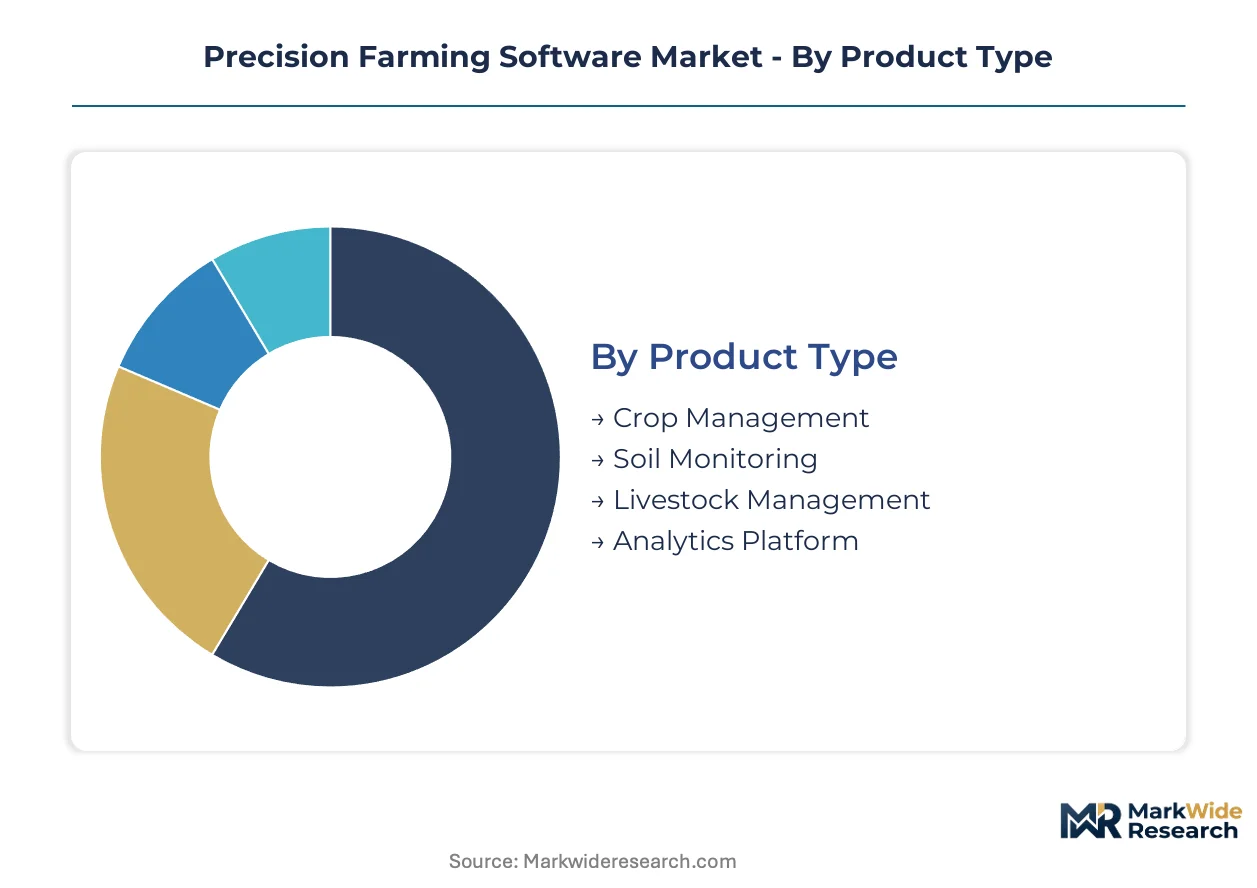
Precision farming software market segmentation offers a granular view of diverse product offerings, deployment models, technological foundations, and end-user requirements. Understanding these distinct segments is crucial for vendors to tailor solutions, optimize market penetration, and address specific agricultural challenges across different regions.
Product Type:
The functional scope of precision farming software is delineated by its product type, reflecting specific agricultural needs and operational objectives.
- Crop Management:These platforms integrate data from sensors, imagery, and historical records to optimize planting, irrigation, and pest control schedules. Demand concentrates in large-scale grain and oilseed operations, driven by the need for yield optimization and regulatory compliance, such as those mandated by the EU's Farm to Fork Strategy.
- Analytics Platform:These solutions process disparate data streams from various farm operations, employing AI and machine learning to generate predictive insights and actionable recommendations. Demand is concentrating in primary agricultural regions like the United States and Western Europe, where advanced data interpretation enhances decision-making and resource efficiency.
- Soil Monitoring:These tools provide real-time data on soil moisture, nutrient levels, and temperature, supporting optimized fertilization and irrigation strategies for sustainable resource management.
- Livestock Management:Software for livestock management tracks animal health, feeding, and breeding cycles, improving operational efficiency and profitability for large animal farms.
Crop Management commands the established base. The steepest expansion runs through Analytics Platform.
Deployment:
The architectural model chosen for precision farming software deployment significantly impacts accessibility and scalability for users, influencing data sharing and operational flexibility.
- Cloud-Based:These platforms host data and applications on remote servers, accessible via the internet, offering flexibility, scalability, and ease of data sharing among stakeholders. Demand is concentrating in North America and Western Europe, driven by improved rural connectivity and the desire for collaborative data access.
- Mobile Application:Designed for smartphones and tablets, these applications provide on-the-go access to farm data, field maps, and decision-support tools, often integrating with cloud platforms. Demand is accelerating in regions with high mobile penetration and a need for real-time field operations management.
- On-Premise:On-premise solutions involve software installed directly on local farm servers, offering full data control but requiring significant upfront IT investment and maintenance.
- Hybrid:Hybrid deployment combines local server components with cloud-based services, balancing data security with remote accessibility for various farm operations.
Cloud-Based solutions represent the dominant method for software delivery. Mobile Application deployment is gaining share fastest due to its accessibility.
Technology:
The underlying technological components empower precision farming software to collect, process, and interpret agricultural data, driving automation and decision support.
- Data Analytics:This technology involves advanced algorithms and statistical models to derive actionable insights from complex agricultural datasets, including yield, weather, and soil information. Demand concentrates where predictive agronomic advice is critical for optimizing input use and crop performance, such as in large grain and oilseed operations.
- IoT Sensors:Internet of Things (IoT) sensors collect real-time environmental and plant data, such as soil moisture, temperature, and nutrient levels, transmitting it for analysis. Demand is strong in high-value crop production and resource-constrained environments, enabling precise resource allocation and sustainable practices.
- Drones:Drones provide high-resolution aerial imagery for crop health monitoring and field mapping, offering a cost-effective solution for large-area surveillance and early problem detection.
- Satellite Imaging:Satellite imaging offers broad-area crop health and growth monitoring, providing valuable data for large-scale agricultural planning and environmental assessments, especially in remote regions.
Data Analytics underpins the intelligence of modern precision farming. IoT Sensors are climbing the fastest in adoption for real-time data acquisition.
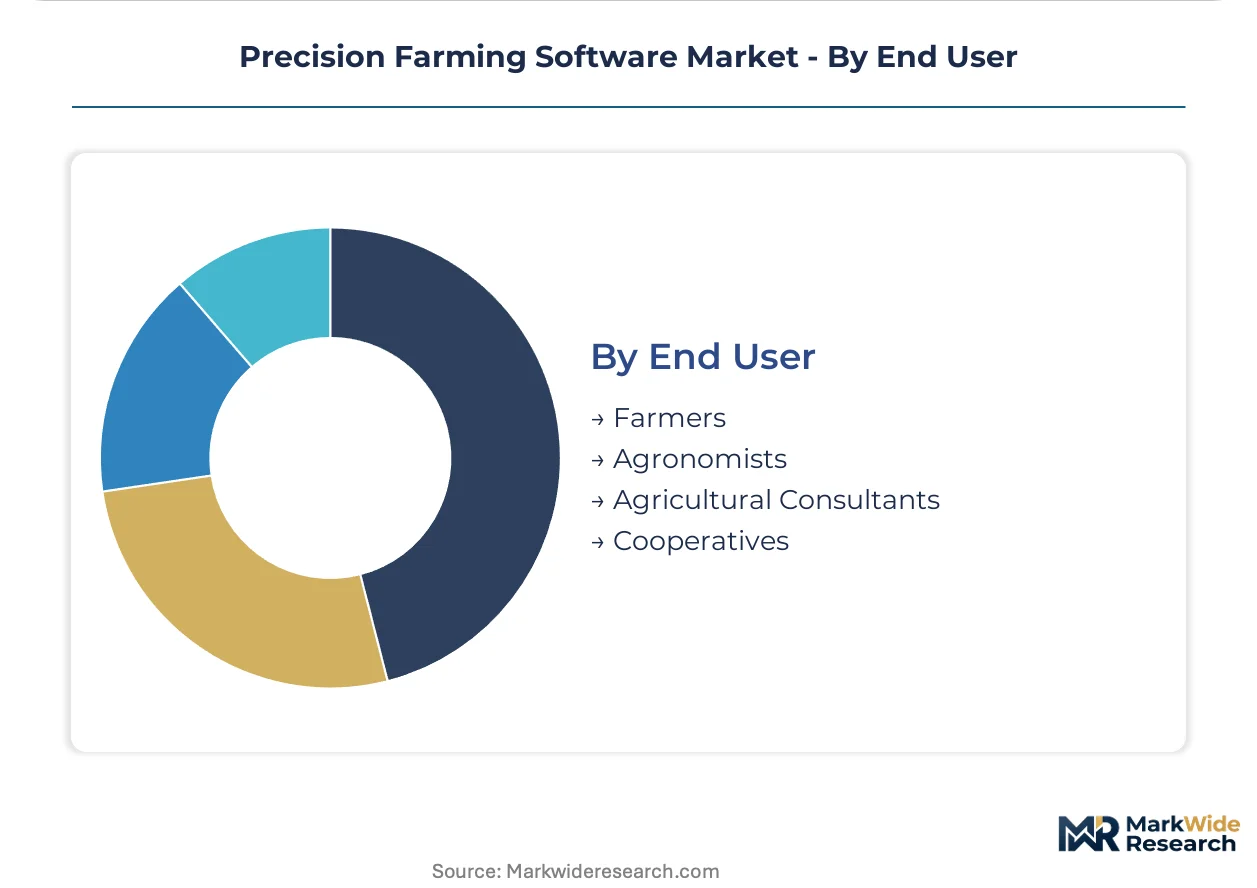
End User:
The specific needs and operational scales of various end-user groups shape the adoption patterns and feature requirements for precision farming software, influencing product design and market focus.
- Farmers:This segment includes individual farm owners and operators who directly utilize software for day-to-day decision-making, field management, and operational efficiency. Demand is widespread, particularly among large-scale commercial farmers in the United States and Brazil, seeking to optimize yields and reduce input costs.
- Agricultural Consultants:These professionals leverage precision farming software to provide expert advice, create variable-rate prescriptions, and manage data for multiple client farms. Demand is concentrating in regions where specialized agronomic expertise is valued, aiding farmers in complex data interpretation and sustainable practices.
- Cooperatives:Agricultural cooperatives use software to manage collective resources, optimize supply chains, and provide shared services to their member farmers, enhancing collective efficiency.
- Agronomists:Agronomists use precision software for detailed crop analysis, soil health assessments, and developing science-based recommendations for crop improvement and regulatory compliance.
Farmers represent the largest direct user base for precision software. Agricultural Consultants are increasingly driving specialized software adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of advanced precision farming software from technology hubs like the United States and Western Europe to agricultural powerhouses such as Brazil is shaping market dynamics. These technological exchanges facilitate optimized farming practices globally. Regulatory frameworks in these regions significantly influence software design and adoption.
United States
Large-scale grain and oilseed operations in the United States drive demand for yield optimization and resource efficiency. The US EPA's rules on pesticide application records necessitate software for meticulous documentation. California's Central Valley sees significant adoption, leveraging software for water management and high-value crop production.
Brazil
Expanding agribusiness and sustainability goals in Brazil fuel demand for precise input management. Brazil's ABC Plan incentivizes low-carbon agricultural practices, supported by monitoring and reporting software. The Mato Grosso region, a major soybean producer, integrates advanced platforms for large-scale crop management.
France
European farmers in France demand software for compliance with environmental mandates and enhanced productivity. The EU's Farm to Fork Strategy compels reductions in chemical inputs, driving adoption of precision tools. The agricultural plains of the Paris Basin integrate advanced analytics for optimizing cereal and oilseed production.
Germany
High-value crop production and efficient resource use drive software demand among German farmers. Germany's implementation of the EU's Common Agricultural Policy (CAP) eco-schemes creates demand for verifiable sustainability data. Bavaria's diverse agricultural sector utilizes precision platforms for specialized crop management and livestock monitoring.
India
Modernization of large farms and government initiatives for agricultural technology adoption stimulate software uptake in India. Government subsidies for farm mechanization and digital tools encourage investment in precision solutions. The states of Punjab and Haryana, key agricultural hubs, increasingly deploy software for yield forecasting and input optimization.
Precision Farming Software Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, combining deeply integrated machinery manufacturers with specialized software providers. Dominant players leverage proprietary ecosystems, while agile technology firms focus on specific data analytics or IoT solutions. Strategic archetypes include agricultural equipment giants, pure-play precision software developers, and sensor technology innovators. Competitive moves involve strategic partnerships to bridge hardware-software gaps and continuous portfolio diversification into new agronomic functionalities.
Within the integrated machinery sector, Deere & Company exemplifies a model where proprietary software tightly integrates with agricultural equipment. Trimble Inc. occupies a position as a technology specialist, leveraging its expertise in GPS and positioning for field management solutions. Farmers Edge Inc. sits within the segment of pure-play software providers, focusing on data analytics and decision support platforms for farm operations. These companies collectively anchor different approaches to delivering precision farming capabilities to the market.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Topcon Corporation |
| Kubota Corporation |
| Corteva Agriscience |
| Bayer AG |
| Farmers Edge Inc. |
| Others |
Cost & Logistics Intelligence
Regulatory uncertainty surrounding data ownership and interoperability acts as a risk vector. This uncertainty directly determines both pricing tier spreads for software solutions and the structural shape of data integration supply chains.
Pricing Analysis
The pricing gap between advanced AI-driven platforms and legacy data aggregation tools influences market dynamics. Subscription-based SaaS models dominate, offering continuous updates and support to farmers. Price differentiation stems from the customization level for specific crop types and the depth of integration with existing farm machinery. Pricing pressure stems from the need to attract small-to-medium farms with lower upfront costs. Small and medium-sized farms are most price-sensitive; large commercial operations prioritize advanced features and integration.
Supply Chain Analysis
Limited data export controls, particularly concerning sensitive agricultural data, affect the global flow of information. Software development concentrates in technology hubs like the United States and Western Europe. The software supply chain depends on access to skilled software engineers, cloud computing infrastructure, and specific geospatial data providers. Data interoperability standards present a structural risk, creating silos and hindering seamless data flow across different vendor ecosystems. Distribution runs primarily through direct sales teams, value-added resellers, and partnerships with agricultural equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision farming software market is undergoing a platform-economics inflection. This shift is driven by the demand for open, interoperable data ecosystems over closed, proprietary solutions.
For Market Incumbents:Entrench core customer relationships by enhancing interoperability across diverse equipment brands. Integrate emerging AI capabilities to counter the threat from agile pure-play software developers. Invest in robust data security features to maintain farmer trust against cyberattack risks. Leverage existing channel partnerships for deeper market penetration in grain and oilseed operations.
For New Entrants and Emerging Players:Establish a beachhead in carbon farming platforms, targeting the underpenetrated sustainability segment. Focus on mobile application development for regions with high mobile penetration and limited fixed broadband. Penetrate emerging markets in Eastern Europe with localized, subscription-based offerings. Offer specialized solutions for high-value crops where precision offers immediate ROI.
For Investors and Strategic Acquirers:Specialized analytics platforms with strong AI integration represent an attractive acquisition target archetype. Long-term viability hinges on scalable cloud-based solutions addressing data interoperability challenges. Acquirers should prioritize firms with strong intellectual property in variable rate technology or digital twin applications. A signal to watch is the increasing uptake of open-source agricultural data standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Interoperability Development | Facilitates seamless data exchange between diverse farm equipment and software. |
| AI-Driven Agronomic Advice | Transforms raw data into actionable insights for optimized crop management. |
| Carbon Farming Module Launch | Creates new revenue streams by enabling farmers to monetize sustainable practices. |
| Cloud Infrastructure Expansion | Enhances scalability and data accessibility for global agricultural operations. |
| Strategic Partnerships with Equipment OEMs | Bridges hardware-software gaps and expands market reach for integrated solutions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews. Industry stakeholders included farm managers, agricultural consultants, software developers, and equipment manufacturers. Secondary data sources comprised agricultural association reports, government agricultural census data, and technology company financial filings. This approach ensured bottom-up and top-down triangulation for robust market insights.
Market size calibration involved analyzing historical growth trends and future projections across the analysis window. Segmentation dimensions modeled included product type, deployment, technology, end-user, and farm size. Compound annual growth rates were derived from a multi-factor regression model incorporating economic indicators and technology adoption rates. Forecast inputs included agricultural commodity price forecasts and rural broadband infrastructure investment plans.
Sensitivities concentrate around unforeseen regulatory changes and the pace of rural connectivity improvements. Forecasts reflect assumptions concerning technology maturation and farmer investment appetite. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Global Digital Agriculture Platform Market