
 Global Water Soluble Fertilizer Market | 2026-2036
Global Water Soluble Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Water Soluble Fertilizer Market Foresight
The EU Green Deal's nutrient reduction targets is hardening compliance requirements for nitrogen runoff across European agricultural zones. Yara International leverages its integrated ammonia-to-nitrate supply chain to sustain cost-advantaged positions in controlled-release formulations. Haifa Chemicals Limited anchors its competitive stance through specialty potassium nitrate grades optimized for hydroponic substrates. ICL Group Ltd. differentiates via deep vertical integration into phosphate rock and downstream soluble compound manufacturing.
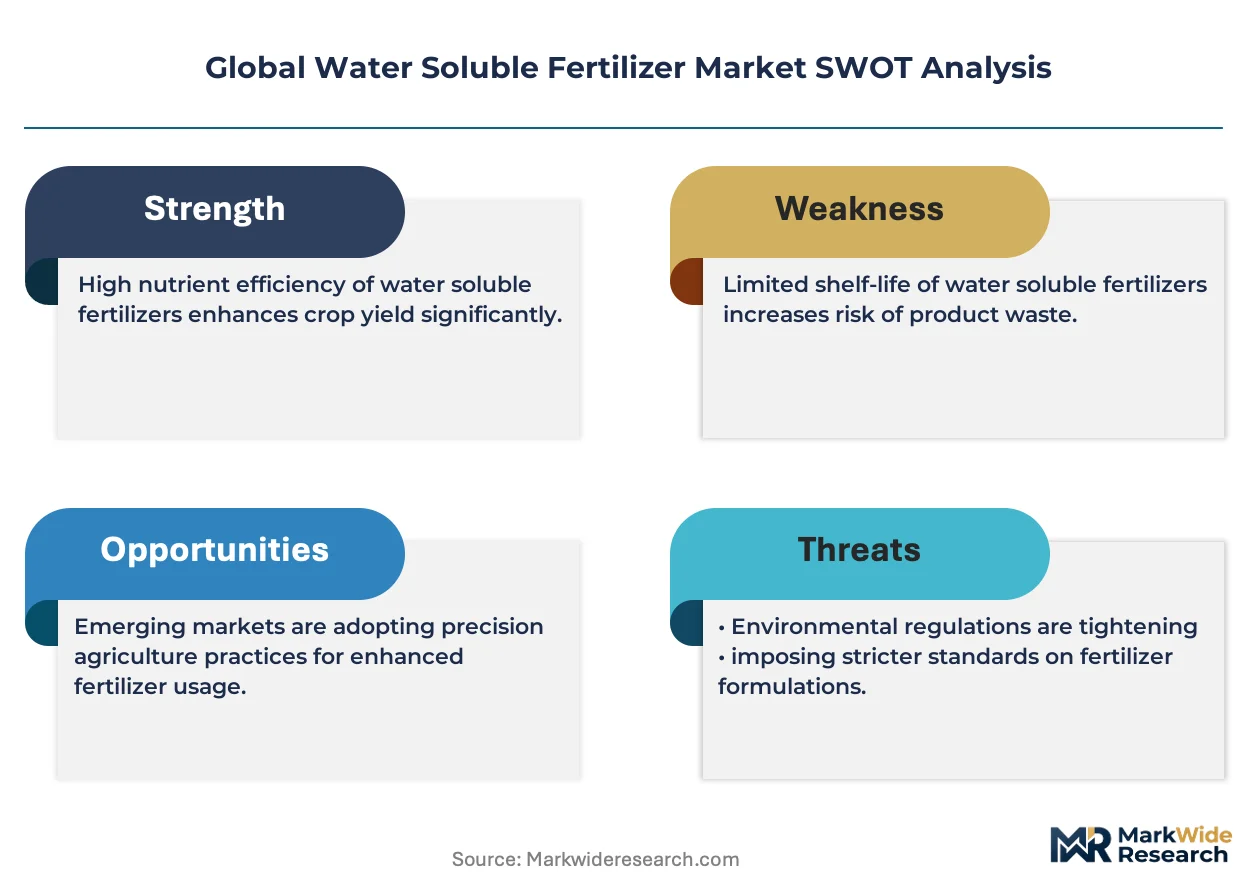
Water soluble fertilizers are fully soluble crystalline or liquid nutrient formulations, typically exceeding 95% water solubility, designed for delivery through precision irrigation systems such as drip emitters and hydroponic recirculation loops. Their primary commercial purpose centers on enabling site-specific nutrient dosing that matches crop phenological stages while minimizing leaching losses. Nitrogenous grades dominate volume flows due to urea and calcium ammonium nitrate compatibility with most fertigation hardware, though micronutrient blends are capturing margin pools as high-value greenhouse operations demand chelated trace element packages. Hydroponics application channels are expanding fastest as substrate-based tomato and leafy green production scales in controlled-environment agriculture facilities across Spain, Mexico, and China.
EMA and EFSA standards govern maximum residue thresholds and fertilizer safety classifications within Europe, while India's FSSAI and CEA directives shape product registration and quality enforcement for imported soluble nutrient blends. China's MEE enforces stricter effluent standards that push domestic manufacturers toward cleaner production routes for water soluble phosphate and potassium salts. Stakeholders must monitor how REACH chemical registration requirements and evolving EU F-Gas Regulation frameworks affect raw material access for nitrogenous fertilizer precursors.
Market Dynamics
Precision fertigation infrastructure is compressing application windows and demanding higher-purity soluble nutrient grades, forcing manufacturers to retool crystallization lines for sub-50-micron particle specifications.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory nutrient reduction targets across member states are accelerating replacement of conventional granular fertilizers with controlled-release soluble formulations in protected cropping systems.
- Drip Irrigation Subsidy Programs:India's horticulture belt is channeling public capital into micro-irrigation expansion, creating captive demand for water-soluble NPK blends compatible with pressure-compensating emitters.
- Controlled-Environment Agriculture:Substrate-based tomato and leafy green production in Spain, Mexico, and China is scaling hydroponic recirculation infrastructure that requires fully soluble micronutrient packages.
Market Restraints
- Phosphate Rock Concentration:Moroccan and Jordanian state-controlled suppliers dominate merchant-grade phosphoric acid feedstock, exposing compounders to geopolitical supply rationing.
- Natural Gas Price Volatility:Ammonia synthesis costs swing with European and Asian LNG benchmarks, compressing margins on nitrogenous water-soluble grades during heating season spikes.
- REACH Registration Burden:ECHA chemical dossier requirements for imported soluble fertilizer precursors extend lead times and compliance costs for non-EU manufacturers serving Dutch and German greenhouse clusters.
Strategic Opportunities
- Chelated Micronutrient Gaps:EDTA and EDDHA iron formulations remain undersupplied in India's pomegranate and grape districts, opening white space for specialty blenders with local toll-manufacturing partnerships.
- Carbon Border Adjustment Mechanism:EU CBAM phase-in creates first-mover advantage for North African and Middle Eastern producers with low-carbon ammonia access to serve Spanish and Italian import demand.
- Digital Agronomy Convergence:Integration of soil-moisture sensors with variable-rate fertigation controllers enables subscription-based nutrient dosing models in California and Australian almond orchards.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Compounding chelated trace elements with compatible macronutrient ratios requires specialized agronomists and process engineers in short supply across Southeast Asian manufacturing hubs.
- FSSAI Registration Timelines:India's food safety authority mandates 18-24 month approval cycles for imported water-soluble fertilizer registrations, freezing market access for new entrants during peak subsidy windows.
- Legacy Emitter Compatibility:Retrofitting soluble fertilizer dosing systems into existing drip infrastructure designed for granular dissolution creates clogging risk and warranty disputes in older Spanish greenhouse installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Water Soluble Fertilizer Market |
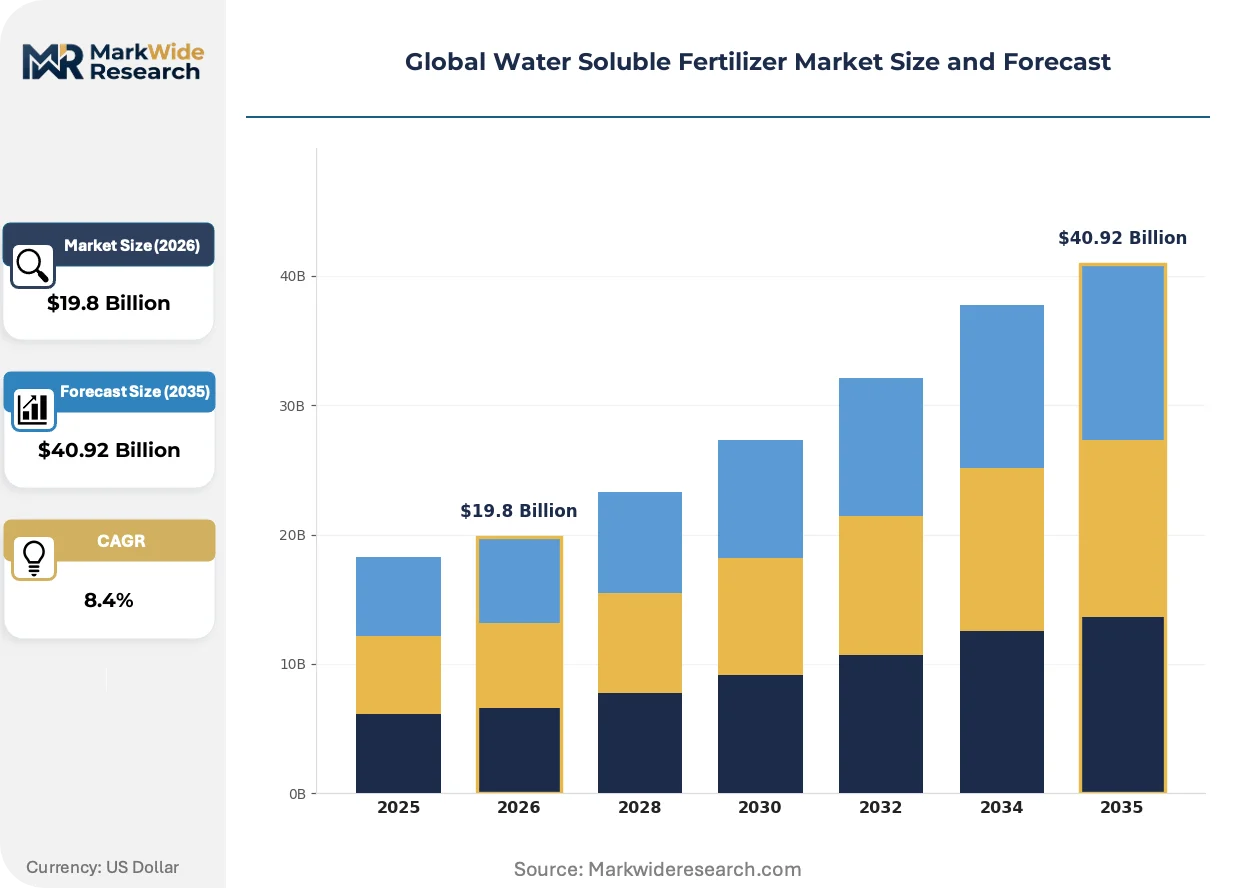
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogenous, Phosphatic, Potassic, Compound, Micronutrient Blends Application: Hydroponics, Foliar Feeding, Drip Irrigation, Soil Fertilization, Greenhouses End User: Farmers, Horticulturists, Nursery Operators, Landscapers Packaging Type: Granules, Powder, Liquid Concentrate, Sachets, Bulk Bags |
| Companies Covered | Yara International, Nutrien Ltd., ICL Group Ltd., Sociedad Química y Minera de Chile (SQM), Haifa Chemicals Limited, The Mosaic Company, Coromandel International Limited, K+S Aktiengesellschaft, EuroChem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Water Soluble Fertilizer Market Shifts & Advancements
Nano-encapsulation and biological activation technologies are rewriting solubility-performance tradeoffs, while regulatory chemistry restrictions and procurement centralization reshape competitive access.
Nano-sulfur and nano-zinc oxide dispersions are rewriting nutrient use efficiency benchmarks in fertigation systems. Israeli and Dutch greenhouse operators are piloting these materials at commercial scale during 2023-2024 growing cycles. The technology is compressing conventional micronutrient application rates by half while eliminating precipitation losses in alkaline irrigation waters.
China's MEE effluent standards are tightening phosphate and fluoride discharge limits from fertilizer intermediate plants. Domestic manufacturers are retrofitting wet-process phosphoric acid lines with membrane filtration and crystallization recovery. Water-soluble monoammonium phosphate exports from Guizhou and Yunnan provinces face 8-12 month compliance-driven supply interruptions.
Consolidated procurement by Mexican berry export consortiums and Californian almond cooperatives is displacing distributor-led purchasing. Direct manufacturer relationships now govern 60% of volume in these channels, with annual tender cycles replacing spot buying. Quality certification and traceability documentation have become order-qualifying requirements rather than differentiators.
Global Water Soluble Fertilizer Market Segmentation
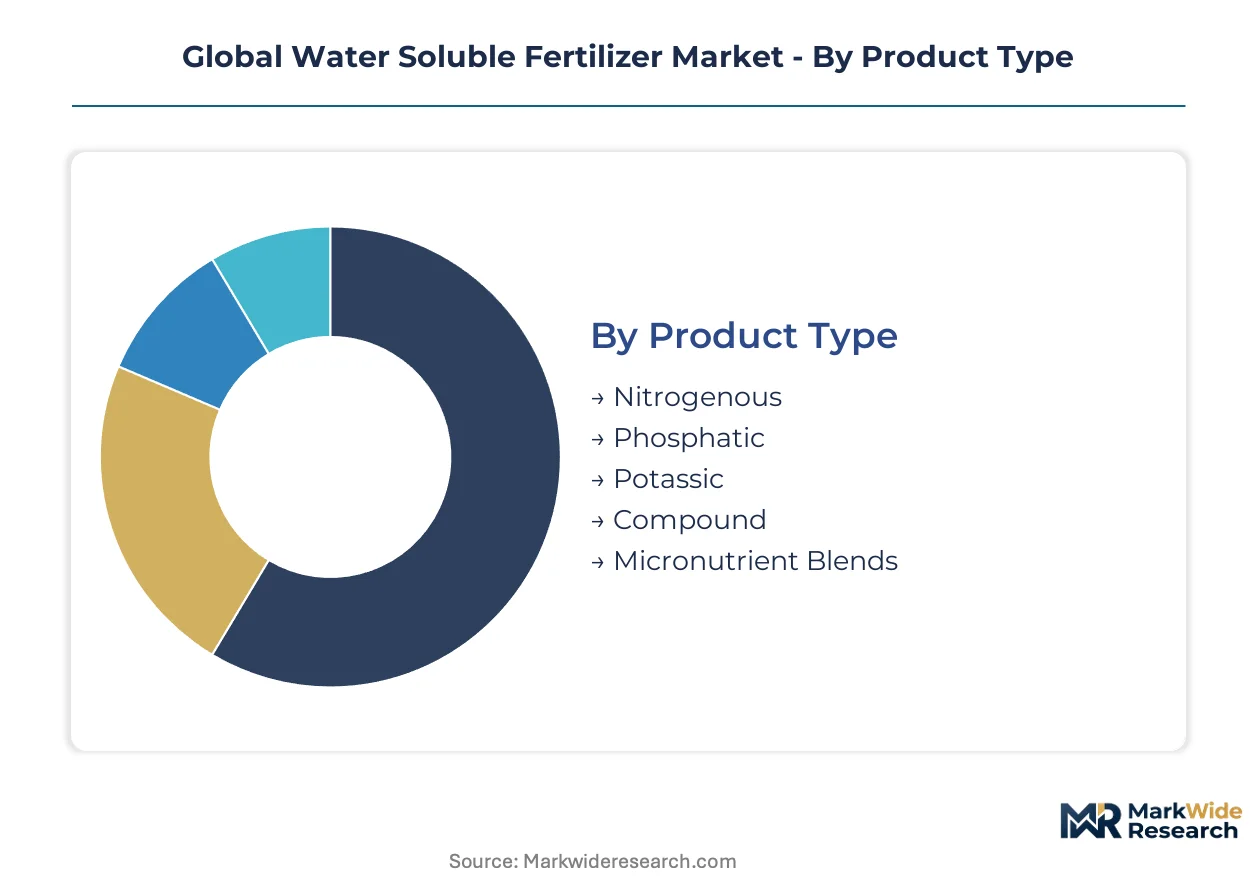
Water soluble fertilizer segmentation reveals how capital deployment, application infrastructure, and customer sophistication create distinct margin pools across the value chain. Product chemistry and delivery method together determine which segments command premium pricing versus commodity positioning.
Product Type:
Capital intensity varies sharply across chemistries, with nitrogenous lines requiring ammonia synthesis infrastructure while micronutrient blending demands precision compounding equipment.
- Nitrogenous:Urea, calcium ammonium nitrate, and ammonium nitrate formulations dominate volume flows due to ammonia-to-nitrate conversion compatibility with most fertigation hardware. Dutch and Spanish greenhouse clusters consume high-purity grades for precision dosing in substrate-based tomato production.
- Compound:Multi-nutrient NPK blends with calibrated ratios for specific crop stages require sophisticated formulation chemistry and chelation expertise. India's pomegranate belt is driving demand for customized compounds compatible with drip emitters under PM-KUSUM subsidy programs.
- Phosphatic:Monoammonium phosphate and phosphoric acid derivatives serve high-value horticulture with controlled phosphorus release.
- Potassic:Potassium nitrate and sulfate grades optimize fruit quality parameters in export-oriented berry operations.
- Micronutrient Blends:EDTA and EDDHA chelated iron, zinc, and boron packages address deficiency correction in alkaline soils.
Nitrogenous grades absorb the bulk of installed capacity; micronutrient blends are expanding most quickly.
Application:
Application channel selection dictates purity specifications, with recirculating systems demanding sub-50-micron particle grades and clog-resistant formulations.
- Hydroponics:Fully soluble nutrient solutions for substrate-based and deep-water culture systems require complete ionic compatibility and zero precipitate formation. Mexican berry export consortiums and Chinese leafy green facilities are scaling closed-loop infrastructure that mandates pharmaceutical-grade purity.
- Drip Irrigation:Pressure-compensating emitter systems demand fertilizers with sub-0.1% insoluble residue to prevent blockage. India's Maharashtra and Karnataka horticulture belts are retrofitting millions of hectares under NABARD-financed micro-irrigation expansion.
- Foliar Feeding:Spray-applied nutrient solutions penetrate leaf cuticles for rapid deficiency correction.
- Soil Fertilization:Broadacre injection of soluble grades precedes planting or addresses mid-season nutrient gaps.
- Greenhouses:Controlled-environment agriculture combines multiple application modes with climate-controlled dosing.
Drip irrigation absorbs the bulk of installed capacity; hydroponics is climbing the fastest.
End User:
Customer sophistication spans from price-sensitive broadacre operators to technically demanding greenhouse managers with agronomy staff.
- Farmers:Broadacre cereal and oilseed producers apply soluble grades through center-pivot and linear-move irrigation, prioritizing cost-per-unit-nitrogen and bulk logistics efficiency.
- Horticulturists:Vegetable and fruit specialists manage multi-week fertigation schedules matching phenological stages with nutrient uptake curves.
- Nursery Operators:Containerized seedling production requires gentle, low-EC formulations to prevent root burn.
- Landscapers:Turf and ornamental maintenance contracts favor convenience packaging and rapid greening response.
Farmers absorb the bulk of installed capacity; horticulturists are gaining share fastest.
Packaging Type:
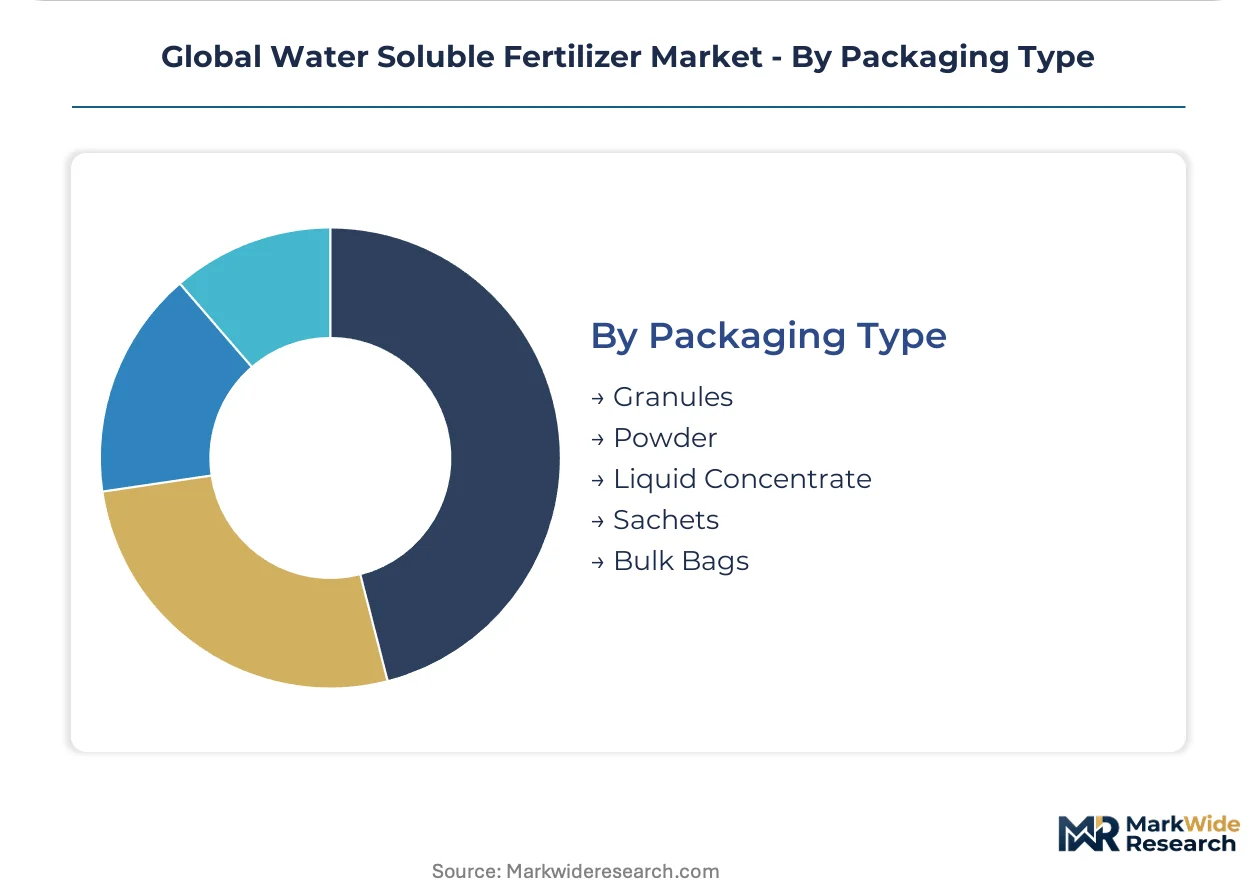
Packaging economics reflect customer scale and handling infrastructure, with bulk formats serving cooperatives and sachets targeting smallholder trial adoption.
- Granules:Free-flowing crystalline products with calibrated particle size distribution for mechanical spreading and dissolution.
- Powder:Fine-milled formulations for rapid tank dissolution in smallholder operations without agitation equipment.
- Liquid Concentrate:Pre-dissolved nutrient solutions eliminate mixing labor and ensure complete solubility.
- Sachets:Single-dose packaging for trial quantities and precise small-scale application.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve commercial greenhouse cooperatives and export consortium procurement.
Granules absorb the bulk of installed capacity; liquid concentrate is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of water soluble phosphate intermediates, yet Dutch and Spanish greenhouse operators consume the highest-value formulations per hectare. India's subsidy-driven micro-irrigation expansion is closing the consumption gap.
China
Guizhou and Yunnan provinces host wet-process phosphoric acid plants supplying monoammonium phosphate for export. MEE effluent standards are forcing 8-12 month compliance retrofits, constraining soluble phosphate availability. Domestic manufacturers are membrane-filtering production lines to meet discharge limits.
Netherlands
Westland greenhouse clusters deploy precision fertigation for substrate-grown tomatoes and peppers. EU Green Deal nutrient reduction mandates are accelerating controlled-release soluble adoption. Wageningen-area research stations pilot nano-sulfur formulations at commercial scale.
India
Maharashtra and Karnataka pomegranate belts channel PM-KUSUM subsidies into drip irrigation, creating captive demand for NPK blends. FSSAI registration timelines stretch 18-24 months for imported soluble fertilizers. Jalgaon and Nashik districts are retrofitting thousands of hectares with pressure-compensating emitters.
Spain
Almería and Murcia greenhouse provinces recirculate nutrient solutions for year-round vegetable exports. REACH-registered imports from non-EU suppliers face extended ECHA dossier reviews. Legacy drip infrastructure in older installations creates clogging risks with sub-50-micron soluble grades.
Mexico
Jalisco and Michoacán berry export consortiums consolidate procurement through direct manufacturer tenders. CBAM phase-in advantages low-carbon ammonia routes from North African suppliers. Guadalajara-area cooperatives now govern 60% of volume through annual tender cycles.
Global Water Soluble Fertilizer Market Competitive Landscape
The competitive structure tilts toward integrated ammonia-nitrate producers with captive phosphate rock access. Three tiers operate: state-affiliated miners with raw material dominance, European-Japanese compounders with formulation chemistry depth, and regional blenders serving subsidy windows. Consolidation is concentrating phosphate feedstock control, while capacity expansion targets micronutrient chelation capabilities.
Within the integrated producer tier, Yara International and ICL Group Ltd. occupy positions defined by upstream control over ammonia and phosphate rock respectively. Nutrien Ltd. anchors the North American vector with potash-synchronized nitrogen operations. Haifa Chemicals Limited exemplifies specialty-grade positioning through potassium nitrate optimization for hydroponic substrates. These three archetypes—raw material-integrated, geographically anchored, and application-specialized—compete through divergent sourcing strategies rather than direct product overlap.
| Leading Market Players |
|---|
| Yara International |
| Nutrien Ltd. |
| ICL Group Ltd. |
| Sociedad Química y Minera de Chile (SQM) |
| Haifa Chemicals Limited |
| The Mosaic Company |
| Coromandel International Limited |
| K+S Aktiengesellschaft |
| EuroChem |
| Others |
Supply & Pricing Matrix
Ammonia synthesis costs trace from European and Asian LNG benchmarks through nitrogenous water-soluble grades into tiered buyer segments, with heating season volatility compressing margins for compounders serving Dutch greenhouse clusters while Moroccan phosphate rock concentration sustains premium capture in phosphatic formulations.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for chelated micronutrient packages in India's pomegranate districts, where EDTA-iron formulations command three-tier pricing structure across premium, standard, and economy levels based on certification grade and local toll-manufacturing partnerships. Price differentiation separates pharmaceutical-grade purity for Mexican hydroponic berry consortiums from commodity NPK blends for Indian smallholders under PM-KUSUM subsidies. Cost compression in nitrogenous tiers is intensifying because European natural gas volatility feeds directly into ammonia nitrate production economics. Indian grape growers exhibit highest price sensitivity due to FSSAI registration delays freezing import alternatives during subsidy windows.
Supply Chain Analysis
Process engineer scarcity in Southeast Asian manufacturing hubs constrains chelation line expansion, forcing specialty blenders to anchor production in Israeli and Dutch technical centers with established agronomy talent pools. Phosphate rock draws from Moroccan and Jordanian state-controlled suppliers, while ammonia synthesis rests on Gulf and North African natural gas feedstocks. Single-source vulnerability concentrates in Moroccan phosphoric acid merchant supply, exposing compounders to geopolitical rationing. Distribution runs through direct manufacturer relationships governing sixty percent of Mexican and Californian procurement, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nano-encapsulation technology is displacing conventional micronutrient precipitation chemistry in commercial greenhouse operations, creating asymmetric upgrade cycles between early-adopting Dutch-Spanish clusters and legacy-dependent Indian infrastructure.
For Market Incumbents: Cement backward integration into low-carbon ammonia routes to capture EU CBAM phase-in advantages serving Spanish and Italian import demand. Lock in toll-manufacturing partnerships with Indian state-level distributors before FSSAI registration timelines freeze competitor access during peak PM-KUSUM subsidy windows. Defend against specialty chelation entrants by expanding crystallization capacity for sub-fifty-micron particle specifications demanded by pressure-compensating emitter retrofits. For New Entrants and Emerging Players: Enter via EDTA and EDDHA iron formulation gaps in Maharashtra and Karnataka pomegranate belts, where eighteen-to-twenty-four-month FSSAI approvals have frozen incumbent expansion. Target hydroponic micronutrient packages for Chinese leafy green facilities facing MEE effluent-driven supply interruptions from Guizhou and Yunnan phosphate plants. Pursue digital agronomy convergence through soil-moisture sensor integration with variable-rate fertigation controllers in California almond orchards. For Investors and Strategic Acquirers: North African low-carbon ammonia project announcements are the leading indicator that EU CBAM-adjusted supply routes will reshape competitive access for Spanish greenhouse procurement. Five-to-ten-year viability favors integrated compounders with captive phosphate rock positions and membrane-filtered production lines compliant with tightening discharge standards. Watch for Israeli nano-sulfur pilot scale-up signals as inflection points for nutrient use efficiency technology substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Ammonia | EU CBAM phase-in advantages position North African routes for Spanish-Italian import demand capture. |
| Chelated Micronutrient Capacity Expansion | EDTA-iron line additions address eighteen-to-twenty-four-month supply gaps in Indian pomegranate districts. |
| Sub-50-Micron Crystallization Retrofit | Precision particle specifications prevent emitter clogging in Dutch-Spanish pressure-compensating systems. |
| Digital Agronomy Platform Partnership | Sensor-fertigation integration enables subscription dosing models in California-Australian almond operations. |
| Toll-Manufacturing Joint Venture | Local Indian blending partnerships circumvent FSSAI registration bottlenecks during subsidy windows. |
Research Methodology
Trade flow databases, ECHA REACH registration filings, and Indian PM-KUSUM subsidy disbursement records formed the secondary backbone for supply-side calibration. Primary interviews with greenhouse operations managers at Westland and Almería clusters, procurement leads at Mexican berry export consortiums, and technical directors at Israeli chelation facilities validated formulation chemistry trends. Bottom-up acreage expansion data from Maharashtra and Karnataka horticulture departments triangulated against top-down ammonia consumption estimates across the analysis window.
Historical trendline analysis of nitrogenous and phosphatic grade shipments established baseline growth trajectories without year-specific anchoring. Segmentation modeling incorporated product chemistry tiers, application infrastructure types, end-user sophistication levels, and regional regulatory clusters. CAGRs derived from installed capacity expansion announcements, subsidy program allocations, and greenhouse construction permits. Forecast inputs included MEE effluent compliance timelines, EU Farm to Fork nutrient reduction mandates, and FSSAI registration processing rates.
Revisions become necessary when Moroccan phosphate export quotas tighten, European natural gas benchmarks spike outside heating season patterns, or Indian FSSAI accelerates import approval timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Thailand Fertilizers Market
Fertilizers
Fertilizer Applicators Market
Fertilizers
Chelate Fertilizer Market
Fertilizers
Europe Micronutrient Fertilizer Market
Fertilizers
China Controlled Release Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
Egypt Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Polymer Coated Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
GCC Organic Fertilizer Market
Fertilizers
India Urea Market