
 Crop Monitoring Market | 2026-2036
Crop Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Monitoring Market Analysis
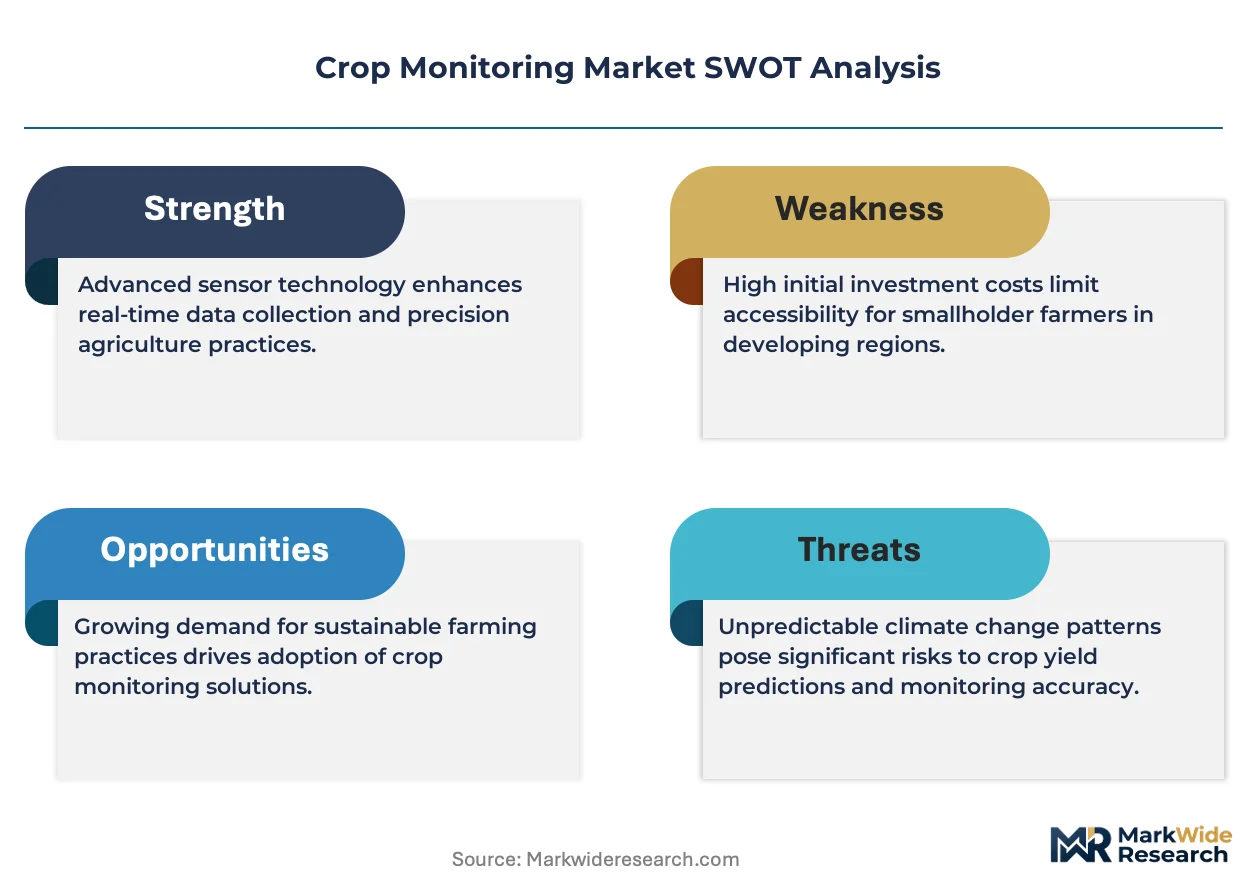
Multispectral sensor arrays is decoupling crop monitoring from manual scouting labor, collapsing per-hectare inspection costs by an order of magnitude. Trimble Inc. leverages its GNSS heritage to dominate field-level positioning accuracy for automated machinery guidance. John Deere anchors its competitive position through captive supply of integrated display terminals and cloud-connected agronomy platforms. CropX Technologies specializes in soil-moisture telemetry, competing directly against conventional tensiometer networks with wireless mesh deployments.
Crop monitoring encompasses the systematic acquisition, transmission, and analysis of biophysical crop data through airborne and ground-based sensor networks operating across visible, near-infrared, and thermal spectral bands, typically at spatial resolutions between 10 meters and sub-centimeter scales depending on platform altitude. The primary commercial purpose is to translate vegetation index fluctuations into actionable agronomic prescriptions for irrigation, fertilization, and pest intervention timing. Satellite imaging currently occupies the largest installed base due to broad-area coverage economics, though drone-based systems represent the fastest-expanding segment as battery endurance and onboard processing capacity improve. Software solutions command disproportionate margin pools relative to hardware devices because recurring subscription revenue attaches to data layers and predictive yield models. Data analytics tools increasingly differentiate through integration with weather forecasting APIs and commodity price feeds, creating decision-support dashboards that agribusiness companies prioritize over standalone imagery.
The EPA regulates pesticide application timing and buffer zones in the United States, directly shaping how monitoring data translates into regulatory-compliant spraying decisions, while the EU Green Deal's carbon-accounting requirements force European operators to document input-use intensity through auditable digital records. India's CEA and state agricultural departments promote IoT sensor adoption through subsidized precision agriculture pilots, though fragmented landholding patterns complicate platform economics for individual farmers. Stakeholders must weigh capital deployment toward autonomous drone fleets against satellite subscription models as spectral resolution and revisit frequency thresholds shift with climate volatility.
Market Dynamics
Variable-rate application systems tethered to satellite guidance are compressing input waste margins across Brazilian soybean operations, while EU Green Deal chemical-use reporting mandates force compliance architecture upgrades throughout European supply chains.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory chemical-use documentation creates captive demand for auditable digital monitoring platforms across European grain operations.
- Sub-centimeter GNSS positioning:Centimeter-level accuracy enables automated machinery guidance that eliminates overlap spraying and input waste in large-scale row-crop systems.
- Indian CEA subsidized pilots:State agricultural departments deploy cost-shared IoT sensor networks to overcome fragmented landholding economics in precision agriculture adoption.
Market Restraints
- Lithium-ion battery cost volatility:Drone fleet expansion faces margin pressure from raw material price swings in energy storage systems.
- Spectral resolution thresholds:Satellite revisit frequency limitations create data gaps during critical crop phenological windows that ground-based sensors must fill.
- REACH chemical authorization delays:Pesticide registration timelines in Europe compress the actionable window between detection and permitted application.
Strategic Opportunities
- Ukrainian grain belt reconstruction:Post-conflict agricultural modernization creates demand for full-stack monitoring infrastructure in Black Sea corridor operations.
- Wireless mesh soil telemetry:Soil-moisture sensor networks displace conventional tensiometer installations through lower per-node deployment costs.
- Australian carbon accounting integration:Commodity price feeds layered onto yield prediction dashboards attract agribusiness procurement prioritization over standalone imagery subscriptions.
Industry Challenges
- Agronomic data science talent scarcity:Interpretation of vegetation index fluctuations into prescription maps requires specialized skill sets that outpace university pipeline output.
- Legacy display terminal fragmentation:Proprietary machinery interfaces complicate third-party sensor integration and data portability across mixed-equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Monitoring Market |
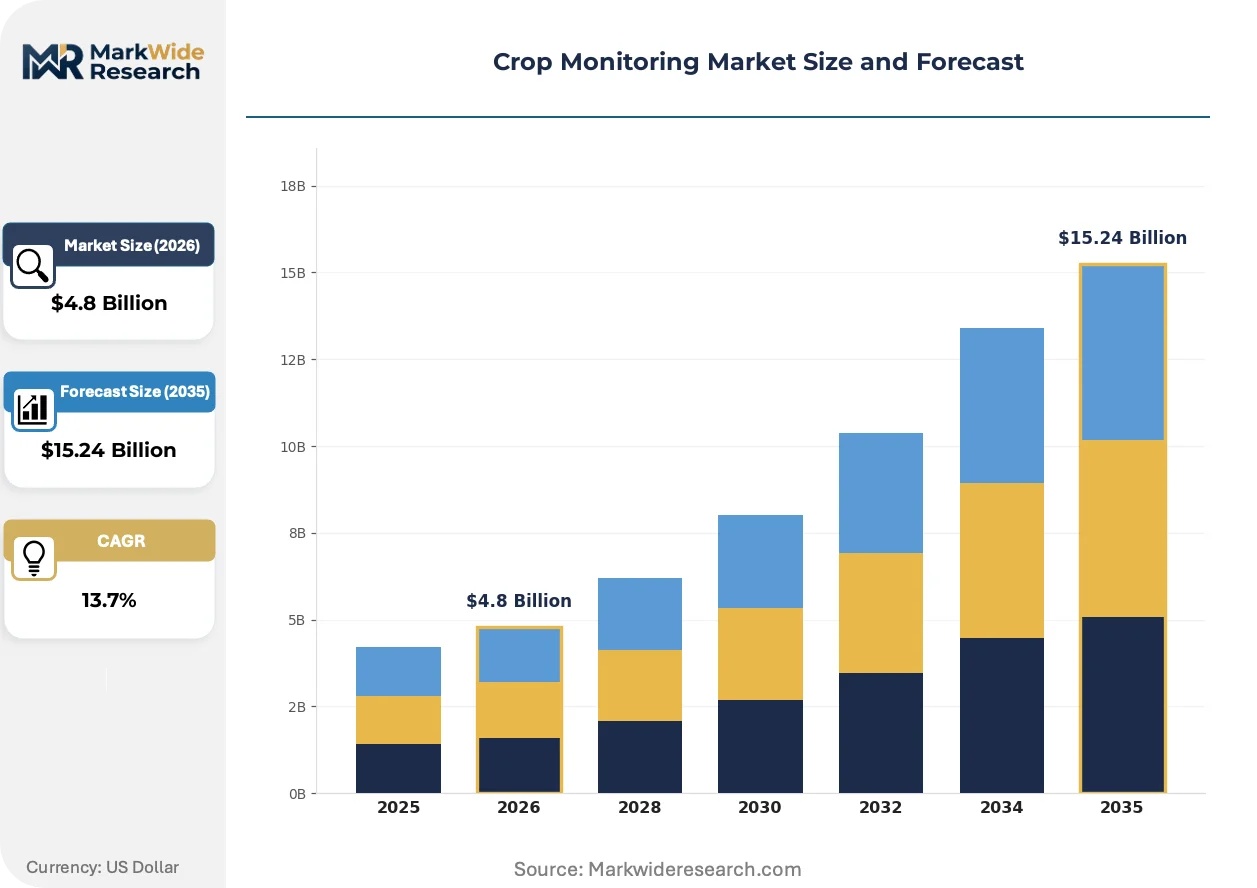
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Remote Sensing, Drones, IoT Sensors, Satellite Imaging Product Type: Software Solutions, Hardware Devices, Data Analytics Tools, Mobile Applications End User: Agricultural Cooperatives, Individual Farmers, Research Institutions, Agribusiness Companies Crop Type: Cereals, Fruits, Vegetables, Pulses |
| Companies Covered | Trimble Inc., John Deere (Deere & Company), Topcon Corporation, AGCO Corporation, Yara International, The Climate Corporation, CropX Technologies, Raven Industries, PrecisionHawk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Monitoring Market Emerging Trajectories
Multispectral sensor arrays are collapsing the labor economics of manual field scouting while regulatory pressure on input documentation accelerates platform consolidation around integrated data layers.
Hyperspectral imaging payloads mounted on fixed-wing drones are automating early-stage disease detection in vineyard and orchard operations. Large-scale wine cooperatives in France and Italy deploy these systems weekly during growing season. The technology is automating vineyard management decisions that previously required trained pathologist site visits, compressing response timelines from weeks to days.
EPA buffer zone regulations for pesticide application are reshaping how monitoring data translates into spray timing decisions. Operators must now document wind speed, temperature inversion risk, and proximity to water bodies through timestamped sensor logs. Specialty crop growers in California's Central Valley face the steepest compliance burden, driving adoption of integrated weather-monitoring drone stations.
Agribusiness procurement departments now prioritize decision-support dashboards that fuse yield models with commodity price feeds and weather APIs. Standalone imagery subscriptions lose share to bundled platforms. This preference shift concentrates most visibly among US Corn Belt grain elevators and Brazilian trading houses managing export logistics.
Crop Monitoring Market Segmentation
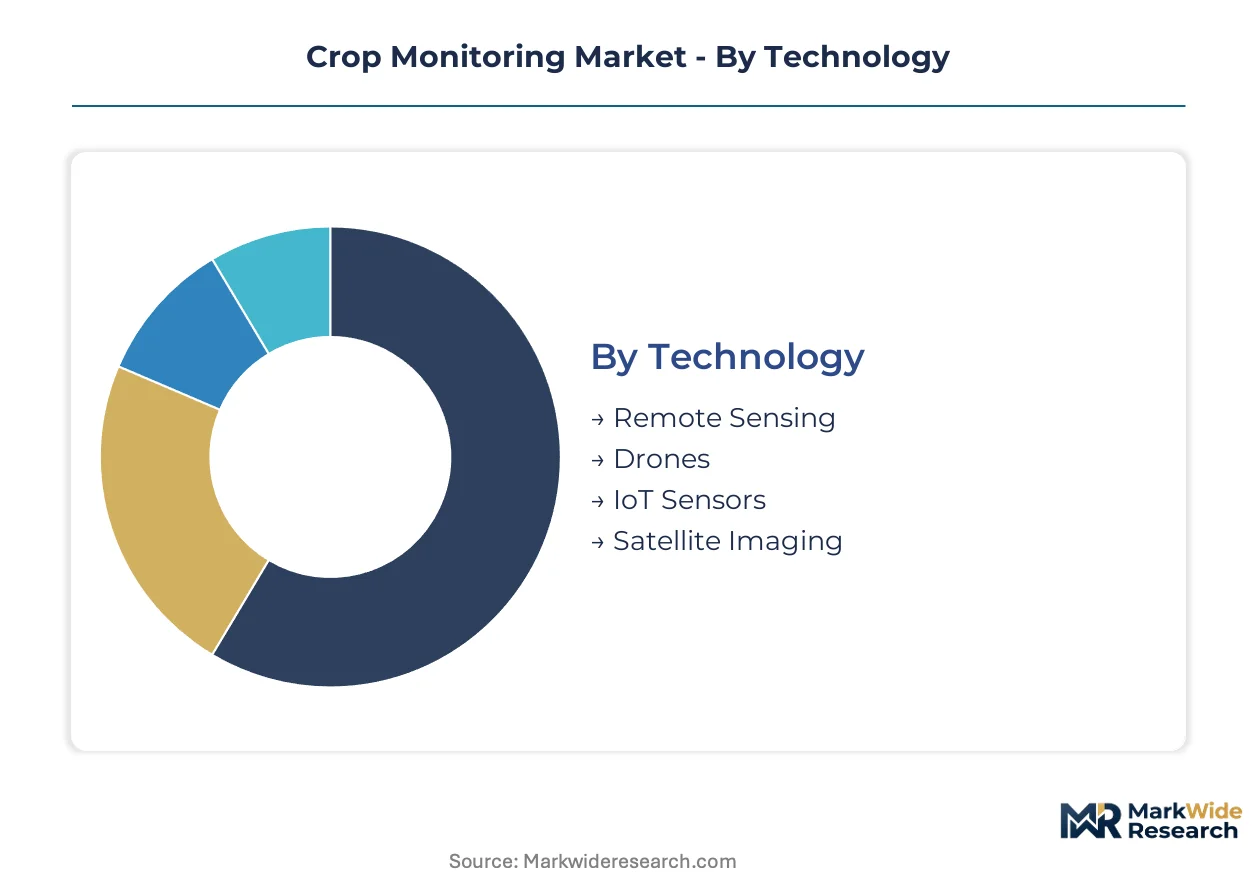
Crop monitoring vendors design pricing and deployment models around distinct technology cost tiers, product integration requirements, and end-user operational scales. Each segmentation axis reveals where margin pools concentrate and which customer segments drive platform consolidation.
Technology:
Technology selection hinges on spatial resolution requirements versus coverage economics, with buyers trading spectral granularity against per-hectare monitoring costs.
- Remote Sensing:Airborne platforms including manned aircraft and high-altitude balloons capture multispectral imagery at 0.5-5 meter resolution, serving regional crop insurance underwriters and commodity traders requiring broad-area yield forecasting across Ukrainian grain belts and Australian wheat regions.
- Drones:Unmanned aerial vehicles with sub-centimeter RGB and thermal payloads automate vineyard scouting and orchard disease detection in French wine cooperatives and California Central Valley specialty crop operations, though battery endurance limits daily coverage acreage.
- IoT Sensors:Soil-moisture telemetry nodes with wireless mesh connectivity displace conventional tensiometer networks through lower per-node deployment costs, concentrating demand in Indian CEA-subsidized precision agriculture pilots.
- Satellite Imaging:Constellation-based revisit frequencies now reach daily coverage for major agricultural zones.
Satellite imaging leads volumes today; drones are gaining share fastest through battery and onboard processing improvements.
Product Type:
Margin structure diverges sharply between recurring software subscriptions and one-time hardware sales, with procurement departments prioritizing bundled platforms over standalone components.
- Software Solutions:Cloud-connected agronomy platforms with vegetation index dashboards and prescription map generation command disproportionate margin pools through annual subscription renewals, particularly among Brazilian soybean estates and US Corn Belt grain elevators.
- Hardware Devices:Integrated display terminals, multispectral camera payloads, and soil-moisture probes generate upfront revenue with thinner recurring attachment, facing margin pressure from lithium-ion battery cost volatility in drone fleet expansions.
- Data Analytics Tools:Decision-support dashboards fusing yield models with weather forecasting APIs and commodity price feeds attract agribusiness procurement prioritization over standalone imagery subscriptions in Brazilian trading houses managing export logistics.
- Mobile Applications:Smartphone-based scouting apps with offline field-data capture serve individual farmers and smallholder cooperatives in fragmented landholding markets.
Software solutions capture the highest recurring margins; data analytics tools show the steepest expansion trajectory through API integration demand.
End User:
Scale economics determine platform viability, with large operators absorbing fixed infrastructure costs that exclude smaller holdings.
- Agricultural Cooperatives:Member-owned operations spanning thousands of hectares deploy shared sensor networks and variable-rate application systems across Brazilian soybean estates, amortizing precision agriculture investments across pooled acreage.
- Individual Farmers:Fragmented landholding patterns in India and Eastern Europe complicate platform economics, though subsidized IoT pilots and mobile app pricing tiers expand access.
- Research Institutions:Universities and agricultural extension services validate vegetation index algorithms and prescription accuracy, generating reference datasets for commercial platform calibration.
- Agribusiness Companies:Vertically integrated trading houses and input suppliers mandate compliance-grade documentation under EU Green Deal chemical-use reporting requirements.
Agribusiness companies drive premium platform adoption; agricultural cooperatives are expanding most quickly through shared infrastructure models.
Crop Type:
Monitoring intensity varies with crop value density and input sensitivity, with high-value perishables justifying more frequent spectral intervention than bulk commodities.
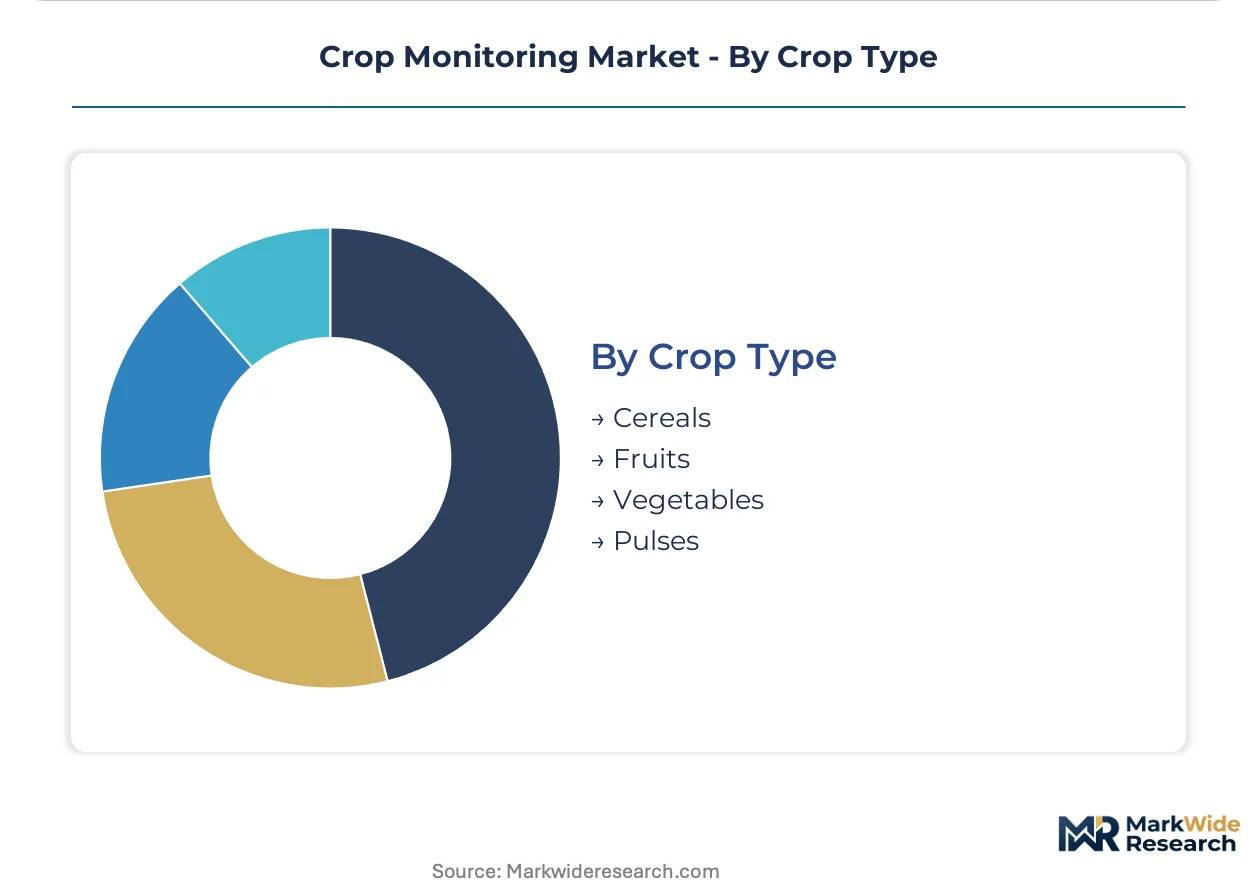
- Cereals:Wheat, corn, and soybean operations across the US Corn Belt and Ukrainian grain belts prioritize broad-area satellite coverage and variable-rate nitrogen application guided by NDVI fluctuations, generating the largest installed base by hectare.
- Fruits:Vineyard and orchard operations in France, Italy, and California deploy weekly hyperspectral drone surveys for early-stage pathogen detection, compressing response timelines from weeks to days.
- Vegetables:Specialty crop growers in California's Central Valley face EPA buffer zone compliance burdens that drive adoption of integrated weather-monitoring stations for spray timing documentation.
- Pulses:Chickpea and lentil cultivation in Australian wheat regions and Indian state agricultural department jurisdictions applies soil-moisture telemetry for irrigation optimization in water-constrained environments.
Cereals dominate hectare coverage; fruits command the highest per-hectare monitoring spend through disease detection premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Corn Belt anchors commercial deployment volumes, with precision agriculture corridors spanning Illinois, Iowa, and Nebraska generating concentrated demand for satellite-guided variable-rate application systems.
United States
EPA buffer zone regulations for pesticide application reshape how monitoring data converts into spray timing decisions. Specialty crop growers in California's Central Valley deploy integrated weather-monitoring drone stations to document wind speed and temperature inversion risk. Corn Belt grain elevators prioritize decision-support dashboards fusing yield models with commodity price feeds.
Brazil
Large-scale soybean estates drive satellite-guided variable-rate adoption across Mato Grosso and Paraná states. ANVISA chemical registration timelines compress actionable windows between pest detection and permitted application. Brazilian trading houses managing export logistics mandate bundled platforms over standalone imagery subscriptions.
India
CEA-subsidized IoT sensor pilots overcome fragmented landholding economics in Maharashtra and Gujarat. State agricultural departments deploy cost-shared wireless mesh soil telemetry networks. Pulses cultivation in water-constrained regions applies soil-moisture monitoring for irrigation optimization.
France
Wine cooperatives in Bordeaux and Burgundy deploy weekly hyperspectral drone surveys for early-stage pathogen detection. EU Green Deal Farm to Fork chemical-use documentation mandates create captive demand for auditable digital platforms. Vineyard operations command the highest per-hectare monitoring spend through disease detection premiums.
Australia
Wheat belt operations across Western Australia and New South Wales prioritize broad-area satellite coverage for yield forecasting. Carbon accounting integration attracts agribusiness procurement prioritization over standalone imagery. Soil-moisture telemetry networks displace conventional tensiometer installations through lower per-node deployment costs.
Crop Monitoring Market Vendor Landscape
Platform consolidation dominates the current landscape as recurring subscription revenue pools concentrate around integrated data layers. The vendor base stratifies across three tiers: diversified agricultural machinery conglomerates with captive display terminal supply, specialized soil telemetry and drone sensor providers, and pure-play cloud agronomy platforms. Two strategic archetypes define positioning: GNSS heritage players leveraging positioning accuracy for automated machinery guidance, and soil-moisture specialists competing against conventional tensiometer networks. M&A activity and API integration partnerships represent the dominant competitive vectors as procurement departments prioritize bundled decision-support dashboards.
Within the diversified machinery tier, John Deere exemplifies integrated platform architecture through captive supply of cloud-connected agronomy terminals. Trimble Inc. anchors the precision positioning segment, leveraging GNSS heritage for field-level accuracy in automated guidance systems. CropX Technologies occupies the specialized telemetry position, competing directly against conventional tensiometer networks with wireless mesh soil-moisture deployments. These three archetypes illustrate how competitive positioning crystallizes around hardware-software integration depth versus component specialization.
| Leading Market Players |
|---|
| Trimble Inc. |
| John Deere (Deere & Company) |
| Topcon Corporation |
| AGCO Corporation |
| Yara International |
| The Climate Corporation |
| CropX Technologies |
| Raven Industries |
| PrecisionHawk |
| Others |
Supply Flow & Price Mechanics
Agribusiness procurement departments now mandate bundled decision-support dashboards over standalone imagery subscriptions, forcing vendors to absorb sensor hardware costs into recurring SaaS tiers and compressing upfront margins across Brazilian trading houses and US Corn Belt grain elevators.
Pricing Analysis
Lithium-ion battery and multispectral sensor cost pass-through dominates hardware pricing, with drone fleet operators facing margin compression from raw material volatility. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade API-integrated platforms from basic vegetation index dashboards. Pricing pressure stems from EU Green Deal compliance documentation mandates that commoditize base-layer monitoring. Individual farmers in fragmented landholding markets exhibit highest price sensitivity; agribusiness companies show lowest sensitivity due to regulatory penalty avoidance.
Supply Chain Analysis
Reverse-logistics flows for sensor refurbishment and drone battery replacement concentrate service operations in the United States, Germany, and China. Component sourcing draws from Taiwanese semiconductor fabs for imaging processors, South Korean lithium-cell manufacturers for drone power systems, and Chinese PCB assembly for IoT telemetry nodes. Single-source vulnerability in GNSS chipset supply creates exposure to export control restrictions. Distribution runs through agricultural machinery dealerships and direct enterprise sales to large-scale cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in crop monitoring rests on software subscription attach rates rising as hardware commoditizes, with premium-tier decision-support dashboards capturing recurring revenue from compliance-driven documentation requirements.
For Market Incumbents: To counter hyperspectral drone specialists automating vineyard disease detection, John Deere and Trimble must deepen API integration partnerships with weather forecasting services and commodity price data providers. Captive supply of cloud-connected display terminals should extend to soil-moisture telemetry networks through acquisition of wireless mesh sensor specialists. For New Entrants and Emerging Players: Agricultural cooperatives in post-conflict Ukrainian grain belts represent the most penetrable white-space target, lacking integrated monitoring infrastructure and facing reconstruction-funded modernization. Mobile-first scouting apps priced for smallholder economics in Indian state-subsidized pilots offer a second entry vector. Partnership with state agricultural departments for cost-shared IoT deployment provides the critical go-to-market channel. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play cloud agronomy platforms possessing pre-trained yield prediction models and established API ecosystems. Long-term viability favors vendors whose software margins compound faster than hardware replacement cycles. Watch for inflection when satellite revisit frequency improvements eliminate data gaps during critical crop phenological windows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API fusion of yield models with weather forecasting services attracts Brazilian trading house procurement. |
| Acquisition of Specialist Firm | Wireless mesh soil telemetry specialists displace conventional tensiometer networks at lower per-node cost. |
| Geographic Expansion | Post-conflict Ukrainian grain belt reconstruction creates demand for full-stack monitoring infrastructure. |
| Product Launch | Hyperspectral drone payloads automate early-stage pathogen detection in French wine cooperatives. |
| Strategic Partnership | State agricultural department cost-sharing in India overcomes fragmented landholding economics. |
Methodological Framework
Direct dialogue with precision agriculture platform engineers, agribusiness procurement directors, agricultural cooperative managers, and regulatory compliance officers grounded the qualitative foundation. Secondary validation drew from EPA pesticide application filings, EU Green Deal implementation guidance, Indian CEA subsidy program disclosures, and Brazilian ANVISA chemical registration timelines. Bottom-up and top-down triangulation cross-checked sensor deployment counts against satellite imagery subscription revenues.
Bottom-up modeling built from hectare-level adoption rates across technology tiers, while top-down analysis tracked input supplier R&D allocations and machinery OEM connected-services revenue. Segmentation dimensions included platform altitude, spectral resolution tier, end-user operational scale, crop value density, and regional regulatory stringency. CAGRs derived from weighted-average technology substitution curves and compliance mandate enforcement timelines. Forecast inputs incorporated battery energy density improvement trajectories and constellation revisit frequency expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium raw material price volatility, REACH authorization delays compressing pesticide application windows, and fragmentation patterns in Indian landholding structures. Forecasts reflect documented assumptions regarding EU Green Deal enforcement intensity and satellite operator constellation deployment cadence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
United States Precision Farming Software Market