
 Americas Precision Farming Software Market | 2026-2036
Americas Precision Farming Software Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Precision Farming Software Market Outlook
Specialty crop growers is repositioning toward precision irrigation and drone-based canopy monitoring. Deere & Company dominates integrated hardware-software bundles across Midwestern grain operations. Trimble Inc. navigates GNSS-dependent field operations with strong channel control in precision guidance. AGCO Corporation extends its FendtONE platform to connect fleet management with agronomic decision layers.
Americas Precision Farming Software encompasses digital platforms that integrate geospatial data, sensor telemetry, and algorithmic field prescriptions to optimize input application and harvest logistics. These systems process sub-inch GPS correction signals, multispectral imagery bands, and soil electrical conductivity maps to generate executable task files for variable-rate equipment. Cloud-based deployment leads in new installations due to lower capital barriers and automatic feature updates, while on-premises systems persist in regions with unreliable cellular coverage. Yield monitoring and GPS soil mapping represent mature revenue pools with established farmer familiarity, whereas precision irrigation and drone analytics capture expanding margin pools as water stress intensifies across Western US and Brazilian Cerrado zones.
USDA NRCS Environmental Quality Incentives Program and EPA nutrient management guidelines shape platform requirements by mandating documented input reductions for cost-share eligibility. Brazil's MAPA digital agriculture initiatives and ANA water use regulations in water-stressed basins create compliance-driven demand for irrigation optimization modules. Stakeholders must monitor how evolving carbon credit verification protocols intersect with field-level data granularity standards to determine platform architecture investments.
Market Dynamics
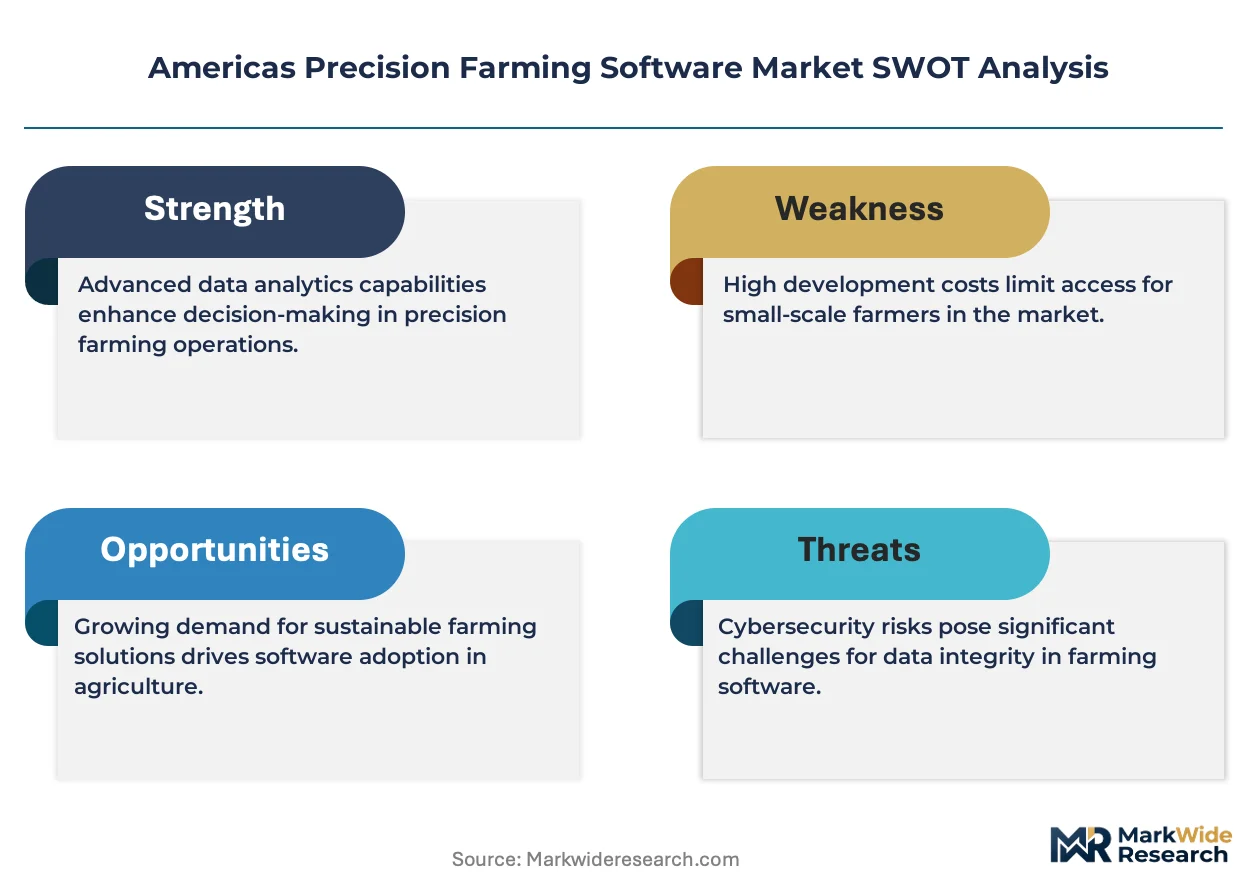
Subscription-based farm management platforms are compressing capital barriers for row-crop operators across the US Corn Belt, while USDA NRCS conservation compliance programs mandate documented input reductions that reshape platform architecture requirements.
Growth Catalysts
- USDA NRCS Environmental Quality Incentives Program:Cost-share eligibility tied to documented variable-rate input reductions accelerates platform deployment among Midwestern grain producers seeking compliance certification.
- Variable-rate input optimization:Corn Belt operators achieve measurable fertilizer and seed savings through algorithmic field prescriptions, creating demonstrable ROI that drives word-of-mouth adoption.
- Western US water stress:Precision irrigation modules capture expanding demand as basin-level allocation restrictions intensify across California Central Valley and High Plains aquifer zones.
Market Restraints
- Cellular coverage gaps:On-premises system persistence in Montana, North Dakota, and Brazilian Cerrado frontier zones limits cloud-native feature penetration and automatic update delivery.
- Hardware-software bundle lock-in:Integrated equipment ecosystems from dominant Midwestern machinery suppliers create switching friction for multi-vendor data interoperability.
- Data sovereignty requirements:Brazilian ANA water use regulations and state-level privacy frameworks impose localized server mandates that inflate platform deployment costs.
Strategic Opportunities
- ANA-regulated water basins:Irrigation optimization modules face underpenetration in São Paulo and Minas Gerais sugarcane zones where compliance-driven demand remains nascent.
- Carbon credit verification protocols:Emerging field-level data granularity standards create white space for platforms that integrate soil carbon quantification with agronomic decision layers.
- Drone-based canopy monitoring:Specialty crop growers in California's Central Valley and Pacific Northwest berry regions represent untapped demand for multispectral analytics beyond grain operations.
Industry Challenges
- Sub-inch GPS correction expertise:Agronomic advisory networks lack sufficient personnel trained in RTK-GNSS signal management and electrical conductivity map interpretation.
- Legacy equipment integration:Mixed-fleet operations struggle to execute variable-rate task files across machinery generations with incompatible ISOBUS implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Precision Farming Software Market |
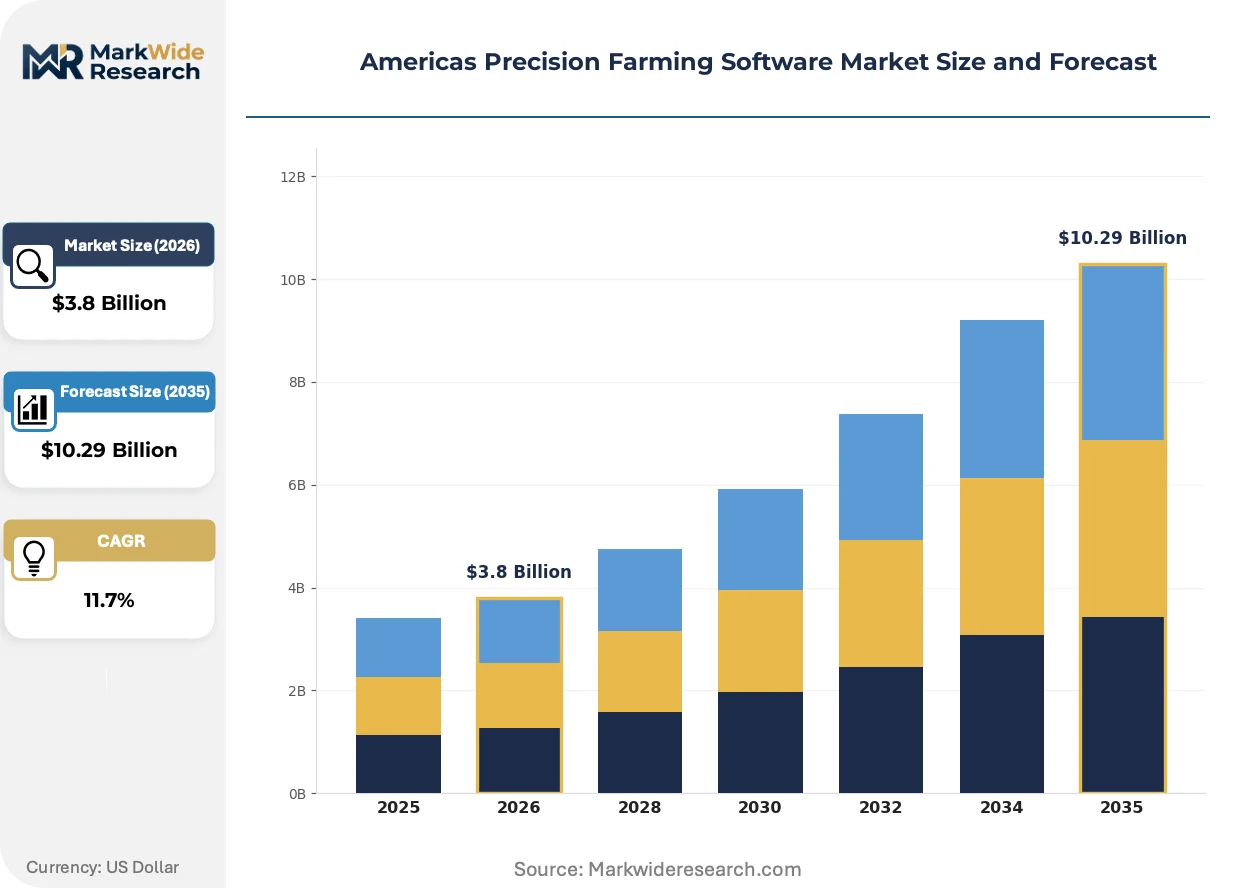
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Farm Management Software, Yield Monitoring, Precision Irrigation, GPS Soil Mapping Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Applications End User: Farmers, Agricultural Cooperatives, Agribusinesses, Research Institutions Technology: IoT Sensors, Drones, Data Analytics, Remote Sensing |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Corteva Agriscience, Raven Industries, Ag Leader Technology, AgJunction, AgEagle Aerial Systems, Bayer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Precision Farming Software Market Strategic Shifts
Algorithmic field prescription engines are compressing decision cycles from seasonal to real-time, while regulatory data mandates and procurement model evolution reshape how platforms capture value across the Americas agricultural technology stack.
Cloud-native farm management platforms are consolidating previously fragmented point solutions—yield monitoring, soil mapping, and input logistics—into unified subscription stacks. Mid-scale Corn Belt operators now demand single-vendor data continuity rather than piecing together best-of-breed modules. This consolidation is compressing margins for standalone soil analytics providers and forcing API-first architecture investments.
Brazil's ANA water use regulations in stressed basins now mandate flow-meter telemetry integration for irrigation cost-share eligibility. MAPA digital agriculture initiatives align with these requirements, pushing platform vendors to embed sensor hardware partnerships. Sugarcane and citrus operations in São Paulo state face the steepest compliance timelines, accelerating localized Portuguese-language support investments.
Outcome-based agronomic advisory contracts are displacing per-acre software licensing in the US Corn Belt. Retail agronomists at cooperative extension networks bundle platform access with fertility recommendations, capturing recurring revenue streams. This shift concentrates buyer power among multi-county cooperative systems in Iowa and Illinois, pressuring pure-software vendors to embed professional services.
Americas Precision Farming Software Market Segmentation
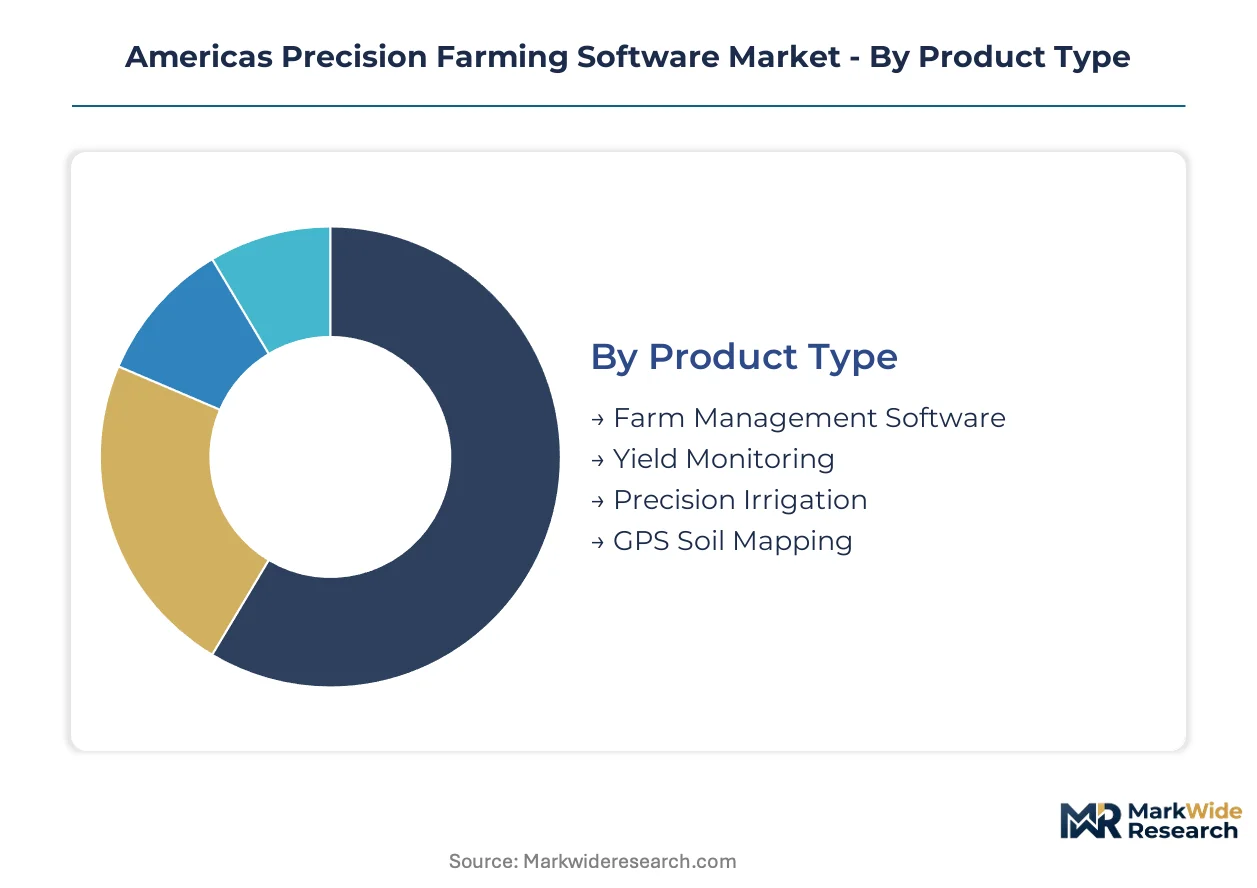
Precision farming software vendors architect product portfolios around distinct operational workflows, connectivity constraints, and buyer sophistication levels. Segment boundaries reflect how Corn Belt grain operators, Brazilian sugarcane processors, and California specialty crop growers differentially prioritize capital efficiency against data sovereignty.
Product Type:
Customization intensity varies sharply across this category, with configurable agronomic modules commanding premium positioning against standardized yield logging tools.
- Farm Management Software:Unified subscription platforms consolidate fragmented point solutions—yield monitoring, soil mapping, input logistics—into single-vendor data continuity stacks. Corn Belt cooperatives in Iowa and Illinois now bundle platform access with fertility recommendations, displacing per-acre licensing models.
- Yield Monitoring:Mature revenue pool with established farmer familiarity; GPS-enabled mass flow sensors generate sub-field productivity maps that feed algorithmic variable-rate prescriptions. Hardware-software bundle lock-in from Midwestern machinery suppliers creates switching friction for multi-vendor interoperability.
- Precision Irrigation:Flow-meter telemetry integration mandated by Brazil's ANA for cost-share eligibility in São Paulo sugarcane zones. Western US basin allocation restrictions intensify demand across California Central Valley and High Plains aquifer regions.
- GPS Soil Mapping:Electrical conductivity mapping and sub-inch GPS correction signals generate executable task files for variable-rate equipment. On-premises persistence in Montana and North Dakota cellular coverage gaps limits cloud-native penetration.
Most installed capacity flows through Yield Monitoring. Expansion is steepest in Precision Irrigation.
Deployment:
Connectivity infrastructure quality across the Americas dictates deployment architecture choices, with frontier agricultural zones forcing hybrid compromises.
- Cloud-Based:Lower capital barriers and automatic feature updates drive new installations; dominates where cellular coverage supports real-time telemetry upload. Brazilian ANA water use regulations impose localized server mandates that inflate deployment costs in regulated basins.
- On-Premises:Persist in Montana, North Dakota, and Brazilian Cerrado frontier zones with unreliable cellular coverage. Higher upfront capital requirements and manual update cycles limit adoption outside infrastructure-constrained regions.
- Hybrid Solutions:Edge computing architectures process field-level data locally while syncing aggregated analytics to cloud repositories. Appeals to mid-scale operators balancing real-time decision needs against intermittent connectivity.
- Mobile Applications:Smartphone-native interfaces for task file execution and scout note capture; limited standalone value without backend platform integration.
Cloud-Based deployment captures the majority of new procurement decisions. Hybrid Solutions are climbing the fastest as connectivity gaps persist.
End User:
Buyer scale and technical staffing depth segment procurement patterns, from individual operator subscriptions to enterprise-wide cooperative mandates.
- Farmers:Individual operators across US Corn Belt and Brazilian Cerrado prioritize demonstrable ROI through variable-rate fertilizer and seed savings. Word-of-mouth adoption accelerates where algorithmic prescriptions deliver measurable input reductions.
- Agricultural Cooperatives:Multi-county systems in Iowa and Illinois concentrate buyer power, bundling platform access with retail agronomist advisory services. USDA NRCS cost-share eligibility documentation reshapes platform architecture requirements.
- Agribusinesses:Large-scale row-crop operations repositioning procurement toward subscription-based farm management platforms with fleet-scale data continuity.
- Research Institutions:Field trial data granularity requirements drive demand for sub-inch GPS correction and multispectral analytics beyond commercial production needs.
Agricultural Cooperatives channel the largest procurement volumes. Farmers represent the steepest expansion trajectory as subscription models compress capital barriers.
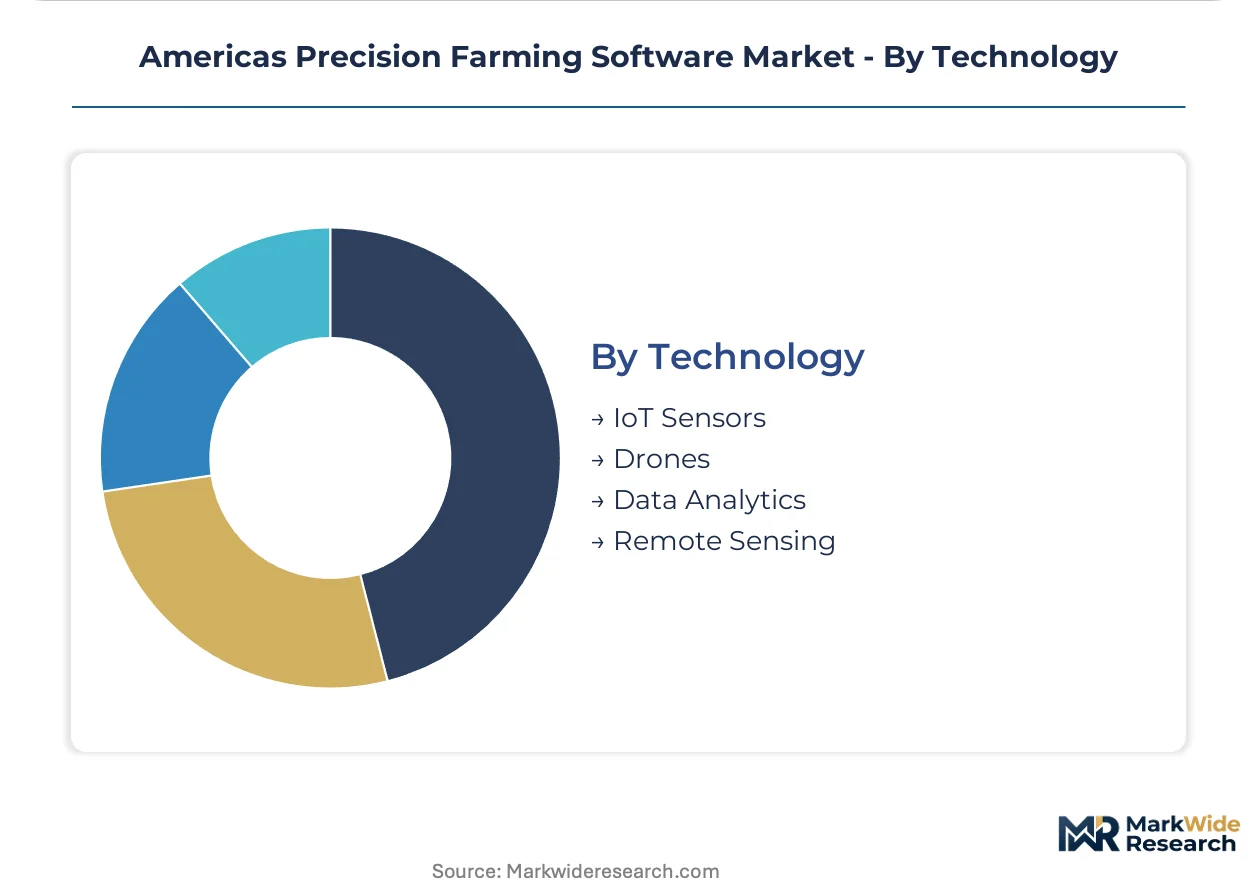
Technology:
Sensor hardware partnerships and analytics engine sophistication differentiate competitive positioning across the technology stack.
- IoT Sensors:Soil moisture probes, weather stations, and equipment telematics generate continuous field-condition data streams. Brazil's MAPA digital agriculture initiatives push vendors to embed sensor hardware partnerships for irrigation compliance.
- Drones:Multispectral canopy monitoring captures expanding demand from California Central Valley and Pacific Northwest berry specialty crop growers. ANA-regulated water basins in São Paulo and Minas Gerais represent underpenetrated demand.
- Data Analytics:Algorithmic field prescription engines compress decision cycles from seasonal to real-time; carbon credit verification protocols create white space for soil carbon quantification integration.
- Remote Sensing:Satellite-derived vegetation indices and yield forecasting at regional scale; lower granularity than drone analytics but broader coverage for portfolio-level risk management.
Data Analytics underpins value capture across all other technology segments. Drones are gaining share fastest as specialty crop applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting platform deployment patterns across the Americas as compliance cost differentials between US federal programs and Brazilian state mandates reshape vendor investment priorities. The USDA NRCS Environmental Quality Incentives Program and Brazil's ANA water basin regulations create divergent architectural requirements that favor localized server infrastructure in some markets and cloud-native stacks in others.
United States
Corn Belt grain operations in Iowa and Illinois drive concentrated demand for variable-rate input optimization platforms. The USDA NRCS mandates documented fertilizer reductions for cost-share eligibility, forcing platform vendors to embed audit-trail functionality. Multi-county cooperative systems in these states bundle software access with retail agronomist advisory services.
Brazil
Sugarcane and citrus processors in São Paulo state face accelerating compliance timelines under ANA water use regulations for stressed basins. MAPA digital agriculture initiatives align with flow-meter telemetry mandates, pushing vendors toward Portuguese-language support and localized server deployments. The Cerrado frontier zones persist with on-premises systems due to cellular coverage gaps.
Canada
Prairie Provinces grain operations in Saskatchewan and Manitoba prioritize subscription-based farm management platforms with fleet-scale data continuity. Health Canada PMRA nutrient management guidelines shape documentation requirements for variable-rate applications. The Red River Valley specialty crop zones show nascent demand for precision irrigation modules.
Mexico
Bajío Region vegetable and berry growers in Guanajuato and Querétaro states represent underpenetrated demand for drone-based canopy monitoring. The country's national agricultural regulator promotes digital agriculture adoption through extension network partnerships. Sinaloa's large-scale tomato operations are testing algorithmic field prescription engines for water stress management.
Americas Precision Farming Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated equipment ecosystems dominating Midwestern grain operations while standalone software vendors capture specialty crop niches. The vendor base concentrates around three strategic archetypes: machinery OEMs bundling hardware-software stacks, pure-play SaaS platforms targeting mid-scale operators, and sensor-embedded irrigation specialists. M&A activity focuses on API-first architecture acquisitions and regional compliance capability buildouts.
Within the integrated equipment tier, Deere & Company and AGCO Corporation anchor positions through captive distribution networks and fleet management connectivity. Trimble Inc. exemplifies the GNSS-dependent precision guidance archetype with strong channel control in field operations. Among specialty crop specialists, AgEagle Aerial Systems occupies a position representing drone-based canopy monitoring capabilities for California and Pacific Northwest berry regions.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Corteva Agriscience |
| Raven Industries |
| Ag Leader Technology |
| AgJunction |
| AgEagle Aerial Systems |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Captive hardware-software bundling by Midwestern machinery OEMs anchors supply positions and pricing power across the Americas Precision Farming Software landscape. This integration pattern compresses channel margins for standalone software vendors while concentrating buyer leverage among multi-county agricultural cooperatives in Iowa and Illinois.
Pricing Analysis
Distributor margin compression runs through subscription-based farm management platforms as Corn Belt cooperatives consolidate procurement power. Three-tier pricing structure across enterprise, professional, and grower levels differentiates by fleet scale and advisory service bundling. Cost compression in the entry tier is intensifying because cloud-native deployment lowers capital barriers for mid-scale operators. Individual farmers in Brazilian Cerrado frontier zones exhibit highest price sensitivity due to cellular infrastructure constraints forcing on-premises premiums.
Supply Chain Analysis
Regional distribution centers in Des Moines, São Paulo, and Calgary anchor hub-and-spoke patterns for precision agriculture hardware-software bundles. Manufacturing concentration rests on the United States, Brazil, and Canada for platform development, with sensor hardware sourcing from Taiwan and South Korea. Single-source vulnerability in RTK-GNSS correction signal networks creates exposure for sub-inch accuracy-dependent operations. Distribution runs through captive OEM dealer networks in Midwestern grain territories and independent agronomic advisory channels in specialty crop regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas Precision Farming Software market reads as a late-cycle quality story as Corn Belt operators shift procurement toward unified subscription stacks with embedded professional services. Premium specifications now center on algorithmic field prescription engines with documented audit trails for USDA NRCS compliance certification.
For Market Incumbents: Deepen API-first architecture investments to defend against pure-play SaaS challengers eroding standalone soil analytics margins. Prioritize backward integration into sensor hardware partnerships for Brazilian ANA-regulated water basin compliance. Channel control through multi-county cooperative systems in Iowa and Illinois remains the critical defensive lever against platform unbundling. For New Entrants and Emerging Players: Agricultural extension networks in Mexico's Bajío Region offer white-space access for drone-based canopy monitoring deployment. California Central Valley specialty crop growers represent the most penetrable segment given underdeveloped multispectral analytics adoption outside grain operations. Portuguese-language platform localization unlocks São Paulo sugarcane processor procurement cycles. For Investors and Strategic Acquirers: Roll-up economics work for precision irrigation specialists because ANA water use regulations in Brazilian stressed basins create compliance-driven demand concentration with limited vendor alternatives. Five-to-ten year viability hinges on carbon credit verification protocol integration capabilities. The signal to watch is field-level data granularity standard adoption by emerging soil carbon quantification registries.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies yield monitoring, soil mapping, and input logistics into single-vendor data continuity stacks for Corn Belt cooperatives. |
| Geographic Expansion | Portuguese-language localization and localized server deployment capture ANA-regulated water basin compliance demand in São Paulo. |
| Strategic Partnership | Sensor hardware partnerships embed flow-meter telemetry for Brazil MAPA digital agriculture initiative alignment. |
| Acquisition of Specialist Firm | API-first architecture targets consolidate fragmented point solutions and compress standalone soil analytics margins. |
| Product Launch | Algorithmic field prescription engines with USDA NRCS audit-trail functionality address documented input reduction mandates. |
Study Parameters
Multiple input streams — primary interviews with precision agriculture platform executives, agronomic advisory network leads, and cooperative procurement officers; secondary validation against USDA NRCS program documentation, ANA regulatory filings, and SEC 10-K equipment manufacturer disclosures; plus customs data on sensor hardware trade flows — were reconciled through bottom-up and top-down triangulation.
Historical adoption curves were cross-referenced against panel input from farm management software vendors and agricultural cooperative systems. Segmentation dimensions modeled span deployment architecture, buyer scale tier, crop type specialization, and regional regulatory cluster. CAGR derivation incorporated algorithmic prescription engine penetration rates and subscription model transition velocity across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon credit verification protocol standardization and cellular infrastructure buildout pace in Brazilian Cerrado frontier zones. Forecasts reflect assumptions about cooperative procurement consolidation and ANA compliance timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Precision Livestock Farming Market
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Global Advanced Farming Market