
 Autonomous Crop Management Market | 2026-2036
Autonomous Crop Management Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Crop Management Market Intelligence
Precision-grade autonomy is redrawing competitive boundaries in agricultural technology. Trimble leverages its dominance in GPS-guided steering systems to anchor premium positioning among broadacre operators. Raven Industries specializes in autonomous spraying and planting hardware, sustaining manufacturing scale that competes with diversified industrial portfolios. CropX differentiates through soil-sensor analytics, occupying the data-layer niche that connects ground-truth measurements to variable-rate prescriptions.
Autonomous crop management encompasses sensor-integrated, algorithm-driven systems that execute or recommend agronomic decisions with minimal human intervention, typically operating through machine learning models processing sub-inch GPS coordinates, multispectral imagery, and real-time soil moisture data to optimize input application and harvest timing. The primary commercial purpose centers on reducing per-unit production costs while maintaining yield stability across variable field conditions. Drones and soil sensors represent the fastest-expanding product categories, with drones capturing margin pools in early-season crop scouting and soil sensors deepening penetration in irrigated districts where water stewardship commands price premiums. Machine learning applications within yield prediction are displacing simpler statistical models, while computer vision in robotic harvesters remains concentrated in high-value specialty crops where bruise-free handling justifies capital intensity.
The US EPA regulates pesticide application rates and drift standards that autonomous sprayers must document, while USDA conservation programs incentivize precision nutrient management that drives platform adoption. The EU Green Deal and F-Gas Regulation shape equipment import requirements for multinational suppliers serving European growers. Stakeholders must monitor how evolving sustainability disclosure rules in multiple jurisdictions reshape data architecture requirements and customer procurement criteria.
Market Dynamics
Machine learning inference at the edge is compressing decision latency from days to minutes, forcing equipment manufacturers to re-architect around GPU-accelerated controllers rather than cloud-dependent workflows.
Growth Catalysts
- Labor scarcity economics:California's Central Valley and the US Corn Belt face acute seasonal worker shortages that accelerate payback calculations for autonomous tractors and robotic harvesters.
- USDA Environmental Quality Incentives Program:Precision nutrient management subsidies reduce net equipment costs for adopters of variable-rate application systems in water-stressed districts.
- Sub-inch RTK-GPS maturation:Correction signal density improvements enable centimeter-level steering without base stations, lowering entry barriers for mid-scale operators.
Market Restraints
- Semiconductor supply concentration:GPU and FPGA sourcing dependency on Taiwan-based foundries creates 26-40 week lead times for perception-compute modules.
- FAA Part 107 operational limitations:Beyond-visual-line-of-sight waivers for agricultural drones remain discretionary, capping autonomous scouting coverage per flight.
- Lithium-ion cell cost volatility:Battery-electric autonomous platforms face input cost swings that destabilize OEM pricing models and farmer TCO projections.
Strategic Opportunities
- Brazilian Cerrado mechanization:Soybean expansion into Mato Grosso and Goiás creates first-mover openings for autonomous planting fleets where labor pools are thin.
- Computer vision-robotics convergence:Integration of hyperspectral cameras with robotic end-effectors enables selective weeding in organic vegetable operations.
- EU Carbon Farming Initiative:Soil carbon measurement mandates generate demand for autonomous soil-sensor networks that verify sequestration claims.
Industry Challenges
- Mechatronics talent scarcity:Agricultural OEMs compete with automotive and aerospace for embedded systems engineers with ROS-2 and SLAM expertise.
- Interoperability certification delays:ISOBUS-TC compatibility testing for third-party implements extends product launch timelines by 8-14 months.
- Legacy fleet integration friction:Retrofit autonomy kits for 5-10 year-old tractors require hydraulic protocol translation that complicates dealer support models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Crop Management Market |
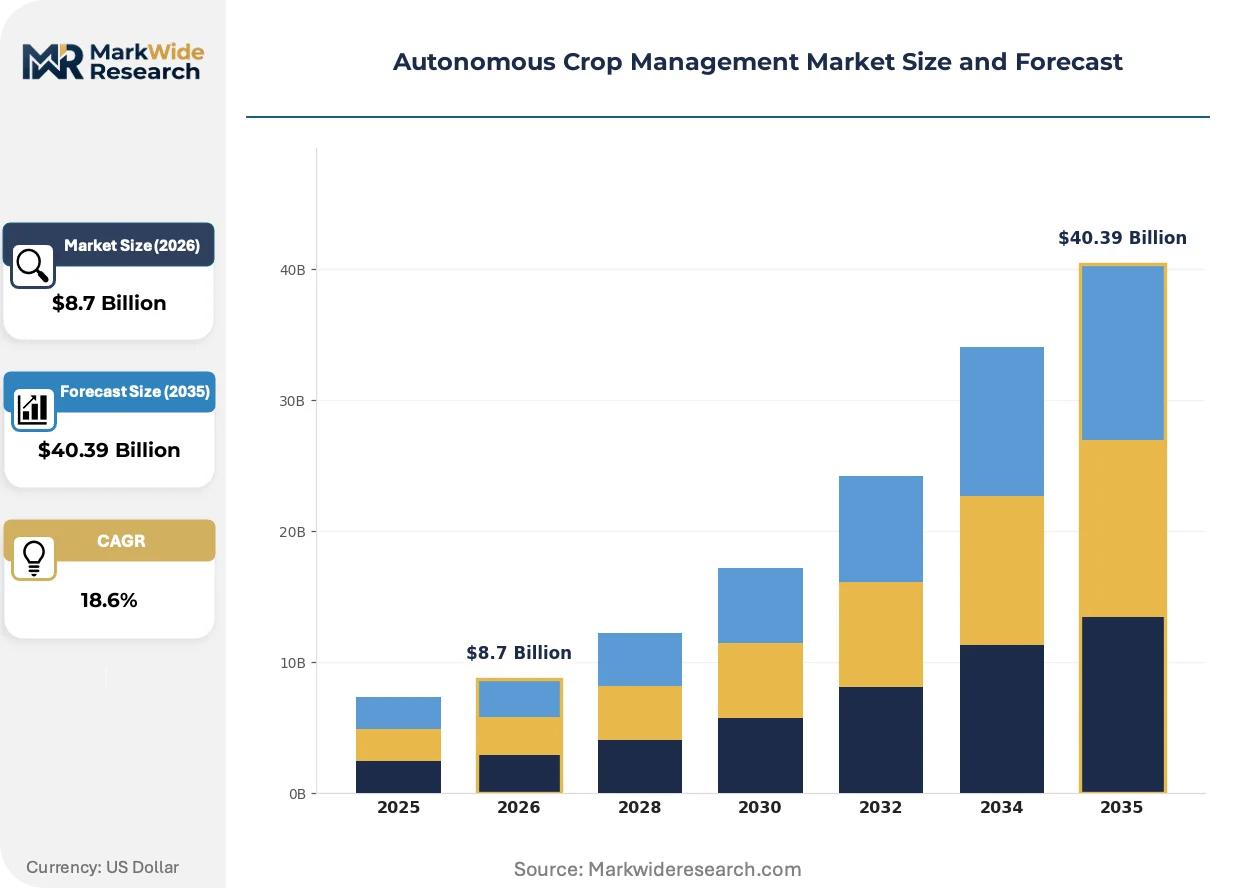
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Harvesters, Drones, Automated Planters, Soil Sensors Technology: Machine Learning, Computer Vision, IoT Connectivity, GPS Navigation End User: Large Scale Farms, Smallholdings, Agricultural Cooperatives, Research Institutions Application: Precision Agriculture, Crop Monitoring, Irrigation Management, Yield Prediction |
| Companies Covered | Trimble, Cropin, CropX, Agrivi, Croptracker, Granular, Conservis, Proagrica, Raven Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Crop Management Market Strategic Shifts & Innovations
Autonomous crop management is pivoting from single-task automation toward orchestrated multi-machine systems that coordinate planting, spraying, and harvesting through unified fleet management platforms.
Transformer-based computer vision architectures are supplanting convolutional neural networks for in-field weed identification, enabling real-time classification of 200+ species at 15 mph operating speeds. Large-scale row-crop operators in Iowa and Illinois are piloting these perception stacks on retrofitted sprayers. The shift is compressing herbicide application windows from 72-hour scouting cycles to same-day treatment execution.
The EU AI Act's high-risk system classification is mandating conformity assessments for autonomous harvesting equipment with human-proximity operation modes. Manufacturers must now document algorithmic decision logic and maintain post-market performance monitoring. Specialty crop producers in Spain's Almería greenhouse cluster face the steepest compliance burden as robotic tomato harvesters fall under the new requirements.
Subscription-based autonomy licensing is displacing perpetual equipment purchases among mid-scale Midwestern grain operations. John Deere's Operations Center and Raven's Slingshot platform unbundle software access from iron ownership. The model concentrates adoption in Kansas and Nebraska where 2,000-5,000 acre farms prioritize operational flexibility over balance-sheet asset accumulation.
Autonomous Crop Management Market Segmentation
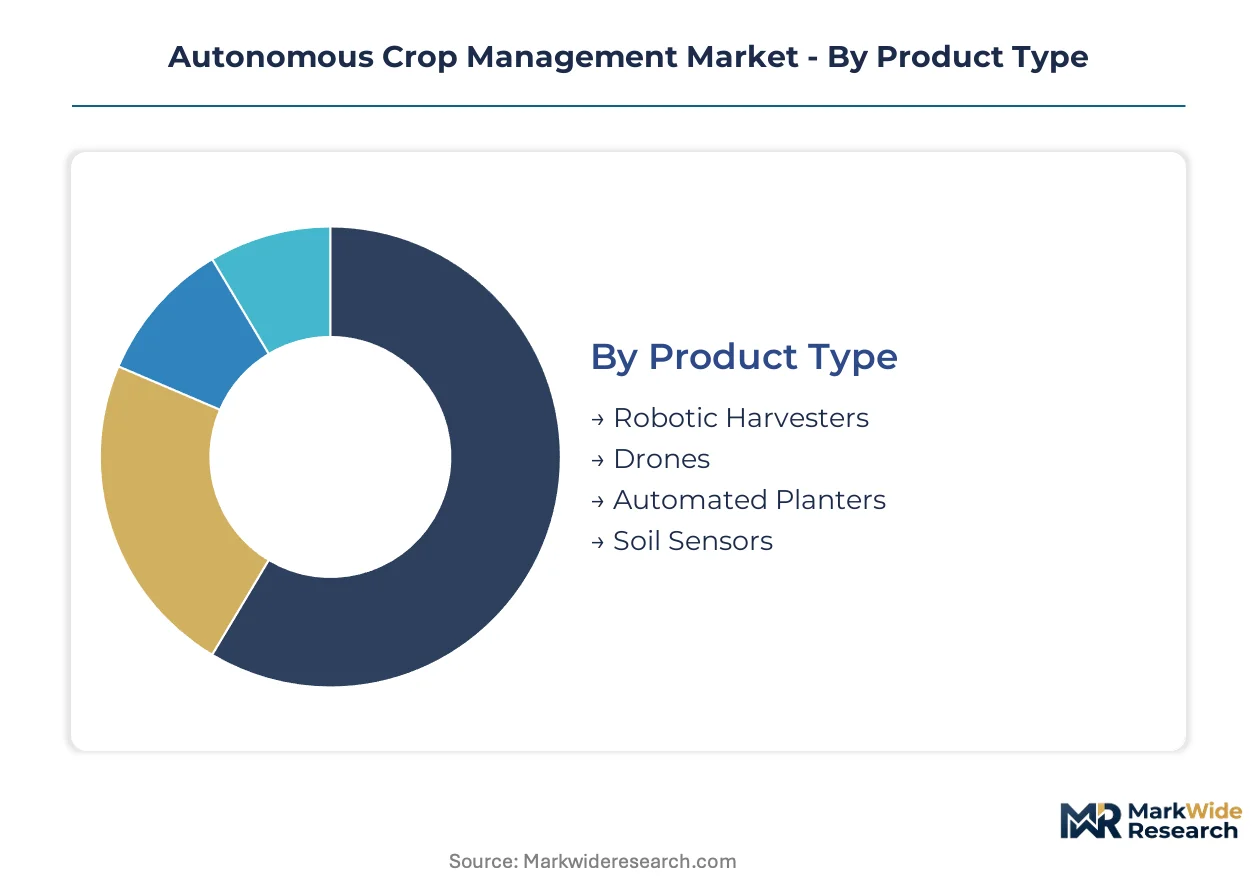
Autonomous crop management systems fragment across equipment categories, algorithmic architectures, and operator scale tiers. Regulatory compliance requirements diverge sharply between precision spraying drones and soil-carbon verification sensors, reshaping vendor R&D priorities and customer procurement criteria across each segment boundary.
Product Type:
EPA drift documentation mandates for autonomous sprayers and FAA Part 107 operational waivers for aerial platforms create divergent compliance burdens across hardware categories, concentrating vendor investment toward certifiable form factors.
- Robotic Harvesters:Electro-pneumatic end-effectors with bruise-detection algorithms handle delicate produce at 0.3-0.5 m/s cycle speeds. California's Central Valley specialty crop operations deploy these systems where labor scarcity exceeds $25/hour seasonal wages, though EU AI Act conformity assessments for human-proximity operation modes extend deployment timelines.
- Drones:Multispectral and hyperspectral camera payloads mounted on hexacopter frames capture NDVI and thermal stress indices at 15-50 meter altitude bands. Iowa and Illinois row-crop operators use these platforms for same-day herbicide prescription mapping, constrained by discretionary FAA beyond-visual-line-of-sight waiver availability.
- Automated Planters:RTK-GPS-guided seeding units with variable-rate population control execute sub-inch accuracy planting without base station dependency.
- Soil Sensors:Capacitance and TDR-based moisture probes with LoRaWAN backhaul provide ground-truth validation for irrigation scheduling in water-stressed districts.
Established volume favors robotic harvesters; emerging adoption favors drones.
Technology:
Edge inference requirements and cloud dependency trade-offs segment technology adoption by connectivity infrastructure maturity and latency tolerance across farm operations.
- Machine Learning:Transformer-based architectures process multispectral imagery for weed species classification at field-edge GPU accelerators, displacing cloud-dependent convolutional models. Kansas and Nebraska grain operations prioritize these systems where cellular coverage is intermittent, with USDA Environmental Quality Incentives Program subsidies reducing net implementation costs.
- Computer Vision:Stereo camera arrays with SLAM-based localization enable robotic navigation without GPS dependency in canopy-obstructed environments. Brazil's Mato Grosso soybean expansion zones deploy these perception stacks where RTK correction signal density remains sparse.
- IoT Connectivity:Low-power wide-area networks aggregate sensor telemetry across distributed field deployments.
- GPS Navigation:Multi-constellation receivers with RTK correction achieve centimeter-level steering accuracy for autosteer applications.
Hardware intensity concentrates in computer vision; software margin pools concentrate in machine learning.
End User:
Capital access and operational scale determine autonomy adoption patterns, with subsidy eligibility and fleet management complexity creating distinct customer archetypes.
- Large Scale Farms:Integrated fleet management platforms coordinate multi-machine planting and harvesting sequences across 10,000+ acre operations. US Corn Belt broadacre operators in Illinois and Iowa deploy these orchestrated systems, leveraging balance-sheet capacity for perpetual equipment purchases alongside subscription software licensing.
- Smallholdings:Retrofit autonomy kits for existing tractor platforms reduce entry costs for 500-2,000 acre Midwestern grain farms. Kansas and Nebraska operators in this tier prioritize operational flexibility through Raven's Slingshot and John Deere Operations Center unbundled software access.
- Agricultural Cooperatives:Shared equipment pools spread autonomous system costs across member growers with consolidated procurement power.
- Research Institutions:Experimental platforms for algorithm validation and cultivar-specific agronomic model development.
Equipment revenue concentrates at large scale farms; subscription growth concentrates at smallholdings.
Application:
Input cost reduction objectives and sustainability verification requirements segment application demand by commodity price environment and regulatory pressure intensity.
- Precision Agriculture:Variable-rate input application based on real-time sensor feedback optimizes fertilizer and pesticide use across spatially variable field zones. California's Central Valley operators deploy these systems where US EPA pesticide drift documentation mandates intersect with water stewardship price premiums.
- Crop Monitoring:Early-season stress detection through multispectral index trending enables intervention timing optimization. Spain's Almería greenhouse cluster applies computer vision-based monitoring for tomato and pepper operations under EU Green Deal sustainability disclosure requirements.
- Irrigation Management:Soil moisture sensor networks with predictive evapotranspiration models schedule water application in drought-prone districts.
- Yield Prediction:Machine learning models integrating weather, soil, and imagery data forecast harvest volume for supply chain planning.
Operational efficiency drives precision agriculture; compliance verification drives crop monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers cluster in industrial corridors where precision agriculture R&D infrastructure and subsidy programs intersect. Taiwan-based semiconductor foundries supply GPU and FPGA components for perception-compute modules, while regulatory frameworks in multiple jurisdictions reshape deployment timelines.
United States
Labor scarcity in California's Central Valley and the US Corn Belt accelerates autonomous tractor and robotic harvester deployments. The USDA Environmental Quality Incentives Program subsidizes variable-rate application systems, reducing net equipment costs for adopters. Iowa and Illinois row-crop operators pilot transformer-based computer vision stacks on retrofitted sprayers for same-day herbicide execution.
Brazil
Soybean expansion into Mato Grosso and Goiás creates first-mover openings for autonomous planting fleets where seasonal labor pools remain thin. ANVISA regulates agricultural chemical application standards that autonomous equipment must document for compliance. The Cerrado mechanization corridor concentrates deployment of GPS-guided seeding units with RTK correction independence.
Germany
ISOBUS-TC compatibility requirements for third-party implements extend product certification timelines, favoring established OEMs with dedicated compliance teams. The KBA oversees autonomous vehicle type approval for agricultural equipment operating in mixed-traffic scenarios. Bavaria's agricultural machinery cluster hosts testing facilities for human-proximity robotic harvesters under EU AI Act high-risk system classifications.
Spain
Almería's greenhouse tomato and pepper operations deploy computer vision-based monitoring systems under EU Green Deal sustainability disclosure mandates. The EU AI Act conformity assessment burden falls heaviest on robotic harvester manufacturers serving this cluster. Andalusian specialty crop producers prioritize bruise-detection algorithms for delicate produce handling at sub-meter cycle speeds.
Australia
Drought-prone districts in New South Wales and Victoria drive soil moisture sensor network adoption for predictive irrigation scheduling. The TGA oversees electromagnetic compatibility standards for wireless telemetry systems in agricultural deployments. Queensland broadacre operators integrate multi-constellation GPS receivers with sparse RTK infrastructure for autosteer applications across station-distant paddocks.
Autonomous Crop Management Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized precision agriculture technology providers. The vendor base spans three tiers: GPS navigation and steering system specialists, data-layer analytics platforms, and autonomous hardware fabricators. Consolidation pressures intensify as subscription-based software licensing displaces perpetual equipment purchases. Strategic moves center on fleet management platform unbundling and edge-compute architecture partnerships that reduce cloud dependency.
Within the navigation and guidance tier, Trimble anchors premium positioning among broadacre operators through its dominance in GPS-guided steering infrastructure. Raven Industries exemplifies the autonomous hardware fabrication archetype, sustaining manufacturing scale in spraying and planting equipment that competes with diversified industrial portfolios. CropX occupies the data-layer niche, connecting ground-truth soil measurements to variable-rate prescription workflows through sensor-integrated analytics platforms.
| Leading Market Players |
|---|
| Trimble |
| Cropin |
| CropX |
| Agrivi |
| Croptracker |
| Granular |
| Conservis |
| Proagrica |
| Raven Industries |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts for GPU and FPGA perception-compute modules lock in supply access and price visibility for agricultural OEMs navigating Taiwan foundry lead times. These arrangements stabilize input costs for edge-accelerated controllers while exposing buyers to lithium-ion cell volatility that destabilizes battery-electric platform pricing.
Pricing Analysis
The US EPA pesticide drift documentation mandate dictates the pricing tier structure across autonomous sprayer categories. Three-tier pricing structure across premium RTK-GPS integrated systems, standard cellular-corrected units, and economy manual-override configurations separates compliance-bundled offerings from basic hardware. Cost compression in the economy tier is intensifying because semiconductor supply concentration forces OEMs to absorb margin pressure or pass through component inflation. Smallholdings in Kansas and Nebraska exhibit highest price sensitivity, prioritizing subscription software unbundling over perpetual equipment purchases.
Supply Chain Analysis
Strategic stockpiling of GPU accelerators and RTK correction receivers dominates inventory strategy as agricultural OEMs buffer against Taiwan foundry lead times and sparse base station infrastructure. Hardware sourcing centers on Taiwan for perception-compute modules, South Korea for lithium-ion cells, and Germany for precision hydraulic components. Raw material dependencies span silicon wafers, rare earth magnets for electric drivetrains, and high-grade aluminum for lightweight chassis. Single-source vulnerability in Taiwan-based GPU fabrication creates supply chain risk. Distribution runs through dealer networks with certified technician support for hydraulic protocol translation and ISOBUS-TC compatibility validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous crop management represents a service-attach opportunity where subscription-based fleet management platforms and predictive maintenance contracts expand faster than iron sales. Recurring software revenue layers now command valuation premiums over hardware margins.
For Market Incumbents: Secure edge-compute architecture partnerships that reduce cloud dependency and compress decision latency for row-crop operators. Lock in mechatronics talent through ROS-2 and SLAM expertise retention programs before automotive and aerospace competitors exhaust the pipeline. Vertical integration into GPU sourcing buffers Taiwan foundry concentration risk. For New Entrants and Emerging Players: Anchor in Brazil's Cerrado mechanization corridor where soybean expansion into Mato Grosso and Goiás creates first-mover openings for autonomous planting fleets. Target organic vegetable operations in California's Central Valley with computer vision-robotics convergence for selective weeding. Pursue EU Carbon Farming Initiative verification contracts as the go-to-market angle. For Investors and Strategic Acquirers: Sensor-integrated analytics platforms with established soil-carbon measurement workflows represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance automation as the EU AI Act and US EPA documentation mandates expand. Watch FAA beyond-visual-line-of-sight waiver approval velocity as the inflection indicator for drone scouting scalability. Revision becomes warranted when semiconductor supply normalization crosses thresholds that collapse strategic stockpile premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Compute Architecture Partnership | GPU-accelerated controllers from Taiwan foundries reduce cloud dependency for Iowa row-crop operators. |
| Subscription Platform Unbundling | Software licensing separates from iron ownership for Kansas smallholdings prioritizing operational flexibility. |
| EU AI Act Conformity Investment | Algorithmic decision documentation opens Spain's Almería greenhouse cluster to robotic harvester deployment. |
| Brazilian Cerrado Market Entry | ANVISA-compliant autonomous planting fleets capture soybean expansion in Mato Grosso and Goiás. |
| ISOBUS-TC Certification Acceleration | Interoperability testing compression enables third-party implement integration for Midwestern grain operations. |
Research Approach
Operator-level perspectives from precision agriculture directors, OEM platform engineers, dealer service technicians, and USDA conservation program administrators anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from EPA pesticide application filings, FAA Part 107 waiver databases, USDA Environmental Quality Incentives Program disbursement records, and EU AI Act implementation guidance. Bottom-up equipment shipment tracking and top-down subsidy program scaling triangulated market sizing across the analysis window.
Sensitivity analysis tested forecast robustness against semiconductor supply normalization scenarios and FAA regulatory relaxation assumptions. The analytical framework modeled segmentation across equipment categories, algorithmic architectures, operator scale tiers, and application types throughout the forecast period. CAGRs derived from equipment replacement cycles intersecting with subsidy program renewal schedules. Yield prediction model accuracy improvement curves and RTK-GPS correction signal density expansion served as industry-specific forecast inputs.
Material uncertainties — Taiwan foundry supply disruption, FAA beyond-visual-line-of-sight waiver policy shifts, lithium-ion cell cost volatility — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and subsidy program continuity. Revision becomes warranted when EU AI Act enforcement intensity or US EPA documentation stringency crosses thresholds that alter OEM compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market