
 South America Agricultural Films Market | 2026-2036
South America Agricultural Films Market Size, Share, and Industry Trends Forecast 2026-2036
South America Agricultural Films Market Analytics
ISO 9001 quality management certification is unwinding the competitive landscape, filtering out smaller extrusion operators that lack documented process controls. Dow Inc. leverages its polyethylene resin supply chain to anchor pricing power across Brazilian distribution networks. Agroflex Indústria de Plásticos Ltda. specializes in customized silage formulations tailored to Argentina's dairy belt humidity conditions. Grupo Armando Alvarez dominates Iberian-linked export channels into Paraguay and Uruguay with standardized greenhouse film portfolios.
South America agricultural films are thermoplastic polymer sheets, typically 15-200 microns thick, manufactured through blown film extrusion of linear low-density polyethylene with UV stabilizers and anti-fog additives, deployed to modify microclimates, suppress weeds, and reduce post-harvest losses. Mulch films lead volume consumption across the region's soybean and tomato rotations, though margin pools concentrate in greenhouse films where multilayer coextrusion commands premium pricing. Biodegradable plastics represent the fastest-growing material category as Argentine and Brazilian regulators tighten disposal requirements for conventional polyethylene field waste.
Brazil's ANVISA and Argentina's national agricultural technology institute set residue migration limits for food-contact films, while Chile's Ministry of Environment enforces extended producer responsibility schemes that reshape material selection across Andean supply chains. ANVISA's updated polymer additive positive list forces reformulation cycles among imported and domestic compounders alike. Stakeholders must monitor pending biodegradable certification harmonization between Mercosur technical committees and EU REACH equivalence protocols to anticipate cross-border product registration barriers.
Market Dynamics
Biodegradable mulch film adoption is bifurcating competitive positioning across Brazil's cerrado belt, as specialty crop producers face ANVISA's updated polymer additive positive list and PNRS compliance requirements for field waste disposal.
Growth Catalysts
- Extended Producer Responsibility Schemes:Chile's Ministry of Environment mandates reshape material selection across Andean supply chains, forcing compounders toward certified biodegradable formulations.
- Soil Degradation Pressures:Specialty crop producers across Brazil's intensive vegetable corridors expand mulch film usage to combat erosion and extend growing seasons.
- Cooperative Bulk Procurement:São Paulo state producer cooperatives drive consolidated purchasing of greenhouse and silage films, compressing distributor margins while scaling manufacturer volumes.
Market Restraints
- Resin Supply Concentration:Linear low-density polyethylene feedstock dependence on Gulf Coast and Middle Eastern petrochemical complexes exposes Brazilian extruders to freight cost volatility and currency mismatch risks.
- Biodegradable Certification Fragmentation:Pending harmonization gaps between Mercosur technical committees and EU REACH equivalence protocols create cross-border product registration barriers.
- Conventional Film Substitution Lag:Cost premiums for biodegradable alternatives sustain polyethylene mulch dominance in price-sensitive soybean rotations despite regulatory pressure.
Strategic Opportunities
- Argentina's Dairy Belt Humidity Adaptation:Customized silage film formulations tailored to Pampas region moisture conditions command premium positioning against standardized imports.
- Paraguay-Uruguay Export Channels:Iberian-linked distribution networks into underserved Mercosur periphery markets bypass saturated Brazilian competition.
- Multilayer Coextrusion Technology Convergence:Integration of oxygen barrier layers with UV stabilizer packages enables premium greenhouse film portfolios for high-value horticulture.
Industry Challenges
- ISO 9001 Documentation Burden:Smaller extrusion operators lacking process control certification face systematic exclusion from cooperative and export procurement tenders.
- Reformulation Cycle Compression:ANVISA's additive positive list updates force compounders into accelerated re-registration timelines without grandfathering provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Agricultural Films Market |
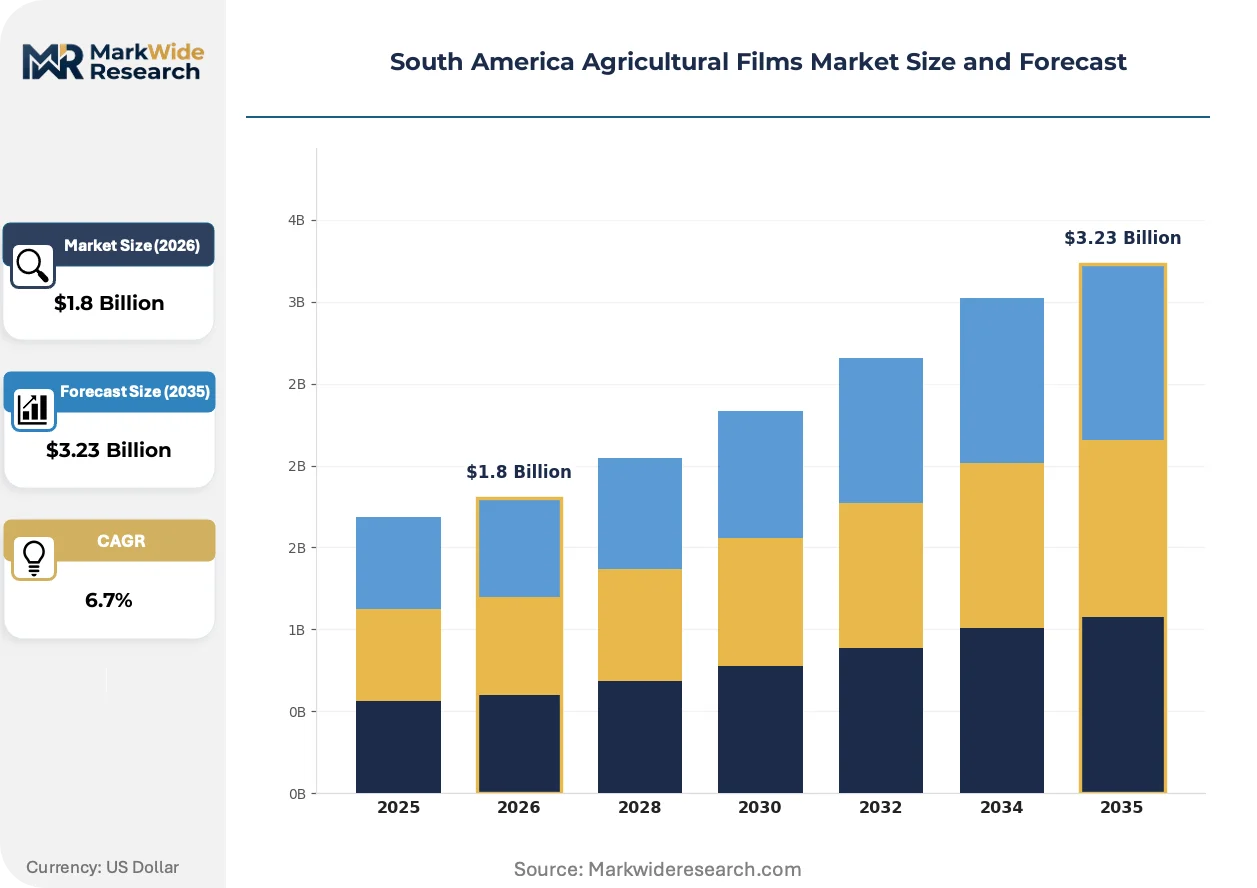
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Films, Mulch Films, Greenhouse Films, Silage Films Application: Crop Protection, Soil Moisture Retention, Weed Control, Packaging Applications Material: Polyethylene, Polypropylene, Biodegradable Plastics, Nylon End User: Farmers, Distributors, Agricultural Cooperatives, Retailers |
| Companies Covered | Manupackaging Deutschland GmbH & Co. KG, Novamont S.p.A., Dow Inc., RKW SE, ExxonMobil Corporation, Berry Global Inc., Agroflex Indústria de Plásticos Ltda., Grupo Armando Alvarez, BASF SE, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Agricultural Films Market Evolving Landscape
Active ingredient migration control and climate-adaptive barrier properties are reshaping formulation priorities across South American agricultural film manufacturing.
Multilayer blown film extrusion is bifurcating the competitive landscape between commodity mulch producers and premium greenhouse specialists. High-value tomato and berry growers in São Paulo's protected cultivation corridors adopt seven-layer coextruded structures with integrated anti-fog and infrared-blocking functionalities. This technology compression is squeezing single-layer operators out of margin pools while enabling compounders to capture value previously retained by additive masterbatch suppliers.
ANVISA's residue migration limits for food-contact films are forcing reformulation investments among domestic and imported compounders alike. The industrial consequence is a consolidation of approved additive suppliers capable of documenting polymer stability under tropical UV exposure conditions. Greenhouse film categories face the steepest compliance costs, driving producers toward pre-certified European compounders despite landed cost premiums.
Cooperative procurement consolidation is compressing distributor intermediation across Brazil's vegetable production belts. Bulk tendering by São Paulo and Minas Gerais producer associations displaces traditional regional distributor networks with direct manufacturer relationships. This channel restructuring is most visible in silage film categories, where dairy cooperatives leverage volume concentration to negotiate formulation customization and extended payment terms previously unavailable to fragmented farm-level buyers.
South America Agricultural Films Market Segmentation
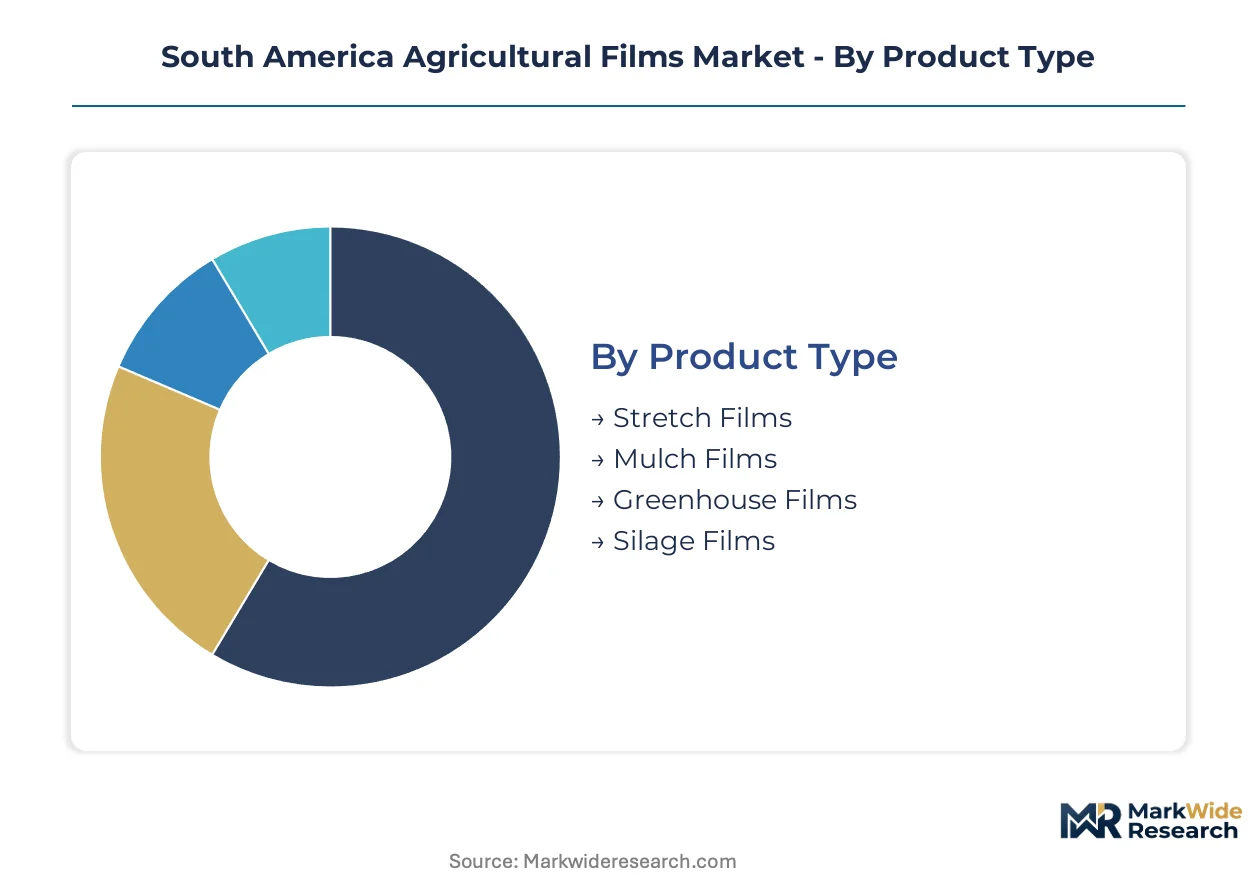
Segmentation in South America's agricultural films market reflects divergent regulatory pressures across Brazil, Argentina, and Chile, where ANVISA migration limits, PNRS waste compliance, and extended producer responsibility schemes each reshape material selection and procurement patterns. Understanding these category boundaries enables stakeholders to align formulation investments with enforcement trajectories rather than treating the region as a uniform demand pool.
Product Type:
ANVISA's residue migration limits and Brazil's PNRS field waste requirements create divergent compliance burdens across film categories, concentrating premium positioning in greenhouse applications while pressuring commodity mulch producers toward biodegradable reformulation.
- Mulch Films:Linear low-density polyethylene sheets, typically 15-30 microns thick with UV stabilizer packages, dominate volume consumption across Brazil's cerrado soybean rotations and São Paulo tomato corridors. ANVISA's updated polymer additive positive list forces compounders into accelerated re-registration cycles without grandfathering provisions, squeezing margin pools for single-layer operators.
- Greenhouse Films:Multilayer coextruded structures, often seven-layer configurations with integrated anti-fog and infrared-blocking functionalities, command premium pricing in São Paulo's protected cultivation belts. Chile's Ministry of Environment extended producer responsibility mandates reshape material selection toward certified biodegradable formulations for high-value berry and flower growers.
- Silage Films:Oxygen barrier formulations tailored to Pampas region humidity conditions support Argentina's dairy belt operations.
- Stretch Films:Bale wrapping applications concentrate in cooperative procurement channels across Brazil's Minas Gerais dairy clusters.
Established volume favors mulch films; emerging adoption favors greenhouse films.
Application:
Customer procurement scale determines specification intensity, with cooperatives driving bulk tendering for compound formulations that individual farm-level buyers cannot access.
- Crop Protection:Greenhouse and tunnel film deployments modify microclimates for high-value horticulture in São Paulo's intensive vegetable corridors, where multilayer coextrusion with climate-adaptive barrier properties enables premium positioning.
- Soil Moisture Retention:Mulch film usage expands across Brazil's cerrado belt to combat erosion and extend growing seasons, though biodegradable alternatives face cost premium barriers in price-sensitive commodity rotations.
- Weed Control:Black polyethylene mulch suppresses competition in organic-certified vegetable operations facing ANVISA food-contact compliance requirements.
- Packaging Applications:Post-harvest stretch and shrink films for fruit export logistics concentrate in Chile's central valley operations.
Volume concentrates in moisture retention; margin expansion concentrates in crop protection.
Material:
Feedstock sourcing geography exposes compounders to freight volatility and currency mismatch risks, particularly for resin dependence on Gulf Coast and Middle Eastern petrochemical complexes.
- Polyethylene:Linear low-density polyethylene dominates conventional mulch and greenhouse film production through blown film extrusion with additive masterbatch integration, though resin supply concentration creates vulnerability to landed cost fluctuations for Brazilian extruders.
- Biodegradable Plastics:Starch-based and polylactic acid formulations gain regulatory momentum as Argentine and Brazilian regulators tighten disposal requirements for conventional polyethylene field waste, with pending Mercosur-EU REACH harmonization gaps creating cross-border registration barriers.
- Polypropylene:Higher temperature resistance supports limited greenhouse clip and fastening applications.
- Nylon:Oxygen barrier layers in multilayer silage structures address Pampas region humidity conditions.
Polyethylene anchors current volume; biodegradable plastics climb the fastest under regulatory compression.
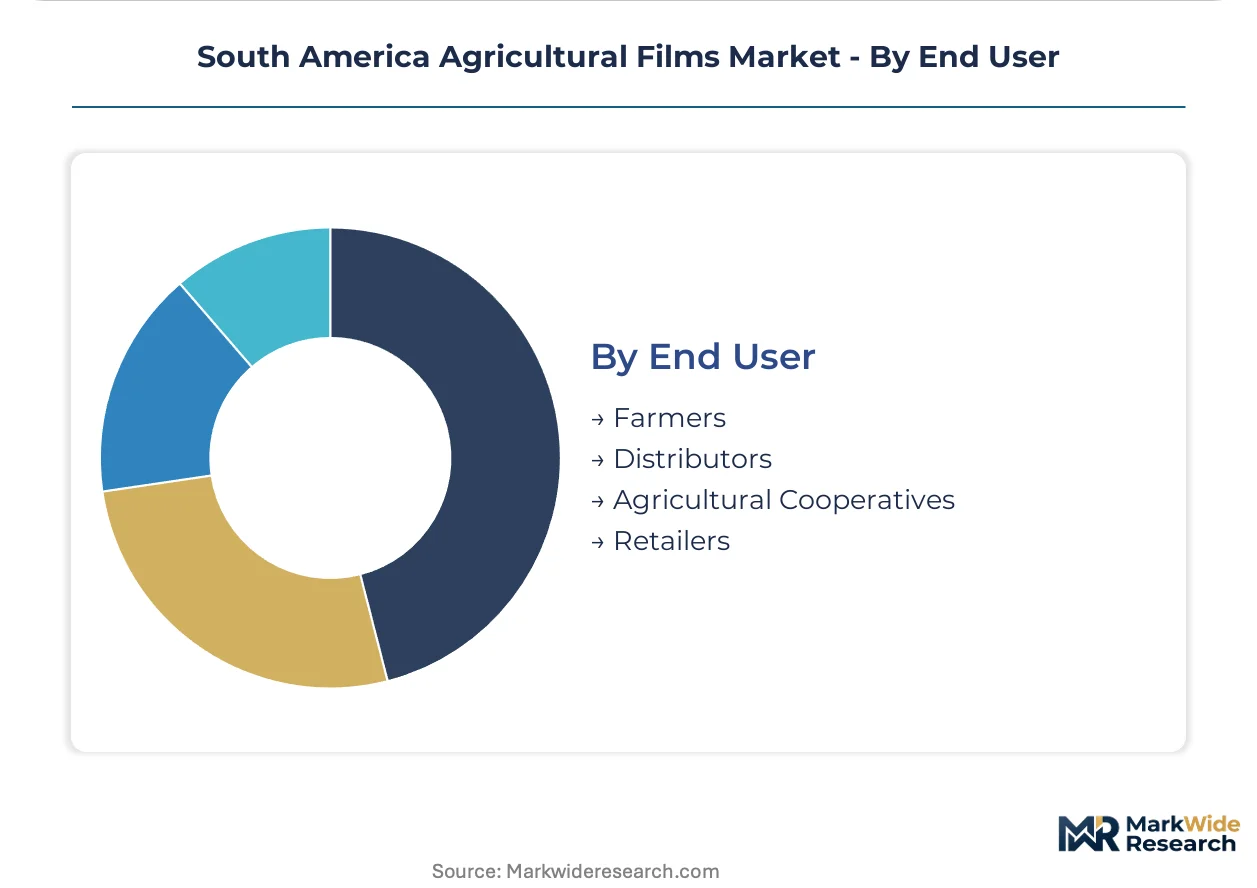
End User:
Channel restructuring displaces traditional distributor networks as procurement scale concentrates, compressing intermediation margins while enabling direct manufacturer relationships.
- Agricultural Cooperatives:São Paulo and Minas Gerais producer associations drive consolidated purchasing of greenhouse and silage films, leveraging volume concentration to negotiate formulation customization and extended payment terms previously unavailable to fragmented buyers.
- Farmers:Individual operations in Brazil's soybean belt and Argentina's Pampas region remain price-sensitive adopters of standardized mulch and silage specifications, with ISO 9001 certification requirements systematically excluding smaller extrusion operators from procurement tenders.
- Distributors:Regional networks face margin compression as cooperative bulk tendering bypasses traditional intermediation.
- Retailers:Farm supply stores serve fragmented smallholder demand with limited technical specification involvement.
Procurement gravity centers on cooperatives; specification influence concentrates with farmers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's updated polymer additive positive list and Brazil's PNRS compliance requirements are redirecting procurement toward certified biodegradable formulations across South American agricultural corridors.
Brazil
São Paulo state's intensive vegetable production corridors drive consolidated cooperative purchasing of greenhouse and silage films. ANVISA's residue migration limits for food-contact films force compounders into accelerated re-registration cycles without grandfathering provisions. The cerrado belt specialty crop producers expand mulch film deployment to combat soil degradation and extend growing seasons.
Argentina
Pampas region dairy operations sustain demand for customized silage formulations adapted to local humidity conditions. The country's national agricultural technology institute sets residue migration limits that reshape material selection for food-contact applications. Buenos Aires province anchors formulation customization as dairy cooperatives negotiate extended payment terms and technical specifications.
Chile
Central valley fruit export logistics concentrate post-harvest stretch film demand among large-scale agricultural exporters. The Ministry of Environment enforces extended producer responsibility schemes that redirect material selection toward certified biodegradable alternatives. Metropolitan Santiago serves as the compliance coordination hub for Andean supply chain restructuring.
Paraguay
Underserved Mercosur periphery markets attract Iberian-linked distribution networks bypassing saturated Brazilian competition. Import-dependent procurement channels expose buyers to currency mismatch risks and freight cost volatility from Middle Eastern resin sources. Asunción's commercial corridors facilitate cross-border film distribution into interior agricultural regions.
Uruguay
Pasture-based livestock operations generate steady silage film demand through cooperative procurement channels. Regulatory harmonization gaps between Mercosur technical committees and EU REACH equivalence protocols create product registration barriers for imported formulations. Montevideo's port infrastructure supports distribution logistics for regional agricultural supply chains.
South America Agricultural Films Market Competitive Landscape
Player mix skews toward multinational resin suppliers with captive polyethylene feedstock and regional extrusion specialists with formulation customization capabilities. Market structure concentrates around three tiers: Gulf Coast-linked resin majors controlling pricing power, Brazilian compounders with ANVISA certification proximity, and Iberian-connected distributors serving Mercosur periphery markets. Two strategic archetypes dominate: backward-integrated petrochemical operators leveraging feedstock cost advantages, and technology-focused compounders capturing premium positioning through multilayer coextrusion capabilities. Competitive moves center on cooperative procurement channel capture and biodegradable certification pre-positioning ahead of regulatory harmonization.
Among multinational resin suppliers, Dow Inc. and ExxonMobil Corporation anchor pricing power through Gulf Coast and Middle Eastern polyethylene supply chains. BASF SE and Novamont S.p.A. occupy positions within the biodegradable materials tier, representing reformulation investment capacity as ANVISA and Mercosur regulators tighten disposal requirements. Regional specialists including Agroflex Indústria de Plásticos Ltda. exemplify the customization-focused archetype, while Grupo Armando Alvarez sits within the export channel tier linking Iberian manufacturing to Paraguayan and Uruguayan demand.
| Leading Market Players |
|---|
| Manupackaging Deutschland GmbH & Co. KG |
| Novamont S.p.A. |
| Dow Inc. |
| RKW SE |
| ExxonMobil Corporation |
| Berry Global Inc. |
| Agroflex Indústria de Plásticos Ltda. |
| Grupo Armando Alvarez |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Blown film extrusion scale economies in São Paulo's industrial corridor concentrate margin capture among operators running multilayer coextrusion lines above 2,000 tons annual capacity, compressing price floors for single-layer commodity mulch producers while enabling premium positioning for certified greenhouse formulations. This capacity gradient shapes procurement negotiations across Brazilian agricultural cooperatives, where volume concentration extracts formulation customization that fragmented buyers cannot access.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-documented compounders and uncertified regional extruders, with ANVISA-compliant additive packages commanding 15-25% premiums over non-food-contact grades. Three-tier pricing structure separates multilayer greenhouse specialists from standard mulch producers and economy silage suppliers. Pricing pressure stems from cooperative bulk tendering compressing distributor margins in Minas Gerais dairy clusters. Individual soybean belt farmers exhibit highest price sensitivity, while São Paulo berry cooperatives prioritize performance specifications over unit cost.
Supply Chain Analysis
Strategic resin stockpiling dominates inventory strategy among Brazilian compounders buffering Gulf Coast polyethylene supply disruptions, with just-in-time preferences limited to standardized mulch grades. Raw material sourcing draws from US Gulf Coast, Middle Eastern petrochemical complexes, and domestic Braskem polyethylene production. Linear low-density polyethylene resin, UV stabilizer masterbatches, and anti-fog additive packages anchor formulation costs. Single-source vulnerability concentrates in Gulf Coast hurricane exposure disrupting seaborne resin flows. Distribution runs through cooperative procurement channels displacing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in agricultural films expand through technical formulation support and extended payment terms, with cooperative procurement channels prioritizing compounders offering on-field agronomic consultation over transactional resin supply.
For Market Incumbents: Shield margin pools in São Paulo greenhouse corridors by accelerating biodegradable certification pre-positioning ahead of Mercosur-EU REACH harmonization. Deepen backward integration into additive masterbatch production to offset ANVISA re-registration cycle compression. Channel control through direct cooperative relationships defends against Iberian-linked distributors entering Paraguay-Uruguay periphery markets.
For New Entrants and Emerging Players: Anchor in Paraguay-Uruguay import-dependent corridors where currency mismatch risks deter established Brazilian compounders from aggressive pricing. Underserved silage film demand in Uruguay's pasture-based dairy cooperatives offers penetrable entry with humidity-adapted formulations. Go-to-market execution through Montevideo port logistics partnerships bypasses saturated Brazilian distribution.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with multilayer coextrusion capabilities and ANVISA certification proximity over commodity mulch operators facing polyethylene substitution pressure. Acquisition targets with seven-layer blown film lines and established cooperative procurement relationships offer durable viability. Watch biodegradable certification harmonization progress as inflection signal for cross-border product registration barriers easing or intensifying.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Pre-Positioning | Mercosur-EU REACH alignment secures cross-border registration ahead of regulatory enforcement. |
| Multilayer Coextrusion Capacity Expansion | Seven-layer greenhouse film lines capture margin pools from single-layer commodity producers. |
| Cooperative Procurement Channel Capture | Direct relationships with São Paulo producer associations displace distributor intermediation. |
| Backward Integration into Additive Masterbatches | In-house UV stabilizer production buffers ANVISA re-registration cost compression. |
| Paraguay-Uruguay Distribution Network Buildout | Iberian-linked export channels bypass Brazilian saturation for Mercosur periphery access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blown film extrusion plant managers, agricultural cooperative procurement leads, ANVISA regulatory affairs specialists, and distributor channel partners across Brazil, Argentina, and Chile. Secondary validation drew from customs trade data, SEC filings of resin suppliers, ANVISA polymer additive positive list updates, and PNRS compliance documentation. Bottom-up volume modeling triangulated against top-down polyethylene consumption estimates across South American agricultural applications.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, material category, end-user procurement scale, and regional regulatory cluster intensity. CAGRs derived from trend extrapolation of cooperative purchasing patterns and biodegradable adoption curves under enforcement trajectory assumptions. Key inputs incorporated resin price volatility indices, currency mismatch exposure matrices, and certification timeline projections.
Decision-makers should treat outputs as directional under assumptions of continued ANVISA enforcement stringency and cooperative procurement consolidation; material deviation would warrant model refresh. Specific risks include Mercosur-EU harmonization delays extending cross-border registration barriers, and Gulf Coast supply disruptions accelerating faster than strategic stockpile buffers absorb. Revision becomes warranted when biodegradable cost premiums compress below 20% versus conventional polyethylene in soybean belt applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Fabrics
Global Agriculture Nets Market
Agricultural Fabrics
Hay Bags Market
Agricultural Fabrics
Agricultural Fabrics Market
Agricultural Fabrics
Africa Agricultural Film Market
Agricultural Fabrics
Biodegradable Mulch Film Market
Agricultural Fabrics
Horticulture Film Market
Agricultural Fabrics
Canopy Market
Agricultural Fabrics
North America Silo Bags Market
Agricultural Fabrics
Silo Bags Market
Agricultural Fabrics
Asia-Pacific Agricultural Films Market
Agricultural Fabrics
Global Mulch Films Market
Agricultural Fabrics
Silage Wrap Films Market
Agricultural Fabrics
Coco Coir Market
Agricultural Fabrics
Agricultural Films and Bonding Market
Agricultural Fabrics
Global Greenhouse Film Market
Agricultural Fabrics
Shade Net Market