
 Biological Organic Fertilizers Market | 2026-2036
Biological Organic Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Organic Fertilizers Market Analysis
India's Gujarat corridor is fragmenting as new fermentation facilities and composting yards multiply across the Kheda and Anand districts. National Fertilizers Limited anchors its position through captive biogas slurry supplies from adjacent dairy cooperatives. Lallemand, Inc. competes via specialized microbial inoculant strains developed for tropical soil profiles. Novonesis Group differentiates through enzymatic processing platforms that accelerate organic matter decomposition timelines.
Biological organic fertilizers are nutrient-bearing amendments derived from decomposed plant residues, animal manures, bone-derived minerals, and cultivated microbial consortia, typically processed through aerobic composting, vermicomposting, or controlled anaerobic digestion to achieve stabilized carbon-to-nitrogen ratios between 15:1 and 25:1. These inputs replenish soil organic carbon, enhance microbial biomass, and reduce synthetic nitrogen runoff in intensive cropping systems. Compost dominates volume flows among product types due to lower per-ton production costs and compatibility with mechanized spreading equipment, while vermicompost commands premium positioning in horticultural channels where porosity and microbial diversity drive root-zone performance. Direct sales to farmer cooperatives capture the deepest margin pools by eliminating distributor markups, though online channels are gaining traction among peri-urban gardening segments.
The EPA's Clean Water Act provisions on agricultural runoff shape product registration requirements for manure-based formulations in US watersheds. India's FCO standards under the Ministry of Agriculture mandate minimum organic carbon and beneficial microbe counts for commercial biofertilizer labeling. The EU Green Deal's Farm to Fork strategy tightens synthetic input reduction targets, redirecting subsidy eligibility toward certified organic amendments. Stakeholders must monitor how carbon credit methodologies for soil organic sequestration reshape farmer willingness to pay for verified biological inputs.
Market Dynamics
California's SB 1383 organic waste recycling mandate is compressing compost production timelines while fragmenting supply chains across multiple state clusters, forcing manufacturers to co-locate with municipal waste streams to secure feedstock access.
Growth Catalysts
- EU Green Deal's Farm to Fork strategy:Synthetic input reduction targets redirect subsidy eligibility toward certified organic amendments across member state agricultural programs.
- India's PLI scheme for bio-input manufacturing:Production-linked incentives expand fermentation capacity in the Indo-Gangetic Plain, lowering per-unit costs for microbial consortia formulations.
- Carbon credit methodologies for soil organic sequestration:Verified carbon accounting frameworks create new revenue streams for farmers adopting compost-based nutrient management.
Market Restraints
- Feedstock cost volatility:Dairy manure and crop residue prices fluctuate with commodity cycles, compressing margins for compost producers without captive supply agreements.
- Technical shelf-life limitations:Microbial inoculants require cold-chain distribution infrastructure absent in rural India and sub-Saharan Africa, constraining market reach.
- Regulatory friction from EPA Clean Water Act:Manure-based formulation registrations face extended approval timelines in Chesapeake Bay and Mississippi River watersheds.
Strategic Opportunities
- Underpenetrated peri-urban gardening segments:Online direct-to-consumer channels bypass distributor markups in North American and European metro corridors.
- Technology convergence of enzymatic processing with anaerobic digestion:Accelerated decomposition platforms reduce production cycle times from months to weeks.
- India's FCO standards expansion:Mandatory organic carbon and beneficial microbe count labeling creates premium tier for verified biofertilizer products.
Industry Challenges
- Microbiologist talent scarcity:Strain isolation and formulation science expertise concentrates in agricultural university clusters, limiting R&D bandwidth for mid-tier producers.
- Certification timeline compression:Organic input approvals under India's APEDA and the EU's organic regulation require 18-24 month validation cycles, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Organic Fertilizers Market |
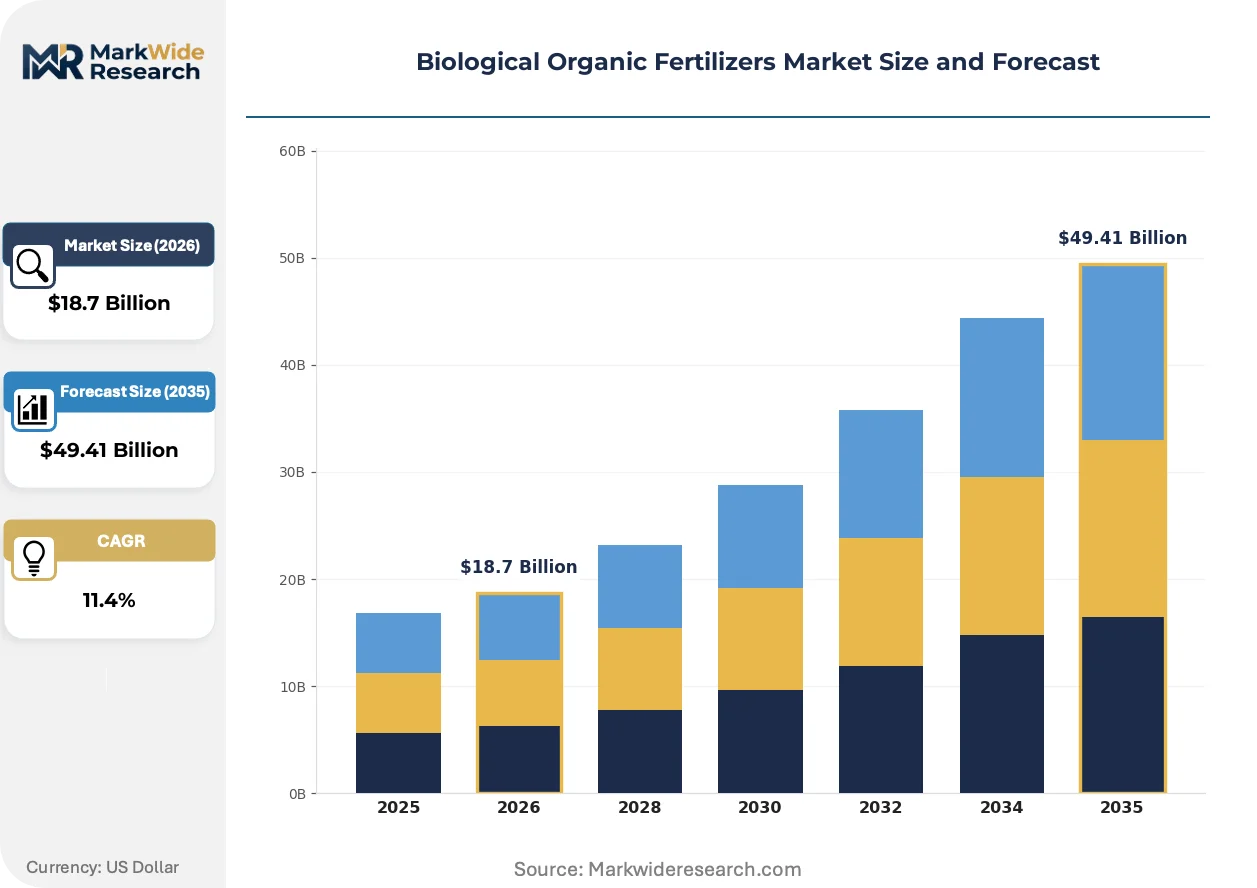
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Vermicompost, Bone Meal Application: Agricultural, Horticultural, Landscaping, Gardening Distribution Channel: Direct Sales, Retail, Online, Wholesalers Customer Type: Farmers, Nurseries, Garden Centers, Homeowners |
| Companies Covered | National Fertilizers Limited, Agri Life, Rizobacter Argentina S.A., The Scotts Miracle-Gro Company, Bioceres Crop Solutions Corp, Lallemand, Inc., UPL Limited, Novonesis Group, Coromandel International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Organic Fertilizers Market Emerging Trajectories
Processing technologies and verification frameworks are restructuring how biological fertilizers achieve price parity with synthetic alternatives, with speed-to-stability and carbon quantification emerging as the decisive competitive variables.
Controlled anaerobic digestion with biogas co-generation is migrating from centralized municipal facilities to on-farm modular units. Dairy cooperatives in Gujarat and California's Central Valley are installing small-scale digesters to capture methane while stabilizing nitrogen in digestate outputs. This distributed model compresses transportation costs and enables real-time quality monitoring that batch composting cannot match.
The EU's CSRD disclosure requirements now mandate Scope 3 agricultural emissions reporting for food processors and retailers. Downstream pressure is forcing fertilizer procurement teams to source verifiable soil carbon inputs with chain-of-custody documentation. Specialty crop growers in the Netherlands and Denmark are switching to enzymatically processed amendments that generate quantifiable sequestration credits.
Farmer cooperatives in India's Maharashtra and Karnataka states are consolidating input purchasing through digital platforms that aggregate demand and standardize quality specifications. These procurement collectives displace traditional distributor networks, capturing margin pools previously split across multiple intermediaries. The model is compressing payment cycles and enabling direct feedback loops between manufacturers and end-users.
Biological Organic Fertilizers Market Segmentation
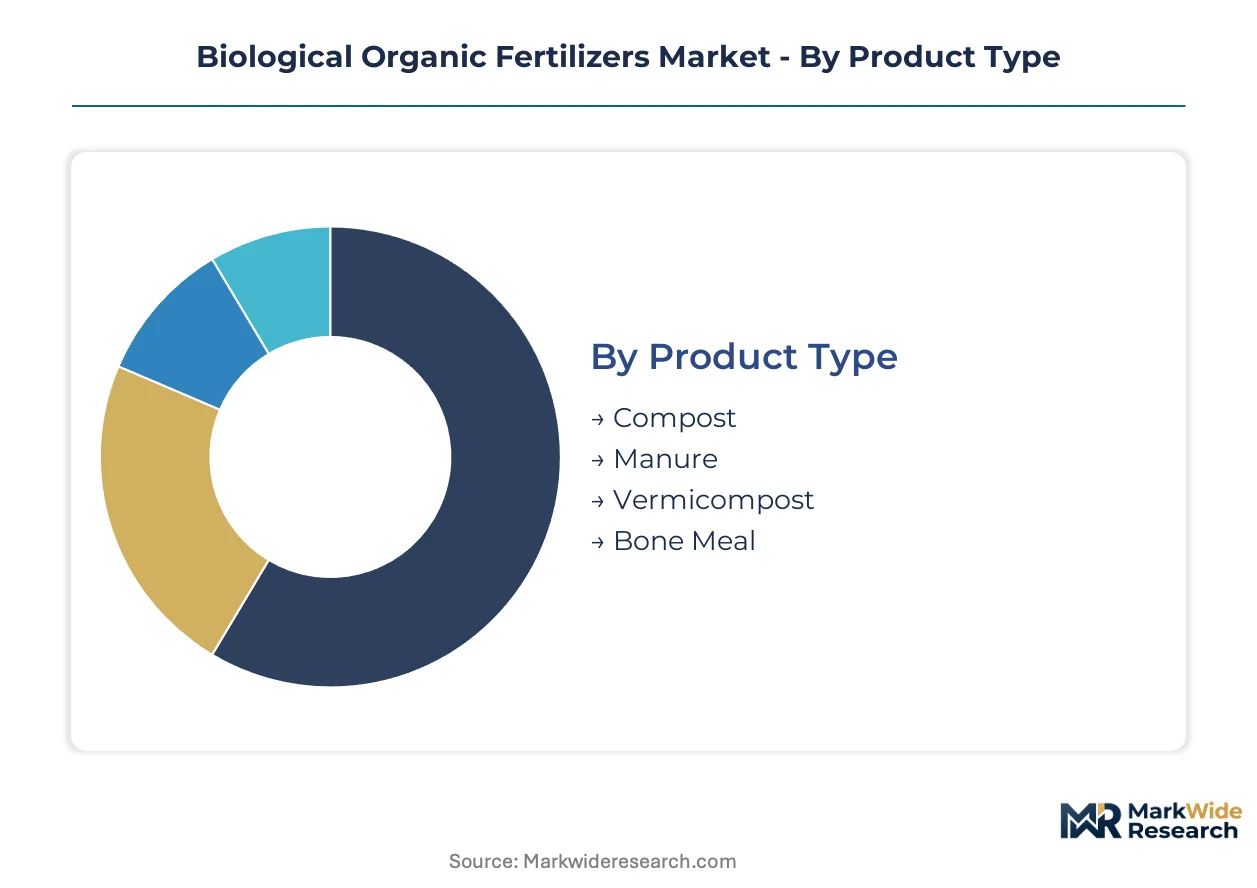
Segmentation in biological organic fertilizers reveals how production economics, application specificity, and channel accessibility fragment commercial opportunity across distinct user profiles and use intensities.
Product Type:
The use-case spectrum spans subsistence-level soil amendment to precision horticulture, with decomposition method and nutrient stability determining price positioning and geographic reach.
- Compost:Aerobically decomposed organic matter achieving carbon-to-nitrogen ratios between 15:1 and 25:1, processed through windrow or in-vessel systems. Demand concentrates in California's Central Valley specialty crop operations under SB 1383 mandate pressures, where mechanized spreading compatibility and per-ton cost efficiency override premium positioning. Feedstock access agreements with municipal waste streams increasingly dictate manufacturer location decisions.
- Manure:Animal waste-based formulations requiring stabilization through composting or anaerobic digestion to reduce pathogen loads and volatile ammonia. Dairy cooperatives in Gujarat's Kheda district leverage captive biogas slurry supplies to anchor integrated production, though EPA Clean Water Act registration friction extends approval timelines in US watersheds.
- Vermicompost:Earthworm-processed organic matter with elevated microbial diversity and fine particulate structure commanding premium pricing in horticultural root-zone applications.
- Bone Meal:Steamed or raw bone-derived phosphorus source regulated under mineral fertilizer standards in EU member states, with organic certification eligibility varying by processing temperature.
Established volume favors compost; emerging adoption favors vermicompost.
Application:
Application intensity correlates with crop value per hectare and synthetic input substitution economics, creating divergent margin profiles across broadacre and intensive systems.
- Agricultural:Field-scale deployment in cereal, oilseed, and fiber cropping systems where organic carbon replenishment drives synthetic nitrogen reduction compliance. India's Indo-Gangetic Plain PLI-subsidized bio-input manufacturing concentrates supply for wheat and rice rotations, with farmer cooperatives aggregating demand to displace distributor markups.
- Horticultural:High-value fruit, vegetable, and ornamental production requiring porosity-optimized amendments and verified microbial consortia. Dutch and Danish specialty growers under EU CSRD Scope 3 disclosure mandates source enzymatically processed inputs with chain-of-custody documentation for quantifiable sequestration credits.
- Landscaping:Turf establishment and maintenance applications in commercial and municipal settings, with bulk delivery logistics dominating procurement patterns.
- Gardening:Peri-urban and residential use segments where packaging size and retail accessibility override per-unit cost optimization.
Volume concentration sits with agricultural deployment; margin expansion sits with horticultural certification tiers.
Distribution Channel:
Channel selection determines working capital intensity and quality control accountability, with direct relationships capturing margin pools otherwise fragmented across intermediaries.
- Direct Sales:Manufacturer-to-farmer or manufacturer-to-cooperative transactions eliminating distributor markups and compressing payment cycles. Maharashtra and Karnataka procurement collectives standardize quality specifications through digital aggregation platforms, enabling direct feedback loops between microbial inoculant producers and end-users.
- Retail:Garden center and agricultural supply store networks serving peri-urban gardening and smallholder segments, with shelf-life limitations constraining microbial product placement.
- Online:Direct-to-consumer channels gaining traction in North American and European metro corridors, bypassing traditional wholesale infrastructure for home gardener segments.
- Wholesalers:Regional distributors managing bulk logistics for compost and manure volumes, with transportation radius economics dictating effective market boundaries.
Margin retention favors direct sales; geographic expansion favors online channel development.
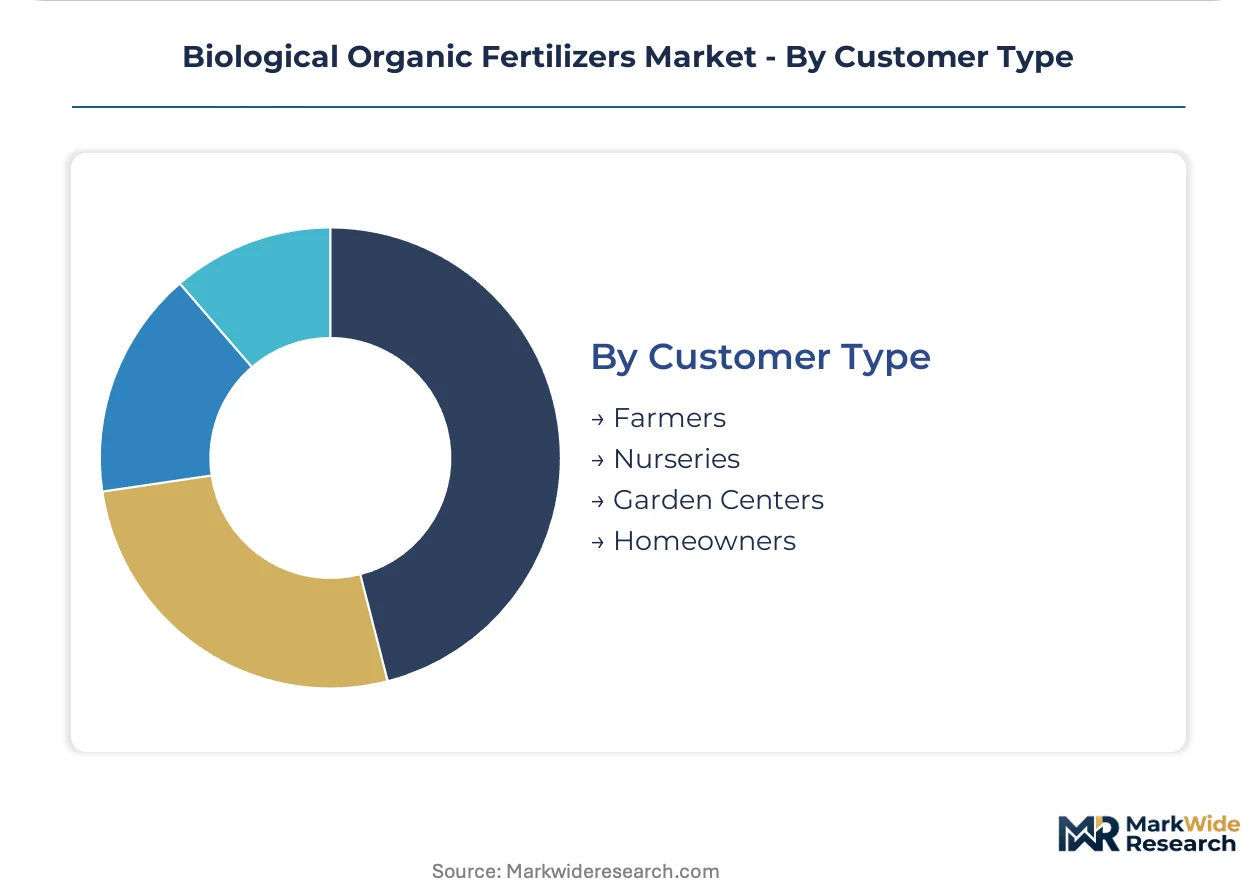
Customer Type:
Customer scale and technical sophistication determine formulation complexity requirements and price elasticity, segmenting the market between volume commodity and precision input demand.
- Farmers:Commercial agricultural operators prioritizing per-hectare cost efficiency and regulatory compliance documentation. Cold-chain infrastructure gaps in rural India and sub-Saharan Africa constrain microbial inoculant reach, limiting shelf-stable compost and manure formulations in these geographies.
- Nurseries:Plant propagation specialists requiring consistent porosity and pathogen-free specifications, with vermicompost premium positioning aligned to root establishment performance.
- Garden Centers:Retail intermediaries serving hobbyist and landscaping contractor segments, with packaging and branding investments driving SKU differentiation.
- Homeowners:Residential gardening consumers purchasing through retail or online channels, with convenience and application guidance outweighing bulk cost optimization.
Procurement scale favors farmer cooperatives; margin per transaction favors nursery direct relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compost production capacity clusters around municipal waste streams in the United States, India, and the Netherlands, while microbial inoculant manufacturing concentrates in temperate agricultural zones with established fermentation infrastructure.
United States
California's SB 1383 mandate diverts organic waste from landfills into composting facilities, compressing production timelines across the Central Valley specialty crop belt. EPA Clean Water Act provisions shape manure-based formulation registrations in Chesapeake Bay and Mississippi River watersheds. Dairy cooperatives in the Central Valley install modular anaerobic digesters to stabilize nitrogen in digestate outputs.
India
The PLI scheme for bio-input manufacturing expands fermentation capacity across the Indo-Gangetic Plain for wheat and rice rotations. FCO standards under the Ministry of Agriculture mandate minimum organic carbon and beneficial microbe counts for commercial labeling. Gujarat's Kheda and Anand districts fragment as new composting yards and fermentation facilities multiply along the dairy corridor.
Netherlands
EU Green Deal Farm to Fork strategy tightens synthetic input reduction targets, redirecting subsidy eligibility toward certified organic amendments. CSRD disclosure requirements mandate Scope 3 agricultural emissions reporting for food processors and retailers. Specialty growers in Dutch greenhouse clusters source enzymatically processed inputs with chain-of-custody documentation.
Brazil
Soybean and sugarcane operators adopt biological amendments to meet EU import standards for deforestation-free supply chains. ANVISA regulates microbial inoculant imports and domestic production licensing. São Paulo state agribusiness clusters integrate compost-based programs into no-till cropping systems.
Germany
The F-Gas Regulation and national climate targets accelerate biogas co-generation from agricultural residues. REACH compliance shapes bone meal and animal-derived input classifications across member state markets. Bavarian dairy cooperatives deploy on-farm digesters to capture methane while producing stabilized organic amendments.
Biological Organic Fertilizers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in strain development and enzymatic processing. The vendor base spans state-affiliated fertilizer incumbents, multinational microbial technology platforms, and regional composting cooperatives. Three archetypes dominate: captive feedstock aggregators with dairy or municipal waste access, specialized microbial inoculant developers with tropical or temperate strain libraries, and enzymatic processing platforms accelerating decomposition timelines. Capacity expansion through co-location with waste streams and strategic partnerships for cold-chain distribution represent the dominant competitive moves.
Among publicly listed agricultural input conglomerates, The Scotts Miracle-Gro Company and UPL Limited occupy positions spanning retail distribution and direct-to-farmer channels. National Fertilizers Limited anchors the state-affiliated tier through captive biogas slurry arrangements with adjacent dairy cooperatives. Lallemand, Inc. and Novonesis Group exemplify the specialized technology tier, with the former representing microbial inoculant development and the latter enzymatic processing platforms. These five entities collectively illustrate the competitive spectrum from commodity compost volume to premium microbial formulation.
| Leading Market Players |
|---|
| National Fertilizers Limited |
| Agri Life |
| Rizobacter Argentina S.A. |
| The Scotts Miracle-Gro Company |
| Bioceres Crop Solutions Corp |
| Lallemand, Inc. |
| UPL Limited |
| Novonesis Group |
| Coromandel International Limited |
| Others |
Supply Flow & Price Mechanics
Freight corridors connecting Gujarat's dairy belt to the Indo-Gangetic Plain transmit feedstock cost volatility into downstream price spreads, compressing margins for compost producers lacking captive biogas slurry agreements while enabling enzymatic processors to command carbon-certified premiums.
Pricing Analysis
India's FCO standards dictate the pricing tier structure across the biological organic fertilizers landscape, separating verified biofertilizer products with mandatory organic carbon and beneficial microbe counts from unlabeled commodity compost. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and cold-chain infrastructure investment, with microbial inoculants bearing distribution cost penalties in rural India. Pricing pressure stems from dairy manure and crop residue commodity cycles, squeezing mid-tier producers without long-term feedstock contracts. Smallholder cooperatives in Maharashtra exhibit acute price sensitivity, while Dutch greenhouse operators under CSRD mandates absorb premium tier costs for quantifiable sequestration documentation.
Supply Chain Analysis
Tariff exposure between India and raw material sourcing zones for specialized microbial strains dominates supply chain risk calculus for fermentation-dependent producers. Manufacturing gravity centers on India, the Netherlands, and California, with each node drawing from distinct feedstock ecosystems: dairy cooperatives, municipal organic waste streams, and specialty crop residues respectively. Raw material dependencies rest on biogas slurry, enzymatic substrates, and earthworm cultivation media, with quality variability constraining batch consistency. Single-source vulnerability concentrates in tropical strain libraries held by limited agricultural university clusters. Distribution runs through farmer cooperative digital platforms in India and direct-to-retail channels in European metro corridors, bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological organic fertilizers are shifting toward platform economics as carbon credit interoperability and procurement collective aggregation reshape value capture from product sales to ecosystem orchestration.
For Market Incumbents: Insulate core margin pools by securing captive biogas slurry agreements with dairy cooperatives in Gujarat and California, locking in feedstock cost stability against commodity volatility. Accelerate enzymatic processing certification under EU Green Deal Farm to Fork subsidy eligibility to defend positioning against emerging microbial technology platforms. Cold-chain infrastructure partnerships represent the critical lever for expanding microbial inoculant reach into rural India without shelf-life degradation. For New Entrants and Emerging Players: Pursue peri-urban gardening segments in North American and European metro corridors where online direct-to-consumer channels bypass entrenched distributor networks. India's fragmented Gujarat corridor offers white-space opportunity for modular anaerobic digestion units co-located with municipal waste streams. A subscription-based soil health monitoring bundle, combining biological amendments with carbon sequestration verification, unlocks recurring revenue models absent in commodity compost sales. For Investors and Strategic Acquirers: Carve-out targets emerge from state-affiliated fertilizer incumbents with underutilized fermentation capacity and captive dairy cooperative relationships awaiting operational optimization. Long-term viability hinges on carbon credit methodology convergence creating measurable revenue streams beyond input sales. The signal to watch is APEDA organic certification timeline compression, which will separate acquisition-ready assets from stranded regulatory compliance liabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Cooperatives | Captive biogas slurry agreements in Gujarat and California stabilize feedstock costs against commodity cycles. |
| Enzymatic Processing Platform Deployment | Accelerated decomposition timelines under Novonesis methods generate quantifiable carbon sequestration credits for Dutch growers. |
| Farmer Cooperative Digital Aggregation | Maharashtra and Karnataka procurement collectives displace distributor markups and compress payment cycles for manufacturers. |
| Cold-Chain Distribution Partnership | Rural India infrastructure gaps constrain microbial inoculant shelf life, requiring strategic logistics alliances for market expansion. |
| APEDA Organic Certification Investment | Eighteen-to-twenty-four month validation cycles under India's organic regulation create premium tier eligibility and barrier to entry. |
Methodological Framework
Initial hypotheses were tested against primary input from compost facility operations managers, dairy cooperative procurement leads, microbial inoculant R&D directors, and agricultural extension officers across India, California, and the Netherlands, then refined against secondary validation from FCO standard filings, EPA Clean Water Act registration databases, EU CSRD disclosure registries, and customs trade data on organic amendment flows. Bottom-up volume estimates from individual facility capacity and top-down demand modeling from cropped acreage and synthetic nitrogen substitution rates were triangulated to constrain forecast variance.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application intensity, distribution channel working capital structure, and customer technical sophistication. CAGRs were derived from logistic diffusion curves for synthetic input substitution and carbon credit methodology adoption rates. Industry-specific forecast inputs incorporated PLI scheme capacity expansion timelines in the Indo-Gangetic Plain and SB 1383 organic waste diversion mandates in California's Central Valley.
Sensitivities concentrate around feedstock commodity price volatility, regulatory approval timeline extensions under EPA and APEDA frameworks, and carbon credit methodology standardization delays. Forecasts reflect documented assumptions on substitution elasticity and subsidy continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Middle East and Africa Fertilizers Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Asia-Pacific Micronutrient Fertilizer Market
Fertilizers
Argentina Fertilizer Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
United States Micronutrient Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
Australia Fertilizer Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Russia Fertilizers Market
Fertilizers
Biochar Fertilizer Market