
 Precision Livestock Market | 2026-2036
Precision Livestock Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Livestock Market Analytics
Market Context with Strategic Players
Dutch dairy equipment manufacturing is rebalancing toward integrated automation platforms. DeLaval leverages its full-line robotics portfolio to anchor premium positioning in rotary milking systems. GEA Farm Technologies competes through specialized manure handling and ventilation solutions that extend into climate-controlled barn design. Nedap N.V. dominates livestock identification and monitoring hardware, particularly in European markets where traceability mandates tighten.
Technical Definition and Structural Segments
Precision livestock farming deploys networked sensors, wearable biometrics, and automated feeding machinery to capture individual-animal data streams for real-time health, nutrition, and reproductive decisions. The technology stack typically integrates RFID ear tags, rumen boluses, and computer vision cameras with cloud-based analytics platforms to reduce mortality rates and optimize feed conversion ratios. IoT Devices and wearable systems lead technology adoption as hardware costs decline and battery life extends across multi-year deployment cycles. Dairy Farmers represent the deepest end-user segment given milking frequency and per-cow value, while Data Analytics services capture expanding margin pools as farms outsource algorithmic interpretation. Feeding Management applications show accelerated growth as compound feed prices pressure operational budgets across European and North American operations.
Regulatory Frame and Forward Outlook
The EU Green Deal and F-Gas Regulation shape equipment standards by restricting refrigerants in milk cooling systems and mandating emissions disclosures from large livestock holdings. The FDA and USDA in the United States impose residue-testing protocols and antibiotic-use tracking that drive demand for automated health-monitoring systems with audit-ready data trails. Stakeholders must evaluate whether to build in-house data science capabilities or partner with specialized analytics providers as regulatory reporting granularity intensifies.
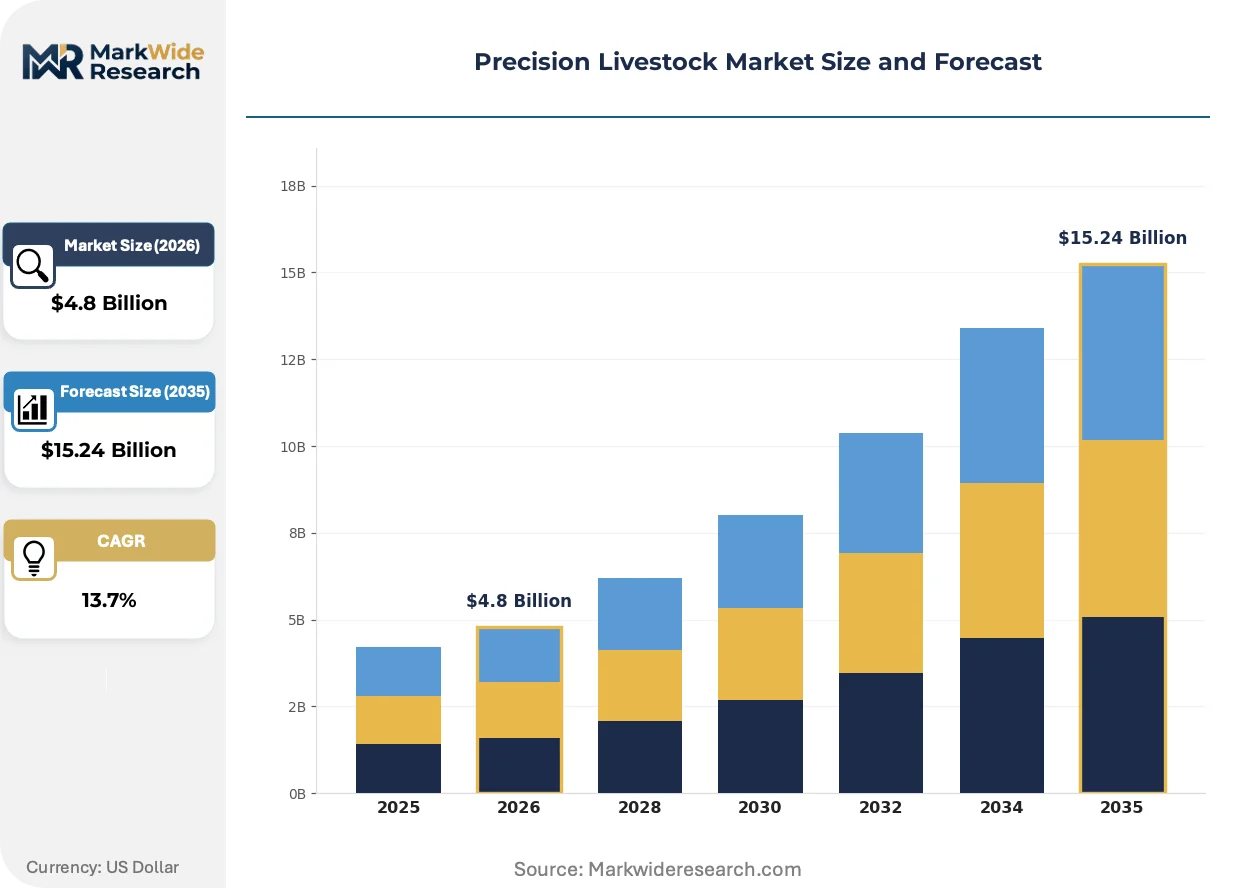
Market Dynamics
Sensor-to-cloud integration is compressing decision cycles from days to minutes, forcing equipment vendors to pivot from hardware sales toward recurring data-service revenue models anchored by livestock health analytics.
Growth Catalysts
- EU Green Deal Farm to Fork mandates:Binding emissions disclosure requirements for large livestock holdings drive automated monitoring system procurement across Dutch and Danish dairy cooperatives.
- Rumen bolus sensor maturation:Extended battery life and reduced unit economics enable individual-cow metabolic tracking at commercial scale in North American feedlot operations.
- Compound feed price volatility:Sustained input cost pressure accelerates adoption of algorithmic feeding optimization systems by European dairy farmers seeking feed conversion ratio improvements.
Market Restraints
- Semiconductor supply concentration:Taiwan-domiciled foundry capacity constraints create 6-9 month lead times for RFID tag and sensor microcontroller procurement.
- F-Gas refrigerant phase-down:EU restrictions on conventional cooling agents inflate retrofit costs for existing milk cooling infrastructure.
- Cloud connectivity gaps:Rural broadband dead zones in Australia and Canada limit real-time data transmission from remote pasture-based grazing systems.
Strategic Opportunities
- Brazilian cattle ranching digitization:Underpenetrated beef operations present first-mover positioning for integrated herd management platforms in Mato Grosso and Pará states.
- Computer vision convergence with edge AI:On-device image processing reduces latency for lameness detection and behavioral anomaly alerts without continuous uplink dependency.
- USDA Conservation Reserve Program incentives:Carbon credit eligibility for methane-reduction technologies creates subsidized demand pull for enteric fermentation monitoring systems.
Industry Challenges
- Veterinary data science talent scarcity:Farms struggle to recruit professionals capable of interpreting algorithmic health alerts and integrating recommendations with clinical protocols.
- Multi-vendor integration friction:Proprietary data formats from competing sensor manufacturers obstruct unified dashboard deployment and cross-platform analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Livestock Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, Sensors, Drones, Wearable Systems Application: Livestock Monitoring, Health Tracking, Feeding Management, Breeding Optimization End User: Dairy Farmers, Beef Producers, Poultry Farmers, Aquaculture Operators Service Type: Consulting Services, Data Analytics, Software Solutions, Maintenance Services |
| Companies Covered | DeLaval, GEA Farm Technologies, Afimilk Ltd., Allflex Livestock Intelligence, BouMatic, Nedap N.V., Lely, SCR Dairy, Dairymaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Livestock Market Evolving Landscape
Automation architectures are converging on unified platforms that collapse separate feeding, milking, and health monitoring workflows into single-vendor ecosystems with centralized data lakes.
Computer vision-based animal monitoring is consolidating standalone camera networks into integrated barn infrastructure. Large-scale dairy operations in the Netherlands and California are deploying ceiling-mounted 3D cameras for automated body condition scoring and estrus detection. This compression of point solutions into building-integrated systems is consolidating vendor relationships and raising switching costs for producers.
REACH chemical restrictions and the EU F-Gas Regulation are mandating refrigerant transitions in milk cooling equipment. Equipment manufacturers must redesign compressor architectures to accommodate lower-global-warming-potential alternatives. German and Danish dairy technology suppliers face compressed certification timelines to maintain market access.
Service contracting is displacing capital purchase models among mid-scale dairy operations. Farmers in Wisconsin and Ontario increasingly lease robotic milking systems with bundled predictive maintenance and algorithmic optimization. This shift transfers technology obsolescence risk to vendors while locking in multi-year recurring revenue streams.
Precision Livestock Market Segmentation
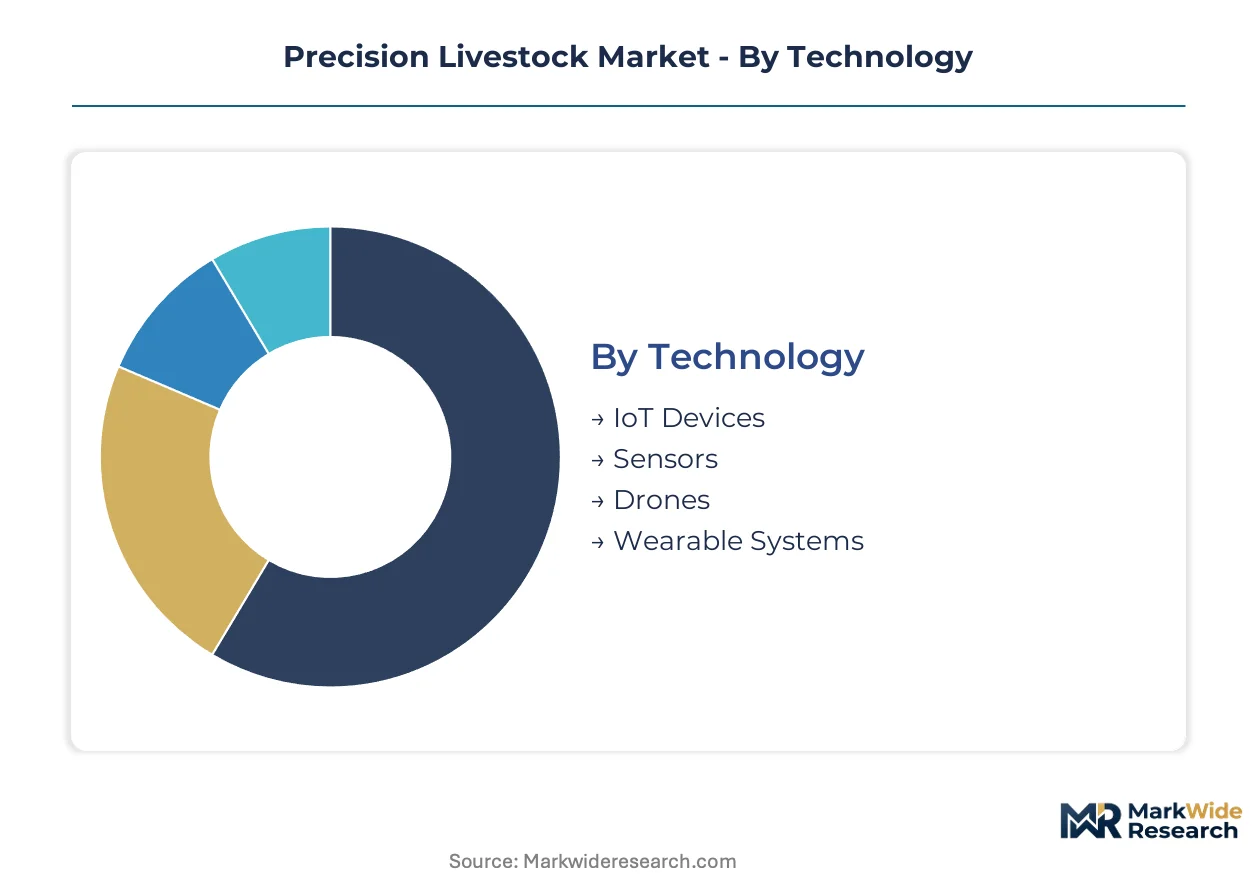
Precision livestock farming segments reflect divergent technology maturity and buyer sophistication. Dairy cooperatives prioritize integrated automation platforms while beef operations lag in sensor deployment. Understanding these splits reveals where margin pools concentrate and which customer profiles justify specialized go-to-market investment.
Technology:
Hardware selection hinges on battery longevity, connectivity infrastructure, and per-unit economics across grazing versus confinement systems.
- Wearable Systems:Collar-mounted accelerometers and ear-tag biometrics capture continuous activity, rumination, and estrus signals. Dutch dairy cooperatives deploy these at scale for individual-cow metabolic tracking under EU Green Deal emissions disclosure mandates.
- IoT Devices:Environmental sensors for barn climate, ammonia detection, and automated ventilation control. North American feedlot operators favor these for pen-level monitoring where Wi-Fi backhaul exists.
- Sensors:Fixed-position weight scales, milk flow meters, and automated sort gates. Demand concentrates in rotary milking parlors where throughput optimization justifies capital intensity.
- Drones:Aerial thermal imaging for pasture-based herd location and body condition assessment. Australian and Canadian ranchers adopt these where cellular dead zones limit ground-based telemetry.
Wearable Systems lead volumes today; IoT Devices are gaining share fastest.
Application:
Use case prioritization tracks feed cost pressure, labor scarcity, and regulatory audit burden by production system.
- Feeding Management:Algorithmic ration formulation and automated delivery systems optimize feed conversion ratios. European dairy farmers accelerate procurement here as compound feed price volatility squeezes margins.
- Health Tracking:Automated lameness detection, mastitis early warning, and antibiotic-use logging with FDA-auditable data trails. Large US dairies deploy these to satisfy USDA residue-testing protocols.
- Livestock Monitoring:Location tracking, behavioral anomaly alerts, and predator detection. Brazilian cattle ranchers in Mato Grosso represent underpenetrated demand for integrated herd visibility.
- Breeding Optimization:Estrus detection algorithms and genetic selection support tools. Premium semen distributors bundle these services to lock in recurring revenue from progressive breeders.
Feeding Management dominates current procurement; Health Tracking shows the steepest expansion trajectory.
End User:
Customer economics vary dramatically by animal value, handling frequency, and technology sophistication.
- Dairy Farmers:Daily milking contact creates data capture opportunities and justifies automation investment per cow. California and Netherlands operations lead in robotic milking and sensor integration.
- Beef Producers:Extensive grazing systems and lower per-head value delay sensor deployment. Brazilian operations in Pará state present first-mover positioning for integrated platforms.
- Poultry Farmers:High-density housing favors environmental monitoring over individual-animal tracking. EU F-Gas Regulation drives cooling system retrofits alongside climate control upgrades.
- Aquaculture Operators:Dissolved oxygen sensors and automated feeding systems for intensive fish farming. Norwegian salmon producers anchor demand in this emerging segment.
Dairy Farmers anchor revenue today; Beef Producers are expanding most quickly as unit economics improve.
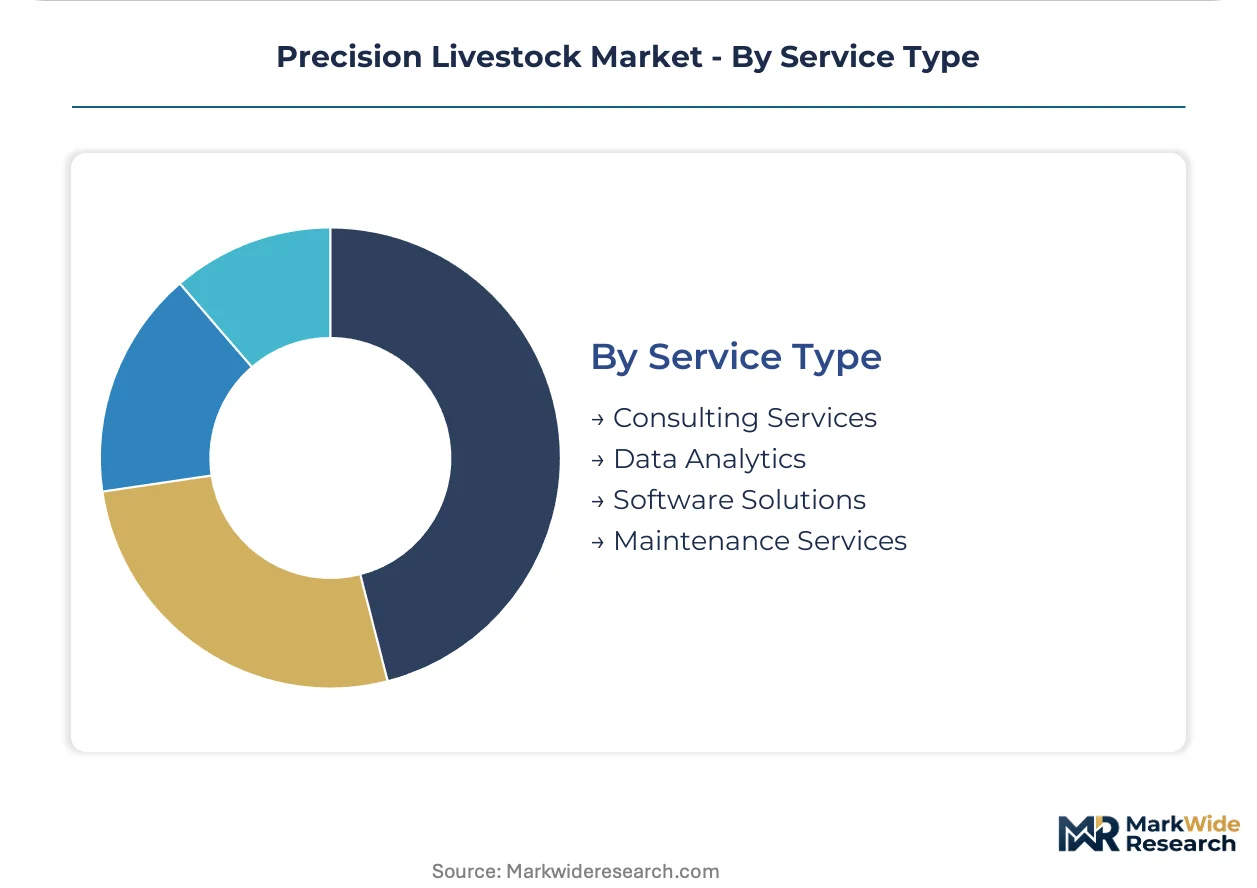
Service Type:
Delivery model preferences shift with in-house technical capacity and regulatory reporting complexity.
- Data Analytics:Cloud-based algorithmic interpretation of sensor streams for predictive health and productivity insights. Mid-scale operations outsource this capability given veterinary data science talent scarcity.
- Software Solutions:Herd management platforms integrating third-party sensor feeds into unified dashboards. Multi-vendor integration friction drives demand for interoperability layers.
- Consulting Services:Technology selection support, change management, and staff training. Equipment vendors bundle these to reduce deployment failure rates.
- Maintenance Services:Predictive repair contracts and sensor calibration programs. Wisconsin and Ontario dairy farmers increasingly prefer leased systems with bundled uptime guarantees.
Data Analytics captures the fastest-climbing share; Software Solutions retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting capital toward regions with clearer compliance pathways and stronger subsidy frameworks for agricultural automation.
Netherlands
Dutch dairy cooperatives deploy sensor networks at scale to satisfy EU Green Deal emissions disclosure mandates. The national government channels innovation grants through Wageningen University partnerships. Friesland and Noord-Brabant host concentrated clusters where robotic milking penetration exceeds any other European region.
United States
USDA Conservation Reserve Program incentives now cover methane-reduction technologies, pulling venture capital toward enteric fermentation monitoring. FDA residue-testing protocols and antibiotic-use tracking requirements drive automated health system procurement. Wisconsin and California anchor demand, with Wisconsin dairies increasingly favoring leased robotic systems over capital purchase.
Brazil
Underpenetrated cattle ranching operations in Mato Grosso and Pará states present first-mover positioning for integrated herd management platforms. ANVISA regulatory frameworks for veterinary device registration remain less granular than FDA or EMA equivalents, compressing market entry timelines. São Paulo-based equipment distributors are expanding technical service capacity to support precision technology deployment.
Germany
German dairy technology suppliers face compressed certification timelines under EU F-Gas Regulation refrigerant phase-down requirements. Bavarian and Lower Saxony equipment manufacturers are redesigning compressor architectures for lower-global-warming-potential alternatives. Munich and Hanover industrial clusters concentrate climate-controlled barn design expertise.
Australia
Rural broadband dead zones in Queensland and New South Wales limit real-time data transmission from remote pasture-based grazing systems. TGA-equivalent agricultural device standards create moderate regulatory friction for imported sensor hardware. Victorian dairy regions near Melbourne maintain stronger connectivity infrastructure and anchor domestic precision technology adoption.
Precision Livestock Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent analytics services and regional market expansion. The vendor base separates into three recognizable clusters: full-line automation platforms, specialized sensor hardware manufacturers, and software-centric analytics providers. Consolidation pressure intensifies as farms demand unified dashboards over point solutions. Equipment vendors are pivoting toward recurring data-service revenue models, while semiconductor supply constraints force strategic inventory positioning.
Within the full-line automation tier, DeLaval and GEA Farm Technologies exemplify integrated platform strategies spanning milking, feeding, and climate systems. Nedap N.V. occupies a distinct position in livestock identification and monitoring hardware, particularly where EU traceability mandates tighten. These three anchors represent divergent competitive vectors: one emphasizes robotics breadth, another targets specialized environmental solutions, and the third dominates identification infrastructure.
| Leading Market Players |
|---|
| DeLaval |
| GEA Farm Technologies |
| Afimilk Ltd. |
| Allflex Livestock Intelligence |
| BouMatic |
| Nedap N.V. |
| Lely |
| SCR Dairy |
| Dairymaster |
| Others |
Value Network & Pricing Analysis
Veterinary data science talent concentration in the Netherlands and Denmark widens labor-cost differentials between premium full-service platforms and economy hardware-only tiers. Dutch cooperative consolidation absorbs these specialists into integrated automation vendors, compressing margin spreads for mid-market sensor suppliers competing on price.
Pricing Analysis
Distributor margins of 15-25% separate factory-gate sensor hardware from farm-delivered installed systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU F-Gas Regulation-compliant cooling systems commanding material premiums over legacy refrigerant architectures. Pricing pressure stems from semiconductor supply constraints inflating RFID microcontroller costs. Mid-scale dairy cooperatives exhibit highest price sensitivity, while Netherlands-based premium rotary milking operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Eindhoven, Hanover, and Madison anchor hub-and-spoke patterns for spare parts and sensor calibration services. Taiwan, Germany, and the United States concentrate semiconductor foundry capacity and precision machining for milking robotics. Raw material dependencies include lithium-ion cells for wearable battery systems, rare earth elements for RFID antenna substrates, and specialized polymers for rumen bolus housings. Single-source vulnerability in Taiwan-domiciled microcontroller fabrication creates procurement risk. Distribution runs through agricultural equipment dealer networks with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU Green Deal compliance specifications filter procurement toward integrated platforms with audit-ready data infrastructure. Premium automation vendors capture expanding margin pools as regulatory granularity intensifies.
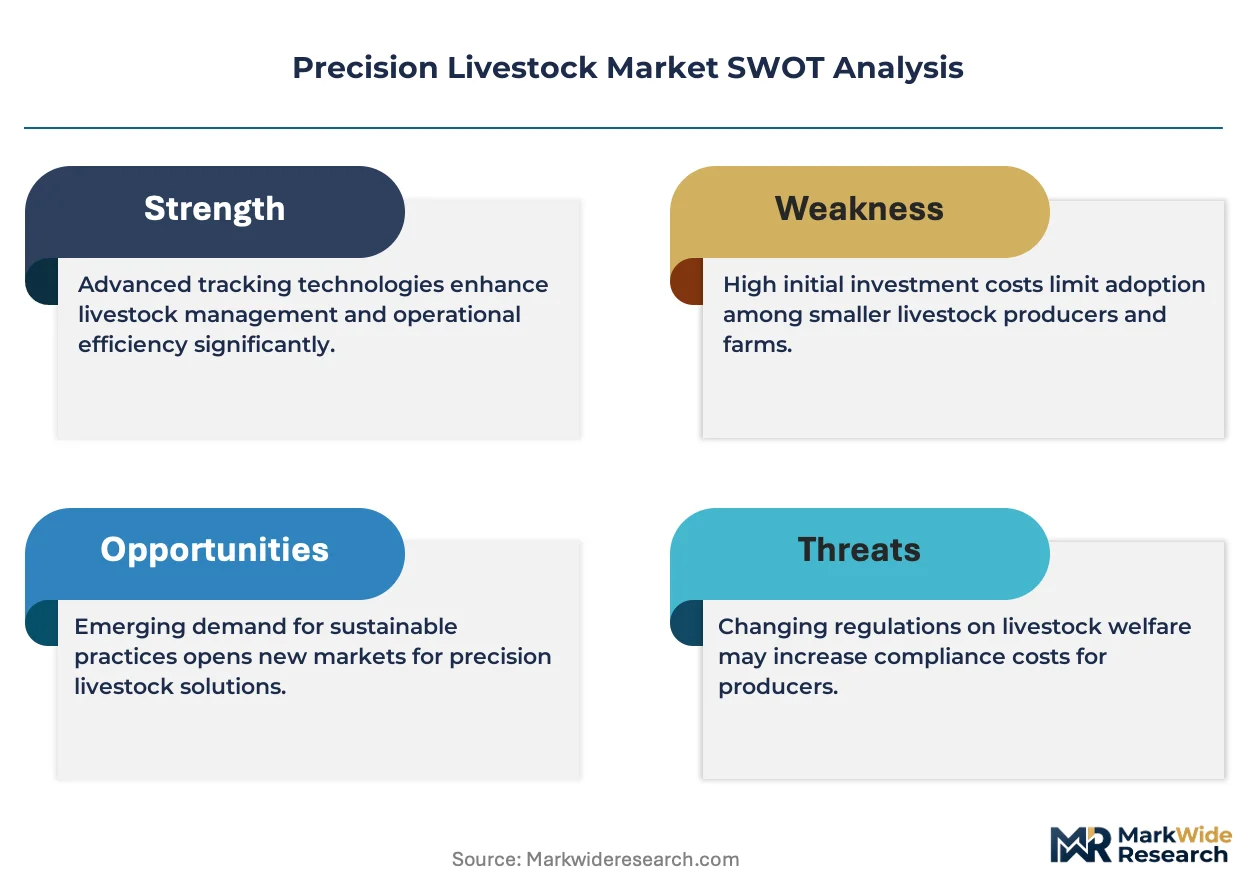
For Market Incumbents: Deploy subscription revenue conversion as the priority lever. DeLaval and GEA Farm Technologies should accelerate service contracting displacement of capital sales in Wisconsin and Ontario to lock in multi-year recurring streams. Backward integration into sensor firmware development reduces Taiwan foundry exposure. Certification investment for EU F-Gas Regulation refrigerant transitions protects market access against compressed compliance timelines. For New Entrants and Emerging Players: Brazilian cattle ranchers in Mato Grosso represent the most penetrable buyer archetype. Underpenetrated beef operations lack incumbent automation relationships and tolerate higher deployment failure rates than dairy cooperatives. Edge AI computer vision for lameness detection bypasses cloud connectivity gaps that limit incumbent IoT platforms. ANVISA's less granular veterinary device registration compresses market entry timelines versus FDA or EMA pathways. For Investors and Strategic Acquirers: Full-line automation platforms are the most active acquirer in this space, consolidating specialized sensor hardware and analytics capabilities into unified ecosystems. Long-term viability hinges on data-service revenue ratios exceeding hardware sales within the projection horizon. Acquisition targets should demonstrate veterinary data science talent depth and existing integration partnerships with DeLaval or GEA. Watch for USDA Conservation Reserve Program incentive expansion as inflection signal for methane-monitoring technology demand.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contracting Conversion | Transfers technology obsolescence risk to vendors while capturing recurring revenue from Wisconsin dairy cooperatives. |
| Edge AI Computer Vision Deployment | Reduces latency for behavioral anomaly alerts without continuous uplink dependency in Australian pasture systems. |
| F-Gas Refrigerant Transition | Maintains EU market access for German compressor manufacturers facing compressed certification timelines. |
| Brazilian Distribution Partnership | Positions integrated platforms for first-mover capture in Mato Grosso cattle ranching digitization. |
| Data Analytics Capability Acquisition | Addresses veterinary data science talent scarcity constraining farm-side algorithmic interpretation. |
Research Methodology
Multiple input streams — primary interviews with dairy cooperative technology officers, veterinary data scientists, and agricultural equipment distributors; secondary validation through EU F-Gas Regulation filings, USDA Conservation Reserve Program documentation, and SEC disclosures from listed automation vendors; customs data for RFID and sensor hardware trade flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged robotic milking system operators, barn climate engineering specialists, and compound feed procurement managers across Netherlands, Wisconsin, and São Paulo state clusters.
Data-stream reconciliation anchored volume and value outputs across the analysis window. Segmentation dimensions modeled include technology tier, application use case, end-user production system, and service delivery model, with additional granularity on EU regulatory compliance status. CAGRs were derived from installed base growth curves and replacement cycle dynamics. Forecast inputs incorporated rumen bolus battery life extension trajectories and cloud connectivity infrastructure buildout schedules in target geographies.
Underlying measurement precision varies by segment; dairy farmer automation adoption rates carry tighter precision than beef producer sensor deployment given more mature data infrastructure. Forecasts reflect documented assumptions around semiconductor supply normalization and EU Green Deal enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Digital Agriculture Platform Market