
 Crop Monitoring Technology in Precision Farming Market | 2026-2036
Crop Monitoring Technology in Precision Farming Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Monitoring Technology in Precision Farming Market Analysis
NDVI-grade imagery resolution is rotating toward the center of procurement decisions across commercial farming operations. Deere & Company leverages its integrated displays-to-cloud connectivity to anchor premium service tiers. CNH Industrial N.V. competes through Raven-branded application control systems that extend into aftermarket retrofit channels. TartanSense specializes in AI-driven pest detection hardware for smallholder-dominated districts in South Asia.
Crop monitoring technology in precision farming denotes sensor-to-decision systems that collect spectral, thermal, and biometric field data at sub-meter resolution to enable variable-rate input application and early stress detection. These platforms fuse multispectral imagery with soil electrical conductivity mapping and microclimate telemetry to generate prescription maps for seeding, irrigation, and crop protection. Satellite imaging and drone-based platforms currently occupy the largest value pools, though soil sensors are gaining share as edge-computing deployments reduce latency for irrigation automation. Machine learning models trained on yield-history layers now dominate technology roadmaps, while IoT mesh networks sustain connectivity in remote acreage where cellular coverage fails.
The European Green Deal's Farm to Fork Strategy and the EU AI Act create dual compliance obligations for algorithmic input recommendations and chemical reduction targets. The US EPA and FAA jointly govern drone application altitudes and pesticide payload thresholds, shaping hardware specifications for aerial platforms. Brazil's national agricultural regulator ANVISA coordinates with the Ministry of Agriculture on drone spraying certifications, tightening market access for unapproved equipment. Stakeholders must monitor how sustainability disclosure mandates in the EU and emerging carbon credit protocols in North America reshape the economic case for monitoring subscription models versus capital-intensive hardware ownership.
Market Dynamics
Subscription-based imagery platforms are compressing capital expenditure cycles for large-scale row-crop operators, forcing hardware manufacturers to defend installed bases through cloud-integrated service tiers rather than equipment refresh revenues.
Growth Catalysts
- EU Farm to Fork Strategy:Mandatory sustainability reporting for agricultural inputs is compelling commercial farms to deploy spectral monitoring systems that generate auditable chemical reduction documentation for export compliance.
- Edge computing architectures:Latency reduction in irrigation automation is accelerating soil sensor deployments that previously stalled on connectivity limitations in remote acreage.
- Mato Grosso soybean consolidation:Brazilian producers are bundling precision agriculture investments to simultaneously optimize input costs and satisfy EU import standards.
Market Restraints
- Cellular coverage gaps:IoT mesh network dependency in remote farming districts inflates total cost of ownership where terrestrial infrastructure remains sparse.
- Drone payload thresholds:Joint EPA-FAA regulations on pesticide application altitudes constrain aerial platform specifications and limit operational flexibility.
- ANVISA certification timelines:Brazil's agricultural regulator coordinates with the Ministry of Agriculture on drone spraying approvals, creating equipment market access delays for unapproved hardware.
Strategic Opportunities
- Smallholder districts in South Asia:AI-driven pest detection hardware remains underpenetrated where manual scouting dominates and labor costs are compressing margins.
- Carbon credit protocols:Emerging North American verification frameworks for soil carbon sequestration create monetizable data streams from existing monitoring subscriptions.
- Multispectral-thermal fusion:Convergence of biometric stress detection with microclimate telemetry enables new prescription mapping for variable-rate irrigation.
Industry Challenges
- Yield-history data interoperability:Machine learning model training requires standardized field boundary and crop rotation records that legacy farm management software formats fragment across platforms.
- Dual compliance architecture:Simultaneous satisfaction of EU AI Act algorithmic transparency requirements and EPA operational safety standards strains development resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Monitoring Technology in Precision Farming Market |
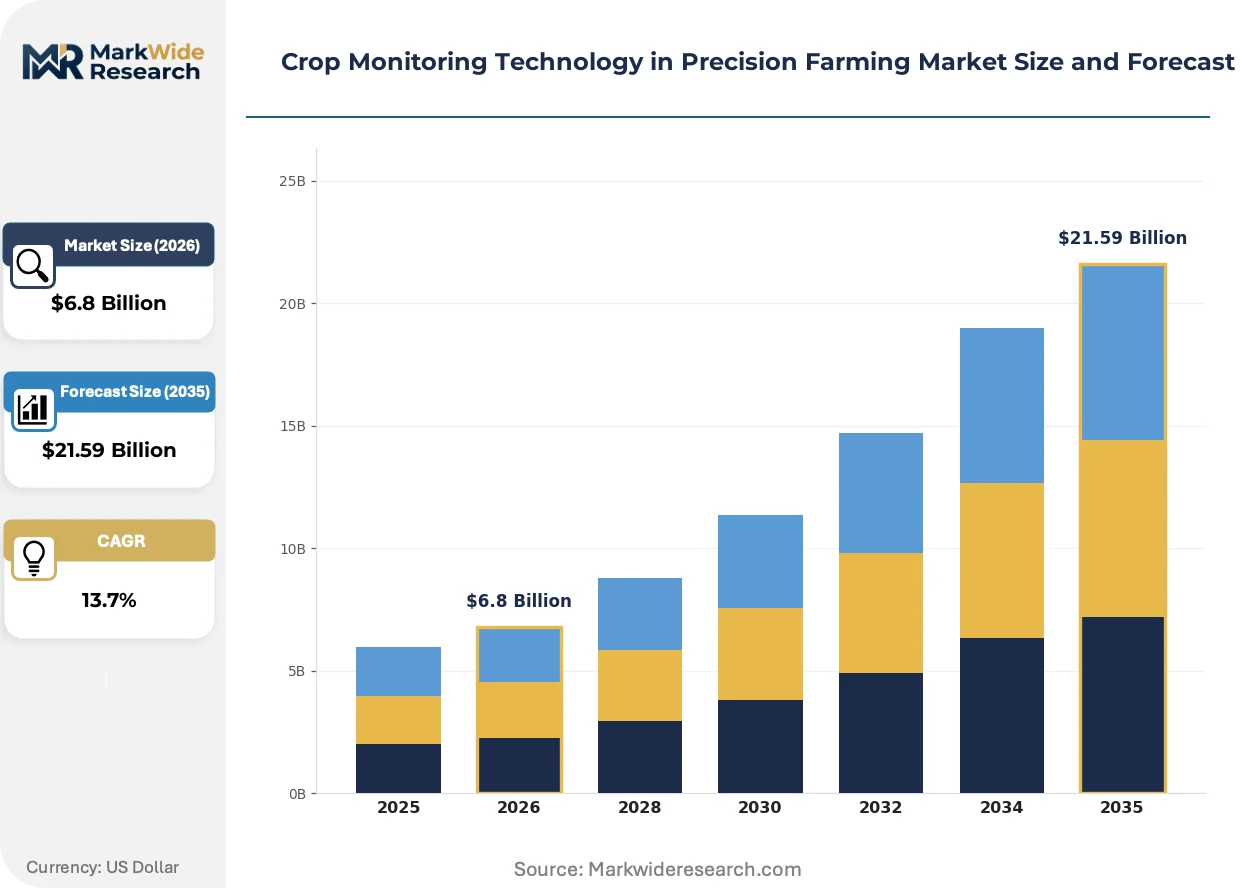
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Imaging, Drones, Soil Sensors, Weather Stations Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Farmers, Agricultural Cooperatives, Research Institutions, Agribusiness Technology: Machine Learning, IoT, Remote Sensing, Big Data Analytics |
| Companies Covered | Topcon Corporation, Plantix, Deere & Company, Instacrops, Agrosmart, CNH Industrial N.V., Farmonaut Technologies, TartanSense, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Monitoring Technology in Precision Farming Market Emerging Trajectories
Sensor-to-decision architectures are fragmenting into modular component markets as buyers resist vertically locked ecosystems. Three concurrent developments are reshaping competitive positioning.
Hyperspectral imaging is decomposing the NDVI-grade resolution standard that dominated procurement decisions for commercial operations. Row-crop managers in the North American Corn Belt are piloting narrow-band sensors that detect early nutrient stress before visible symptoms emerge. This capability compression is decomposing premium pricing tiers for multispectral platforms by exposing performance gaps in legacy hardware specifications.
REACH chemical authorization protocols under the European Green Deal are tightening residue monitoring requirements for imported soybeans and corn. EU-bound export operations must now deploy continuous field surveillance to document pre-harvest interval compliance. Brazilian producers in Mato Grosso are responding by consolidating application control data with satellite imagery archives to generate chain-of-custody evidence.
After-sales service unbundling is disrupting traditional equipment-software bundle structures. Buyers in precision farming are separating hardware procurement from analytics subscriptions, forcing vendors to defend recurring revenue through API interoperability rather than display ecosystem lock-in. This pattern is most visible in North American large-scale operations where fleet heterogeneity from multiple OEMs complicates single-vendor cloud commitments.
Crop Monitoring Technology in Precision Farming Market Segmentation
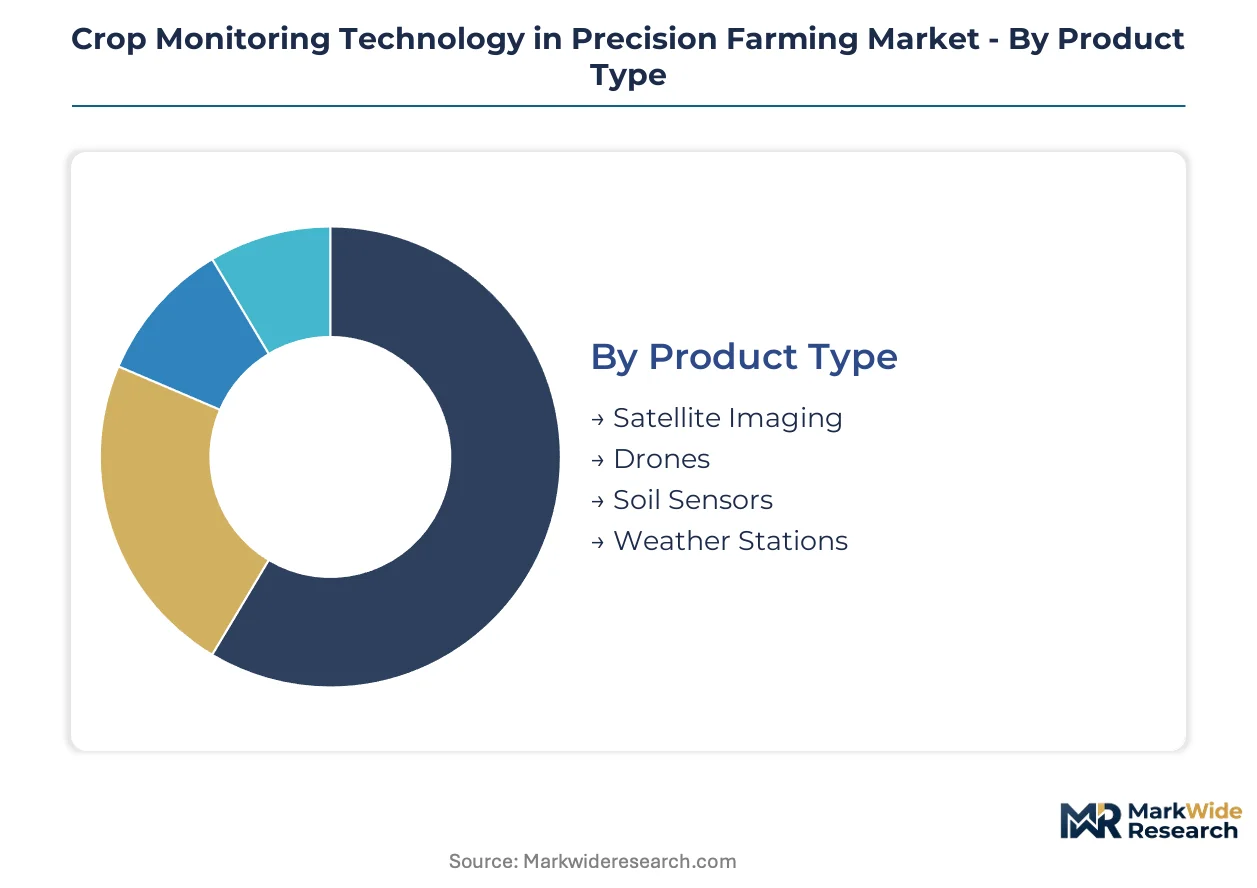
Crop monitoring technology segments fragment along connectivity infrastructure maturity and data sovereignty requirements. Procurement decisions increasingly separate hardware acquisition from analytics subscriptions, forcing vendors to defend position through interoperability rather than ecosystem lock-in.
Product Type:
Satellite imaging platforms face the strongest substitution pressure from drone-based systems as regulatory clarity on low-altitude spraying expands operational envelopes for aerial alternatives.
- Satellite Imaging:Multispectral and hyperspectral platforms deliver sub-meter resolution across thousands of hectares without terrestrial infrastructure. Demand concentrates in Brazil's Mato Grosso state, where soybean exporters require continuous field surveillance to document pre-harvest interval compliance for EU-bound shipments under REACH protocols.
- Drones:Rotary and fixed-wing unmanned aerial vehicles carry NDVI-grade sensors and variable-rate application payloads. US Corn Belt row-crop operators are accelerating adoption as joint EPA-FAA regulations clarify operational altitudes and pesticide payload thresholds, though ANVISA certification timelines in Brazil create market access delays for unapproved equipment.
- Soil Sensors:Electrical conductivity and moisture probes enable edge-computing irrigation automation.
- Weather Stations:Microclimate telemetry nodes fuse biometric stress detection with prescription mapping.
Satellite imaging retains volume leadership; drones hold the steepest expansion curve.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from recurring subscription models that compress upfront expenditure cycles.
- Cloud-Based:Centralized data lakes process spectral imagery through API-accessible machine learning pipelines. Large-scale North American operators favor this model for fleet heterogeneity management across multiple OEM equipment lines.
- Edge Computing:Distributed processing architectures reduce latency for automated irrigation triggers in remote acreage where cellular coverage fails. Mato Grosso producers deploy these nodes to maintain operational continuity beyond terrestrial network boundaries.
- Hybrid:Split architectures balance local preprocessing with cloud-based model training.
- On-Premises:Dedicated server installations serve data sovereignty requirements in research and institutional settings.
Cloud-based deployments dominate commercial farm procurement; edge computing is climbing the fastest as connectivity gaps persist in remote districts.
End User:
Customer type determines purchasing authority structure, from individual farm managers to consolidated cooperative procurement committees.
- Agribusiness:Vertically integrated operators manage portfolio-scale monitoring across dispersed acreage. These entities demand standardized field boundary and crop rotation records that legacy farm management software formats fragment across platforms.
- Agricultural Cooperatives:Member-owned entities pool precision agriculture investments to achieve input cost optimization at collective scale. EU Farm to Fork Strategy compliance obligations drive spectral system adoption for chemical reduction documentation.
- Farmers:Individual operators select modular components resistant to vertically locked ecosystems.
- Research Institutions:Academic and government laboratories require algorithmic transparency under EU AI Act provisions for model training validation.
Agribusiness commands the largest contract values; agricultural cooperatives are expanding most quickly as consolidation accelerates in export-oriented regions.
Technology:
Technology maturity curves separate proven remote sensing architectures from emerging machine learning pipelines that dominate vendor roadmaps.
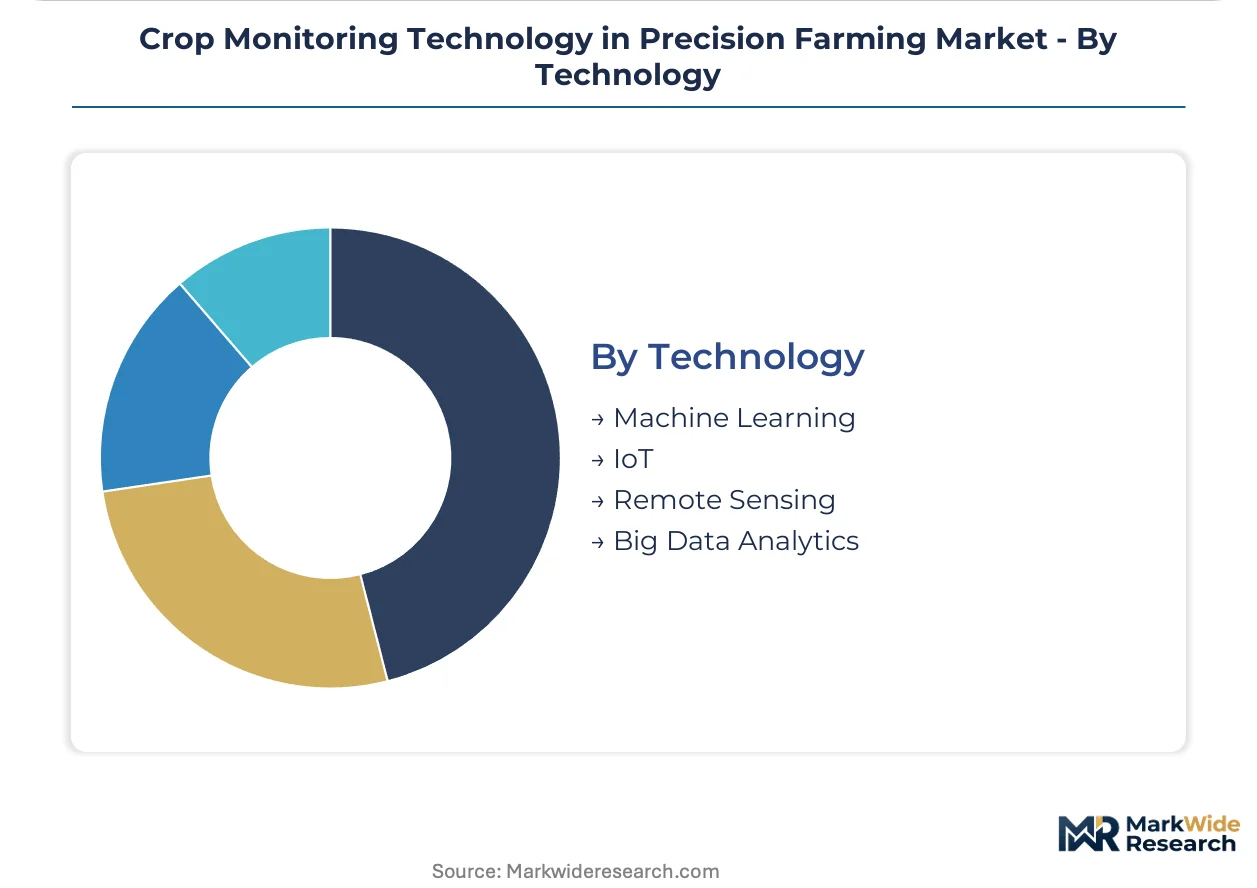
- Machine Learning:Yield-history layer training enables predictive stress detection before visible symptoms emerge. Model development strains under dual compliance obligations requiring simultaneous satisfaction of EU AI Act algorithmic transparency and EPA operational safety standards.
- Remote Sensing:Multispectral, thermal, and hyperspectral data capture constitutes the foundational data layer for all monitoring architectures. This technology anchors procurement decisions as resolution specifications decompose legacy hardware pricing tiers.
- IoT:Mesh network protocols sustain connectivity in cellular dead zones through distributed node architectures.
- Big Data Analytics:Historical yield and input archives generate prescription maps for variable-rate application.
Remote sensing maintains installed base dominance; machine learning is gaining share fastest as prescription automation replaces manual scouting workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented farming economies drive procurement intensity for crop monitoring systems, with compliance documentation for destination markets shaping technology selection. Import-dependent regions prioritize cost-efficient subscription models over capital-intensive hardware ownership.
United States
Corn Belt row-crop operators accelerate subscription-based imagery adoption to manage fleet heterogeneity across multiple OEM equipment lines. Joint EPA-FAA regulations clarify drone operational altitudes and pesticide payload thresholds, expanding aerial platform deployment envelopes. Large-scale agribusinesses in Iowa and Illinois consolidate precision agriculture investments to optimize input costs.
Brazil
Soybean producers in Mato Grosso state bundle monitoring technologies to satisfy EU import standards and REACH chemical authorization protocols. ANVISA coordinates with the Ministry of Agriculture on drone spraying certifications, creating equipment market access delays for unapproved hardware. Export-oriented operations deploy continuous field surveillance to document pre-harvest interval compliance.
Germany
Agricultural cooperatives pool precision farming investments to achieve collective-scale input optimization under Farm to Fork Strategy obligations. EU AI Act algorithmic transparency requirements strain machine learning model development resources. Bavarian and North Rhine-Westphalian farming clusters deploy spectral systems for mandatory chemical reduction documentation.
India
Smallholder-dominated districts in South Asia present underpenetrated demand for AI-driven pest detection hardware where manual scouting compresses margins. National agricultural extension programs promote precision technology adoption among fragmented landholdings. Punjab and Haryana rice-wheat systems pilot edge-computing irrigation nodes to overcome cellular coverage gaps.
Australia
Broadacre wheat and cotton operations leverage satellite imaging platforms across remote acreage where terrestrial infrastructure remains sparse. Emerging carbon credit verification frameworks create monetizable data streams from existing monitoring subscriptions. Queensland and New South Wales farming enterprises integrate soil sensor networks with microclimate telemetry for variable-rate irrigation automation.
Crop Monitoring Technology in Precision Farming Market Vendor Landscape
Concentration sits with integrated agricultural equipment manufacturers that anchor premium service tiers through cloud-connected display ecosystems. Tiered competition separates vertically integrated OEMs from specialized analytics providers and regional retrofit specialists. Hardware-software unbundling pressures traditional bundle structures as buyers separate equipment procurement from analytics subscriptions. Dominant competitive moves include API interoperability investments and aftermarket channel expansion through third-party application control systems.
Among integrated equipment manufacturers, Deere & Company and CNH Industrial N.V. exemplify the display-to-cloud connectivity archetype that defends installed bases against pure-play software entrants. AGCO Corporation occupies a position within the same tier, representing diversified agricultural machinery portfolios. TartanSense anchors the specialized hardware segment, exemplifying AI-driven pest detection focused on smallholder market penetration. Topcon Corporation represents precision positioning technology specialists that extend into agricultural automation through aftermarket retrofit channels.
| Leading Market Players |
|---|
| Topcon Corporation |
| Plantix |
| Deere & Company |
| Instacrops |
| Agrosmart |
| CNH Industrial N.V. |
| Farmonaut Technologies |
| TartanSense |
| AGCO Corporation |
| Others |
Supply Flow & Price Mechanics
Hyperspectral sensor substitution for NDVI-grade multispectral platforms is compressing premium pricing tiers while relocating component sourcing from Japanese optics houses to Taiwanese semiconductor foundries. This displacement simultaneously fragments legacy equipment margins and concentrates supply chain leverage among CMOS image sensor fabricators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on resolution specifications and cloud-connectivity bundling rather than hardware alone. Cost compression in subscription tiers is intensifying because Deere and CNH Industrial are unbundling analytics from display ecosystems. Agricultural cooperatives exhibit highest price sensitivity due to pooled procurement committee dynamics, while vertically integrated agribusinesses absorb premium tiers for API interoperability across fleet heterogeneity.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific trade lanes are elevating inbound logistics costs for edge-computing hardware sourced from Shenzhen and Taipei manufacturing clusters. Component supply concentrates in Taiwan for CMOS sensors, Germany for precision optics, and China for IoT mesh network hardware. Raw material dependencies span gallium arsenide for hyperspectral arrays, rare earth elements for sensor stabilization, and lithium-ion cells for drone power systems. Single-source vulnerability sits with Taiwanese semiconductor foundries. Distribution runs through OEM captive service networks and aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat architecture where cloud-connected display ecosystems generate switching costs that lock in recurring subscription revenues. Regulatory entrenchment via EPA-FAA operational certifications and ANVISA drone spraying approvals compounds incumbent advantage.
For Market Incumbents: Consolidate application control data archives with satellite imagery to generate chain-of-custody documentation for EU REACH compliance. Acquire edge-computing irrigation automation specialists to defend against pure-play software entrants unbundling analytics from hardware. Channel control through Raven-branded retrofit systems extends installed base protection. For New Entrants and Emerging Players: Differentiate on AI-driven pest detection hardware for smallholder districts in South Asia where manual scouting dominates. Target agricultural cooperatives in Germany's Bavarian cluster seeking collective-scale input optimization under Farm to Fork obligations. Go-to-market through national extension programs in India's Punjab rice-wheat systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture analytics platforms lacking OEM distribution integration. Long-term viability hinges on API interoperability investments that transcend single-vendor cloud commitments. Watch for carbon credit protocol maturation in Australia and North America as inflection signal for monetizable data stream valuations.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Enables fleet heterogeneity management across Deere, CNH Industrial, and AGCO equipment lines. |
| Edge Computing Node Deployment | Reduces latency for automated irrigation triggers in Mato Grosso cellular dead zones. |
| ANVISA Certification Acceleration | Unlocks drone spraying market access in Brazil's soybean export corridor. |
| Hyperspectral Sensor Integration | Exposes performance gaps in legacy multispectral hardware specifications. |
| Carbon Credit Data Stream Development | Creates monetizable verification frameworks from existing monitoring subscriptions. |
Methodological Framework
Initial hypotheses were tested against primary input from precision agriculture platform engineers, agribusiness technology procurement directors, cooperative committee members, and ANVISA regulatory affairs specialists and refined through secondary validation. Sources included EPA drone operation filings, EFSA Farm to Fork implementation guidance, ANVISA certification databases, and OEM service revenue disclosures in SEC 10-K extracts. Bottom-up sensor deployment counts and top-down subscription revenue estimates were triangulated.
Variance decomposition across product type, deployment architecture, end-user consolidation level, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth curves and replacement cycle compression. Yield-history data interoperability standards and EU AI Act algorithmic transparency timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA-FAA joint governance, EU Green Deal REACH protocols, and ANVISA-Ministry of Agriculture coordination; material policy shifts would require re-modeling. Commodity price volatility in soybeans and corn, cellular infrastructure buildout pace, and hyperspectral sensor cost curves constitute specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Soil Moisture Meter Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
Variable Rate Technology Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market