
 Soil Moisture Sensor Market | 2026-2036
Soil Moisture Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Moisture Sensor Market Intelligence
Data analytics and subscription-based service revenue is reconfiguring the profit landscape, shifting value from hardware sales to ongoing monitoring solutions. This transition pressures traditional device manufacturers to build out software capabilities. Campbell Scientific, Inc. leverages its expertise in integrated environmental monitoring systems to offer comprehensive data logging and telemetry. METER Group, Inc. specializes in high-precision, scientific-grade sensors for research and high-value crop applications, differentiating on accuracy and data integrity.
A soil moisture sensor is an instrument that measures the volumetric water content in soil. These devices typically operate by measuring a proxy property, such as the soil's dielectric constant or electrical resistance, which correlates directly to moisture levels. Their primary purpose is to enable optimized irrigation scheduling for agriculture, landscaping, and scientific research, thereby conserving water and improving crop yields. Time Domain Reflectometry (TDR) sensors offer the highest accuracy for research fields, while capacitive sensors provide a cost-effective solution for large-scale farmland deployments. The adoption of wireless technologies like LoRaWAN is facilitating real-time data collection from vast and remote areas.
Regulatory frameworks directly influence market adoption by mandating water conservation. The European Union's Common Agricultural Policy (CAP) provides subsidies for farmers implementing precision agriculture tools. In the United States, the EPA's WaterSense program certifies irrigation controllers that use sensor data, promoting their use in landscaping. Water allocation plans in Australia, overseen by entities like the Murray-Darling Basin Authority, also drive the need for precise water usage monitoring. Stakeholders must now decide whether to prioritize low-cost, high-volume sensor networks or invest in higher-fidelity systems with advanced analytical overlays.
Market Dynamics
The market's structure is defined by the convergence of global water scarcity mandates and the agricultural sector's push for higher yields. This dynamic forces innovation in both sensor affordability for mass deployment and data analytics for precision resource management, creating a clear division between volume and value strategies.
Growth Catalysts
- Regulatory Subsidies:The EU's Common Agricultural Policy offers financial incentives for farmers adopting precision agriculture tools, directly boosting demand for water-saving sensor technologies.
- IoT Network Expansion:The spread of LoRaWAN enables cost-effective data collection from remote farms, making large sensor networks economically viable for agricultural operations.
- Precision Farming Demand:Large-scale farms in the United States and Australia require precise irrigation management, driving adoption of sensor networks to optimize water use.
Market Restraints
- High Initial Cost:The upfront investment for high-precision TDR sensors remains a significant barrier for smaller farms, limiting market penetration in that segment.
- Calibration Requirements:Sensor accuracy degradation from soil salinity and texture necessitates complex site-specific calibration, increasing operational overhead for farmers and researchers.
- Inertia of Traditional Methods:Low-tech irrigation scheduling based on fixed timers or visual inspection persists due to simplicity, acting as a non-technological substitute.
Strategic Opportunities
- Urban Green Infrastructure:Integrating sensors into smart city projects for automated irrigation of parks and green roofs opens a new non-agricultural application vertical.
- Predictive Analytics Platforms:Combining sensor data with AI and satellite imagery enables new subscription services for predictive irrigation, moving value beyond just hardware.
- Emerging Agricultural Economies:Targeting markets in Southeast Asia and Latin America, where water conservation policies are gaining traction, offers significant geographic expansion potential.
Industry Challenges
- Data Interoperability:A lack of standardization in data formats and communication protocols creates significant challenges in integrating sensors from different manufacturers into a unified farm management system.
- Cybersecurity of IoT Networks:Securing data transmitted from thousands of distributed wireless sensors against cyber threats is a major operational hurdle for both vendors and large-scale agricultural users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Moisture Sensor Market |
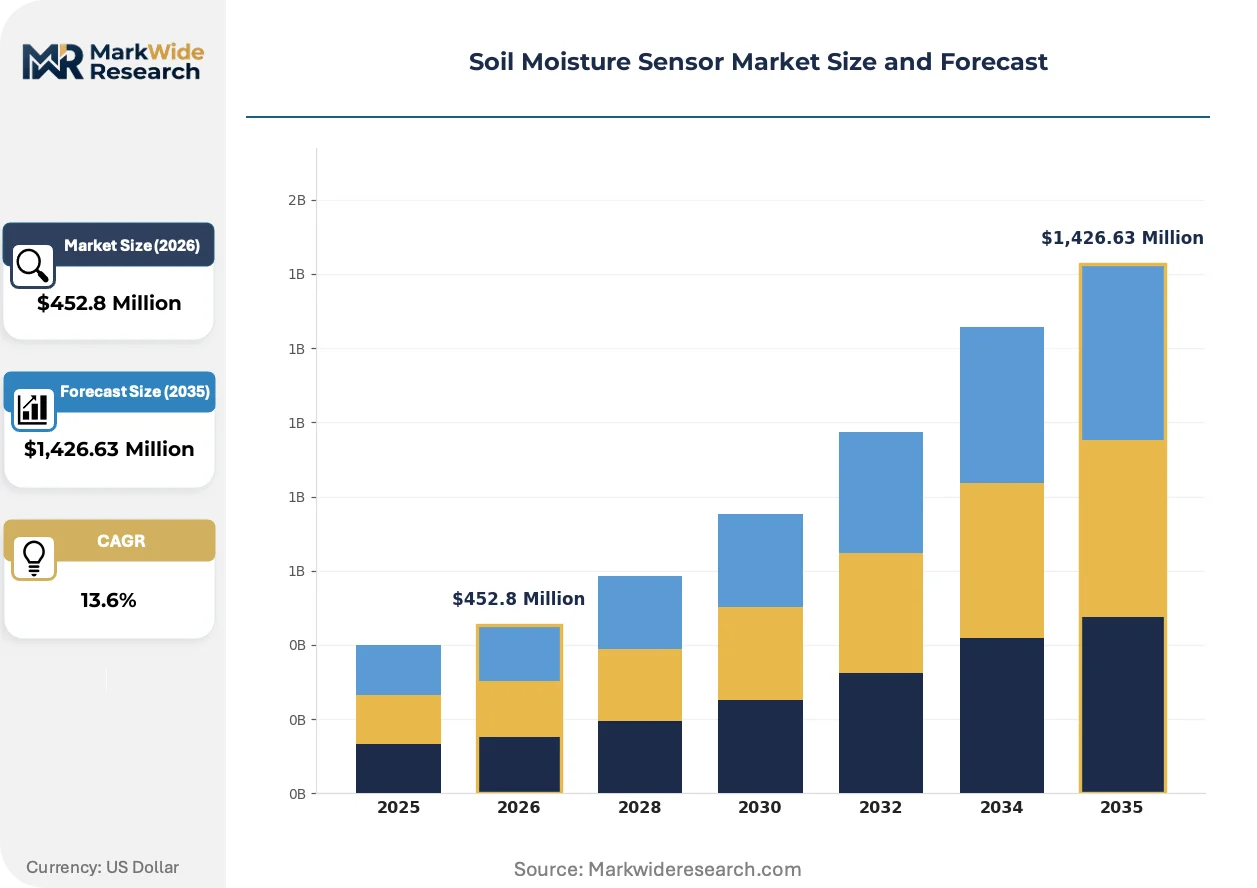
| Market Size in 2026 | $452.8 Million |
| Market Size in 2035 | $1,426.63 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Capacitive, Resistive, Time Domain Reflectometry, Frequency Domain Reflectometry, Gypsum Block Deployment Environment: Greenhouses, Farmlands, Golf Courses, Landscapes, Research Fields Technology: Wireless Sensors, LoRaWAN, NB-IoT, Bluetooth Low Energy, ZigBee End User: Agricultural Developers, Horticulturists, Turf Managers, Environmental Scientists, Soil Testing Labs |
| Companies Covered | Campbell Scientific, Inc., Irrometer Company, Inc., METER Group, Inc., Spiio, Inc., Acclima, Inc., Delta-T Devices, Sentek Technologies, Stevens Water Monitoring Systems Inc., Spectrum Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Moisture Sensor Market Strategic Shifts & Innovations
The market is evolving from discrete hardware sales toward integrated, data-driven agronomic solutions. This transition is marked by the fusion of sensing technologies, the influence of water conservation mandates, and a shift in how farmers procure and use data.
Multi-parameter sensors now combine volumetric water content measurement with soil temperature, electrical conductivity, and nutrient level monitoring. High-value crop producers and research institutions are rapidly adopting these devices to gain a holistic view of soil conditions. This development is hybridizing the function of a simple moisture meter with that of a complete soil health diagnostic tool.
In the United States, the EPA’s WaterSense program certifies irrigation controllers that leverage soil moisture sensor data to improve efficiency. This federal labeling initiative drives adoption in landscaping by offering a clear benchmark for water-saving performance. Consequently, irrigation equipment manufacturers are prioritizing the integration of certified sensor technology to meet consumer and municipal demand for WaterSense-labeled products.
A clear demand-side shift is the move from one-time hardware sales to subscription-based service models that bundle sensors with data analytics. This "Sensing-as-a-Service" approach is disrupting traditional equipment distributors by offering ongoing agronomic insights and support. The model is gaining the most traction with large agricultural corporations in the United States seeking outcome-based solutions over capital expenditures.
Soil Moisture Sensor Market Segmentation
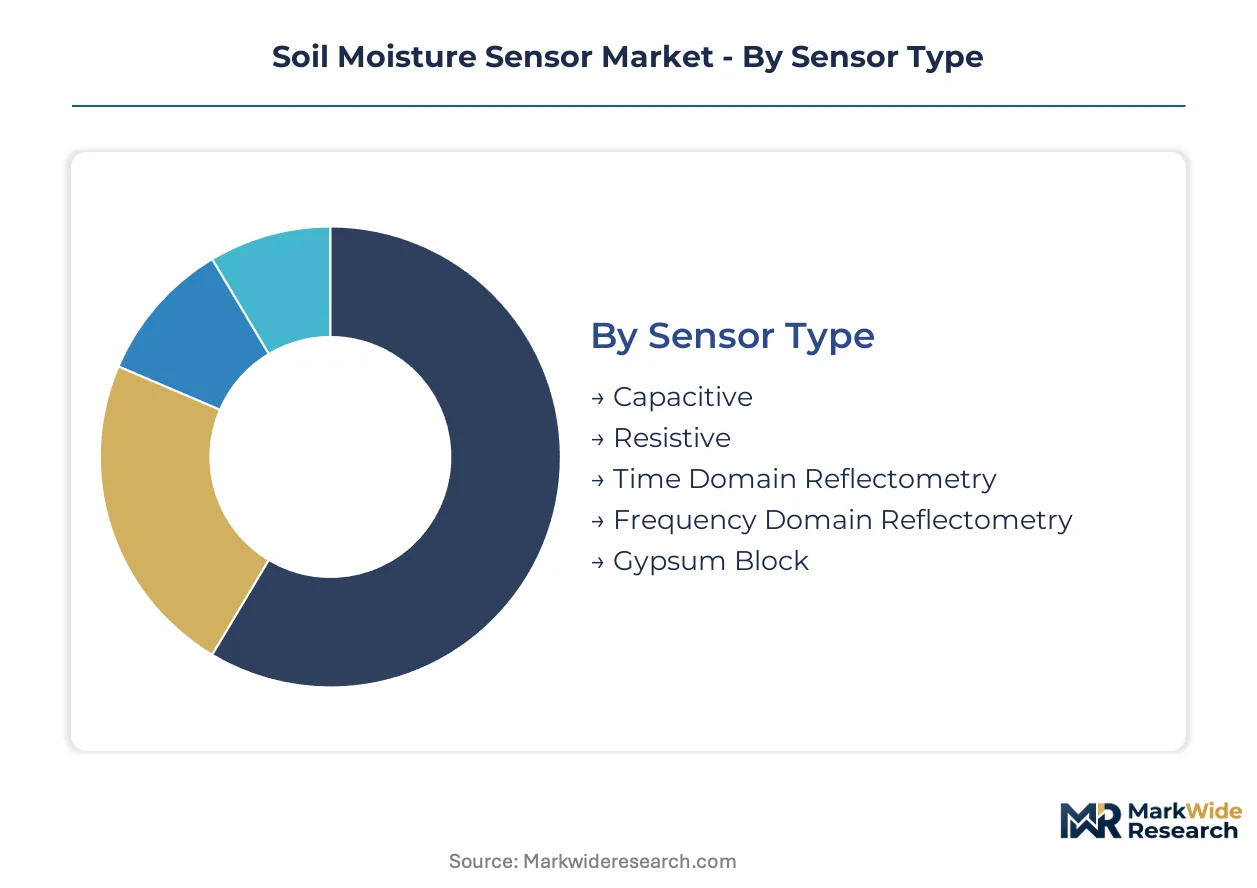
The Soil Moisture Sensor Market's segmentation reveals how diverse technological solutions address varied end-user needs across different environments. Understanding these distinct market components helps stakeholders identify specific growth opportunities and tailor product development. This granular analysis supports strategic decision-making for market penetration and innovation.
Sensor Type:
The sensor type segment exhibits a range from established, cost-effective technologies to advanced, high-precision instruments. This spectrum dictates application suitability and adoption patterns across diverse agricultural and research settings.
- Time Domain Reflectometry:These sensors measure soil dielectric constant by analyzing reflected electromagnetic pulses, providing highly accurate volumetric water content. Research fields and high-value crop producers demand TDR sensors for their precision in critical irrigation scheduling and scientific studies.
- Capacitive:Capacitive sensors determine soil moisture by measuring changes in electrical capacitance within the soil, offering a cost-effective and robust solution. Large-scale agricultural operations in the United States concentrate demand for capacitive sensors due to their affordability for vast farmland deployments.
- Resistive:Resistive sensors measure electrical resistance between electrodes, which changes with soil moisture, providing a simple and low-cost indication for basic irrigation needs.
- Frequency Domain Reflectometry:FDR sensors utilize an oscillating signal to measure soil dielectric properties, offering a balance of accuracy and cost for various agricultural applications.
- Gypsum Block:Gypsum block sensors measure soil matric potential through the electrical resistance of a gypsum block, suitable for monitoring soil dryness in specific horticultural contexts.
Capacitive sensors retain volume leadership; Time Domain Reflectometry holds the steepest expansion curve due to increasing precision farming demands.
Deployment Environment:
Deployment environments dictate sensor specifications, ranging from controlled indoor settings to expansive outdoor agricultural areas. Each environment presents unique challenges for sensor longevity, data transmission, and installation.
- Farmlands:These environments encompass vast outdoor agricultural areas requiring extensive sensor networks for optimized irrigation management. Large-scale farms in Australia and the United States drive demand for robust, wireless sensors to maximize crop yields and conserve water across wide areas.
- Research Fields:Controlled experimental plots and scientific study sites utilize sensors for precise data collection on soil-plant-water interactions. Environmental scientists and academic institutions prioritize high-accuracy sensors for detailed hydrological modeling and crop physiology investigations.
- Greenhouses:Controlled indoor agricultural facilities use sensors to maintain optimal soil moisture for high-value crops under regulated climate conditions.
- Golf Courses:Turf management professionals deploy sensors to ensure optimal turf health and efficient water use on extensive recreational green spaces.
- Landscapes:Urban green spaces, public parks, and residential gardens utilize sensors for automated, water-efficient irrigation systems certified by programs like EPA WaterSense.
Farmlands represent the largest deployment segment; Landscapes represent the fastest-growing trajectory due to urban green infrastructure initiatives.
Technology:
Communication technologies define how soil moisture data is transmitted from the field to central monitoring systems. This segment reflects the ongoing shift towards real-time data collection and remote management capabilities.
- Wireless Sensors:These devices transmit soil moisture data without physical cable connections, enabling flexible deployment across large or remote areas. Agricultural developers increasingly adopt wireless sensors to facilitate real-time monitoring and automated irrigation scheduling on expansive farmlands.
- LoRaWAN:This Low-Power Wide-Area Network protocol offers long-range communication with minimal power consumption, ideal for battery-powered sensors in rural settings. The expansion of IoT infrastructure makes LoRaWAN a preferred choice for cost-effective data collection from remote agricultural sites.
- NB-IoT:Narrowband Internet of Things technology provides secure and reliable cellular connectivity for sensors, suitable for applications requiring consistent data transmission over long distances.
- Bluetooth Low Energy:BLE enables short-range, low-power data transfer, primarily used for localized monitoring or direct sensor-to-handheld device communication in smaller plots or greenhouses.
Wireless Sensors dominate the market volume; LoRaWAN technology demonstrates significant growth due to its remote monitoring capabilities.
End User:
End-user segments highlight the diverse professional groups leveraging soil moisture data for specific operational or research outcomes. Each group has distinct requirements for sensor accuracy, data integration, and analytical support.
- Agricultural Developers:These professionals manage large-scale farming operations, integrating soil moisture data to optimize irrigation, enhance crop yields, and conserve water resources. Precision farming initiatives, particularly in the United States and Australia, drive significant demand from this end-user group.
- Environmental Scientists:Researchers and academics utilize soil moisture sensors for detailed studies on hydrology, climate change impacts, and ecosystem dynamics. This group prioritizes high-fidelity data for accurate modeling and scientific investigations in various ecological contexts.
- Horticulturists:Professionals managing nurseries, orchards, and vineyards use sensors to optimize water application for specialized and high-value plant cultivation.
- Turf Managers:Individuals overseeing golf courses, sports fields, and public parks deploy sensors to maintain healthy turf while minimizing water consumption.
- Soil Testing Labs:These facilities use sensors for controlled experiments and to validate soil moisture measurements, supporting agricultural and environmental research.
Agricultural Developers remain the main demand driver; Environmental Scientists represent a high-value niche for advanced sensor systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Soil Moisture Sensor Market's demand concentration is evident in agricultural powerhouses, driving specialized sensor development and deployment. Precision farming initiatives in the United States and Australia significantly influence market dynamics. European Union policies further stimulate demand for water-saving technologies across its member states.
United States
United States agricultural developers drive significant demand for soil moisture sensors, particularly for optimizing irrigation in large-scale operations. The EPA's WaterSense program promotes sensor-enabled irrigation controllers, boosting adoption in landscaping. California's Central Valley, a major agricultural hub, leverages these sensors to manage water resources for diverse high-value crops.
Australia
Australia's extensive agricultural sector, especially large-scale farms, necessitates precise irrigation management for water conservation. The Murray-Darling Basin Authority's water allocation plans directly influence sensor adoption for usage monitoring. Farmers in the Murray-Darling Basin region deploy robust sensor networks to comply with water efficiency mandates.
Germany
Germany's agricultural sector benefits from strong support for precision farming and sustainable resource management. The EU's Common Agricultural Policy provides financial incentives for farmers adopting sensor technologies. Bavarian agricultural technology firms develop integrated solutions, combining sensors with advanced analytics for efficient crop production.
India
India's vast agricultural landscape increasingly seeks soil moisture sensors to enhance crop yields and address water scarcity challenges. Government programs promoting agricultural modernization support the adoption of water-saving technologies. Farmers in states such as Maharashtra are integrating sensors for optimized irrigation in diverse cultivation practices.
Brazil
Brazil's expansive agricultural operations, particularly in commodity crops, require efficient water management for sustained productivity. National agricultural policies increasingly emphasize sustainable practices and resource optimization. Large farms in the Mato Grosso region utilize soil moisture sensors to precisely manage irrigation for vast cultivation areas.
Soil Moisture Sensor Market Key Industry Players
High-precision specialists and integrated solutions providers split the competitive landscape in the soil moisture sensor market. The market exhibits a tiered structure, with distinct offerings catering to research-grade accuracy versus large-scale agricultural affordability. Companies pursue portfolio diversification, moving from discrete hardware sales to offering data analytics and subscription-based monitoring services. Strategic partnerships with IoT network providers also expand market reach and data collection capabilities.
Within the integrated solutions provider archetype, Campbell Scientific, Inc. exemplifies a company leveraging expertise in environmental monitoring systems. METER Group, Inc. represents the high-precision, scientific-grade sensor segment, differentiating on accuracy for research and high-value crop applications. Irrometer Company, Inc., a US-based firm, occupies a position among established sensor manufacturers serving diverse agricultural and landscaping needs. These entities anchor distinct value propositions, from comprehensive data logging to specialized measurement fidelity.
| Leading Market Players |
|---|
| Campbell Scientific, Inc. |
| Irrometer Company, Inc. |
| METER Group, Inc. |
| Spiio, Inc. |
| Acclima, Inc. |
| Delta-T Devices |
| Sentek Technologies |
| Stevens Water Monitoring Systems Inc. |
| Spectrum Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Asian manufacturing hubs for microcontrollers and communication modules concentrate upstream supply, directly influencing the cost structure and margin distribution across the soil moisture sensor market. This supply concentration impacts the affordability of sensor hardware, ultimately affecting downstream pricing for agricultural developers and research institutions.
Pricing Analysis
The EU's Common Agricultural Policy dictates the pricing tier structure, incentivizing sensor adoption for sustainable farming. Pricing stratifies across premium, standard, and economy tiers, driven by sensor accuracy and advanced data analytics overlays. Price differentiation stems from the precision level of TDR sensors versus the cost-effectiveness of capacitive models. Pricing softness runs through the high-volume capacitive segment due to increasing competition and demand for affordability. Agricultural developers managing large-scale operations are generally less price-sensitive for high-fidelity data solutions, while smaller farms exhibit higher price sensitivity.
Supply Chain Analysis
The supply chain for soil moisture sensors draws from global electronic component manufacturers. Geographic supply concentration includes China for microcontrollers and other Asian countries for printed circuit boards. Raw material dependencies include silicon wafers for chips, specialized plastics for enclosures, and various metals for sensing elements. A structural supply chain risk is the single-source vulnerability for specific electronic components, which can cause production delays. Distribution runs through specialized agricultural technology distributors, direct sales channels to large enterprises, and system integrators for smart city projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soil moisture sensor market presents a capability scarcity in integrating advanced data analytics with robust hardware, creating a clear gap in comprehensive agronomic solutions.
For Market Incumbents:
Entrench market position by investing heavily in AI-driven predictive analytics platforms, moving beyond simple data logging. Develop strategic partnerships with regional IoT network providers to expand remote data collection capabilities, countering the threat of fragmented data ecosystems. Focus R&D on multi-parameter sensors that offer holistic soil health insights, providing a stronger value proposition against basic moisture meters. Consolidate market share through targeted acquisitions of software-centric startups that possess strong data science expertise.
For New Entrants and Emerging Players:
Geographic underpenetration in Southeast Asia offers significant expansion opportunities for cost-effective sensor solutions. Target urban green infrastructure projects and specialized high-value crop applications as white-space opportunities. The most penetrable segment remains small to medium-sized farms seeking accessible, easy-to-deploy wireless sensor networks. A compelling go-to-market angle involves bundling low-cost hardware with user-friendly mobile applications for immediate actionable insights, minimizing initial investment barriers for new users.
For Investors and Strategic Acquirers:
Capital is best deployed toward companies offering integrated hardware-software solutions with strong data analytics and subscription-based service models. The long-term viability of this market is anchored in global water scarcity mandates and the irreversible shift towards precision agriculture. Acquisition targets should include firms specializing in AI-powered agronomic platforms or those with established LoRaWAN network integration capabilities. The adoption rate of outcome-based "Sensing-as-a-Service" models is a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Predictive Analytics Platforms | Combining sensor data with AI enables farmers to optimize irrigation schedules and reduce water consumption. |
| Form IoT Network Provider Partnerships | Expanding LoRaWAN coverage facilitates real-time data collection from remote agricultural operations across vast areas. |
| Target Emerging Agricultural Economies | Entering markets like Southeast Asia addresses unmet demand for water-saving technologies and sustainable farming. |
| Enhance Software Capabilities | Shifting from hardware sales to subscription-based data analytics services reconfigures the profit landscape. |
| Invest in Multi-parameter Sensor R&D | Developing devices for moisture, temperature, and EC provides a holistic view of soil health for high-value crops. |
Research Approach
Cross-validation between primary interviews with industry experts and secondary market reports anchors the qualitative findings. This involved discussions with agricultural developers, sensor manufacturers, precision farming consultants, and environmental scientists. Secondary data sources included government agricultural statistics, academic research on soil science, technology company press releases, and patent databases. The approach utilized both bottom-up and top-down triangulation to ensure data accuracy.
The forecast framework's calibration relied on historical market data and expert consensus across the analysis window. The quantitative model integrated segmentation dimensions such as sensor type, deployment environment, technology, end-user, and regional agricultural spending patterns. Compound annual growth rates were derived from projected market size evolution and segment-specific growth rates. Key industry-specific forecast inputs included water conservation policy adoption rates and the expansion of IoT infrastructure.
The forecast holds incumbent behavior within observed patterns; aggressive moves by disruptive technology startups or large agricultural conglomerates would shift outcomes. Forecasts reflect assumptions regarding stable regulatory environments and consistent technological advancement. Unforeseen regulatory changes or rapid shifts in agricultural commodity prices represent specific risk factors. Cross-checking against government agricultural agency reports or academic hydrological models is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Agriculture Drone Software Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Global Precision Farming Software and Services Market
Precision Agriculture
United States Precision Farming Software Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Crop Monitoring Market