
 Global Digital Agriculture Platform Market | 2026-2036
Global Digital Agriculture Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Agriculture Platform Market Foresight
Large-scale agribusiness firms are reorganizing procurement priorities around integrated farm management platforms, pulling ahead of smaller cooperatives in technology spend. Deere & Company anchors its position through captive supply of precision hardware bundled with subscription analytics. Trimble Agriculture competes on channel control, embedding its guidance systems into OEM dealer networks across North America and Europe. Farmers Edge differentiates through backward integration into proprietary soil sensing hardware, reducing third-party data licensing costs.
A digital agriculture platform is a cloud-connected software system that ingests field-level data from IoT sensors, satellite imagery, and equipment telematics to generate prescriptive recommendations for planting, irrigation, fertilization, and harvest scheduling. These platforms typically process georeferenced data layers at sub-meter resolution, applying machine learning models to correlate microclimatic conditions with crop performance outcomes. Farm management software occupies the deepest margin pools due to recurring SaaS revenue and high switching costs, while artificial intelligence capabilities represent the fastest-expanding technology segment as vendors race to automate agronomic decision-making. Crop monitoring systems sustain mature growth trajectories in developed markets where satellite coverage is dense and cellular infrastructure is reliable.
The EPA governs pesticide application data reporting in the United States, creating structured data obligations that platform vendors must accommodate to maintain farmer compliance. The EU Green Deal and its Farm to Fork Strategy mandate digital traceability for agricultural inputs, directly stimulating demand for supply chain modules within European deployments. Brazil's national agricultural regulator enforces deforestation monitoring requirements that remote sensing platforms increasingly satisfy. Stakeholders must weigh interoperability investments against the risk of proprietary data lock-in as platform consolidation accelerates.
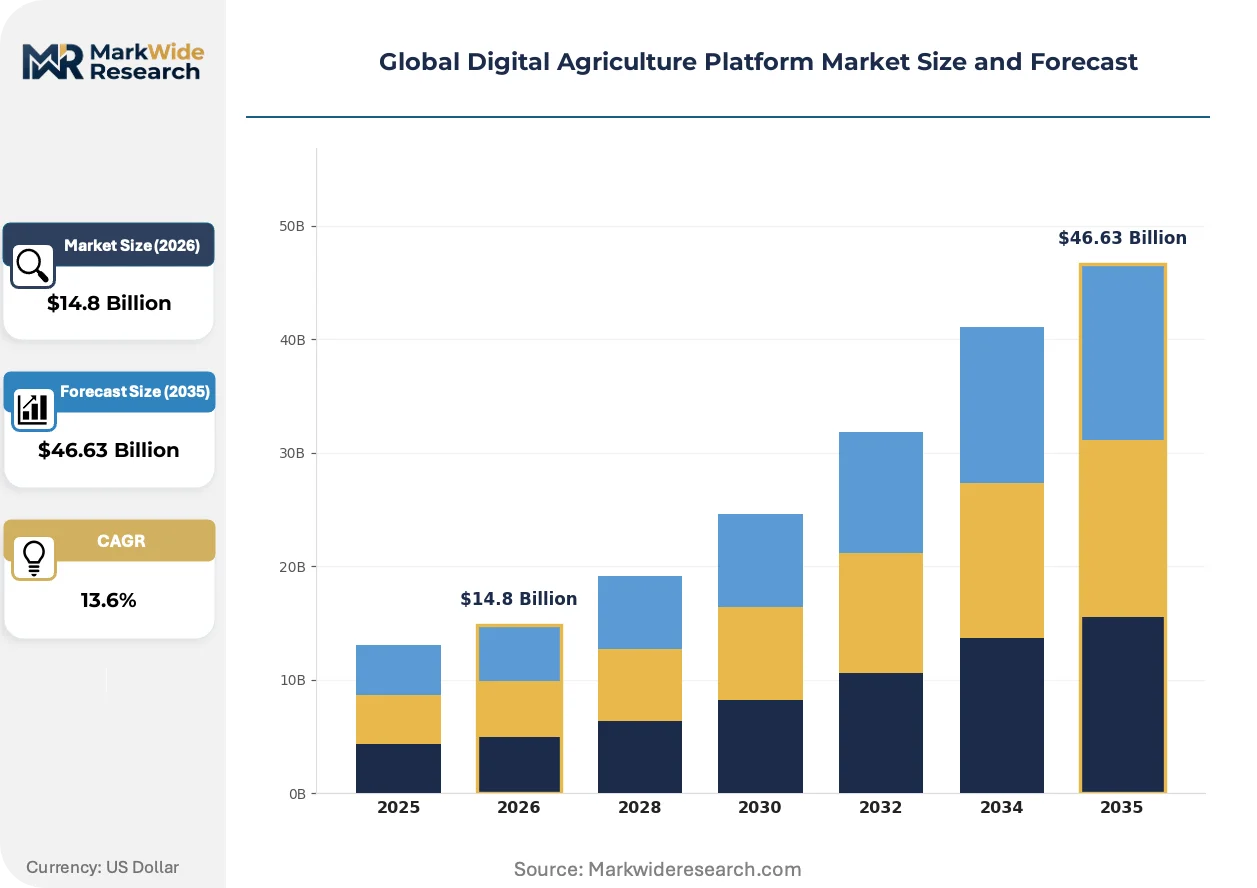
Market Dynamics
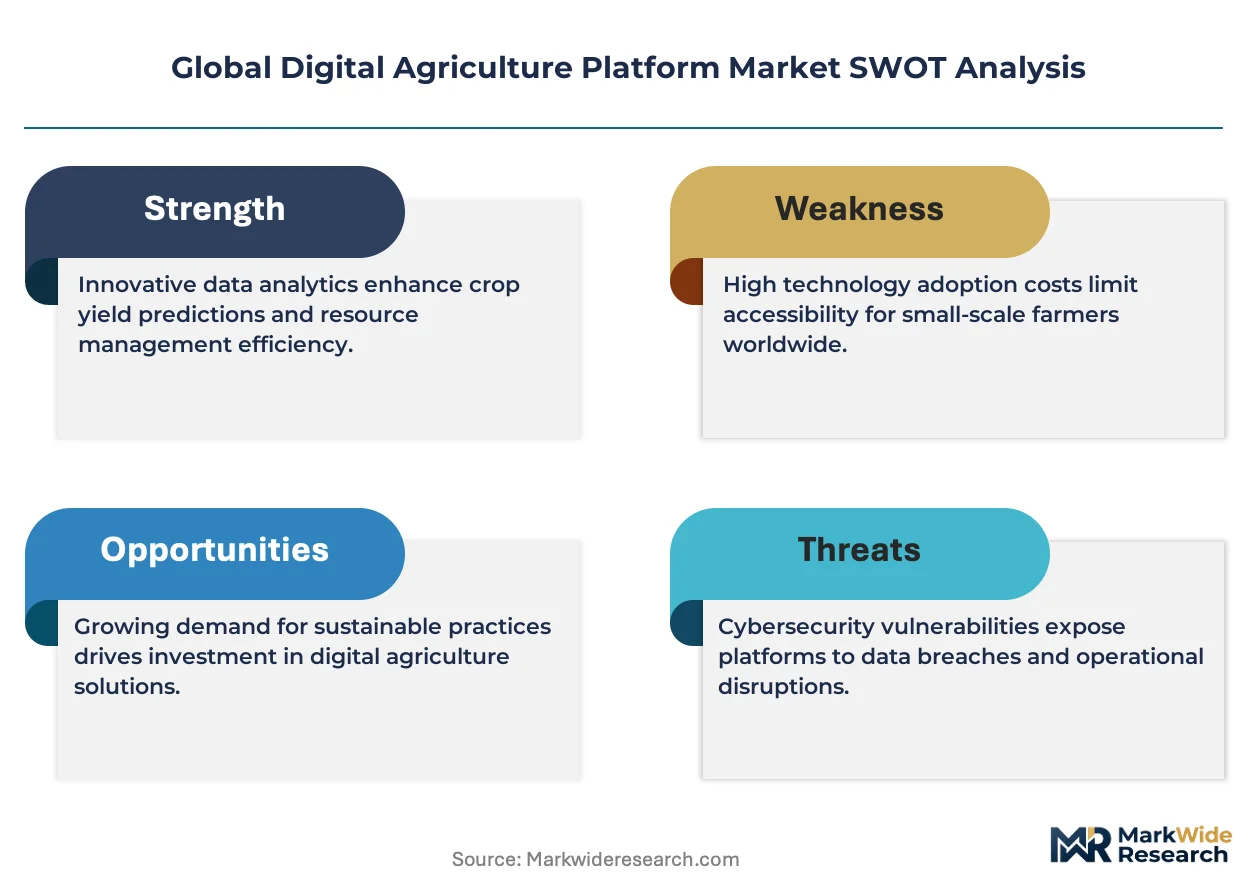
Large-scale agribusiness firms are consolidating procurement around integrated farm management platforms, creating procurement gravity that pulls smaller cooperatives into follower positions and compressing vendor negotiation leverage.
Growth Catalysts
- EU Green Deal traceability mandates:Digital input tracking requirements under the Farm to Fork Strategy force European operators to deploy supply chain modules, creating immediate platform demand.
- IoT sensor density in Brazilian soybean regions:Field-level telemetry networks expand coverage, generating raw data volumes that require cloud-based processing infrastructure.
- Carbon accounting protocols:National frameworks in Brazil and India mandate emissions reporting for agricultural operations, driving compliance module adoption.
Market Restraints
- Cellular infrastructure gaps:Remote wheat-growing regions in India lack reliable connectivity, degrading real-time platform performance and limiting addressable acreage.
- Proprietary data lock-in:Vendor-specific formats create switching costs that freeze farmers in suboptimal contracts and suppress competitive pressure on pricing.
- Hardware bundling requirements:Precision equipment OEMs tie analytics subscriptions to captive hardware purchases, inflating total cost of ownership for price-sensitive segments.
Strategic Opportunities
- Smallholder digitization in India:Federated data cooperatives could aggregate fragmented landholdings into viable platform subscriptions, unlocking a historically underserved segment.
- AI-driven agronomic automation:Machine learning models that automate irrigation scheduling and pest intervention recommendations represent unclaimed white space in decision-support functionality.
- Carbon credit verification services:Platforms that integrate MRV (measurement, reporting, verification) capabilities for agricultural carbon offsets capture new revenue pools from compliance markets.
Industry Challenges
- Agronomic data science talent scarcity:The intersection of crop science and machine learning expertise remains thinly staffed, constraining model development velocity at platform vendors.
- Interoperability standardization delays:Competing data format initiatives from equipment manufacturers and software providers prolong integration timelines for multi-vendor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Agriculture Platform Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Farm Management Software, Crop Monitoring Systems, Precision Farming Tools, Livestock Management Software, Weather Forecasting Platforms Technology: IoT Sensors, Remote Sensing, Artificial Intelligence, Blockchain, Data Analytics Application: Yield Optimization, Soil Health Monitoring, Pest & Disease Prediction, Resource Management, Supply Chain Traceability End User: Smallholder Farmers, Agribusiness Firms, Government Agencies, Research Institutions, Agricultural Cooperatives |
| Companies Covered | Farmers Edge, Topcon Positioning Systems, Deere & Company, Plantix, Raven Industries, Trimble Agriculture, Climate LLC (Bayer), Agteq, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Agriculture Platform Market Shifts & Advancements
Platform architecture is pivoting from data aggregation toward automated decision execution, with vendors racing to close the loop between sensing and actuation in field operations.
Edge computing hardware is miniaturizing. Field-deployable processing units now execute inference directly on combine harvesters and irrigation pivots, reducing latency for time-sensitive interventions. North American grain belt operators are deploying these units at scale during 2024 planting cycles. This distributed architecture is miniaturizing the data transmission burden on rural cellular networks and enabling autonomous equipment coordination without cloud dependency.
EPA pesticide application reporting rules are tightening data granularity requirements. The agency now mandates georeferenced spray records with timestamp verification, forcing platform vendors to rebuild compliance modules around audit-ready data structures. Specialty crop operators in California and Florida face the steepest adaptation costs, with several regional cooperatives consolidating onto shared platform instances to distribute compliance overhead.
Subscription unbundling is fragmenting traditional SaaS packaging. Buyers increasingly reject comprehensive platform bundles, instead purchasing crop monitoring, equipment telematics, and financial management as separate micro-services. Dealer networks in the US Corn Belt report rising attach rates for standalone analytics modules sold alongside precision hardware. This a-la-carte preference is most pronounced among mid-scale operators managing diversified crop portfolios who resist single-vendor dependency.
Global Digital Agriculture Platform Market Segmentation
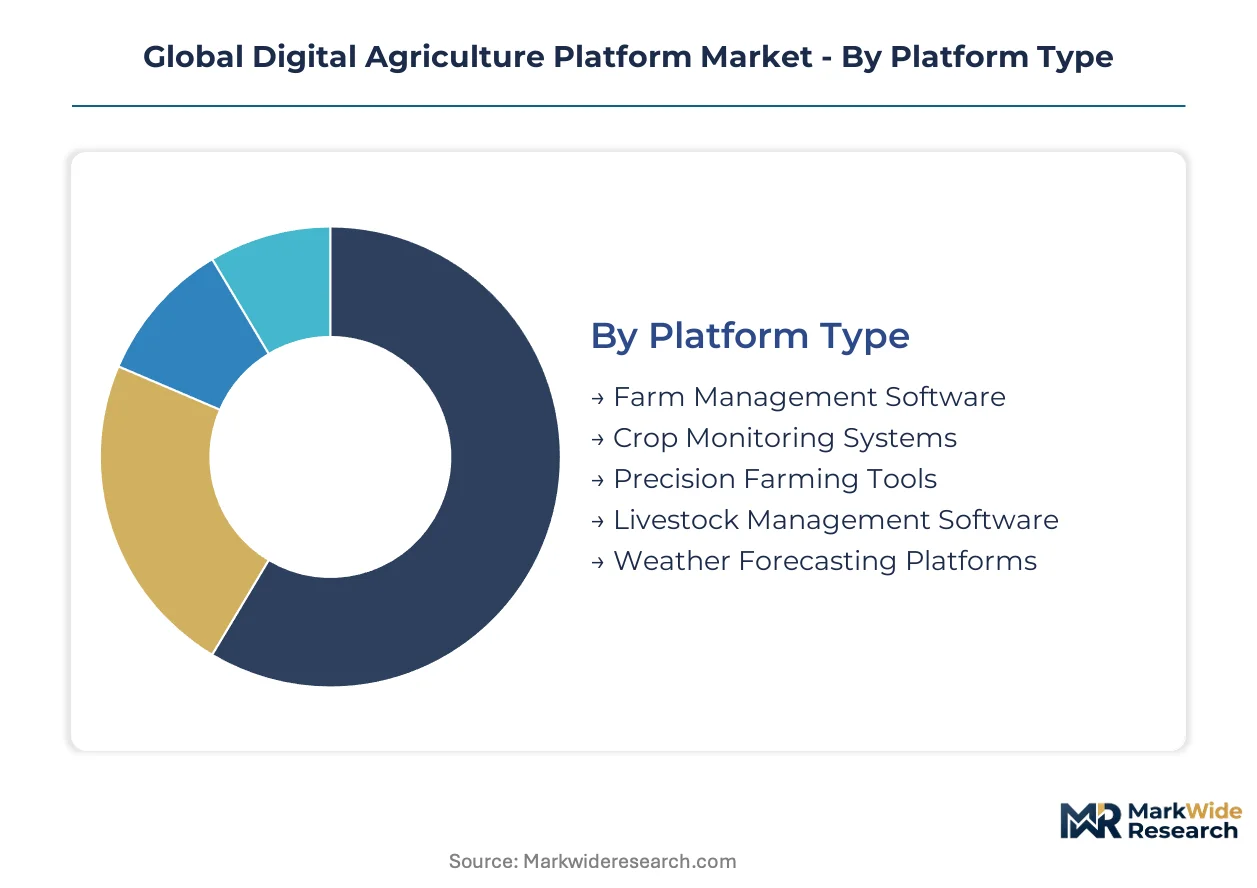
Platform segmentation reveals divergent deployment economics across farm scales and compliance environments. Technology choices cluster around data infrastructure maturity, while application modules map directly to regulatory mandates in major producing countries.
Platform Type:
Farm Management Software dominates procurement budgets in North American grain operations, while Crop Monitoring Systems spread fastest across Brazilian soybean regions with expanding satellite coverage.
- Farm Management Software:Cloud-based ERP systems integrate financial planning, equipment scheduling, and compliance reporting through unified dashboards. Large-scale operators in Iowa, Illinois, and Kansas consolidate procurement around these platforms to satisfy EPA pesticide documentation requirements and streamline audit trails.
- Crop Monitoring Systems:Satellite and drone-based imagery platforms process multispectral data to detect early-stage crop stress, nutrient deficiencies, and irrigation gaps. Brazilian Mato Grosso and Goiás states drive adoption as operators meet national deforestation monitoring mandates through remote sensing verification.
- Precision Farming Tools:Variable-rate application systems for seed, fertilizer, and chemicals tied to GPS guidance hardware.
- Livestock Management Software:Herd health tracking, breeding optimization, and feed rationing systems concentrated in US Great Plains cattle operations.
- Weather Forecasting Platforms:Hyperlocal microclimate prediction services with highest penetration in Australian wheat belts and Indian monsoon-dependent regions.
Farm Management Software commands the established base. The steepest expansion runs through Crop Monitoring Systems.
Technology:
Technology selection tracks connectivity infrastructure density, with IoT Sensors requiring reliable cellular networks that fragment deployment patterns across rural geographies.
- IoT Sensors:Soil moisture probes, weather stations, and equipment telematics nodes generate continuous field-level data streams. Dense networks in German precision farming clusters and California Central Valley specialty crop operations validate investment through irrigation water savings and labor reduction.
- Artificial Intelligence:Machine learning models automate agronomic recommendations for planting density, pest intervention timing, and harvest scheduling. Indian wheat-growing states and Chinese corn belts attract vendor investment as platforms race to close the sensing-to-actuation loop.
- Remote Sensing:Satellite and aerial imagery acquisition with standardized processing pipelines.
- Blockchain:Distributed ledger systems for supply chain traceability, concentrated in EU compliance deployments.
- Data Analytics:Descriptive and predictive analytics engines processing aggregated farm data.
IoT Sensors anchor current infrastructure investment. Artificial Intelligence claims the most aggressive vendor R&D allocation.
Application:
Application modules align with input cost pressures and export market access requirements, creating divergent priority rankings across commodity types.
- Yield Optimization:Prescriptive analytics maximizing output per hectare through input timing and rate optimization. Ukrainian corn and sunflower producers deploy these modules to recover productivity lost to conflict-disrupted supply chains and fertilizer access constraints.
- Supply Chain Traceability:Digital input tracking and chain-of-custody documentation for export compliance. Mandatory under EU Green Deal Farm to Fork Strategy, these modules dominate new platform deployments in France, Netherlands, and Spain as operators secure access to premium European retail channels.
- Soil Health Monitoring:Carbon content, microbiome analysis, and erosion tracking for regenerative agriculture transitions.
- Pest & Disease Prediction:Early warning systems for crop protection timing, prevalent in humid subtropical growing regions.
- Resource Management:Water, energy, and labor optimization tools with strongest adoption in water-stressed growing regions.
Yield Optimization retains the largest installed base. Supply Chain Traceability is climbing fastest as regulatory deadlines approach.
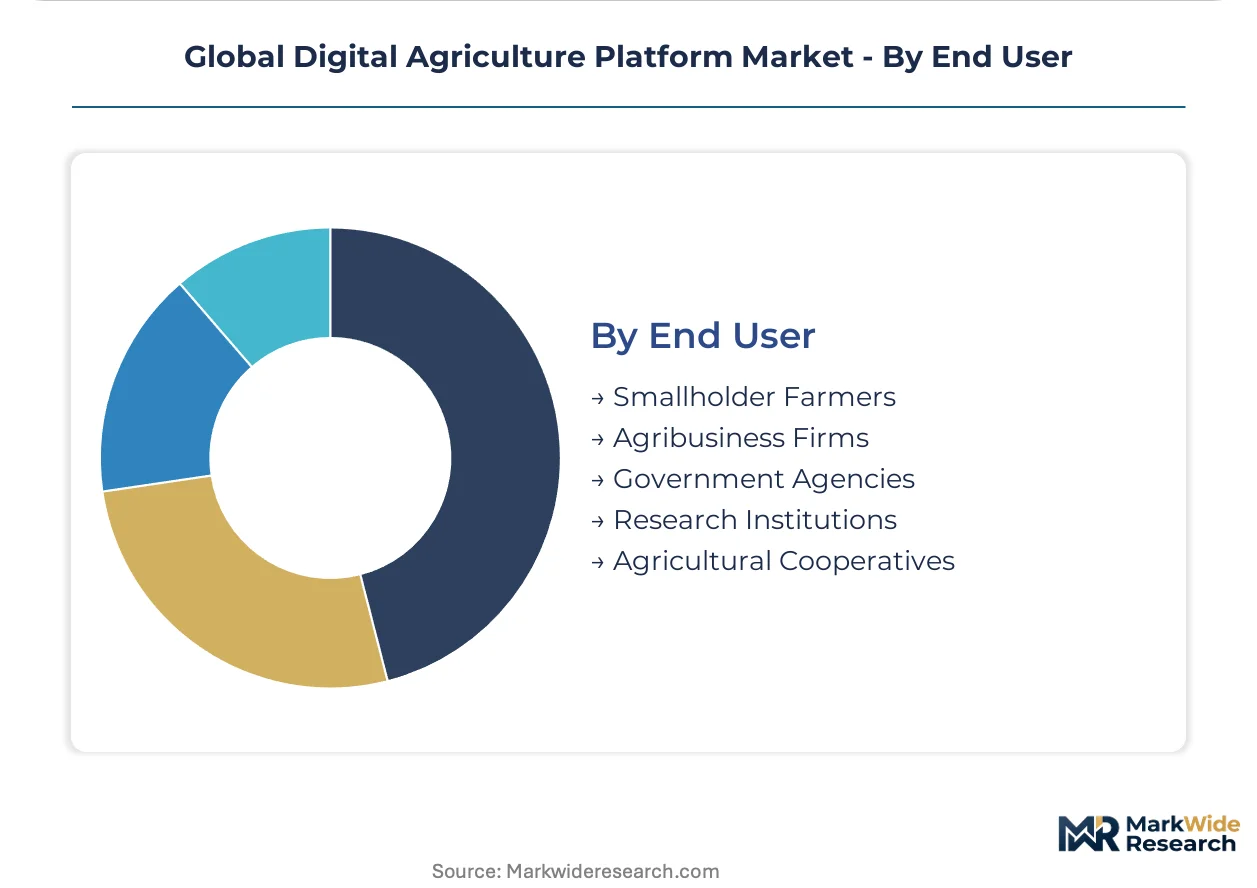
End User:
End user segmentation reflects farm scale economics, with procurement concentration creating technology access gaps that vendors are only beginning to address through cooperative aggregation models.
- Agribusiness Firms:Integrated operators controlling thousands of hectares deploy enterprise platform licenses with customized compliance modules. These firms in Brazil, Argentina, and the US Midwest drive vendor roadmaps through direct specification requirements and volume commitments.
- Smallholder Farmers:Subsistence and semi-commercial operators managing under five hectares, historically underserved due to per-acre economics. Federated data cooperatives in Maharashtra and Punjab states are piloting shared platform subscriptions that aggregate fragmented demand into viable vendor contracts.
- Government Agencies:National agricultural ministries deploying platforms for subsidy verification and production forecasting.
- Research Institutions:Universities and extension services using platforms for variety testing and agronomic model validation.
- Agricultural Cooperatives:Member-owned organizations consolidating procurement and data sharing for medium-scale operators.
Agribusiness Firms dominate current revenue. Smallholder Farmers represent the largest untapped addressable expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean exports to European Union buyers drive compliance-driven platform deployment, as EU Green Deal traceability requirements cascade backward through supply chains into origin-country data infrastructure.
United States
EPA pesticide reporting mandates force grain belt operators into georeferenced spray documentation systems. Iowa and Illinois corn-soy rotations anchor enterprise platform procurement, with Deere & Company bundling precision hardware through captive dealer networks. Kansas wheat operations consolidate compliance modules to satisfy audit-ready data structures.
Brazil
National deforestation monitoring requirements from ANVISA and environmental regulators push Mato Grosso and Goiás soybean producers toward satellite-verified platform subscriptions. Carbon accounting protocols for agricultural emissions create additional module demand. Large-scale agribusiness firms in the Cerrado biome drive vendor specification requirements through direct volume commitments.
India
FSSAI and DGFT traceability initiatives intersect with state-level agricultural digitization programs in Maharashtra and Punjab. Federated data cooperatives pilot shared platform subscriptions to aggregate fragmented smallholder demand. Telangana's precision agriculture clusters demonstrate IoT sensor density viability for irrigation optimization at sub-acre resolution.
Germany
EU Green Deal Farm to Fork Strategy mandates digital input tracking for export market access, with Bavaria and Lower Saxony livestock-crop integrated operations deploying supply chain modules. ECHA chemical registration requirements extend into agricultural input documentation. Baden-Württemberg precision farming clusters validate investment through irrigation water savings.
China
Dual carbon goals and MEE emissions frameworks push Hebei and Shandong wheat-corn operations toward carbon accounting platform modules. NMPA and agricultural ministry digitization subsidies reduce adoption friction for cooperative aggregation models. Yangtze River Delta greenhouse clusters deploy edge computing hardware for autonomous climate control.
Global Digital Agriculture Platform Market Competitive Landscape
Player mix skews toward precision equipment OEMs with captive software ecosystems, creating tiered competition between hardware-anchored platforms and independent analytics vendors. Strategic archetypes include bundled hardware-software systems, channel-embedded guidance providers, and backward-integrated sensor specialists. Consolidation pressure intensifies through M&A activity targeting data science capabilities and geographic expansion into compliance-driven markets.
Within the equipment-anchored tier, Deere & Company and AGCO Corporation represent integrated platform strategies tying analytics subscriptions to precision machinery procurement. Trimble Agriculture exemplifies channel-embedded positioning through OEM dealer network partnerships. Farmers Edge occupies the sensor-integrated specialist position with proprietary soil sensing hardware reducing third-party data licensing exposure.
| Leading Market Players |
|---|
| Farmers Edge |
| Topcon Positioning Systems |
| Deere & Company |
| Plantix |
| Raven Industries |
| Trimble Agriculture |
| Climate LLC (Bayer) |
| Agteq |
| AGCO Corporation |
| Others |
Supply & Pricing Matrix
Edge computing hardware substitution for cloud-dependent processing is redrawing supply geography toward semiconductor fabrication centers in Taiwan and South Korea while compressing pricing premiums for latency-sensitive platform tiers.
Pricing Analysis
Next-generation AI-driven agronomic modules command subscription premiums over legacy crop monitoring dashboards, while prior-generation telematics-only packages face margin compression. Three-tier pricing structure across premium, standard, and economy levels stratifies by data resolution and automation depth. Pricing pressure stems from unbundling preferences among mid-scale diversified operators who reject comprehensive vendor lock-in. Smallholder federated cooperatives exhibit highest price sensitivity; large-scale agribusiness firms with compliance mandates show lowest.
Supply Chain Analysis
Rural cellular infrastructure gaps in Indian wheat-growing states and Brazilian Cerrado fringe zones create connectivity chokepoints that degrade real-time platform performance. Hardware componentry draws from Taiwan for edge processing units, China for sensor assemblies, and Germany for precision guidance systems. GPS chipset and lithium-ion power cell dependencies expose vendors to single-source vulnerability from East Asian semiconductor foundries. Distribution runs through OEM dealer networks in North America and Europe, direct-to-farm sales teams in Brazil and Argentina, and cooperative aggregators in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a regulatory-inflection disruption as EU Green Deal traceability mandates and Brazil-India carbon accounting protocols simultaneously force compliance module deployment and create first-mover data advantages.
For Market Incumbents: Fortify platform stickiness through captive soil sensing hardware integration that reduces third-party data licensing exposure. Deepen backward integration into proprietary IoT sensor production to defend against modular unbundling threats from standalone analytics vendors. Prioritize certification investment for EPA audit-ready data structures and EU Farm to Fork Strategy compliance modules.
For New Entrants and Emerging Players: Differentiate on AI-driven agronomic automation that closes the sensing-to-actuation loop in irrigation scheduling and pest intervention timing. Target smallholder digitization in Maharashtra and Punjab federated cooperatives as the most penetrable white space. Pursue carbon credit verification services as a go-to-market wedge, integrating MRV capabilities for agricultural offset markets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors sensor-integrated specialists with proprietary data infrastructure over pure-software analytics vendors. Long-term viability across the analysis window hinges on platforms that anchor recurring revenue through high-switching-cost compliance modules. Watch for interoperability standardization breakthroughs as the signal indicating which data format investments will capture network effects.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Sensors | Cuts third-party data licensing costs and deepens platform moats for vendors like Farmers Edge. |
| AI-Driven Agronomic Automation | Captures unclaimed white space in irrigation and pest intervention decision-support functionality. |
| Carbon Credit Verification Services | Unlocks new revenue pools from Brazil and India compliance-driven agricultural offset markets. |
| Federated Cooperative Aggregation Models | Addresses smallholder economics in Indian wheat-growing states through shared subscription structures. |
| Edge Computing Hardware Miniaturization | Reduces rural cellular dependency and enables autonomous equipment coordination in North American grain belts. |
Research Methodology
Operator-level perspectives from farm management software executives, precision agriculture hardware procurement leads, agronomic data scientists, cooperative aggregation managers, and regulatory compliance officers anchored the qualitative base. Secondary validation drew from EPA pesticide application filings, EU Farm to Fork Strategy implementation documents, ANVISA deforestation monitoring requirements, and equipment OEM SEC disclosures. Bottom-up acreage deployment estimates triangulated against top-down platform vendor revenue segmentation.
Sensitivity analysis tested forecast outputs against variable cellular infrastructure rollout timelines and carbon accounting protocol adoption curves across the projection horizon. Segmentation dimensions modeled include platform type, technology layer, application module, and farm scale tier. CAGRs derived from historical adoption velocity in comparable regulatory compliance cycles, adjusted for IoT sensor density thresholds and AI model training data availability.
Forecasts assume regulatory continuity in EPA pesticide reporting, EU Green Deal traceability mandates, and Brazil-India carbon accounting frameworks; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as interoperability standardization negotiations and smallholder cooperative pilot results evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Americas Precision Farming Software Market