
 Digital Agriculture Market | 2026-2036
Digital Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Agriculture Market Analysis
Aftermarket service revenue from telemetry-enabled equipment is reconfiguring margin pools away from hardware sales toward recurring data subscriptions. Deere & Company leverages its Operations Center platform to anchor recurring revenue streams across installed tractor fleets. Trimble Inc. competes through specialized GNSS correction services that dominate high-accuracy planting and spraying workflows. AGCO Corporation extends its Fuse platform to control connectivity across mixed-brand machinery environments.
Digital agriculture integrates sensor networks, geospatial systems, and machine-learning algorithms into farm management workflows, typically operating at sub-inch GPS accuracy for automated steering and variable-rate application. Its primary commercial purpose is optimizing input efficiency and yield outcomes through real-time field intelligence. Precision farming commands the largest installed base among product categories, while artificial intelligence within the technology dimension represents the fastest-expanding margin pool as inference models shift from cloud to edge deployment. Smart irrigation sustains above-average growth in water-stressed growing regions where regulatory metering mandates intensify.
The EPA oversees pesticide application data requirements that shape drone-based spraying system certifications in the United States, while the EU Green Deal's Farm to Fork strategy imposes digital traceability obligations across European supply chains. Brazil's national agricultural regulator enforces deforestation monitoring protocols that drive satellite-based compliance tooling demand. Stakeholders must evaluate whether platform consolidation or interoperability standards will determine supplier bargaining power as data ownership frameworks crystallize across jurisdictions.
Market Dynamics
The shift from hardware-centric equipment sales toward recurring data subscriptions is restructuring revenue pools across farm machinery ecosystems, with telemetry-enabled service contracts now capturing margin that previously accrued to capital equipment transactions.
Growth Catalysts
- Variable-Rate Input Systems:Large-scale row-crop operations in Brazil's Mato Grosso soybean belt are deploying fleet-scale precision agriculture platforms to optimize fertilizer and seed application at sub-acre resolution.
- EU Green Deal Compliance:The Farm to Fork strategy mandates digital traceability across European supply chains, compelling farms to adopt sensor networks and geospatial logging systems for chemical-use reporting.
- Smart Irrigation Mandates:Water-stressed growing regions facing regulatory metering requirements are accelerating adoption of soil-moisture monitoring and automated valve control systems.
Market Restraints
- GNSS Correction Cost Volatility:Subscription pricing for centimeter-accuracy positioning services creates ongoing operational expense burdens for mid-scale operators.
- Platform Fragmentation:Proprietary data architectures from major equipment manufacturers limit interoperability across mixed-brand machinery fleets.
- Edge Hardware Limitations:On-device inference capabilities for machine-learning models remain constrained by thermal management and power consumption in field conditions.
Strategic Opportunities
- Interoperability Standards:Industry-wide data protocols could unlock value from previously siloed field intelligence across competing platform ecosystems.
- Carbon Credit Verification:Satellite-based compliance tooling for deforestation monitoring creates adjacent revenue streams from environmental attribute certification.
- Drone Spraying Certification:EPA regulatory pathways for unmanned aerial application systems open new equipment categories for precision chemical deployment.
Industry Challenges
- Data Science Talent Scarcity:Agronomic interpretation of sensor-derived field maps requires hybrid skill sets combining crop science with geospatial analytics.
- Legacy System Integration:Retrofitting connectivity modules onto decade-old tractor fleets demands custom mechanical and electrical engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Agriculture Market |
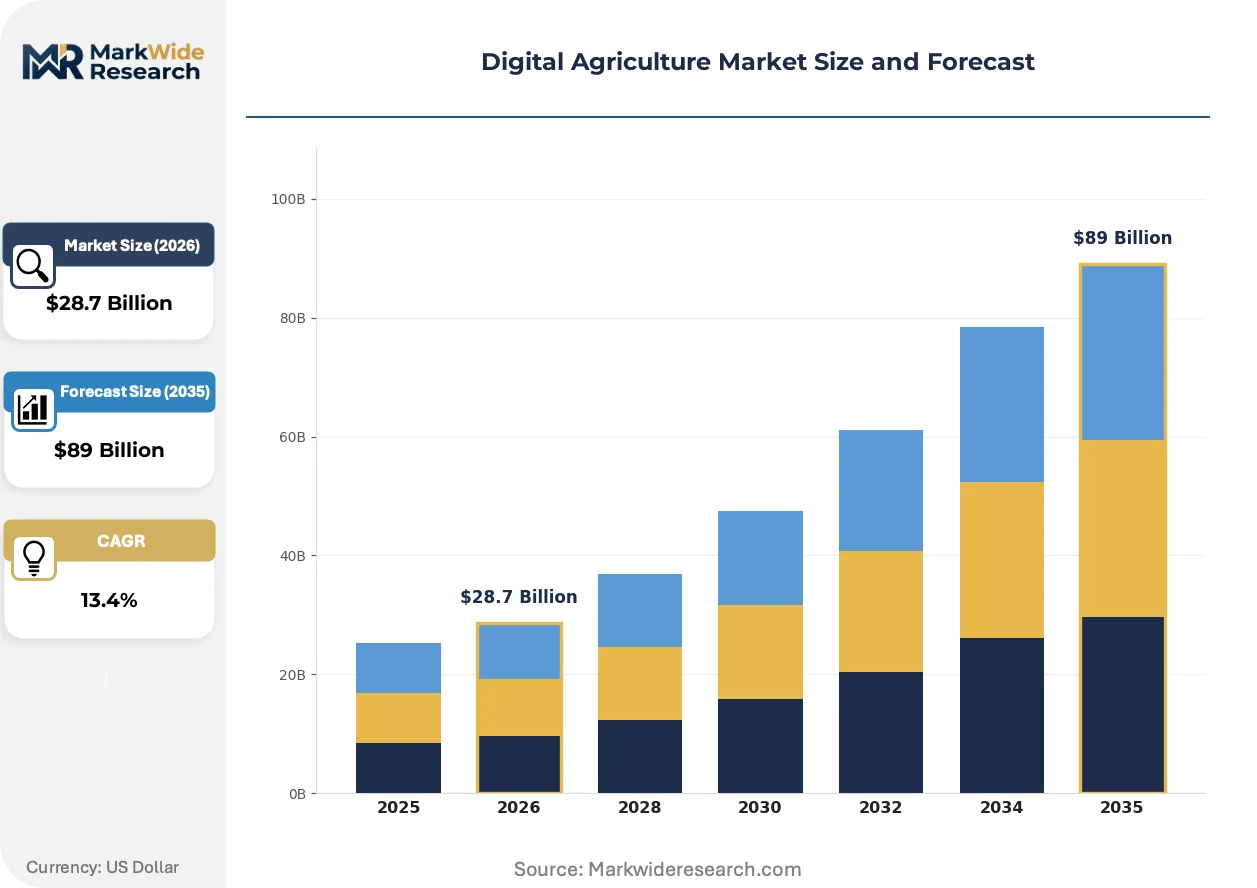
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $89 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precision Farming, Smart Irrigation, Crop Monitoring, Livestock Management Technology: IoT Devices, Drones, Artificial Intelligence, Data Analytics End User: Farmers, Agricultural Cooperatives, Research Institutions, AgriTech Firms Application: Crop Management, Soil Health Monitoring, Yield Prediction, Pest Control |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Bayer AG, Corteva Agriscience, Syngenta Group, CNH Industrial N.V., IBM Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Agriculture Market Emerging Trajectories
Edge-deployed artificial intelligence is compressing decision latency in field operations, enabling real-time agronomic interventions without cloud connectivity dependency. Three developments are actively restructuring competitive positioning.
Computer vision systems mounted on self-propelled sprayers are digitizing weed identification workflows, distinguishing crop from pest plants at speeds exceeding human scouting capacity. Row-crop operators in the US Corn Belt are retrofitting these systems at accelerating rates. The technology is digitizing herbicide application from broadcast coverage toward targeted spot-spraying, reducing chemical volume requirements.
EPA pesticide application data requirements are reshaping certification pathways for autonomous spraying equipment, mandating granular record-keeping for every chemical deposit. Drone manufacturers must now demonstrate sub-meter deposition accuracy and drift mitigation to secure operational waivers. Specialty crop producers in California's Central Valley face the steepest compliance burden, driving consolidation toward integrated service providers.
Aftermarket telemetry subscriptions are displacing upfront hardware margins across dealer networks, with annual recurring revenue contracts now constituting the dominant profitability driver. Equipment distributors are restructuring sales compensation toward service attach rates rather than unit volumes. This transformation is most visible in the US Midwest, where multi-year data platform commitments increasingly determine brand loyalty at fleet replacement cycles.
Digital Agriculture Market Segmentation
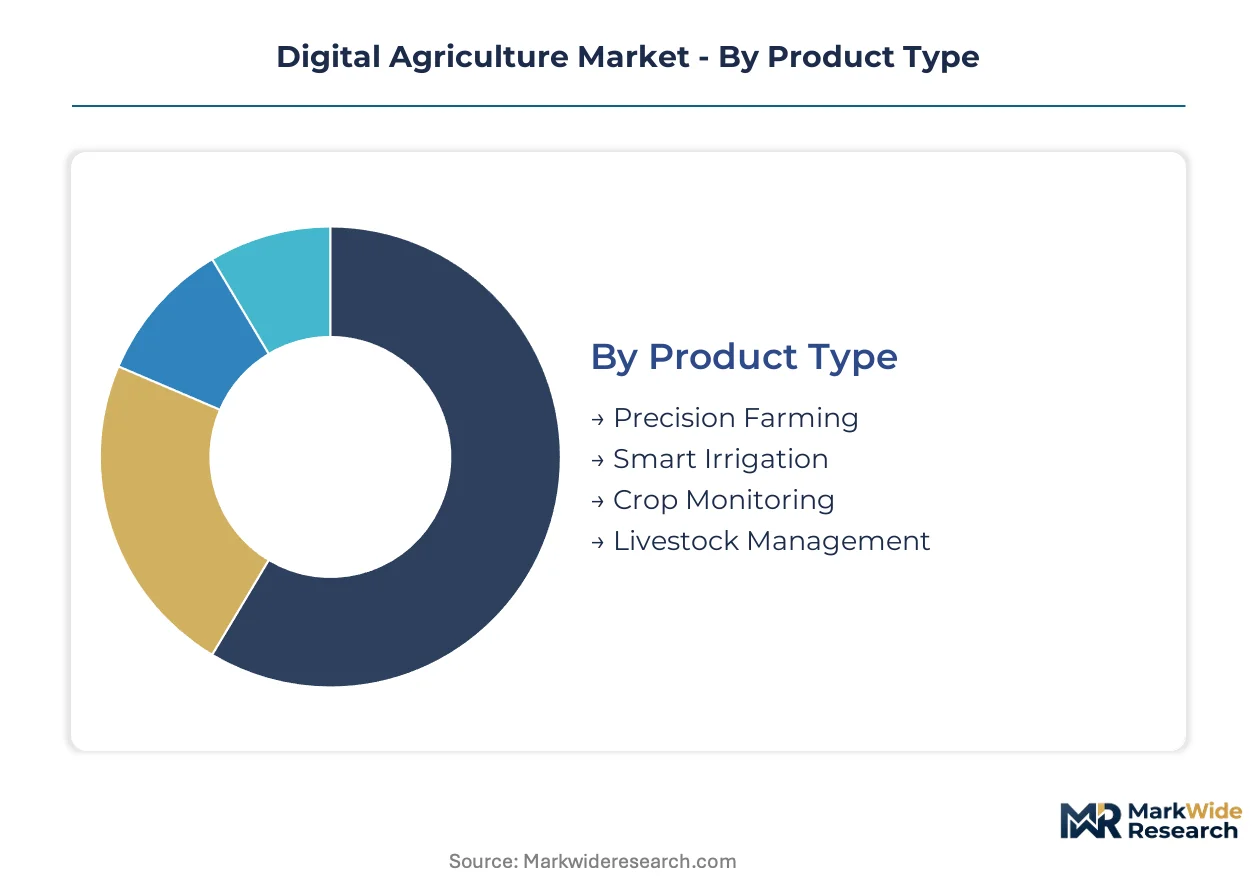
Digital agriculture segments reflect divergent technology maturity and deployment economics. Product categories span hardware-heavy field equipment to software-centric analytics platforms. Understanding segment boundaries clarifies where capital investment concentrates versus where subscription models dominate revenue capture.
Product Type:
Mature precision hardware anchors the category while emerging software layers reshape margin structures.
- Precision Farming:Variable-rate input systems integrate GPS-guided tractors, automated steering, and real-time application control at sub-inch accuracy. Brazil's Mato Grosso soybean belt deploys fleet-scale precision platforms to optimize fertilizer placement across thousand-hectare operations. The installed base here exceeds other categories combined, though hardware margins compress as telemetry subscriptions displace upfront equipment sales.
- Smart Irrigation:Soil-moisture sensor networks and automated valve control systems reduce water consumption in drought-stressed growing regions. California's Central Valley and Australia's Murray-Darling Basin face regulatory metering mandates that accelerate adoption of connected irrigation infrastructure. Thermal management challenges constrain edge-deployed controllers in extreme field conditions.
- Crop Monitoring:Satellite and drone-based imagery platforms deliver vegetation index mapping and growth stage tracking.
- Livestock Management:RFID tagging, automated feeding systems, and health monitoring sensors track animal welfare metrics.
Precision Farming handles the majority of throughput; Smart Irrigation is the fastest mover on share.
Technology:
Cost tiering separates capital-intensive hardware deployments from lightweight software implementations.
- IoT Devices:Field-deployed sensor networks measure soil moisture, nutrient levels, and microclimate conditions through ruggedized hardware designed for agricultural environments. These devices form the physical data layer that feeds upstream analytics platforms. Battery life and connectivity reliability in remote locations constrain deployment density.
- Drones:Unmanned aerial systems capture multispectral imagery and execute targeted spraying operations with sub-meter deposition accuracy. EPA certification requirements for pesticide application reshape competitive barriers, favoring integrated service providers over equipment-only vendors. Drift mitigation protocols and flight autonomy standards determine operational waivers.
- Artificial Intelligence:Machine-learning models shift from cloud to edge deployment, compressing decision latency for real-time agronomic interventions.
- Data Analytics:Cloud-based platforms aggregate field intelligence into actionable prescriptions for input optimization and yield forecasting.
IoT Devices absorb the largest capital allocation; Artificial Intelligence is climbing the fastest on commercial traction.
End User:
Customer type determines purchasing authority and platform stickiness across the value chain.
- Farmers:Individual operators and family enterprises represent the volume base, with adoption concentrated among large-scale row-crop specialists who can amortize technology costs across extensive acreage. Their procurement decisions increasingly hinge on multi-year data platform commitments rather than equipment brand loyalty. Dealer network restructuring toward service attach rates targets this segment specifically.
- Agricultural Cooperatives:Member-owned aggregates deploy shared precision infrastructure across pooled acreage, achieving scale economies unavailable to individual operators. Brazil's cooperative structures in Rio Grande do Sul and Paraná coordinate fleet-scale technology adoption for soybean and corn production. Shared data governance frameworks complicate platform selection.
- Research Institutions:Universities and government agricultural extensions validate emerging technologies through controlled field trials.
- AgriTech Firms:Technology developers and platform integrators purchase components for resale or incorporation into bundled service offerings.
Farmers account for the dominant transaction volume; Agricultural Cooperatives are gaining share fastest through pooled procurement leverage.
Application:
Application focus tracks where measurable ROI crystallizes most rapidly for technology adopters.
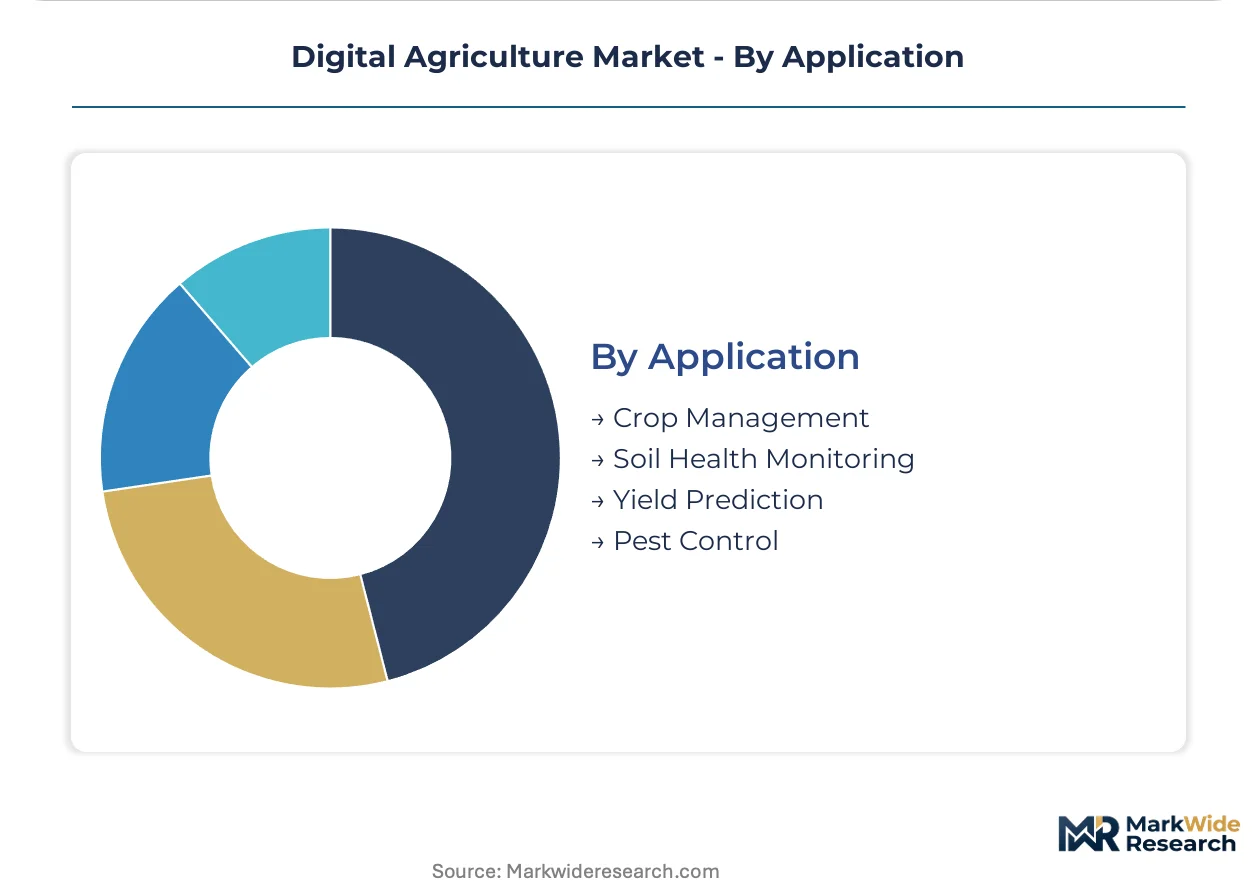
- Crop Management:Integrated platforms coordinate planting, fertilization, and harvest operations through unified field intelligence dashboards. Variable-rate seeding and targeted nutrient application deliver quantifiable yield improvements and input cost reductions. The EU Green Deal's Farm to Fork strategy mandates digital traceability for chemical-use reporting, embedding compliance functionality into core crop management workflows.
- Soil Health Monitoring:Sensor networks and laboratory analytics track organic matter, compaction, and microbial activity to guide regenerative practices. Carbon credit verification protocols create adjacent revenue streams from soil carbon sequestration documentation. Satellite-based compliance tooling for deforestation monitoring extends soil health platforms into environmental attribute certification.
- Yield Prediction:Machine-learning models combine historical performance, weather patterns, and real-time crop condition data to forecast harvest outcomes.
- Pest Control:Computer vision systems on self-propelled sprayers distinguish crop from weed species, enabling spot-spraying that reduces chemical volume requirements.
Crop Management commands the largest deployment footprint; Soil Health Monitoring is expanding most quickly on regulatory and carbon market tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-scale operators in Eastern Europe exhibit the sharpest price sensitivity to GNSS correction subscriptions, while large-scale row-crop specialists in Brazil's Mato Grosso absorb premium positioning costs without volume elasticity.
United States
The US Corn Belt drives fleet-scale precision deployment through variable-rate input systems across thousand-hectare operations. EPA pesticide application data requirements mandate granular record-keeping for every chemical deposit, reshaping certification pathways for autonomous spraying equipment. Iowa and Illinois field clusters concentrate retrofit activity for computer vision systems on self-propelled sprayers.
Brazil
Brazil's Mato Grosso soybean belt anchors fleet-scale precision agriculture adoption for fertilizer and seed optimization at sub-acre resolution. The national agricultural regulator enforces deforestation monitoring protocols that drive satellite-based compliance tooling demand. Cooperative structures in Rio Grande do Sul and Paraná coordinate shared precision infrastructure across pooled acreage.
Germany
German precision farming concentrates in Bavaria and Lower Saxony where large-scale arable operations amortize technology costs across extensive acreage. The EU Green Deal's Farm to Fork strategy imposes digital traceability obligations across European supply chains, compelling sensor network adoption for chemical-use reporting. Claas and Fendt manufacturing clusters in Baden-Württemberg anchor equipment innovation pipelines.
China
China's Yangtze River Delta and Northeast grain belt deploy precision agriculture platforms for rice and corn production optimization. MIIT standards for agricultural IoT devices shape domestic equipment certification requirements, favoring local manufacturers. Shandong Province field trials validate edge-deployed AI for real-time agronomic interventions without cloud dependency.
Australia
Australia's Murray-Darling Basin accelerates smart irrigation adoption under regulatory metering mandates for water-stressed growing regions. The country's national agricultural regulator enforces sustainability reporting that drives soil-moisture sensor network deployment. New South Wales and Victoria field clusters concentrate automated valve control system installations for cotton and wheat operations.
Digital Agriculture Market Vendor Landscape
Capability concentration sits with integrated platform operators; scale advantage sits with diversified machinery manufacturers. The vendor base organizes around three strategic archetypes: telemetry-enabled service platform operators, precision hardware specialists, and cloud-native analytics providers. Consolidation pressure intensifies as recurring revenue contracts displace upfront equipment margins. Dominant competitive moves include strategic partnerships for interoperability standards and backward integration into sensor hardware production.
Within the integrated platform tier, Deere & Company and Trimble Inc. exemplify contrasting positioning strategies. Deere & Company anchors recurring revenue streams through its Operations Center platform across installed tractor fleets. Trimble Inc. competes through specialized GNSS correction services that dominate high-accuracy planting and spraying workflows. AGCO Corporation occupies a position bridging both approaches through its Fuse platform controlling connectivity across mixed-brand machinery environments.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Bayer AG |
| Corteva Agriscience |
| Syngenta Group |
| CNH Industrial N.V. |
| IBM Corporation |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on Chinese-manufactured sensor hardware determines both pricing tier spreads and supply chain shape across precision agriculture markets. Component duties compress margins on economy-tier equipment while accelerating procurement diversification toward Southeast Asian assembly alternatives.
Pricing Analysis
Long-term telemetry subscription contracts dominate revenue capture, displacing spot equipment purchases as the primary commercial structure. Pricing stratifies across premium, standard, and economy tiers based on GNSS correction accuracy grades and after-sales service bundling. Cost compression in economy-tier hardware is intensifying because Chinese manufacturers flood channels with undifferentiated IoT devices. Mid-scale operators in Eastern Europe exhibit the sharpest price sensitivity, while Brazilian mega-fleets absorb premium positioning costs without volume elasticity.
Supply Chain Analysis
Upstream semiconductor feedstock concentrates in Taiwan, South Korea, and the United States for edge-computing chips and GNSS receiver modules. Ruggedized sensor housings and lithium battery cells draw from Chinese manufacturing clusters. Single-source vulnerability sits with Taiwanese foundry capacity for specialized agricultural processors. Distribution runs through OEM dealer networks and direct-to-farm platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-deployed artificial intelligence is disrupting competitive positioning through sub-second agronomic decision latency, while the EU Green Deal's Farm to Fork strategy mandates digital traceability infrastructure investment.
For Market Incumbents: Insulate recurring revenue streams by deepening backward integration into sensor hardware production and securing exclusive dealer service attach rates. Platform fragmentation from proprietary data architectures threatens customer lock-in. Certification investment in EPA drone spraying pathways preserves regulatory moats against cloud-native entrants. For New Entrants and Emerging Players: Mid-scale cooperative structures in Brazil's Rio Grande do Sul and Paraná represent the most penetrable entry point for shared precision infrastructure deployment. Australia's Murray-Darling Basin water-stressed regions offer secondary white-space for smart irrigation compliance tooling. Go-to-market through agricultural cooperative procurement consortia bypasses entrenched OEM dealer relationships. For Investors and Strategic Acquirers: The EPA's evolving pesticide application data requirements reshape the acquisition landscape toward integrated service providers with regulatory compliance capabilities. Long-term viability centers on platform operators capturing telemetry subscription economics across mixed-brand fleets. Vertically integrated specialists with captive GNSS correction networks warrant priority attention. Monitor EPA waiver issuance velocity for drone spraying certification as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Interoperability Standards | AGCO's Fuse platform demonstrates connectivity control across mixed-brand machinery environments. |
| Backward Integration into Sensor Hardware | Captive supply of ruggedized IoT devices reduces tariff exposure and secures margin capture. |
| Carbon Credit Verification Services | Satellite-based compliance tooling for deforestation monitoring creates adjacent revenue streams in Brazil. |
| EPA Drone Spraying Certification | Regulatory pathways for unmanned aerial application systems reshape competitive barriers in California's Central Valley. |
| Edge AI Deployment | Machine-learning models shifting from cloud to edge compress decision latency for real-time field interventions. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with precision agriculture technology directors, cooperative procurement managers, and EPA regulatory compliance officers; and secondary validation through SEC equipment manufacturer filings, USDA agricultural census data, EU Farm to Fork strategy documentation, and Brazilian deforestation monitoring satellite records. Bottom-up equipment deployment estimates triangulated against top-down addressable acreage calculations.
Forecast inputs considered precision farming hardware shipments, telemetry subscription attach rates, and regulatory compliance tooling demand across product type, technology, end user, and application dimensions over the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporating edge AI commercialization timelines and carbon market participation elasticity. Water metering mandate enforcement intensity and GNSS correction service pricing volatility served as industry-specific forecast inputs.
Practitioners should monitor EPA waiver issuance patterns, EU Green Deal implementation velocity, and Brazilian deforestation enforcement actions for early signals of forecast revision. Cross-checking against USDA precision agriculture adoption surveys and ANVISA compliance database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Agriculture IoT Sensor Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Autonomous Crop Management Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Automated Pest Monitoring System Market