
 Agriculture Analytics Market | 2026-2036
Agriculture Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Analytics Market Intelligence
The capability gap between cloud-native analytics platforms and legacy farm management software is redrawing competitive boundaries in agriculture technology. Deere & Company leverages its installed base of precision equipment to embed predictive analytics directly into machinery workflows. SAP SE anchors enterprise agriculture deployments through ERP-integrated supply chain optimization modules. IBM Corporation differentiates via Watson-powered machine learning models trained on satellite imagery and hyperlocal weather data.
Agriculture analytics encompasses the collection, processing, and statistical modeling of agronomic, environmental, and operational data to optimize farm-level decision-making and downstream supply chain performance. These systems typically ingest remote sensing imagery at sub-meter resolution, soil sensor telemetry, and historical yield records to generate prescriptive recommendations for input application, irrigation scheduling, and harvest timing. Predictive analytics and crop monitoring solutions currently capture the largest share of solution spending, while drone surveillance and IoT sensors represent the fastest-expanding technology layer as hardware costs decline and edge computing architectures mature. Yield forecasting applications command premium pricing due to their direct linkage to commodity trading and crop insurance underwriting.
The EPA oversees water quality monitoring requirements that mandate nutrient runoff tracking, while the USDA administers conservation programs incentivizing precision agriculture adoption through the Environmental Quality Incentives Program. The EU Green Deal's Farm to Fork Strategy imposes mandatory sustainability disclosure standards that require granular farm-level data collection and verification. Stakeholders must evaluate whether to build proprietary data lakes or subscribe to multi-tenant platforms as regulatory compliance obligations intensify and data interoperability standards crystallize across jurisdictions.
Market Dynamics
The Agriculture Analytics Market is undergoing structural transformation as the USDA's Environmental Quality Incentives Program subsidizes sensor deployment while the EU Green Deal's Farm to Fork Strategy mandates granular sustainability disclosure. This dual regulatory pressure is forcing agribusinesses to choose between proprietary data architectures and multi-tenant platforms.
Growth Catalysts
- Precision irrigation telemetry:Sub-meter soil moisture sensors enable real-time water application optimization, reducing input waste while satisfying EPA nutrient runoff tracking requirements.
- Federal conservation incentives:The USDA EQIP program covers up to 75% of precision agriculture equipment costs for qualifying conservation practices, accelerating farm-level adoption.
- Commodity trading integration:Yield forecasting platforms command premium subscriptions from crop insurance underwriters and grain elevators seeking harvest timing intelligence.
Market Restraints
- Silicon supply concentration:Edge computing chip fabrication concentrates in Taiwan and South Korea, exposing IoT sensor manufacturers to geopolitical supply disruptions.
- Interoperability fragmentation:Absence of unified data standards between John Deere Operations Center, Climate FieldView, and FarmLogs forces costly API integration workarounds.
- Rural broadband deficits:USDA Rural Development data shows 22% of American farmland lacks adequate connectivity for cloud-native analytics platform operation.
Strategic Opportunities
- Carbon credit verification:The EU Green Deal's CSRD disclosure standards create demand for farm-level emissions monitoring systems that quantify sequestration for voluntary carbon markets.
- Drone-as-a-service models:Agricultural cooperatives in Brazil and Argentina are outsourcing aerial imagery collection to third-party operators rather than capitalizing owned equipment.
- Machine learning convergence:Fusion of satellite hyperspectral imagery with on-ground sensor telemetry enables predictive pest pressure modeling previously impossible with single-data-source approaches.
Industry Challenges
- Agronomic data science talent scarcity:Universities produce insufficient graduates combining crop science expertise with statistical modeling capabilities, forcing employers to train hybrid roles internally.
- Legacy ERP integration complexity:SAP and Oracle agriculture modules require 12-18 month implementation cycles to synchronize with modern API-first analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Analytics Market |
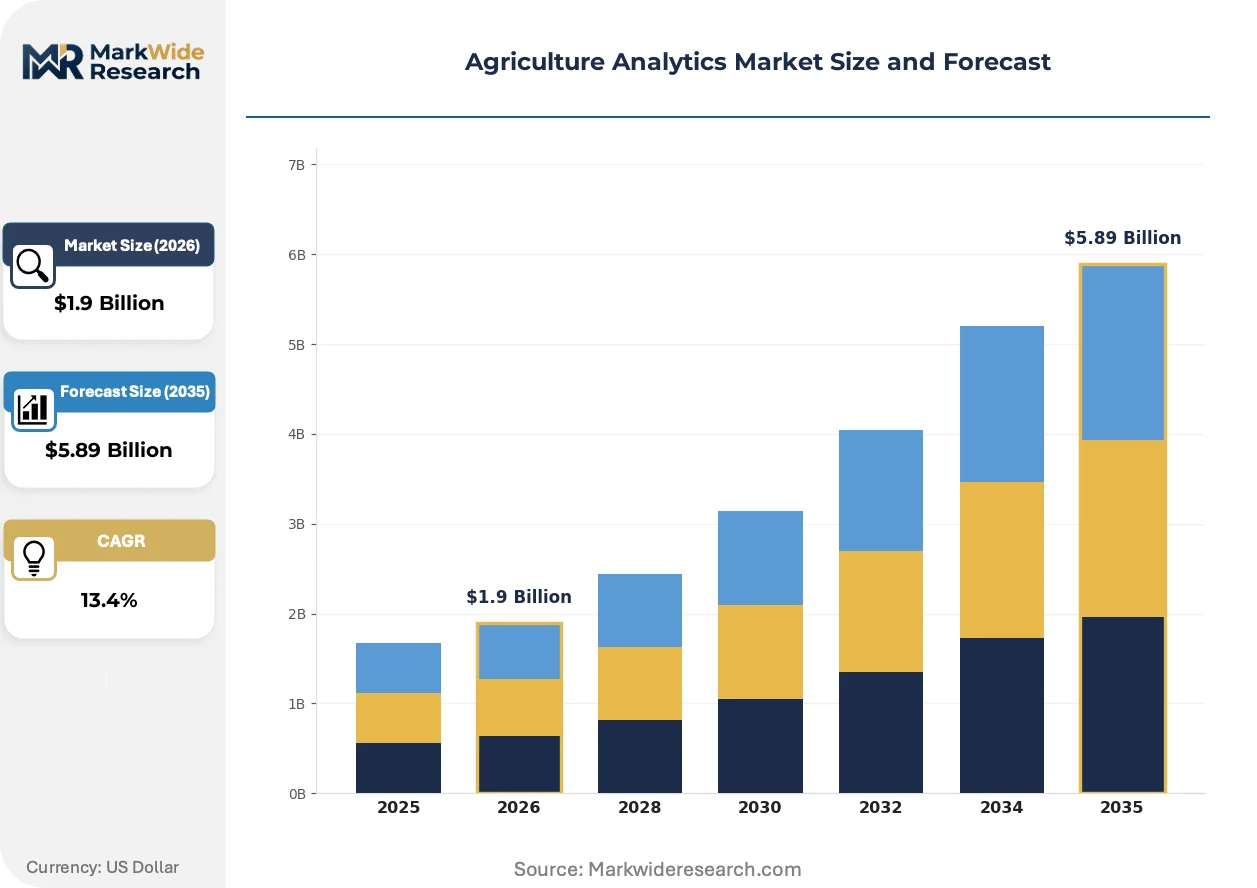
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Crop Monitoring, Soil Analysis, Yield Forecasting, Pest Detection Technology: Remote Sensing, GIS Mapping, Drone Surveillance, IoT Sensors, Machine Learning Application: Precision Farming, Livestock Management, Supply Chain Optimization, Weather Forecasting End User: Farmers, Agribusiness Firms, Cooperatives, Research Institutes |
| Companies Covered | Deere & Company, SAP SE, IBM Corporation, Oracle Corporation, Trimble Inc., Accenture PLC, Bayer AG, Monsanto Company, Iteris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Analytics Market Strategic Shifts & Innovations
Edge computing architectures are redrawing the boundary between field-level processing and cloud analytics, enabling real-time decision loops that were previously bandwidth-constrained. This infrastructure shift is compressing the latency between sensor detection and automated machinery response.
Hyperspectral imaging drones are displacing multispectral satellite subscriptions as the primary vegetation health monitoring tool for high-value specialty crop operations. California almond and Washington apple growers are adopting weekly drone flight schedules during critical growth windows. This displacement is compressing the addressable market for legacy satellite imagery providers while expanding hardware and analytics software bundling opportunities.
The EU Green Deal's Farm to Fork Strategy imposes mandatory sustainability disclosure standards requiring granular farm-level data collection and third-party verification. Agribusinesses must now maintain auditable data chains from input application through harvest. Specialty crop exporters to European markets are investing most heavily in compliance infrastructure, with organic certification bodies expanding their service portfolios to include digital traceability verification.
Buyers are consolidating vendor relationships around integrated platform ecosystems rather than maintaining point solutions for each analytics function. Large grain elevators and input distributors are demanding single-dashboard visibility across their supplier networks. This consolidation pressure is most visible in the US Corn Belt, where cooperative purchasing agreements favor vendors offering combined yield forecasting, input optimization, and sustainability reporting modules.
Agriculture Analytics Market Segmentation
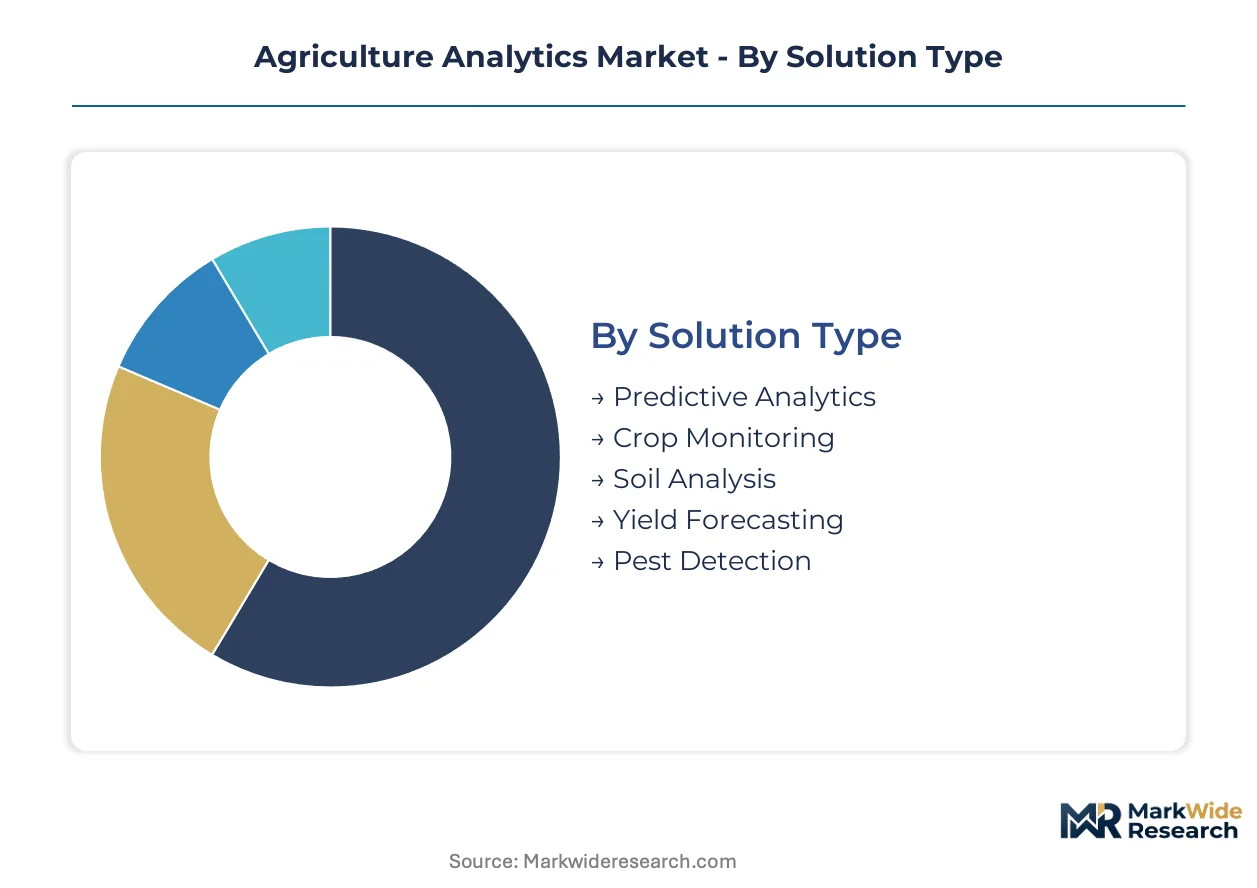
Agriculture analytics vendors configure product portfolios around distinct operational workflows and data maturity levels. Segmentation reveals where pricing power concentrates and which technology layers face commoditization pressure.
Solution Type:
EU Green Deal disclosure mandates and EPA water quality tracking create divergent compliance burdens that shape solution demand across regulatory jurisdictions.
- Predictive Analytics:Machine learning models process historical yield records, weather patterns, and input application logs to generate forward-looking recommendations for planting density and harvest timing. Grain elevators and crop insurance underwriters in the United States subscribe at premium rates for harvest timing intelligence that informs commodity positioning decisions.
- Crop Monitoring:Satellite imagery and ground-truthed sensor networks track vegetation health indices, water stress markers, and nutrient deficiency signatures throughout growing seasons. Specialty crop operations in California and Washington deploy weekly monitoring protocols during critical growth windows to optimize input timing.
- Soil Analysis:Laboratory and in-field spectroscopy measure macronutrient availability, pH gradients, and organic matter content to guide variable-rate input application.
- Yield Forecasting:Integration of remote sensing data with agronomic models generates pre-harvest production estimates for supply chain planning and risk transfer instruments.
- Pest Detection:Computer vision systems identify insect pressure and disease progression through leaf-level imagery analysis, triggering targeted intervention protocols.
Yield forecasting handles the majority of throughput; pest detection is gaining share fastest as climate volatility expands pathogen ranges.
Technology:
Hardware cost curves and edge computing maturation are redrawing the boundary between capital-intensive field deployment and subscription-based analytics services.
- Remote Sensing:Satellite constellations deliver sub-meter multispectral imagery at daily revisit frequencies, with hyperspectral capabilities expanding vegetation health detection precision. Legacy providers face displacement pressure as drone-based alternatives capture high-value specialty crop monitoring contracts.
- GIS Mapping:Spatial data infrastructure layers soil survey boundaries, drainage patterns, and elevation models to enable precision agriculture zone delineation. USDA Natural Resources Conservation Service datasets provide foundational layers for US farm management platform configuration.
- Drone Surveillance:Unmanned aerial vehicles equipped with multispectral and thermal sensors deliver on-demand imagery at spatial resolutions below 5 centimeters. Brazilian and Argentine agricultural cooperatives are adopting drone-as-a-service models rather than capitalizing owned equipment fleets.
- IoT Sensors:Sub-meter soil moisture probes, weather stations, and equipment telematics generate continuous field-level data streams.
- Machine Learning:Fusion algorithms integrate satellite imagery, sensor telemetry, and historical records to generate prescriptive recommendations previously impossible with single-data-source approaches.
Remote sensing dominates current installed capacity; drone surveillance is expanding most quickly as hardware costs decline and flight automation improves.
Application:
Enterprise resource planning integration requirements and farm-scale operational complexity determine where analytics spending concentrates.
- Precision Farming:Variable-rate technology for seeding, fertilization, and irrigation application optimizes input efficiency while satisfying regulatory documentation requirements. USDA Environmental Quality Incentives Program subsidies cover up to 75% of equipment costs for qualifying conservation practices.
- Livestock Management:Sensor networks monitor animal health indicators, feeding behavior patterns, and environmental conditions in confined and pasture-based operations.
- Supply Chain Optimization:ERP-integrated modules synchronize harvest timing, grain elevator capacity, and transportation logistics across multi-farm supplier networks.
- Weather Forecasting:Hyperlocal meteorological models combine regional climate data with on-farm sensor readings to generate field-specific predictions for frost protection and irrigation scheduling.
Precision farming accounts for the largest deployment base; supply chain optimization is climbing fastest as grain elevators consolidate supplier network visibility requirements.
End User:
Data infrastructure investment capacity and technical staffing availability segment the addressable market across organizational types.
- Farmers:Owner-operators with fewer than 500 acres typically subscribe to multi-tenant platforms rather than building proprietary data architectures. Federal conservation program subsidies reduce adoption barriers for precision equipment in the United States.
- Agribusiness Firms:Large integrated operations with dedicated agronomy teams deploy enterprise-grade platforms combining predictive analytics with sustainability reporting modules. EU Green Deal Farm to Fork Strategy disclosure mandates drive compliance infrastructure investment among exporters to European markets.
- Cooperatives:Member-owned purchasing and marketing associations aggregate farm-level data to negotiate input pricing and coordinate harvest logistics.
- Research Institutes:Public and private agricultural research organizations generate foundational datasets and validate algorithm performance across diverse agroecological conditions.
Agribusiness firms command the highest per-seat pricing; cooperatives are expanding fastest as data aggregation models demonstrate procurement leverage value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where federal conservation subsidies accelerate platform adoption, while Brazilian operations face margin pressure from currency volatility and fragmented land tenure patterns.
United States
USDA Environmental Quality Incentives Program subsidies cover up to 75% of precision agriculture equipment costs for qualifying conservation practices. EPA nutrient runoff tracking mandates require granular water quality monitoring across the Corn Belt and Mississippi River watershed. Iowa and Illinois host the densest concentrations of farm management platform deployments, with cooperative purchasing agreements favoring integrated analytics vendors.
Brazil
Agricultural cooperatives in Mato Grosso and Goiás outsource aerial imagery collection to third-party drone operators rather than capitalizing owned equipment fleets. The national agricultural research corporation Embrapa validates algorithm performance across diverse agroecological conditions from Cerrado to Atlantic Forest zones. São Paulo-based grain traders demand harvest timing intelligence from predictive analytics platforms to optimize port logistics and export scheduling.
Germany
EU Green Deal Farm to Fork Strategy disclosure mandates drive compliance infrastructure investment among specialty crop exporters. The Federal Ministry of Food and Agriculture funds digitalization initiatives through the Federal Program for Organic Farming and Other Forms of Sustainable Agriculture. Bavaria's precision livestock operations deploy sensor networks for environmental condition monitoring in confined dairy facilities.
China
Dual carbon goals accelerate demand for farm-level emissions monitoring systems that quantify sequestration for voluntary carbon markets. The Ministry of Agriculture and Rural Affairs promotes smart agriculture demonstration counties in Shandong and Henan provinces. Yangtze River Delta vegetable cooperatives adopt hyperspectral imaging drones for weekly vegetation health monitoring during critical growth windows.
India
PLI scheme incentives for electronic manufacturing reduce sensor hardware costs for domestic IoT deployments. The Ministry of Agriculture and Farmers Welfare operates the National e-Governance Plan in Agriculture to digitize land records and extension services. Punjab and Haryana wheat belts concentrate remote sensing imagery subscriptions as groundwater depletion concerns intensify irrigation optimization demand.
Agriculture Analytics Market Key Industry Players
Concentration sits with precision equipment manufacturers who leverage installed machinery bases to embed predictive analytics directly into operational workflows. The vendor landscape stratifies across three archetypes: machinery-integrated platform providers, enterprise software vendors with agriculture-specific modules, and specialized remote sensing analytics firms. M&A activity targets drone surveillance capabilities and machine learning talent pools, while strategic partnerships between satellite operators and ground sensor manufacturers accelerate data fusion algorithm development.
Among machinery-integrated platform providers, Deere & Company and Trimble Inc. occupy positions where equipment telemetry generates proprietary data streams. SAP SE and Oracle Corporation exemplify the enterprise software archetype, anchoring supply chain optimization deployments through ERP-integrated modules. IBM Corporation represents the specialized analytics tier with machine learning models trained on satellite imagery and hyperlocal meteorological data.
| Leading Market Players |
|---|
| Deere & Company |
| SAP SE |
| IBM Corporation |
| Oracle Corporation |
| Trimble Inc. |
| Accenture PLC |
| Bayer AG |
| Monsanto Company |
| Iteris Inc. |
| Others |
Cost & Logistics Intelligence
Long-term subscription contracts with embedded capacity reservations lock in multi-year platform access for agribusiness firms while stabilizing vendor revenue visibility against hardware cost volatility. These arrangements concentrate pricing power with machinery-integrated platform providers who bundle sensor hardware with analytics software under unified term structures.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from configured-to-order enterprise deployments. Subscription models dominate, with pricing differentiation driven by data resolution guarantees and ERP integration depth. Cost compression in the mid-market tier intensifies as multi-tenant platforms compete for cooperative purchasing agreements. Smallholder farmers exhibit highest price sensitivity, while integrated agribusiness firms accept premium positioning for compliance-ready sustainability reporting modules.
Supply Chain Analysis
Inventory lead times for edge computing chips extend to 26-32 weeks, constraining IoT sensor manufacturer output schedules. Semiconductor fabrication concentrates in Taiwan and South Korea, with raw material dependencies spanning silicon wafers, rare earth elements, and precision optics. Single-source vulnerability in advanced node production exposes hardware vendors to geopolitical disruption. Distribution runs through agricultural equipment dealerships and direct enterprise sales teams rather than traditional IT channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions. The EU Green Deal's mandatory disclosure standards and USDA conservation program eligibility requirements create compliance switching costs that resist vendor displacement.
For Market Incumbents: Shield installed base relationships by embedding predictive analytics deeper into machinery control systems, closing API gaps that expose customers to platform migration friction. Deepen backward integration into sensor hardware production to offset Taiwan semiconductor supply risk and capture margin compression from rising chip costs.
For New Entrants and Emerging Players: Lead with carbon credit verification services targeting EU-exporting specialty crop operations in California and Washington, where compliance infrastructure spending runs ahead of platform saturation. Penetrate through drone-as-a-service partnerships with Brazilian agricultural cooperatives, avoiding capital-intensive equipment sales in currency-volatile markets.
For Investors and Strategic Acquirers: Capital is best deployed toward machine learning specialists with validated agronomic models and satellite imagery training datasets, positioned for acquisition by machinery manufacturers seeking analytics differentiation. Watch for inflection in hyperspectral drone adoption rates among high-value crop segments as signal of platform displacement risk for legacy satellite providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP synchronization with SAP and Oracle modules reduces implementation cycles for agribusiness deployments. |
| Acquisition of Specialist Firm | Machine learning talent pools with crop science expertise remain scarce and command strategic premiums. |
| Strategic Partnership | Satellite operator alliances with ground sensor manufacturers accelerate data fusion algorithm development. |
| Product Launch | Carbon credit verification modules address EU Green Deal CSRD disclosure mandates for farm-level emissions tracking. |
| Geographic Expansion | Drone-as-a-service models in Brazil and Argentina bypass capital constraints in fragmented land tenure markets. |
Research Approach
Operator-level perspectives from precision agriculture directors, cooperative purchasing managers, farm management platform engineers, and crop insurance underwriting leads anchored the qualitative base. Primary fieldwork combined with secondary validation against USDA program documentation, EPA water quality monitoring standards, EU Green Deal regulatory texts, and satellite imagery provider technical specifications. Bottom-up deployment estimates triangulated against top-down vendor revenue analysis across the projection horizon.
Sensitivity analysis tested forecast robustness against hardware cost decline trajectories and regulatory implementation delays. Segmentation dimensions modeled include solution type, technology layer, application workflow, and end-user organizational capacity. CAGRs derived from fitted growth curves incorporating federal conservation subsidy uptake rates and sustainability disclosure mandate compliance timelines. Industry-specific inputs encompassed sensor hardware cost curves and edge computing architecture maturation patterns.
Forecasts assume regulatory continuity in USDA conservation programs and EU Green Deal disclosure regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Precision Viticulture Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Precision Farming Software Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Precision Livestock Market