
 Agriculture IoT Sensor Market | 2026-2036
Agriculture IoT Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture IoT Sensor Market Insights
IP68-rated environmental hardening is bifurcating the Agriculture IoT Sensor Market into premium field-deployable tiers and cost-optimized greenhouse alternatives. Deere & Company leverages its dealership network to bundle telemetry subscriptions with original equipment sales. Trimble Inc. competes through GNSS-integrated sensor platforms that anchor precision spraying workflows. Raven Industries specializes in aftermarket retrofit kits that extend legacy machinery into connected fleets without full replacement.
Agriculture IoT sensors comprise electrochemical, capacitive, and spectral sensing elements encased in weatherproof housings, transmitting biophysical data through low-power wide-area protocols to edge gateways or cloud analytics layers. Soil moisture sensors with volumetric water content accuracy of ±2% dominate hardware shipments, though crop health monitors with multispectral imaging arrays capture disproportionate margin pools in high-value specialty crop zones. Wireless Sensor Networks and LoRaWAN together occupy the connectivity architecture for broadacre deployments, while Cellular IoT gains traction in regions with mature 4G infrastructure where farmers prioritize plug-and-play installation over mesh network configuration.
The EPA's Clean Water Act enforcement and the EU Green Deal's Farm to Fork strategy are tightening nutrient runoff accountability, compelling agricultural operators to install verified flow and soil nitrate sensors. Brazil's ANVISA and the USDA's NASS both advance data standardization frameworks that reduce interoperability friction between equipment brands. Stakeholders must monitor whether emerging national data sovereignty laws fragment cloud platform architectures or consolidate around regionally hosted analytics providers.
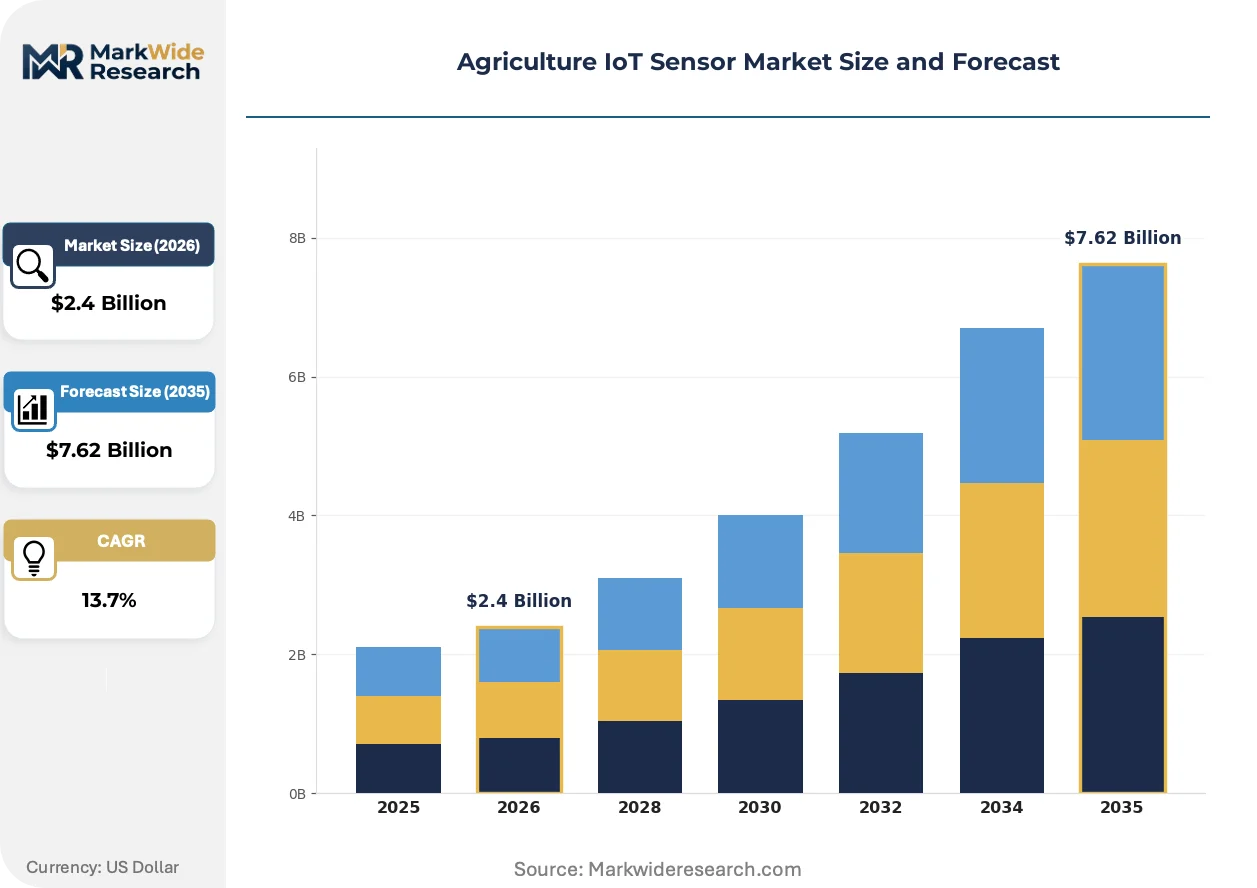
Market Dynamics
The Agriculture IoT Sensor Market is bifurcating around IP68-rated field hardening requirements, as precision spraying workflows and verified runoff monitoring create tiered demand for ruggedized versus cost-optimized sensing hardware. This structural tension between premium durability specifications and greenhouse-scale affordability is reshaping vendor R&D allocation and channel partnerships.
Growth Catalysts
- EU CSRD disclosure mandates:Agricultural enterprises across member states must install verified environmental monitoring systems to meet sustainability reporting requirements, creating pull for certified soil nitrate and flow sensors.
- Mechanized row-crop expansion:Dense sensor network opportunities are materializing in Brazil's Mato Grosso soybean belt where large-scale farming operations prioritize telemetry-integrated equipment bundles.
- LoRaWAN protocol maturation:Low-power wide-area connectivity is reducing mesh network configuration burdens for broadacre deployments, accelerating adoption among technically constrained farm operators.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication bottlenecks in East Asian foundries are extending lead times for spectral imaging arrays and edge processing chipsets.
- Interoperability friction:Fragmented data standardization between Brazil's ANVISA frameworks and USDA NASS protocols forces operators to maintain redundant sensor calibration systems.
- Cellular infrastructure dependency:Regions lacking mature 4G coverage exclude plug-and-play Cellular IoT solutions, limiting addressable market penetration in rural broadband deserts.
Strategic Opportunities
- Aftermarket retrofit penetration:Legacy machinery fleets in North American grain belts present conversion opportunities through telemetry subscription bundles without full equipment replacement.
- Multispectral imaging convergence:Integration of GNSS positioning with crop health monitors is enabling sub-meter precision spraying workflows in high-value specialty crop zones.
- Data sovereignty localization:Emerging national cloud hosting mandates are creating openings for regionally hosted analytics providers to displace centralized platform architectures.
Industry Challenges
- Electrochemical calibration expertise:Volumetric water content accuracy maintenance requires specialized agronomy-technician hybrid roles that remain scarce in rural labor markets.
- Legacy system integration complexity:Retrofitting connected sensor networks into decades-old irrigation infrastructure demands custom gateway configurations that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture IoT Sensor Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soil Moisture Sensors, Weather Sensors, Crop Health Monitors, Livestock Tracking Devices Application: Precision Agriculture, Smart Greenhouses, Livestock Monitoring, Irrigation Management Technology: Wireless Sensor Networks, Zigbee, LoRaWAN, Cellular IoT End User: Farmers, Agronomists, Research Institutions, Agricultural Corporations |
| Companies Covered | AGCO Corporation, Topcon Corporation, Deere & Company, TE Connectivity Ltd., Kubota Corporation, Trimble Inc., Hexagon AB, Raven Industries, CNH Industrial N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture IoT Sensor Market Trends and Innovations
Spectral sensing architectures are actively displacing single-parameter electrochemical probes as the default hardware choice for premium agricultural monitoring deployments. Three interconnected developments are compressing innovation cycles across the value chain.
Multispectral imaging arrays with embedded edge analytics are supplanting standalone soil moisture probes in high-value specialty crop operations. Vineyard and orchard operators in California's Central Valley are deploying these platforms at accelerating rates. The structural consequence is margin compression for single-sensor vendors while integrated platform providers capture disproportionate service revenue pools.
REACH chemical substance restrictions and RoHS hazardous material limits are tightening enclosure material specifications for European-deployed hardware. Manufacturers are reformulating weatherproof housings to eliminate restricted compounds while maintaining IP68 ingress protection ratings. German and Dutch greenhouse operators are absorbing modest cost premiums for compliant certified units to preempt regulatory enforcement actions.
Farm equipment dealerships are unbundling telemetry subscriptions from original equipment sales to capture recurring revenue streams. This channel shift is displacing direct-to-grower sensor procurement in North American row-crop markets. The transformation is most visible across Midwestern US corn-soy operations where bundled service contracts now dominate new sensor deployments.
Agriculture IoT Sensor Market Segmentation
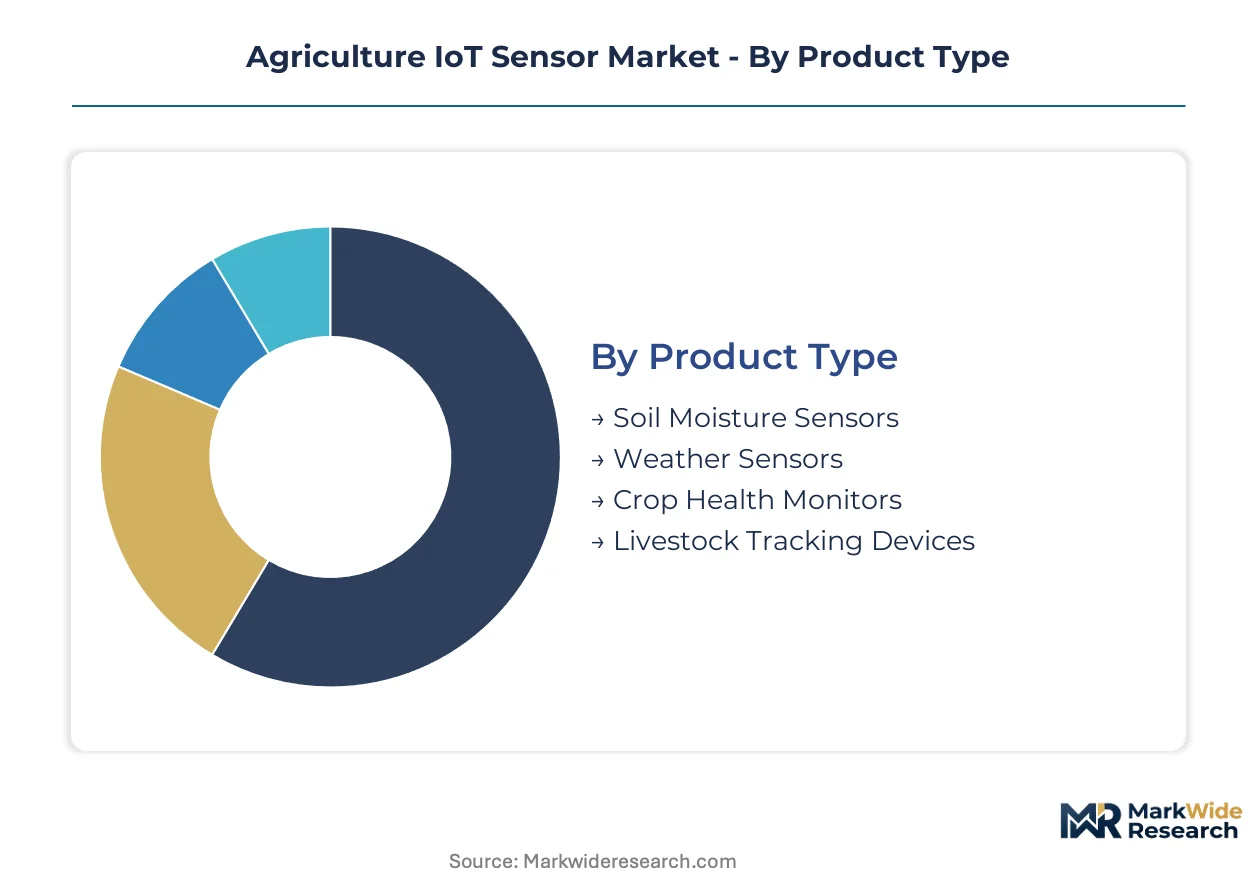
Segmentation reveals how sensor architectures, connectivity protocols, and user capabilities diverge across agricultural operations. Understanding these fault lines exposes where substitution pressures and margin compression concentrate most intensely.
Product Type:
Soil moisture probes face the most acute substitution threat as multispectral imaging platforms absorb their functional scope into integrated crop health systems.
- Soil Moisture Sensors:Electrochemical and capacitive probes measuring volumetric water content with ±2% accuracy dominate hardware shipments across broadacre row-crop operations. Brazilian Mato Grosso soybean belt operators deploy these at scale to optimize irrigation scheduling amid intensifying water stress.
- Weather Sensors:Temperature, humidity, precipitation, and wind speed monitors with IP68-rated enclosures anchor environmental data layers for predictive spraying workflows. European Union CSRD disclosure mandates are pulling certified units into verified sustainability reporting systems.
- Crop Health Monitors:Multispectral imaging arrays with embedded edge analytics capture disproportionate margin pools in California Central Valley vineyards and orchard operations.
- Livestock Tracking Devices:Collar-mounted accelerometers and GPS beacons monitor animal welfare metrics and location in extensive grazing systems.
Soil moisture sensors anchor the volume base while crop health monitors gain share at the steepest rate.
Application:
Cost tier stratification separates premium precision agriculture deployments from standardized greenhouse automation where sensor density per hectare drops by an order of magnitude.
- Precision Agriculture:GNSS-integrated sensor networks enable sub-meter variable-rate application across large-scale mechanized farms. EPA Clean Water Act enforcement and EU Green Deal nutrient runoff accountability are compelling verified flow and soil nitrate sensor installations.
- Smart Greenhouses:Climate-controlled environments favor cost-optimized sensing hardware without IP68 field hardening. Dutch and German operators absorb modest REACH and RoHS compliance premiums to preempt regulatory enforcement.
- Livestock Monitoring:Accelerometer and GPS collar systems track animal welfare metrics in extensive grazing operations across Australia and Brazil.
- Irrigation Management:Soil moisture and flow sensors integrate with automated valve control systems to reduce water consumption in water-stressed agricultural zones.
Precision agriculture commands the premium tier while smart greenhouses deliver volume through standardized deployments.
Technology:
Supply concentration in semiconductor fabrication creates differential lead time exposure across connectivity architectures.
- Wireless Sensor Networks:Mesh topology protocols with self-healing node redundancy suit technically sophisticated farm operators capable of gateway configuration management.
- Zigbee:Short-range, low-power personal area networking fills greenhouse and controlled-environment applications where node density exceeds LoRaWAN range economics.
- LoRaWAN:Low-power wide-area protocol maturation is reducing configuration burdens for broadacre deployments across technically constrained farm operator segments.
- Cellular IoT:Plug-and-play installation simplicity gains traction in regions with mature 4G infrastructure where farmers prioritize immediate deployment over mesh network optimization.
LoRaWAN and Wireless Sensor Networks split the broadacre base while Cellular IoT climbs fastest where infrastructure permits.
End User:
Capability scarcity concentrates among hybrid agronomy-technician roles, segmenting addressable markets by technical sophistication thresholds.
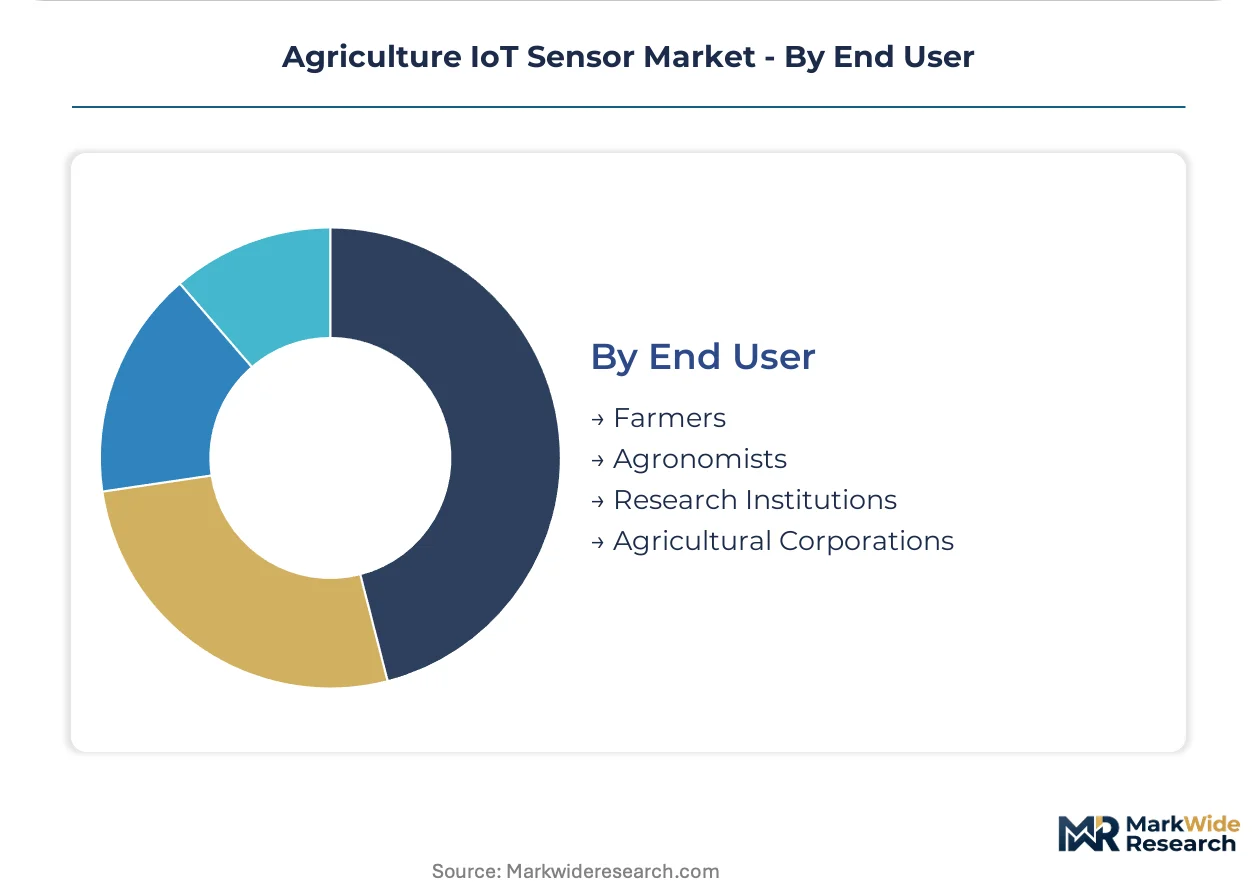
- Farmers:Owner-operators prioritize telemetry subscription bundles through equipment dealership channels over direct sensor procurement.
- Agronomists:Technical advisors specify sensor configurations and interpret electrochemical calibration data for producer clients.
- Research Institutions:Universities and agricultural extension services deploy high-density sensor grids for cultivar development and climate adaptation studies.
- Agricultural Corporations:Large-scale integrated operations with in-house technical teams standardize across multi-site deployments.
Farmers represent the volume foundation while agricultural corporations drive standardization at scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication for spectral imaging arrays and edge processing chipsets concentrates in East Asian foundries, creating differential lead time exposure across regional deployment timelines. This supply-side geography shapes where sensor network rollouts accelerate versus stall.
United States
Midwestern corn-soy belt operators prioritize telemetry subscription bundles through equipment dealership channels over direct procurement. EPA Clean Water Act enforcement tightens nutrient runoff accountability, compelling verified flow and soil nitrate sensor installations. California's Central Valley vineyards deploy multispectral imaging arrays at accelerating rates.
Brazil
Mechanized farming in Mato Grosso's soybean belt generates dense sensor network opportunities for large-scale operations. ANVISA advances data standardization frameworks that reduce interoperability friction between equipment brands. São Paulo-based agricultural corporations standardize multi-site deployments with in-house technical teams.
Germany
Dutch and German greenhouse operators absorb REACH and RoHS compliance premiums for certified weatherproof housings. EU CSRD disclosure mandates pull verified environmental monitoring systems into sustainability reporting frameworks. Bavarian precision agriculture equipment manufacturers integrate GNSS positioning with crop health monitors.
China
Yangtze River Delta greenhouse clusters favor cost-optimized sensing hardware without IP68 field hardening. MIIT standards and dual carbon goals pressure agricultural enterprises toward verified monitoring infrastructure. Shandong Peninsula orchard operators pilot sub-meter precision spraying workflows.
Australia
Extensive grazing systems across New South Wales and Victoria deploy livestock tracking collar systems with accelerometer and GPS beacon technology. TGA-aligned agricultural data frameworks support interoperability with export market requirements. Queensland irrigation districts integrate soil moisture sensors with automated valve control systems.
Agriculture IoT Sensor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Agriculture IoT Sensor Market. Premium field-hardened hardware with IP68 ratings and embedded edge analytics commands structural margin advantages over greenhouse-optimized alternatives. Three archetypes dominate: integrated equipment OEMs bundling telemetry subscriptions, precision agriculture specialists merging GNSS with spectral sensing, and aftermarket retrofit providers extending legacy machinery lifecycles. Competitive moves concentrate on dealership channel capture and regional data sovereignty compliance.
Among integrated equipment manufacturers, Deere & Company and AGCO Corporation exemplify the OEM archetype leveraging captive distribution networks. Trimble Inc. occupies a position within the precision technology tier, while Raven Industries represents the aftermarket retrofit specialist segment. These three anchors illustrate how vendor strategies diverge between original equipment bundling and legacy fleet conversion.
| Leading Market Players |
|---|
| AGCO Corporation |
| Topcon Corporation |
| Deere & Company |
| TE Connectivity Ltd. |
| Kubota Corporation |
| Trimble Inc. |
| Hexagon AB |
| Raven Industries |
| CNH Industrial N.V. |
| Others |
Pricing and Supply Chain Analysis
Foundry-scale economies in East Asian semiconductor fabrication create asymmetric pricing power across sensor tiers, concentrating margin capture among integrated platform providers while compressing single-sensor vendors. This scale dynamic anchors price floors for spectral imaging arrays and edge processing chipsets while greenhouse-optimized alternatives absorb cost pressure from commoditized electrochemical probe competition.
Pricing Analysis
EU CSRD disclosure mandates dictate the pricing tier structure across European deployments, forcing certified sensor premiums for verified environmental monitoring compliance. Three-tier pricing structure across premium field-hardened, standard greenhouse, and economy retrofit tiers separates IP68-rated multispectral platforms from cost-optimized soil moisture probes. Cost compression in the standard tier intensifies because Brazilian ANVISA and USDA NASS interoperability requirements force redundant calibration system investments. Smallholder farmers in technically constrained segments demonstrate highest price sensitivity, while agricultural corporations with in-house technical teams absorb premium pricing for standardized multi-site rollouts.
Supply Chain Analysis
Extended lead times for spectral imaging arrays and edge processing chipsets signal inventory strain across semiconductor-dependent sensor architectures. Manufacturing concentration in Taiwan, South Korea, and China draws from silicon wafer, rare-earth magnet, and specialized optical coating inputs. Single-source vulnerability in advanced node semiconductor fabrication threatens production continuity for premium field-deployable tiers. Distribution runs through farm equipment dealership networks that bundle telemetry subscriptions with original equipment sales, displacing direct-to-grower procurement channels in North American row-crop markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Agriculture IoT Sensor Market operates as a defensive-moat story where dealership channel entrenchment creates switching costs that lock in telemetry subscription revenue streams and marginalize direct procurement alternatives.
For Market Incumbents: Fortify dealership channel control through exclusive telemetry subscription bundling that extends beyond original equipment sales into aftermarket retrofit penetration. Expand in-house production of spectral imaging arrays to reduce Taiwan foundry dependency exposure. Certification investment in EU CSRD-compliant sensor tiers captures sustainability disclosure mandate premiums before standardization commoditizes verified environmental monitoring systems. For New Entrants and Emerging Players: Lead with aftermarket retrofit specialization targeting legacy machinery fleets in North American grain belts where equipment replacement cycles lag telemetry adoption curves. Brazil's Mato Grosso soybean belt presents the most penetrable geography for GNSS-integrated sensor platforms amid mechanized row-crop expansion. Channel partnership with regional analytics providers addresses emerging data sovereignty localization requirements without centralized platform infrastructure investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision agriculture specialists merging spectral sensing with embedded edge analytics over single-sensor hardware vendors facing substitution pressure. Long-term viability hinges on consolidation around integrated platform providers capable of capturing recurring service revenue pools. Monitor ANVISA-USDA NASS data standardization convergence as inflection indicator for interoperability friction reduction and multi-regional deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Retrofit Platform Launch | Extends legacy machinery lifecycles in North American grain belts without full replacement. |
| EU CSRD Certification Investment | Captures verified environmental monitoring premiums under sustainability disclosure mandates. |
| Spectral Imaging Array Integration | Displaces single-parameter electrochemical probes in California Central Valley specialty crops. |
| Regional Data Sovereignty Hosting | Addresses emerging national cloud mandates through locally-hosted analytics infrastructure. |
| LoRaWAN Protocol Optimization | Reduces mesh network configuration burdens for technically constrained farm operators. |
Research Methodology
Desk research of trade association filings, customs and trade databases, and equipment manufacturer SEC disclosures preceded structured interviews with precision agriculture equipment managers, agronomy service providers, farm dealership operations heads, and semiconductor procurement leads at sensor OEMs. Primary fieldwork combined with secondary validation from EPA enforcement records, EU Green Deal implementation guidance, and ANVISA regulatory frameworks supported bottom-up sensor shipment estimates and top-down market size triangulation.
Variance decomposition across product type, application, connectivity protocol, and end-user capability segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic agricultural output indicators and technology adoption S-curve positioning. Modeled inputs included mechanized farming expansion rates in Brazil's Mato Grosso soybean belt and EU CSRD disclosure mandate compliance timelines.
Forecasts assume regulatory continuity in EU CSRD, EPA Clean Water Act, and Brazil ANVISA frameworks; material policy shifts would require re-modeling adoption curves and certification tier premiums. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Telemetry-Linked Smart Fertilizer Program Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Precision Agriculture Market
Precision Agriculture
Agricultural Sensors Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Global Advanced Farming Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Global Agriculture Sensors Market
Precision Agriculture
Europe Precision Farming Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Agriculture Drone Software Market