
 Soil Moisture Meter Market | 2026-2036
Soil Moisture Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Moisture Meter Market Analysis
Commercial agriculture is rebalancing toward precision irrigation as drought cycles intensify across major growing regions. METER Group leverages its research-grade sensor portfolio to anchor the high-end institutional segment. Campbell Scientific sustains dominance in environmental monitoring networks through ruggedized telemetry integration. Spectrum Technologies competes aggressively on price in the turf and landscaping channel.
A soil moisture meter measures volumetric water content in soil media using electrical, thermal, or tensiometric principles, typically operating across a 0-100% saturation range with accuracy thresholds of ±2-3%. These instruments enable calibrated irrigation scheduling, reducing water waste and optimizing crop yield response curves. Digital meters and wireless meters command expanding share as farm operators replace analog dial units with Bluetooth-enabled probes and LoRa telemetry nodes. Capacitive technology leads unit volume due to lower cost and minimal soil-salinity interference, while Time Domain Reflectometry occupies the premium research tier where sub-centimeter resolution justifies higher instrument spend.
EPA water-use regulations under the Clean Water Act shape product certification requirements for agricultural equipment sold in the United States. EU Green Deal farm-to-fork targets and REACH substance restrictions constrain sensor material choices and drive redesign cycles for European market access. Stakeholders must monitor evolving IoT cybersecurity standards and soil-data privacy frameworks as connected meter deployments multiply across tenant farmland and cooperative networks.
Market Dynamics
Precision irrigation mandates are compressing replacement cycles for analog soil moisture meters as commercial farms face intensifying water-use audits and yield-per-acre optimization pressures. The shift from manual sampling to telemetry-integrated probes is restructuring equipment procurement around subscription-based sensor networks rather than standalone hardware sales.
Growth Catalysts
- EPA Clean Water Act irrigation efficiency standards:Agricultural equipment certification requirements in the United States are forcing commercial growers to retrofit legacy systems with calibrated digital meters, creating replacement demand across California's Central Valley and the Great Plains.
- Capacitive sensor miniaturization:Lower-cost printed circuit manufacturing is expanding addressable market reach into smallholder cooperatives and specialty crop operations previously priced out of precision agriculture tooling.
- Netherlands greenhouse cluster water stewardship protocols:Dutch horticulture exporters face retailer-driven sustainability audits that mandate documented soil moisture monitoring, driving probe density requirements in Venlo and Westland growing regions.
Market Restraints
- Semiconductor supply concentration:Analog-to-digital converter chip fabrication bottlenecks in East Asian foundries are extending lead times for wireless meter telemetry modules, constraining manufacturer shipment capacity.
- Soil salinity interference thresholds:Capacitive measurement accuracy degrades beyond 4 dS/m electrical conductivity, limiting deployment viability in coastal agricultural zones and salt-affected irrigation districts without costly calibration protocols.
- EU REACH substance restrictions:Cadmium and lead limits in electronic components are forcing sensor housing redesigns, extending product development cycles and raising material compliance costs for European market entry.
Strategic Opportunities
- Sub-Saharan Africa smallholder digitization:Development finance-backed precision agriculture pilots in Kenya and Ethiopia are creating first-mover advantage for low-cost Bluetooth-enabled probe suppliers willing to localize mobile app interfaces.
- LoRaWAN-5G convergence:Hybrid connectivity architectures combining long-range unlicensed spectrum with cellular backhaul are enabling meter deployments in cellular dead zones without proprietary base station infrastructure.
- India PLI scheme for agricultural IoT:Production-linked incentive allocations for smart farming equipment are attracting component assembly investment, reducing landed costs for domestic meter manufacturers serving the Indo-Gangetic Plain.
Industry Challenges
- Agronomy-data science skill synthesis:Meter vendors struggle to recruit personnel capable of translating volumetric water content readings into irrigation prescription algorithms, slowing customer success team scaling.
- Multi-protocol integration complexity:Farm management software platforms demand API compatibility across proprietary telemetry formats, forcing meter manufacturers to maintain parallel firmware development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Moisture Meter Market |
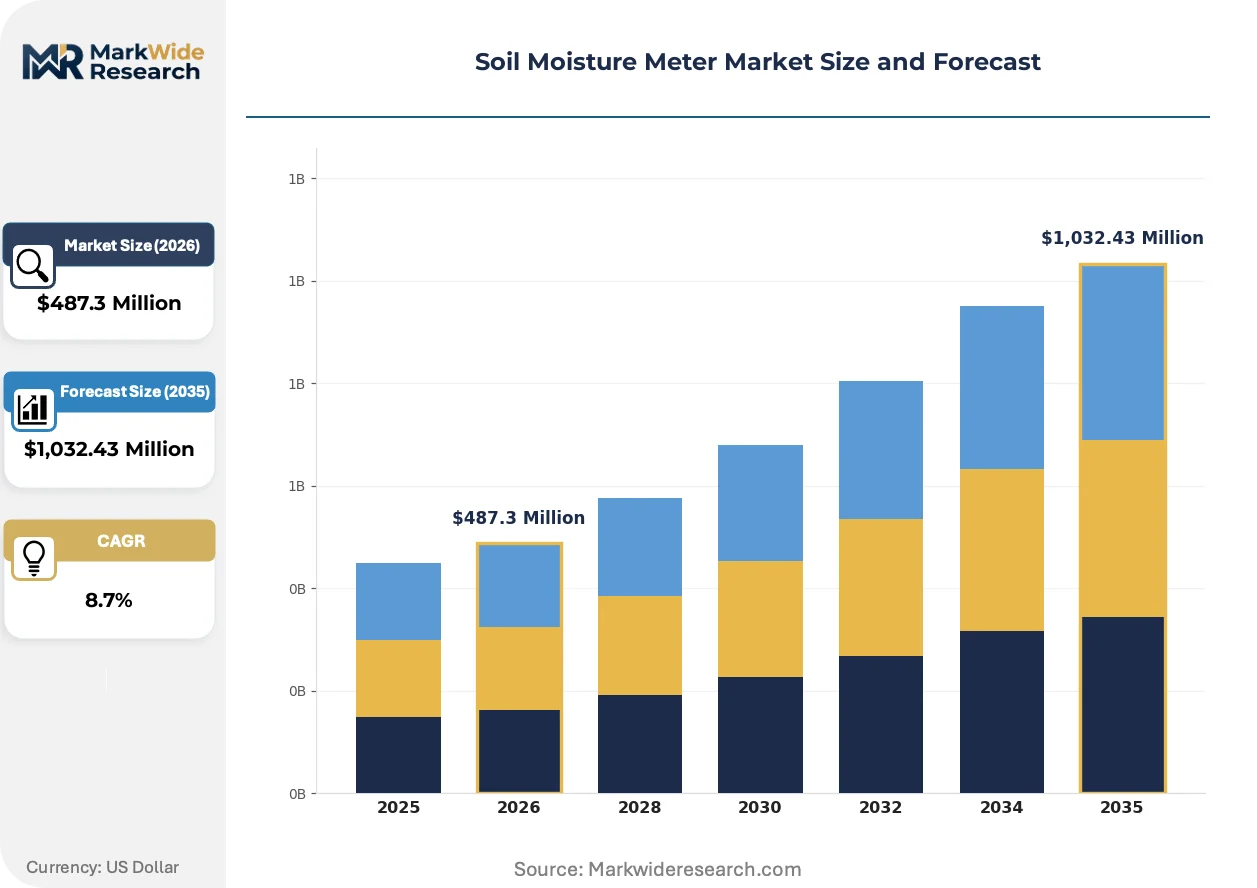
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Meters, Digital Meters, Wireless Meters, Tensiometers Technology: Capacitive, Resistive, Time Domain Reflectometry, Frequency Domain End User: Agriculture, Horticulture, Research Institutions, Environmental Monitoring Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | The Toro Company, METER Group, Inc., Campbell Scientific, Inc., Sentek Technologies, Stevens Water Monitoring Systems, Inc., Delta-T Devices Ltd., Spectrum Technologies, Inc., Trimble Inc., CropX Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Moisture Meter Market Emerging Trajectories
Sensor hardware is commoditizing faster than software analytics can differentiate, pushing competitive advantage toward data platform integration and predictive irrigation recommendation engines. Three developments are restructuring how soil moisture intelligence reaches farm decision-makers.
Multi-depth probe arrays are modularizing field deployment economics. These stackable sensor nodes measure volumetric water content at 10cm, 30cm, and 60cm horizons through a single installation bore, reducing per-acre installation labor by half. Large-scale row-crop operators in Brazil's Cerrado and Australia's Murray-Darling Basin are standardizing on modular configurations that allow seasonal depth adjustment without full probe replacement.
REACH substance restriction enforcement is accelerating material substitution in European-bound sensor housings. ECHA compliance deadlines for cadmium and lead content are compelling manufacturers to validate bio-based polymer alternatives, with certification timelines extending 14-18 months. German and Dutch distributors are prioritizing inventory positions for REACH-compliant stock, creating temporary product mix advantages for early certifiers.
Cooperative procurement consortia are consolidating smallholder demand into volume tender structures. Aggregated purchasing by cotton grower cooperatives in Uzbekistan and coffee associations in Colombia is displacing individual farm equipment decisions, compressing vendor sales cycles but squeezing unit margins. Meter suppliers are responding with stripped-down hardware SKUs bundled with multi-season calibration service contracts.
Soil Moisture Meter Market Segmentation
Soil moisture meter procurement splits sharply between standalone handheld units for spot-checking and telemetry-integrated systems feeding farm management platforms. Vendors configure product lines around this integration-depth fault line, with firmware architecture and calibration protocols diverging accordingly.
Product Type:
Standalone meters dominate manual irrigation scheduling workflows, while embedded probe networks serve automated valve control systems.
- Digital Meters:Microprocessor-based units with LCD readouts and onboard data logging, typically storing 1,000-2,000 readings for later download. California almond growers and Florida citrus operations are replacing analog dials with these units to satisfy EPA water-use audit documentation requirements.
- Wireless Meters:Battery-powered probes transmitting volumetric water content via Bluetooth, LoRa, or cellular modems to cloud dashboards. Dutch greenhouse operators in Westland cluster demand these for integration with climate control computers managing irrigation valves.
- Analog Meters:Needle-display units using gypsum block or tensiometer mechanics without electronic components. Remain prevalent in developing markets where capital constraints and technical service scarcity favor simplicity.
- Tensiometers:Vacuum gauge instruments measuring soil water potential through porous ceramic cups, favored in fine-textured soils where matric potential directly correlates with plant stress.
Volume placements concentrate in Digital Meters; the faster expansion belongs to Wireless Meters.
Technology:
Measurement physics determines calibration burden, salinity tolerance, and price positioning across customer tiers.
- Capacitive:Dielectric permittivity sensing using printed circuit electrodes at 70-150 MHz excitation frequency. Brazilian soybean farms in Mato Grosso deploy these widely due to minimal maintenance and insensitivity to salinity below 4 dS/m.
- Time Domain Reflectometry:Picosecond pulse propagation timing delivering ±1% volumetric accuracy. Australian viticulture researchers and USDA experimental stations specify TDR for root-zone water balance studies where precision justifies instrument cost.
- Resistive:Electrical resistance across gypsum or granular matrix blocks, requiring periodic recalibration as blocks dissolve. Declining share except in budget-constrained educational settings.
- Frequency Domain:Complex impedance spectroscopy distinguishing water content from bulk electrical conductivity. Gaining traction in coastal agriculture where salinity fluctuates seasonally.
Capacitive sensors claim the largest installed base; Frequency Domain technology is climbing the fastest as salinity compensation algorithms improve.
End User:
Customer sophistication ranges from yield-maximizing commercial operators to hypothesis-testing research scientists.
- Agriculture:Row-crop and specialty crop producers managing irrigation for water cost reduction and yield optimization. Nebraska corn operations and California Central Valley vegetable growers drive replacement cycles tied to equipment financing seasons.
- Research Institutions:Universities and government labs requiring traceable calibration chains and raw data export for publication. USDA-ARS locations and Wageningen University maintain instrument pools with NIST-traceable standards.
- Horticulture:Greenhouse and nursery operators monitoring container substrates with high-frequency, low-volume irrigation. Netherlands Venlo cluster exporters face retailer sustainability audits mandating documented moisture management.
- Environmental Monitoring:Ecosystem scientists tracking soil moisture for hydrological modeling and carbon flux studies. NEON network sites and European ICOS stations specify research-grade telemetry.
Agriculture accounts for the heaviest unit volume; Environmental Monitoring shows the steepest expansion trajectory as climate datasets gain policy relevance.
Distribution Channel:
Channel selection reflects customer technical support needs and procurement scale.
- Direct Sales:Manufacturer field engineers configure multi-node telemetry networks for large-scale farming cooperatives. Cotton grower consortia in Uzbekistan and coffee associations in Colombia negotiate volume tenders directly.
- Distributors:Agricultural supply dealers stocking calibrated probes alongside irrigation hardware. Midwest US farm supply chains and Australian rural merchants dominate this channel for replacement demand.
- Specialty Stores:Scientific instrument retailers serving research customers requiring technical pre-sales consultation. University procurement offices favor these for grant-funded equipment purchases.
- Online Retail:E-commerce platforms moving entry-level digital meters to smallholders and hobbyist growers. Kenya and Ethiopia development finance pilots source Bluetooth-enabled probes through mobile-optimized storefronts.
Distributors handle the greatest transaction volume; Direct Sales channels are gaining share fastest as cooperative procurement consolidates demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the Netherlands and India's production-linked incentive corridors are concentrating soil moisture meter assembly capacity near precision agriculture demand centers.
United States
California almond growers and Nebraska corn operations drive replacement cycles for telemetry-integrated probes. EPA Clean Water Act irrigation efficiency standards mandate calibrated digital meters for water-use audit compliance. The Central Valley agricultural corridor hosts the densest probe deployments per irrigated acre.
Netherlands
Greenhouse horticulture exporters face retailer-driven sustainability audits requiring documented soil moisture monitoring. EU Green Deal farm-to-fork targets and REACH substance restrictions constrain sensor material choices. The Westland and Venlo growing clusters standardize on wireless meters feeding climate control computers.
Brazil
Mato Grosso soybean farms deploy capacitive sensors widely due to minimal maintenance requirements and salinity tolerance. The country's national agricultural regulator enforces equipment certification for precision irrigation subsidies. The Cerrado biome's large-scale row-crop operators are modularizing multi-depth probe arrays.
India
Production-linked incentive allocations for agricultural IoT attract component assembly investment toward the Indo-Gangetic Plain. BIS standards for smart farming equipment shape domestic certification requirements. Gujarat and Maharashtra precision agriculture pilots create first-mover opportunities for low-cost Bluetooth-enabled probe suppliers.
Australia
Murray-Darling Basin water allocation constraints intensify volumetric irrigation scheduling adoption. The country's national environmental regulator monitors soil moisture networks for hydrological modeling compliance. Viticulture researchers in South Australia specify research-grade TDR instruments for root-zone water balance studies.
Soil Moisture Meter Market Vendor Landscape
Top-tier vendors anchor the research-grade instrumentation segment, while mid-tier specialists compete on price in commercial agriculture channels. The vendor base stratifies across telemetry-integrated platform providers, sensor component specialists, and precision agriculture software bundlers. Research-grade calibration chains and ruggedized field durability represent distinct strategic archetypes. Competitive moves concentrate on API integration partnerships with farm management platforms and backward integration into sensor fabrication.
Among research-grade instrumentation providers, METER Group, Inc. and Campbell Scientific, Inc. occupy positions emphasizing calibration traceability and environmental monitoring network deployment. Delta-T Devices Ltd. represents the European specialist archetype. Spectrum Technologies, Inc. exemplifies price-competitive positioning in turf and landscaping channels. CropX Technologies anchors the precision agriculture software-integrated vector. These company patterns illustrate how competitive positioning fragments across technical specialization, geographic origin, and customer sophistication tiers.
| Leading Market Players |
|---|
| The Toro Company |
| METER Group, Inc. |
| Campbell Scientific, Inc. |
| Sentek Technologies |
| Stevens Water Monitoring Systems, Inc. |
| Delta-T Devices Ltd. |
| Spectrum Technologies, Inc. |
| Trimble Inc. |
| CropX Technologies |
| Others |
Supply Flow & Price Mechanics
Capacitive sensor miniaturization via printed circuit manufacturing is compressing unit economics at the low end while concentrating margin capture among telemetry-integrated platform providers. This dual dynamic fragments pricing power across the value chain, rewarding backward integration into sensor fabrication and punishing pure hardware assemblers.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent replacement orders from scheduled procurement cycles, with California Central Valley cooperatives paying premiums for expedited delivery during irrigation season windows. Three-tier pricing structure across research-grade, commercial-precision, and economy-digital levels reflects calibration traceability and telemetry bundling. Price differentiation hinges on EPA water-use audit certification tier and volume scale in cooperative tenders. Cost compression in economy-digital tiers is intensifying because East Asian foundry bottlenecks force inventory carrying costs onto distributors. Smallholder cooperatives in Sub-Saharan Africa exhibit highest price sensitivity; USDA-ARS research stations show lowest.
Supply Chain Analysis
Direct-to-farm channels handle hyperscale cooperative demand in Uzbekistan and Colombia, while agricultural supply distributors serve spot replacement needs across the US Midwest and Australian rural corridors. Component fabrication concentrates in China, South Korea, and Taiwan for analog-to-digital converter chips and printed circuit substrates. Finished assembly draws from Mexico, India, and the Netherlands to satisfy regional compliance requirements. Supply chain risk centers on single-source vulnerability for telemetry module semiconductors. Distribution runs through irrigation equipment dealers bundling probes with valve control systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Clean Water Act irrigation efficiency standards and EU REACH substance restrictions erect compliance barriers that favor incumbents with certified product portfolios and extended development cycles. This cost-of-compliance architecture protects market position for players with established regulatory affairs infrastructure.
For Market Incumbents: Cement calibration traceability advantages by securing NIST-standards partnerships before USDA experimental station procurement cycles refresh. Deepen backward integration into printed circuit electrode fabrication to offset foundry margin compression. Defensive priority: neutralize low-cost Bluetooth probe entrants in Kenyan and Ethiopian development finance channels through localized mobile app pre-emption.
For New Entrants and Emerging Players: Begin with stripped-down capacitive probe SKUs bundled with multi-season calibration service contracts for Uzbek cotton and Colombian coffee cooperatives. White-space concentration sits in smallholder digitization pilots where incumbent technical service density remains thin. Go-to-market angle: partner with mobile network operators for SIM-embedded telemetry provisioning in cellular dead zones.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision agriculture software platforms seeking sensor hardware captive supply. Long-term viability favors vendors with telemetry-integrated platform architecture over standalone hardware specialists. Acquisition target archetype: mid-tier capacitive sensor specialists with REACH-compliant housing certifications and established Dutch greenhouse channel relationships. Signal to watch: LoRaWAN-5G convergence deployment velocity in Brazilian Cerrado and Australian Murray-Darling Basin.
| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Partnership | Campbell Scientific and METER Group telemetry formats must embed into Climate FieldView and Granular farm management platforms. |
| REACH Compliance Certification | German and Dutch distributors prioritize bio-based polymer housing inventory positions ahead of ECHA enforcement deadlines. |
| Multi-Depth Probe Modularization | Brazilian Cerrado operators standardize on stackable 10cm-30cm-60cm sensor nodes reducing per-acre installation labor. |
| Backward Integration into Fabrication | Captive printed circuit electrode production insulates margin from East Asian foundry lead-time volatility. |
| Development Finance Channel Entry | Kenya and Ethiopia precision agriculture pilots create first-mover terrain for low-cost Bluetooth-enabled probe localization. |
Methodological Framework
Independent corroboration across sensor manufacturer sales operations, agricultural cooperative procurement committees, and university research station instrumentation officers underwrites the qualitative findings. Primary fieldwork encompassed interviews with irrigation equipment distributors, greenhouse climate control system integrators, EPA regional water-use compliance officers, and Dutch horticulture exporter sustainability auditors. Secondary validation drew from USDA-ARS equipment procurement databases, EU ECHA REACH substance restriction filings, and India BIS smart farming equipment standard notifications. Bottom-up probe shipment tallies triangulated against top-down precision agriculture technology adoption curves.
Comparable-period anchoring to historical equipment replacement cycles and subsidy program enrollment windows structured the projection horizon. The analytical framework modeled volume and value across product type, technology physics, end-user sophistication tier, and distribution channel depth. CAGRs derived from segmented adoption curve penetration rates and equipment financing seasonality patterns. Forecast inputs included EPA audit mandate enforcement intensity and Netherlands greenhouse cluster water stewardship protocol adoption velocity.
Semiconductor supply disruption, EU substance restriction deadline acceleration, and cooperative procurement consolidation are the dominant revision risks. Forecasts reflect assumptions around telemetry module availability and calibration service network scaling. Practitioners should monitor foundry lead-time indicators and development finance pilot expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Digital Agriculture Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Global Digital Agriculture Platform Market
Precision Agriculture
Precision Livestock Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Soil Monitoring System Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Global Internet of Things (IoT) Agriculture Market
Precision Agriculture
Asia-Pacific Agricultural Sensors Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
Agriculture Drone Mapping and Analytics Market
Precision Agriculture
Agriculture Analytics Market
Precision Agriculture
Crop Monitoring Technology in Precision Farming Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Soil Moisture Sensor Market