
 Global Precision Farming Software and Services Market | 2026-2036
Global Precision Farming Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Farming Software and Services Market Analysis
Subscription-based leasing of sensor networks and drone fleets is fragmenting capital requirements across the competitive landscape. Deere & Company anchors its position through captive financing arms that bundle hardware with multi-year software contracts. Trimble Inc. differentiates via deep specialization in GNSS-guided field mapping systems for high-value crop operations. CropX Inc. competes through asset-light cloud deployment that eliminates upfront infrastructure spend for mid-sized growers.
Precision farming software and services encompass geospatial analytics platforms, IoT sensor integration layers, and AI-driven agronomic recommendation engines that process soil moisture, weather patterns, and crop health indicators to optimize input application and harvest timing. Cloud-based deployment models are capturing the fastest expansion as cellular coverage extends into rural production zones, while on-premises systems retain dominance among privacy-sensitive cooperative enterprises. Yield prediction modules command premium pricing due to their direct linkage to commodity hedging decisions, whereas support and maintenance services generate recurring revenue pools that stabilize vendor cash flows.
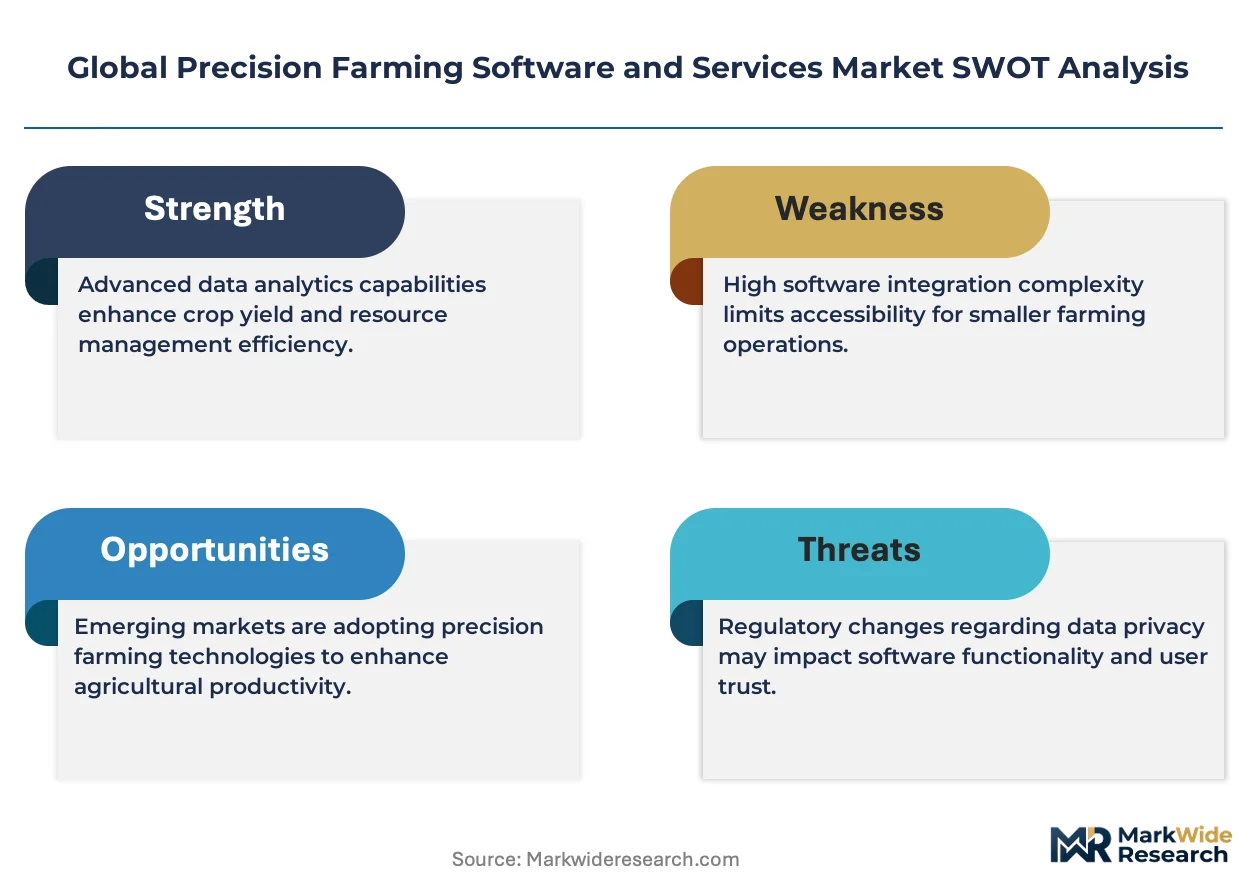
The EPA enforces water runoff reporting standards that compel growers to document fertilizer application through auditable software logs, while the EU Green Deal's Farm to Fork strategy mandates precision nutrient management to achieve emission reduction targets. ISO 17025 accreditation requirements for soil testing laboratories are filtering downstream to demand calibrated digital soil analysis workflows. Stakeholders must evaluate whether regulatory data portability rules will erode vendor lock-in or reinforce platform consolidation through compliance complexity.
Market Dynamics
Cellular network densification in rural corridors is collapsing the infrastructure barrier that previously confined precision farming to well-capitalized operations with private telemetry systems. This connectivity expansion is redistributing competitive advantage toward software-native vendors and away from hardware-anchored incumbents.
Growth Catalysts
- EU Green Deal Farm to Fork mandates:The strategy's binding emission reduction targets force growers to adopt auditable nutrient management platforms. Compliance documentation requirements create non-discretionary demand for soil analysis and input optimization software.
- Brazilian mechanized soy operations:Consolidated farming enterprises across Mato Grosso and Goiás generate data volumes sufficient to train field-specific AI models. Scale economics justify dedicated agronomic data science teams.
- Low-earth orbit satellite constellations:Commercial imagery providers now deliver sub-meter resolution at weekly cadence. This data stream feeds vegetation index algorithms that previously required aircraft or drone deployment.
Market Restraints
- Lithium-ion battery supply concentration:Sensor networks and autonomous field equipment depend on cell supply chains dominated by Chinese cathode and electrolyte producers. Price volatility in lithium carbonate directly inflates hardware leasing costs.
- Legacy equipment interoperability gaps:Proprietary data formats from 1990s-era tractor guidance systems resist API integration. Retrofit costs often exceed replacement economics for mid-life machinery.
- Rural cellular backhaul limitations:Edge computing requirements for real-time variable-rate application exceed latency tolerance of 4G networks in remote production zones. 5G infrastructure buildout timelines remain uncertain.
Strategic Opportunities
- Indian fragmented landholding structure:Cooperative aggregation models enable shared sensor infrastructure across smallholder networks. Federated data architectures preserve plot-level privacy while achieving training-scale datasets.
- Carbon credit verification protocols:Emerging soil carbon quantification methodologies create new revenue streams tied to sequestration measurement. Software platforms that automate MRV (measurement, reporting, verification) workflows capture value from voluntary and compliance markets.
- Drone-to-tractor workflow integration:Converging aerial imagery capture with autonomous ground application closes the sense-decide-act loop. Vendors controlling both layers extract premium pricing for closed-loop field management.
Industry Challenges
- Agronomic data science talent scarcity:The intersection of crop physiology, geospatial statistics, and machine learning engineering remains thinly staffed. Compensation inflation at technology vendors disrupts traditional agricultural extension service hiring.
- ISO 17025 calibration complexity:Digital soil analysis workflows require laboratory-grade sensor validation that conflicts with field-deployment durability requirements. Recertification cycles consume engineering resources without differentiating end-user outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Farming Software and Services Market |
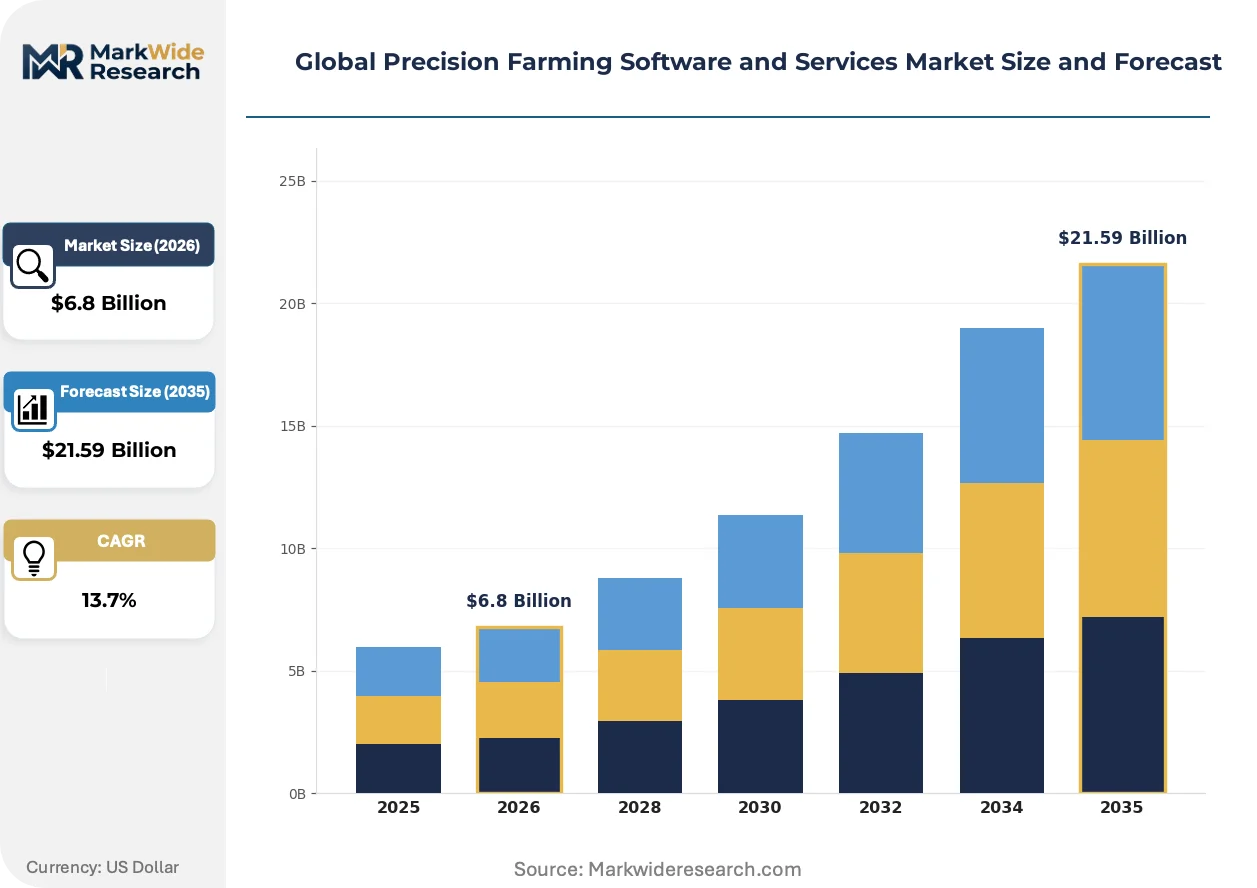
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Field Mapping, Crop Monitoring, Soil Analysis, Yield Prediction Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile Service Type: Consulting, Training, Support & Maintenance, Integration End User: Agricultural Enterprises, Farmers, Research Institutions, Agronomists |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, Topcon Corporation, Kubota Corporation, CNH Industrial, Raven Industries, CropX Inc., Farmers Edge Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Farming Software and Services Market Emerging Trajectories
Multi-spectral imaging hardware commoditization is shifting value capture toward algorithmic interpretation layers and away from sensor manufacturing. This transition favors software-centric business models and pressures vertically integrated equipment vendors to unbundle their technology stacks.
Hyperspectral cameras mounted on fixed-wing drones are digitizing early-stage crop stress detection at canopy-scale resolution. Specialty crop operations in California's Central Valley and Australia's Murray-Darling Basin deploy these systems weekly during critical growth windows. The technology is digitizing insurance underwriting workflows by providing objective damage documentation that accelerates claims processing and reduces loss-adjustment expenses.
REACH chemical registration amendments are tightening data requirements for agrochemical metabolite environmental fate. The regulation forces reformulation of established fertilizer coatings and pesticide delivery systems. High-value crop software vendors in the Netherlands and Denmark are responding by integrating EU Green Deal compliance modules that automate substance volume tracking and runoff risk scoring.
Cooperative purchasing consortiums among Midwestern US grain operations are consolidating software procurement decisions that previously fragmented across individual farm managers. These buying groups negotiate enterprise licensing terms that bundle training and support across member operations. The pattern is most visible in Illinois and Iowa, where three cooperatives now represent over twelve million acres in collective negotiations with platform vendors.
Global Precision Farming Software and Services Market Segmentation
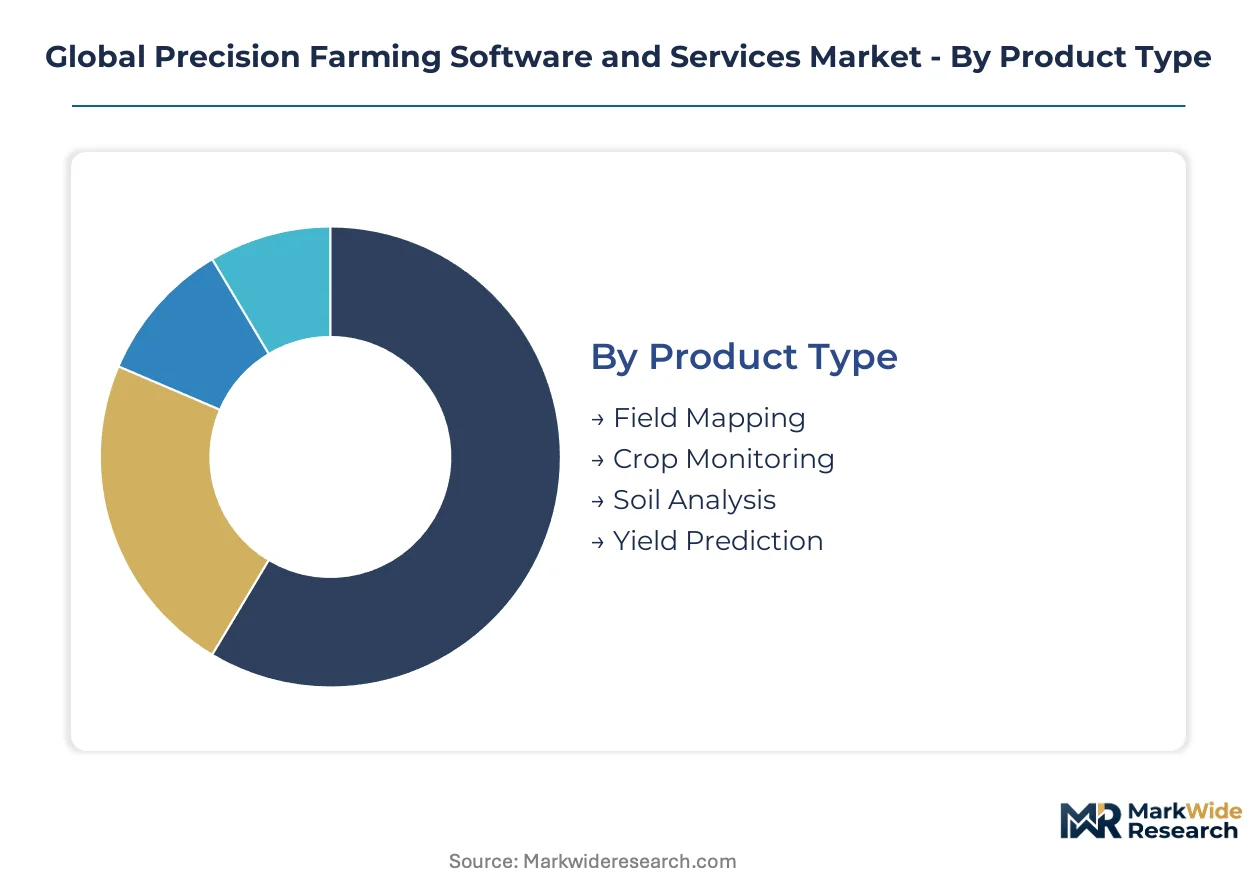
Precision farming software segments reflect divergent capital intensity and data sovereignty requirements across farm operation scales. Deployment choices directly determine vendor pricing power and customer lifetime value in this infrastructure-heavy market.
Product Type:
Field operations span mapping-intensive broadacre systems through prediction-driven commodity hedging workflows.
- Field Mapping:GNSS-guided geospatial platforms generate sub-meter accuracy boundary delineation and prescription maps for variable-rate application. Brazilian soy operations in Mato Grosso deploy these systems across consolidated holdings exceeding fifty thousand hectares. The EPA's water runoff reporting standards mandate auditable field boundary documentation for nutrient management compliance.
- Yield Prediction:Machine learning models integrate satellite imagery, soil moisture telemetry, and weather forecasts to forecast harvest volumes weeks before physical sampling. Large-scale US grain operations leverage these outputs for commodity futures positioning. EU Green Deal emission accounting requires yield-normalized input efficiency metrics that prediction algorithms automate.
- Crop Monitoring:Vegetation index dashboards track canopy health through multi-spectral imagery at weekly cadence.
- Soil Analysis:Digital sampling workflows integrate laboratory-grade sensor calibration with field-deployable probe networks.
Established volume favors Field Mapping; emerging adoption favors Yield Prediction.
Deployment Model:
Capital structure and connectivity infrastructure shape procurement decisions across farm enterprise tiers.
- Cloud-Based:Browser-accessible platforms eliminate server capital expenditure and enable automatic algorithm updates. Australian broadacre operators in the Murray-Darling Basin adopt these systems as cellular coverage extends into remote production zones. Low-earth orbit satellite constellations now feed vegetation analytics without requiring local data storage infrastructure.
- On-Premises:Local server installations preserve data sovereignty for cooperative enterprises and privacy-sensitive multi-generational family operations. German cooperative grain handlers maintain these deployments to satisfy GDPR agricultural data processing requirements. ISO 17025 calibration workflows for soil testing integrate more cleanly with controlled local environments.
- Hybrid:Edge computing architectures process time-sensitive field operations locally while batching analytics to cloud infrastructure.
- Mobile:Smartphone-native applications deliver scouting and input recommendations without dedicated hardware investment.
Cloud-Based deployments are climbing the fastest; On-Premises retains margin concentration in cooperative channels.
Service Type:
Revenue stability varies dramatically between discrete project delivery and recurring operational support.
- Support & Maintenance:Subscription-based technical assistance and software update programs generate predictable annual recurring revenue. US Midwestern cooperative purchasing consortiums negotiate multi-year support bundles across aggregated acreage. Vendor cash flow stability depends on renewal rates in this category.
- Integration:API development and legacy equipment connectivity projects command premium day rates due to agronomic data science talent scarcity. Brazilian mechanized operations require extensive retrofitting of 1990s-era tractor guidance systems. Proprietary data format translation consumes substantial engineering resources without scaling efficiently.
- Consulting:Agronomic advisory services combine software configuration with input optimization recommendations.
- Training:Operator certification and platform onboarding programs address skill gaps in rural labor markets.
Support & Maintenance locks in recurring revenue; Integration captures premium pricing from legacy system complexity.
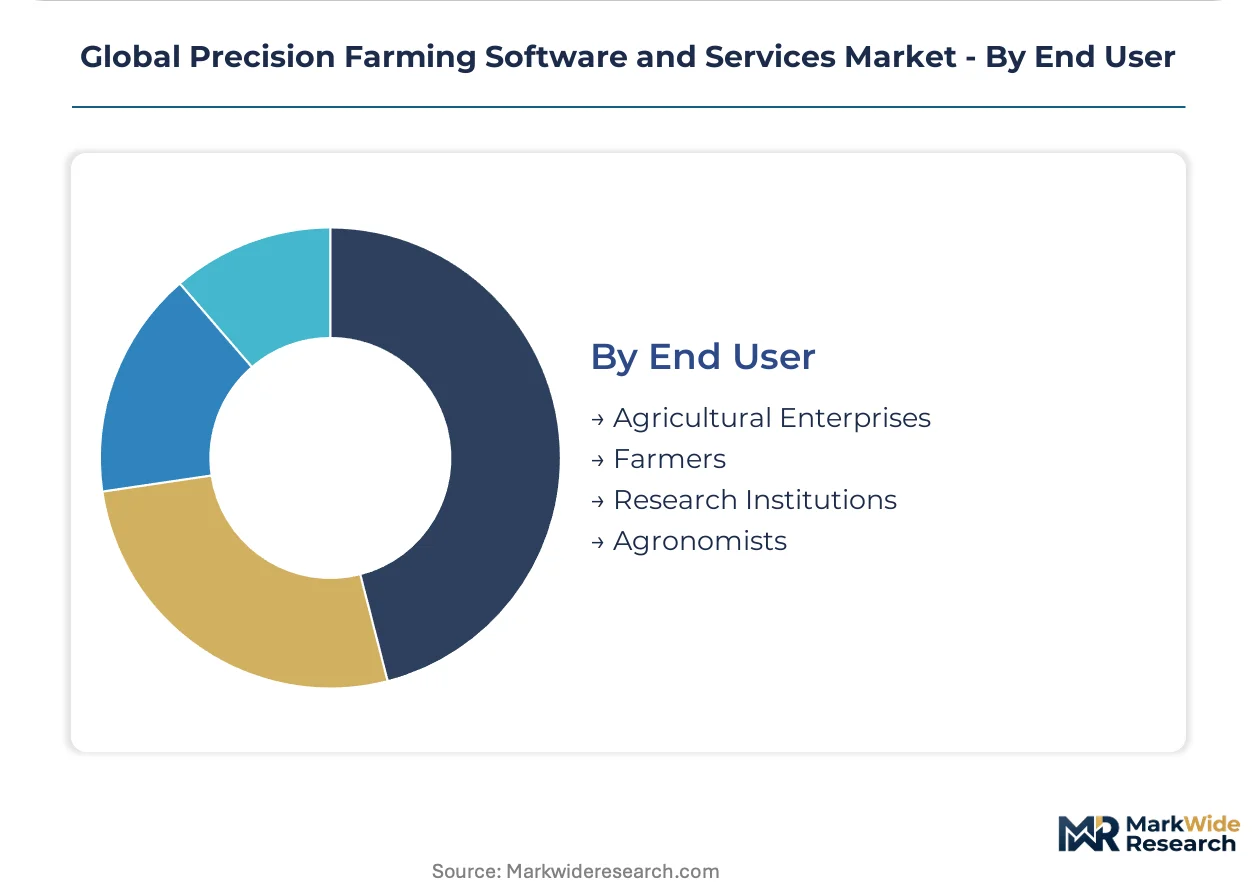
End User:
Procurement authority concentrates differently across organizational structures and decision-making hierarchies.
- Agricultural Enterprises:Consolidated corporate farming operations deploy dedicated agronomic data science teams and negotiate enterprise licensing terms. Illinois and Iowa grain cooperatives now represent over twelve million acres in collective software procurement. Scale economics justify custom algorithm development for field-specific conditions.
- Farmers:Individual owner-operators prioritize mobile-first solutions with minimal upfront infrastructure requirements. Indian fragmented landholding structures drive cooperative aggregation models for shared sensor network access. Federated data architectures preserve plot-level privacy while achieving training-scale datasets.
- Research Institutions:University extension services and government agricultural departments fund method validation and algorithm benchmarking.
- Agronomists:Independent crop consultants license platforms to service multiple client operations under professional service arrangements.
Agricultural Enterprises dominate current procurement volume; Farmers represent the steepest expansion trajectory as subscription models reduce capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consolidated agricultural enterprises in the United States, Brazil, and Australia generate the highest software utilization rates, while regulatory mandates in the European Union and India reshape procurement patterns across diverse farming structures.
United States
Midwestern grain cooperatives in Illinois and Iowa now represent over twelve million acres in collective software negotiations, driving enterprise licensing consolidation. The EPA enforces water runoff reporting standards that compel auditable fertilizer documentation through precision platforms. Yield prediction modules command premium pricing in the Corn Belt as commodity hedging decisions integrate algorithmic harvest forecasts.
Brazil
Mechanized soy operations across Mato Grosso and Goiás generate data volumes sufficient to train field-specific AI models, justifying dedicated agronomic data science teams. ANVISA registration requirements for agrochemical application tracking filter into software procurement specifications. Consolidated holdings exceeding fifty thousand hectares deploy GNSS-guided field mapping systems with captive financing arrangements.
Germany
Cooperative grain handlers maintain on-premises deployments to satisfy GDPR agricultural data processing requirements, preserving data sovereignty for multi-generational family operations. The EU Green Deal Farm to Fork strategy mandates precision nutrient management with binding emission reduction targets. Bavarian precision agriculture clusters integrate ISO 17025 calibration workflows for soil testing laboratories.
Australia
Broadacre operators in the Murray-Darling Basin adopt cloud-based platforms as cellular coverage extends into remote production zones. Low-earth orbit satellite constellations now feed vegetation analytics without requiring local data storage infrastructure. Queensland and New South Wales grain enterprises leverage subscription-based sensor network leasing to fragment capital requirements.
India
Fragmented landholding structures drive cooperative aggregation models for shared sensor infrastructure across smallholder networks. Federated data architectures preserve plot-level privacy while achieving training-scale datasets for algorithm development. Maharashtra and Gujarat pilot programs demonstrate how federated learning approaches enable mid-sized growers to access enterprise-grade analytics without upfront infrastructure spend.
Global Precision Farming Software and Services Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement authority among consolidated agricultural enterprises. Hardware-anchored incumbents with captive financing arms bundle multi-year software contracts, while software-native vendors capture expanding cellular connectivity in rural corridors. Two dominant archetypes emerge: vertically integrated equipment manufacturers and asset-light cloud deployment specialists. Competitive moves center on strategic partnerships for legacy equipment interoperability and geographic expansion through cooperative purchasing consortiums.
Within the equipment-integrated tier, Deere & Company and AGCO Corporation anchor positions through captive financing structures that bind hardware procurement to software subscriptions. Trimble Inc. occupies a specialization position in GNSS-guided systems. Among software-native competitors, CropX Inc. exemplifies asset-light cloud deployment that eliminates upfront infrastructure requirements for mid-sized growers.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| Topcon Corporation |
| Kubota Corporation |
| CNH Industrial |
| Raven Industries |
| CropX Inc. |
| Farmers Edge Inc. |
| Others |
Supply Flow & Price Mechanics
Panama Canal transit corridors shape cost dynamics for lithium-ion battery cells destined for autonomous field equipment, concentrating supply leverage among Chinese cathode producers while forcing downstream tiered pricing across sensor network leasing contracts.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate hardware leasing arrangements, particularly for Brazilian soy operations deploying sensor networks across Mato Grosso holdings. Three-tier pricing structure across premium, standard, and economy levels separates yield prediction modules with commodity hedging integration from basic field mapping subscriptions. Pricing pressure stems from cellular infrastructure commoditization collapsing connectivity premiums. Mid-sized growers exhibit highest price sensitivity, while consolidated agricultural enterprises absorb premium tiers for custom algorithm development.
Supply Chain Analysis
Export-control regimes restricting GNSS receiver technology flow from the United States to designated entities fragment precision guidance component availability. Manufacturing concentrates in China, South Korea, and Germany for sensor assemblies, processor modules, and telemetry hardware. Supply chains draw from lithium carbonate, rare earth magnets, and silicon wafer inputs. Single-source vulnerability persists for high-precision GNSS chipsets. Distribution runs through captive financing arms of equipment manufacturers and cooperative purchasing consortiums aggregating Midwestern US grain operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source geospatial platforms threaten proprietary software margins, forcing incumbents to defend through data network effects and regulatory compliance integration.
For Market Incumbents: Build switching-cost moats through ISO 17025 calibration workflow integration that locks soil testing laboratories into recurring validation cycles. Bundle multi-year software contracts with captive financing arms to capture hardware replacement economics. Defend against asset-light cloud entrants by embedding EU Green Deal compliance modules directly into nutrient management platforms, making regulatory audit trails non-portable across vendors. For New Entrants and Emerging Players: Indian cooperative aggregation models for fragmented smallholder networks represent the most penetrable entry point, with Maharashtra and Gujarat pilot programs demonstrating federated learning architectures. Target mid-sized Australian broadacre operators in the Murray-Darling Basin where cellular coverage expansion eliminates upfront infrastructure barriers. Deploy smartphone-native scouting applications with zero hardware requirements to bypass equipment-anchored incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with precision agriculture divisions lacking standalone software scale. Long-term viability hinges on platforms capturing carbon credit verification workflows as soil carbon quantification methodologies mature. Monitor ANVISA registration requirements for agrochemical application tracking as the inflection signal—vendors automating these compliance layers will extract premium positioning in Brazilian procurement decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API development for 1990s-era tractor guidance systems unlocks retrofit revenue in Brazilian mechanized operations. |
| Geographic Expansion | Cooperative purchasing consortiums in Illinois and Iowa aggregate twelve million acres for enterprise licensing negotiations. |
| Strategic Partnership | Low-earth orbit satellite constellation agreements feed sub-meter imagery to vegetation index algorithms without drone deployment. |
| Acquisition of Specialist Firm | Carbon credit verification protocol developers capture MRV automation value from voluntary and compliance markets. |
| Product Launch | EU Green Deal compliance modules automate substance volume tracking for REACH chemical registration amendments. |
Methodological Framework
Desk research of customs filings, SEC equipment manufacturer disclosures, and cellular infrastructure deployment databases preceded structured interviews with agronomic data science directors, cooperative procurement managers, and GNSS systems engineers. Primary fieldwork with Brazilian soy operations in Mato Grosso and Midwestern US grain cooperatives validated software utilization rates and contract structures. Secondary sources included EPA water runoff reporting standards documentation, EU Green Deal Farm to Fork strategy implementation guidelines, and ANVISA agrochemical registration requirements. Bottom-up acreage deployment estimates triangulated against top-down vendor revenue disclosures.
Assumptions held cellular network densification timelines and lithium carbonate price volatility within historical bands while varying regulatory compliance stringency across jurisdictions. The analytical framework modeled deployment model, farm operation scale, and crop type segmentation throughout the forecast period. CAGRs derived from algorithmic harvest forecast adoption curves and cooperative purchasing consortium formation rates. Forecast inputs incorporated satellite imagery resolution improvements and 5G infrastructure buildout uncertainty in remote production zones.
Practitioners should monitor EU Green Deal emission accounting rulemakings and carbon credit verification protocol standardization for early signals of platform consolidation or fragmentation. Forecasts reflect assumptions of continued mechanization in Brazilian soy operations and stable cooperative governance structures in US Midwestern grain markets. Material shifts in lithium-ion battery supply chain concentration or GDPR agricultural data processing enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Agriculture
Soil Moisture Sensor Market
Precision Agriculture
Global Precision Irrigation Market
Precision Agriculture
Connected Agriculture Software Market
Precision Agriculture
North America Precision Agriculture Market
Precision Agriculture
Precision Farming Market
Precision Agriculture
Agricultural Mapping Services Market
Precision Agriculture
Crop Monitoring Market
Precision Agriculture
Remote Fertigation Monitoring Services Market
Precision Agriculture
Digital Farming Technology Market
Precision Agriculture
Global Digital Farming Market
Precision Agriculture
Automated Pest Monitoring System Market
Precision Agriculture
Americas Precision Farming Software Market
Precision Agriculture
Precision Agriculture Soil Nutrient and Microbiome Field Test Devices Market
Precision Agriculture
Crop Nutrient Management Market
Precision Agriculture
Digital Agriculture Solutions Market
Precision Agriculture
Agricultural Sensors Market